
 Asia-Pacific Vaginal Slings Market | 2026-2036
Asia-Pacific Vaginal Slings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vaginal Slings Market Insights
Multi-source procurement of polypropylene mesh is decoupling from single-supplier dependence across major device manufacturers in the Asia-Pacific region. Boston Scientific Corporation leverages its integrated manufacturing footprint to sustain cost advantages across multiple sling formats. Coloplast competes through specialized channel relationships with urogynecology centers in Australia and Japan. Medtronic anchors its position via deep clinical training networks that tie product adoption to surgeon certification programs.
Vaginal slings are implantable support devices, typically constructed from knitted monofilament polypropylene mesh or biologic graft material, designed to reinforce the pubourethral ligament and restore continence through minimally invasive placement. The synthetic sling segment dominates current volume due to standardized manufacturing and reproducible tensile strength profiles, though biological mesh variants are capturing margin pools in premium reimbursement environments. Hospitals remain the primary end-user channel, while outpatient surgical centers represent the fastest-growing access point as ambulatory procedure codes expand across South Korea and Australia.
Japan's PMDA enforces rigorous biocompatibility testing under revised medical device standards, while Australia's TGA mandates enhanced patient consent protocols for permanent implant procedures. India's Central Drugs Standard Control Organization (CDSCO) is aligning its mesh classification framework with international harmonization initiatives, creating compliance complexity for new entrants. Stakeholders must monitor evolving reimbursement thresholds for ambulatory sling procedures and the shifting regulatory stance on synthetic mesh safety across multiple Asia-Pacific jurisdictions.
Market Dynamics
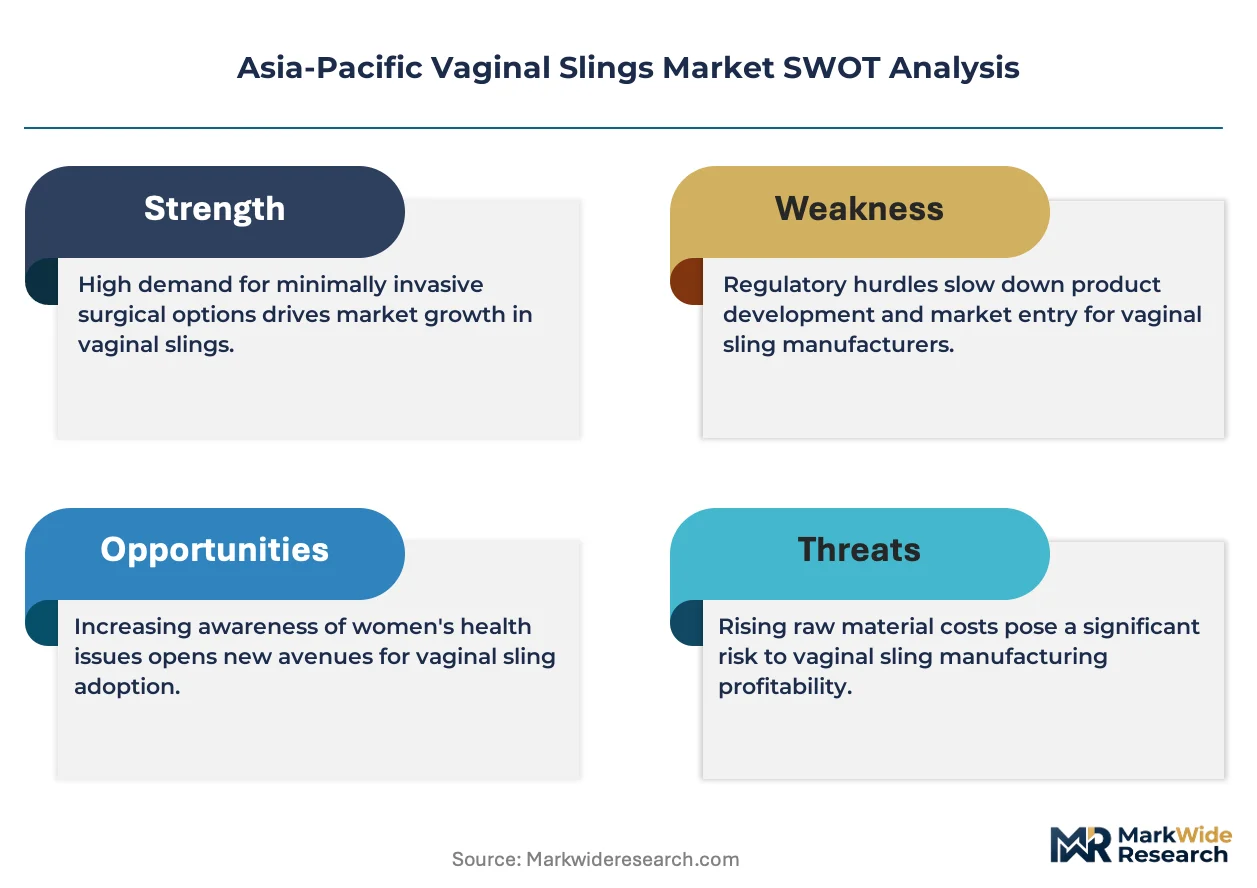
Japan's PMDA and Australia's TGA have tightened biocompatibility requirements for synthetic mesh implants, forcing manufacturers to accelerate material innovation toward safer alternatives while tertiary hospitals across the region expand sling placement volumes.
Growth Catalysts
- Minimally invasive surgical protocols:Urogynecology departments in tertiary hospitals across Japan, Australia, and South Korea are expanding sling placement volumes as laparoscopic and single-incision techniques gain standardized acceptance.
- Aging demographics:Japan, Australia, and South Korea exhibit rising stress urinary incontinence prevalence among women over 55, creating sustained procedure demand supported by higher surgical reimbursement rates.
- PMDA's revised medical device standards:Japan's stricter biocompatibility testing requirements are accelerating R&D investment in next-generation mesh materials that exceed legacy safety thresholds.
Market Restraints
- Polypropylene price volatility:Knitted monofilament polypropylene mesh remains the dominant synthetic material, leaving manufacturers exposed to petrochemical feedstock cost fluctuations.
- Single-supplier concentration:Multi-source procurement remains underdeveloped across several Asia-Pacific markets, creating vulnerability when primary medical-grade polymer suppliers face production constraints.
- Biologic graft scarcity:Human and porcine-derived biological mesh variants face limited tissue bank availability and extended sterilization validation timelines, restricting premium segment expansion.
Strategic Opportunities
- Ambulatory surgical centers:South Korea and Australia are expanding procedure codes for outpatient sling placements, enabling channel shift from inpatient hospital settings.
- CDSCO harmonization:India's Central Drugs Standard Control Organization is aligning mesh classification with international standards, creating regulatory clarity for new entrants targeting the subcontinent's underpenetrated urogynecology sector.
- Surgeon certification networks:Clinical training programs tied to product adoption create sticky demand relationships and raise competitive barriers for unaffiliated manufacturers.
Industry Challenges
- Urogynecology specialist shortage:The limited pipeline of fellowship-trained surgeons capable of minimally invasive sling placement constrains procedure volume growth despite patient demand.
- Mesh safety litigation exposure:Manufacturers face ongoing product liability risks from historical synthetic mesh complications, requiring enhanced patient consent documentation and post-market surveillance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vaginal Slings Market |
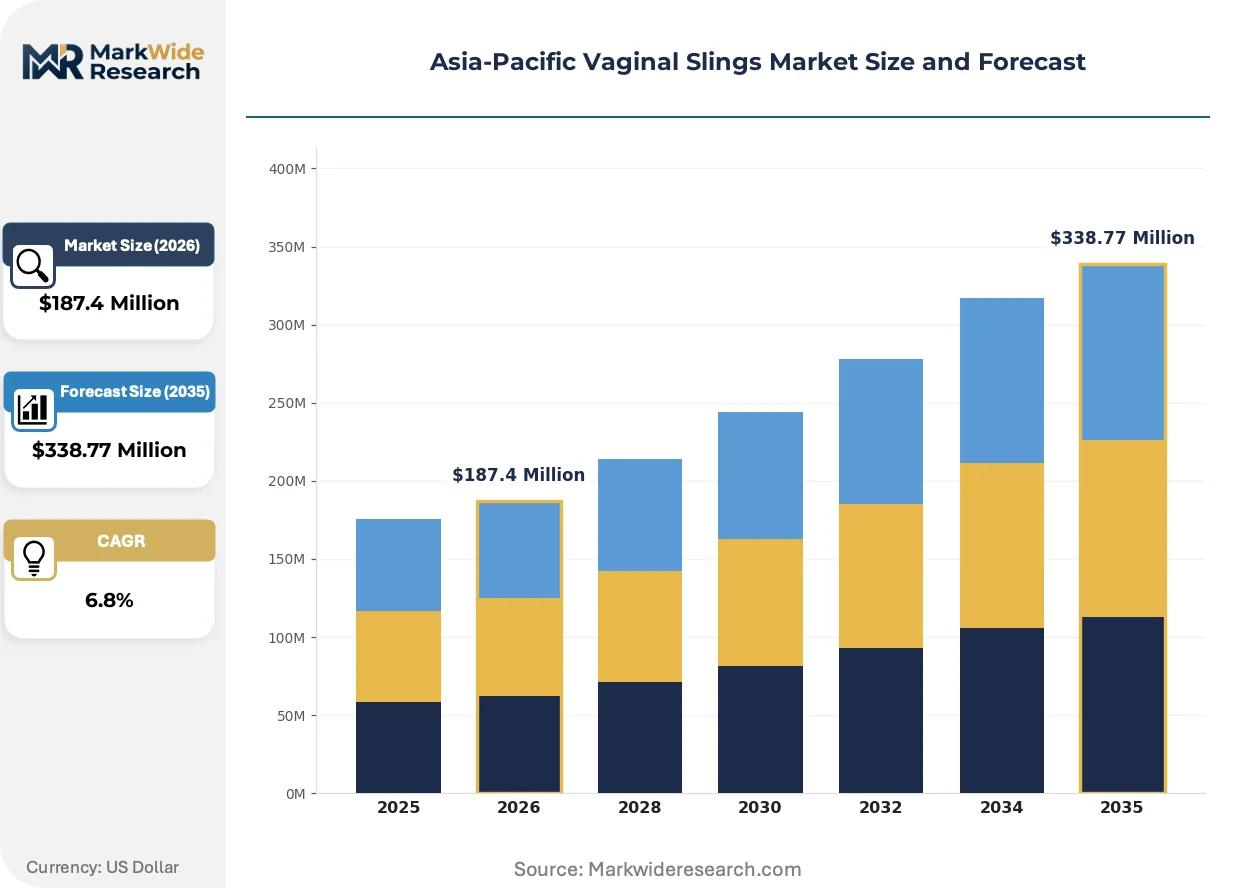
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tension-Free Vaginal Tape, Autologous Sling, Synthetic Sling, Fascial Sling End User: Hospitals, Clinics, Outpatient Surgical Centers, Independent Medical Practices Material: Polypropylene, Biological Mesh, Polyvinyl Alcohol, Polyester Application: Urinary Incontinence, Pelvic Organ Prolapse, Surgical Correction, Support Procedures |
| Companies Covered | Boston Scientific Corporation, Coloplast, Johnson & Johnson (Ethicon), Promedon Group, Medtronic, B. Braun Melsungen AG, Neomedic International, Cook Biotech, Caldera Medical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vaginal Slings Market Trends and Innovations
Material science advances and regulatory tightening are converging to reshape competitive positioning across the Asia-Pacific vaginal slings landscape, with three developments commanding strategic attention.
Absorbable synthetic polymers with controlled degradation profiles are consolidating market share among premium-tier manufacturers seeking to differentiate from permanent polypropylene mesh. Tertiary hospital procurement committees in Japan and Australia are prioritizing these materials for high-risk patient cohorts despite cost premiums. The technology is consolidating previously fragmented purchasing decisions around single-supplier relationships as hospitals standardize on validated bioresorbable platforms.
Australia's TGA has mandated enhanced patient consent protocols for permanent implant procedures, requiring documented discussion of erosion risks and alternative treatment pathways. This regulatory friction is extending sales cycles and elevating documentation burdens for device representatives. The policy is compressing synthetic sling volumes in favor of biologic alternatives where informed consent narratives align more favorably with patient risk perception.
Hospital buying committees are consolidating vendor relationships around integrated supply contracts that bundle mesh implants with disposable trocars and fixation systems. This procurement concentration is marginalizing standalone mesh suppliers unable to offer full procedure kits. The shift is most visible in Australia's private hospital networks, where standardized preference contracts now cover 60-70 percent of annual sling volumes.
Asia-Pacific Vaginal Slings Market Segmentation
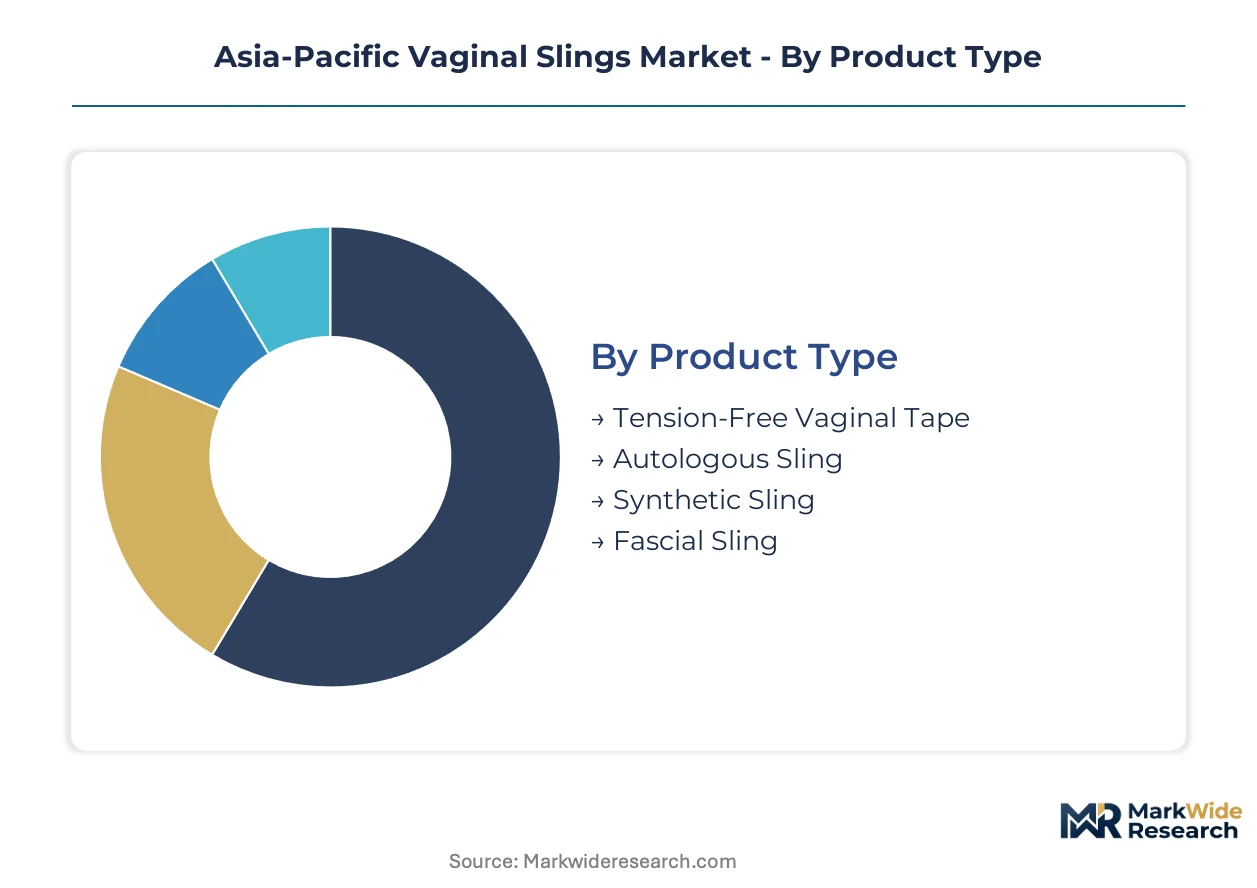
Vaginal sling procurement patterns across Asia-Pacific diverge sharply between standardized hospital protocols and customized surgeon preferences. Segmentation reveals how material science, reimbursement pathways, and procedural settings reshape competitive positioning across Japan, Australia, and South Korea.
Product Type:
The customization-vs-standardization spectrum spans tension-free mid-urethral tapes favored for reproducibility against autologous harvests tailored to complex anatomies.
- Tension-Free Vaginal Tape:Knitted monofilament polypropylene mesh configured for retropubic or transobturator placement without tensioning sutures. Japan's tertiary urogynecology departments standardize on this format for high-volume stress urinary incontinence cases where reimbursement favors efficiency.
- Synthetic Sling:Manufactured meshes with calibrated pore sizes and tensile strength profiles enabling laparoscopic or single-incision deployment. Australia's private hospital networks are consolidating procurement around validated synthetic platforms as TGA consent protocols elevate documentation requirements for permanent implants.
- Autologous Sling:Patient-derived fascia lata or rectus fascia harvested for sling construction. Harvest complexity limits adoption to revision cases in South Korea's academic medical centers.
- Fascial Sling:Cadaveric or processed allograft fascia providing biologic alternative to synthetic meshes. Tissue bank scarcity constrains volume across Asia-Pacific markets.
Most installed capacity flows through Synthetic Sling. Expansion is steepest in Tension-Free Vaginal Tape.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from lean outpatient facilities capturing ambulatory procedure code expansion.
- Hospitals:Tertiary urogynecology departments with fellowship-trained surgical teams and integrated cystoscopy capabilities. Japan's aging demographics sustain inpatient volumes where complex cases require overnight observation.
- Outpatient Surgical Centers:Dedicated ambulatory facilities equipped for monitored anesthesia care and same-day discharge. South Korea's expanded procedure codes are accelerating channel shift from hospital settings.
- Clinics:Urogynecology specialty clinics performing diagnostic workup and postoperative surveillance. Australia's metropolitan clusters concentrate diagnostic volume before surgical referral.
- Independent Medical Practices:Solo or group urology practices with limited surgical suite infrastructure. Reimbursement fragmentation constrains sling placement volume in this channel.
Revenue concentration sits with Hospitals. Outpatient Surgical Centers are climbing the fastest.
Material:
Margin structure separates commodity polypropylene from premium biological meshes commanding price premiums in risk-averse patient cohorts.
- Polypropylene:Knitted monofilament mesh with standardized pore architecture and established biocompatibility profiles. PMDA's revised testing requirements are accelerating R&D investment in next-generation formulations that exceed legacy safety thresholds.
- Biological Mesh:Human or porcine-derived acellular matrices processed for implantation. Australia's enhanced consent protocols for permanent implants are compressing synthetic volumes in favor of biologic alternatives where informed consent narratives align with patient risk perception.
- Polyvinyl Alcohol:Synthetic absorbable polymer with controlled hydrolytic degradation. Limited commercial traction due to tensile strength limitations during tissue integration period.
- Polyester:Multifilament woven or knitted mesh with higher stiffness profiles. Historical erosion complications have constrained adoption across Asia-Pacific markets.
Volume leadership belongs to Polypropylene. Biological Mesh is gaining share fastest.
Application:
Customer type differentiation separates high-volume stress incontinence procedures from complex pelvic reconstruction requiring specialized surgical expertise.
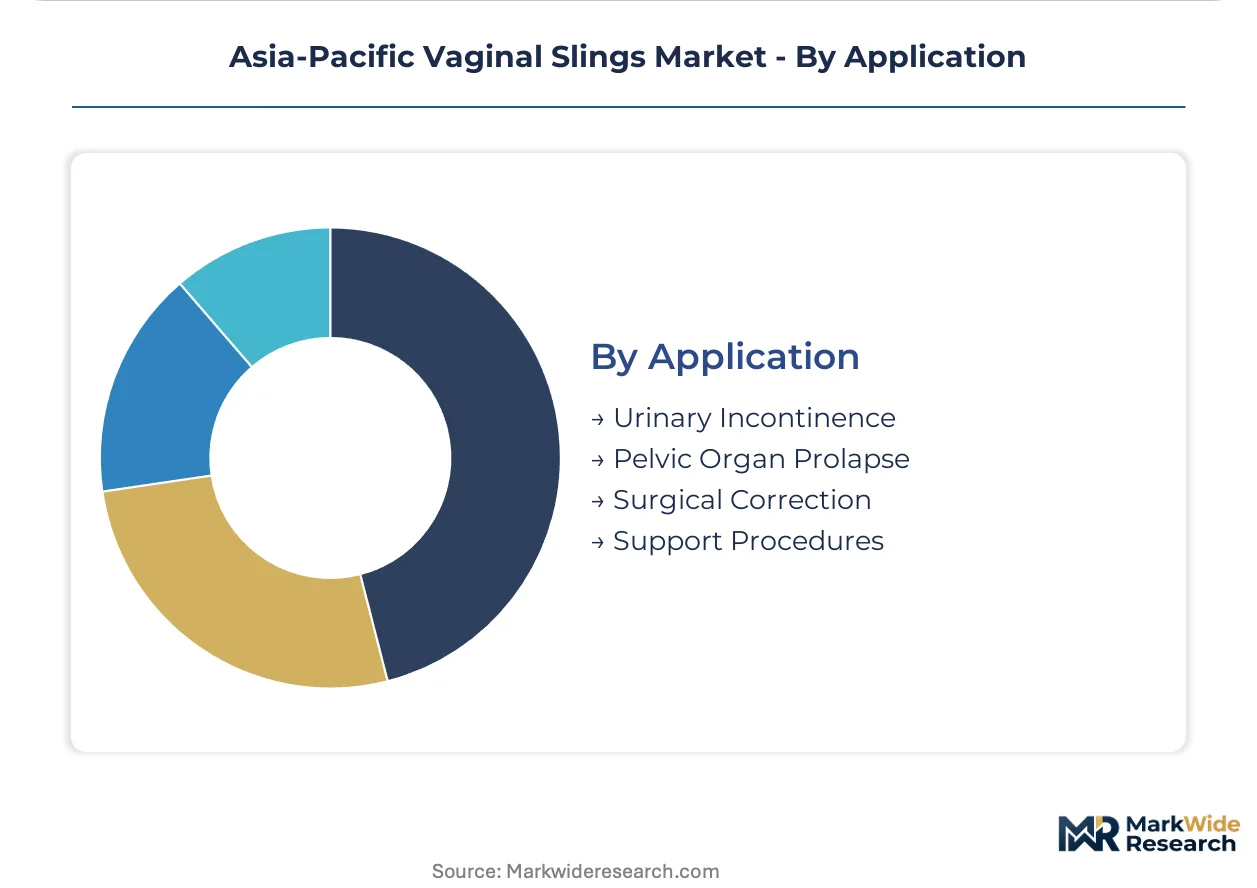
- Urinary Incontinence:Mid-urethral sling placement for stress urinary incontinence in women with urethral hypermobility or intrinsic sphincter deficiency. Australia's aging female population sustains procedure demand supported by surgical reimbursement tiers.
- Pelvic Organ Prolapse:Apical or anterior compartment support using mesh-augmented repairs. PMDA's tightened biocompatibility requirements are forcing manufacturers toward safer material alternatives in this high-risk application.
- Surgical Correction:Revision procedures addressing recurrent incontinence or mesh complications. Fellowship-trained surgeon scarcity constrains volume growth despite patient need.
- Support Procedures:Prophylactic mesh placement during concomitant pelvic surgery. Limited evidence base restricts reimbursement authorization across Asia-Pacific jurisdictions.
Procedure concentration centers on Urinary Incontinence. Pelvic Organ Prolapse shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as PMDA's tightened biocompatibility standards in Japan drive cost-conscious producers toward Australia's TGA-aligned compliance pathways. Cost-of-compliance gaps between Tokyo and Sydney are redirecting R&D investment flows across the region.
Japan
Aging demographics sustain procedure volume growth as women over 55 represent the dominant patient cohort for stress urinary incontinence interventions. PMDA's revised medical device standards mandate extended biocompatibility testing timelines that favor established manufacturers with dedicated regulatory affairs teams. Tokyo's tertiary urogynecology clusters concentrate fellowship-trained surgical capacity and drive adoption of next-generation mesh materials.
Australia
Enhanced patient consent protocols for permanent implants are compressing synthetic sling volumes while elevating documentation burdens for device representatives. TGA's regulatory framework offers streamlined equivalence pathways for manufacturers holding Japanese or US approvals, attracting regional headquarters placement. Sydney and Melbourne's private hospital networks are consolidating vendor relationships around integrated supply contracts covering 60-70 percent of annual sling volumes.
South Korea
Expanded procedure codes for outpatient sling placements are accelerating channel shift from inpatient hospital settings toward ambulatory surgical centers. MFDS maintains alignment with international harmonization initiatives, reducing regulatory friction for multinational entrants. Seoul's metropolitan medical clusters concentrate both diagnostic workup capacity and same-day discharge infrastructure.
India
Underpenetrated urogynecology sectors in tier-2 cities present volume expansion opportunities as surgical training programs expand beyond Delhi and Mumbai. CDSCO's ongoing alignment with international mesh classification frameworks is creating compliance clarity for new entrants targeting the subcontinent. Maharashtra and Karnataka's academic medical centers anchor specialist surgeon training pipelines.
China
Domestic manufacturers are capturing share in provincial hospital procurement as NMPA accelerates review timelines for domestically manufactured Class III devices. Yangtze River Delta medical device clusters are integrating polypropylene mesh production with upstream polymer supply chains. Shanghai's tertiary hospitals balance cost pressures against patient demand for premium biologic alternatives.
Asia-Pacific Vaginal Slings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioresorbable material differentiation and ambulatory channel specialization. The vendor base stratifies across three tiers: multinational device conglomerates with integrated manufacturing footprints, mid-scale regional specialists with concentrated channel relationships, and domestic challengers leveraging cost-positioned synthetic platforms. Strategic archetypes include certification-tied training network operators, integrated procedure kit bundlers, and regulatory-fast followers exploiting harmonization gaps. Dominant competitive moves center on surgeon certification program expansion and backward integration into medical-grade polymer supply.
Among US-based multinationals, Boston Scientific Corporation and Medtronic exemplify the integrated manufacturing archetype with sustained cost advantages across multiple sling formats. Coloplast occupies a position within the specialized channel relationship tier, anchoring urogynecology center partnerships in Australia and Japan. These three entities represent contrasting strategic postures: scale-driven vertical integration, clinical training network depth, and premium segment focus through biologic alternatives.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Coloplast |
| Johnson & Johnson (Ethicon) |
| Promedon Group |
| Medtronic |
| B. Braun Melsungen AG |
| Neomedic International |
| Cook Biotech |
| Caldera Medical |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between PMDA-validated premium meshes and commodity polypropylene platforms splits both pricing power and sourcing strategies across Asia-Pacific procurement committees. Japan's tertiary hospitals concentrate demand around validated bioresorbable materials commanding substantial premiums, while India's CDSCO-aligned entrants compete on cost-positioned synthetic formats that bypass extended regulatory timelines.
Pricing Analysis
Distributor margins for integrated procedure kits absorb 15-25 point spreads between standalone mesh suppliers and full-system vendors across Australian private hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects PMDA certification status, biocompatibility test depth, and surgeon training bundling. Cost compression in economy-tier polypropylene meshes intensifies as Yangtze River Delta manufacturers scale domestic output. Price sensitivity concentrates among India's tier-2 hospital procurement committees, while Japan's academic medical centers prioritize safety documentation over unit cost.
Supply Chain Analysis
Workforce availability for medical-grade polymer knitting and sterilization validation constrains capacity expansion in China's Yangtze River Delta and South Korea's Gyeonggi-do clusters. Raw material flows draw from Saudi petrochemical feedstocks, Japanese precision polymer extrusion, and German textile knitting equipment. Single-source vulnerability in medical-grade polypropylene resin creates exposure when primary suppliers face production constraints. Distribution runs through hospital buying committees consolidating around integrated supply contracts in Australia and Japan, with direct manufacturer relationships penetrating South Korea's ambulatory surgical center expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on bioresorbable material premiums displacing commodity polypropylene volumes, coupled with ambulatory channel shift reducing overhead absorption per procedure.
For Market Incumbents: Anchor market position through captive supply of medical-grade polymers and exclusive surgeon certification networks that lock out unaffiliated competitors. Deepen backward integration into polymer resin sourcing to offset petrochemical feedstock volatility. Defend against emerging bioresorbable specialists by accelerating PMDA submission timelines for next-generation platforms. For New Entrants and Emerging Players: CDSCO harmonization in India opens a window for cost-positioned synthetic mesh suppliers targeting underpenetrated tier-2 urogynecology sectors. Focus initial penetration on Maharashtra and Karnataka academic medical centers building surgeon training pipelines. Leverage streamlined equivalence pathways for manufacturers holding TGA or PMDA approvals to compress market entry timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone mesh suppliers lack integrated trocar and fixation system bundling capabilities required by Australian and Japanese hospital buying committees. Mid-scale regional specialists with concentrated channel relationships in premium reimbursement environments represent priority acquisition archetypes. Watch for PMDA biocompatibility standard revisions as inflection signals for material science R&D valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Biocompatibility Submission | Accelerated regulatory validation in Japan unlocks premium hospital procurement access. |
| Surgeon Certification Network Expansion | Sticky demand relationships in Australia and South Korea raise competitive barriers. |
| Integrated Procedure Kit Bundling | Hospital buying committee consolidation in Sydney and Melbourne marginalizes standalone suppliers. |
| Ambulatory Surgical Center Partnership | South Korea's expanded procedure codes enable channel shift from inpatient settings. |
| Bioresorbable Platform Development | Controlled degradation profiles capture margin pools in Japan's risk-averse patient cohorts. |
Research Methodology
Bottom-up procedure volume modeling reconciled against top-down medical device import tracking forms the analytical core of this study. Primary interviews with urogynecology department heads, hospital procurement managers, biomedical engineers, and GPO contracts specialists informed demand-side assumptions. Secondary validation drew from PMDA medical device filings, TGA regulatory updates, CDSCO classification harmonization notices, and hospital procurement database extracts. Top-down supply-side analysis triangulated against bottom-up surgical volume estimates across Japan, Australia, South Korea, India, and China.
Historical trendline analysis of sling placement volumes, reimbursement code expansions, and regulatory approval timelines anchored the projection framework. Segmentation dimensions modeled include product type, material composition, end-user facility tier, and application complexity. CAGRs were derived from fitted growth curves applied to procedure volume baselines, adjusted for regulatory friction and surgeon supply constraints. Industry-specific inputs incorporated PMDA biocompatibility testing timeline extensions, TGA consent protocol documentation burdens, and ambulatory procedure code expansion trajectories.
Revisions become necessary when PMDA tightens biocompatibility thresholds beyond current testing protocols, when polypropylene feedstock disruptions exceed historical volatility bands, or when Australia's TGA mandates further consent documentation layers. Forecasts reflect documented assumptions regarding surgeon training pipeline expansion, reimbursement rate stability, and regulatory harmonization progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Oxygen Generator Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Laryngoscopes Market
Medical Devices
Capsulotomy Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Global Intraosseous Devices Market