
 Bronchial Blocker Devices Market | 2026-2036
Bronchial Blocker Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchial Blocker Devices Market Analytics
The capital-intensity divergence between integrated device manufacturers and specialized catheter producers is unwinding traditional competitive boundaries in airway management. Teleflex Incorporated leverages its broad anesthesia and critical care portfolio to sustain bundled contracting advantages with hospital purchasing consortia. Cook Medical anchors its position through deep specialization in interventional radiology and pulmonology catheters, while Ambu A/S competes on disposable single-use designs that address infection control priorities.
Bronchial blocker devices are catheter-based instruments designed for selective lung isolation during thoracic surgery, typically featuring an inflatable cuff mechanism with a central lumen for ventilation of the contralateral lung and operational diameters compatible with standard endotracheal tubes. These devices serve the primary commercial purpose of enabling one-lung ventilation without requiring double-lumen endotracheal tube placement, reducing airway trauma risk in patients with difficult airways or postoperative ventilation requirements. Single-lumen bronchial blockers occupy the mature volume tier where standardization drives procurement efficiency, while emergent deployment configurations represent the fastest-growing structural segment as pre-hospital and emergency department airway protocols expand. Visualization tools technology commands premium positioning within the technology dimension, as integrated fiberoptic or video-assisted placement systems reduce procedural failure rates and support premium pricing.
FDA premarket notification pathways and ISO 13485 quality management standards govern device commercialization, with the former dictating clinical evidence requirements for novel cuff materials or deployment mechanisms and the latter mandating process controls across design transfer and manufacturing. The EU Medical Device Regulation extends conformity assessment burdens for European market access, particularly for devices incorporating advanced materials or robotic-assisted placement features. Stakeholders must monitor how evolving surgical training paradigms and simulation-based competency requirements reshape purchasing criteria for bronchial blocker platforms.
Market Dynamics
FDA's updated premarket notification requirements for airway management devices are compressing product development timelines and forcing manufacturers to front-load clinical evidence generation before design finalization.
Growth Catalysts
- Minimally Invasive Thoracic Surgery Expansion:Academic medical centers across the United States are scaling one-lung ventilation protocols for video-assisted thoracoscopic procedures, driving procedural volume growth for selective lung isolation devices.
- ISO 13485 Quality Standard Harmonization:Global alignment of quality management requirements is reducing duplicate certification burdens for manufacturers seeking multi-regional market access.
- Difficult Airway Algorithm Integration:Anesthesiology societies are incorporating bronchial blockers into standardized difficult airway management pathways, embedding device utilization into clinical training curricula.
Market Restraints
- Silicone Cuff Material Cost Volatility:Medical-grade silicone supply concentrates among Asian petrochemical processors, exposing manufacturers to input price swings and forcing hedging strategies.
- Double-Lumen Tube Substitution Threat:Established double-lumen endotracheal tubes retain preference in high-volume thoracic centers with standardized difficult airway infrastructure.
- EU MDR Conformity Assessment Burden:The Medical Device Regulation's expanded clinical evidence requirements for novel cuff materials or robotic-assisted placement features are extending European market entry timelines.
Strategic Opportunities
- Pre-Hospital Emergency Deployment:Emergency medical services in the United States are piloting bronchial blocker protocols for traumatic lung injury management, creating new utilization contexts outside operating rooms.
- Fiberoptic-Video Convergence:Integration of disposable video bronchoscopes with blocker placement systems is enabling real-time visualization without capital equipment investment.
- Simulation-Based Training Mandates:ACGME requirements for competency-based thoracic anesthesia training are institutionalizing device-specific purchasing criteria for residency programs.
Industry Challenges
- Specialized Anesthesiologist Skill Scarcity:One-lung ventilation expertise concentrates among fellowship-trained thoracic anesthesiologists, limiting device utilization in community hospital settings without procedural volume to sustain competency.
- Legacy EMR Integration Complexity:Blocker placement documentation workflows require custom EHR module development, creating implementation friction for hospital systems with entrenched anesthesia information management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchial Blocker Devices Market |
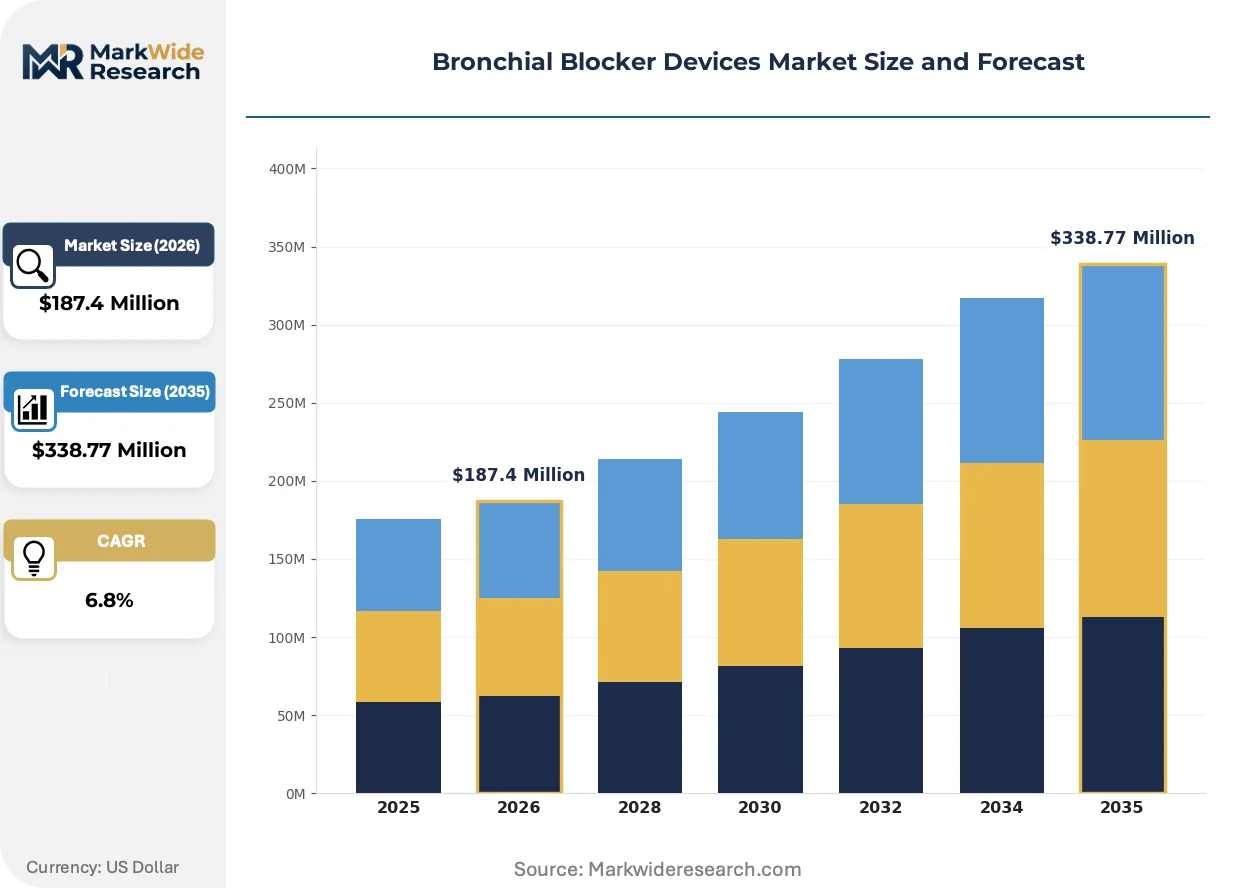
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lumen, Double Lumen, Wire-Guide, Emergent End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Emergency Departments Deployment: Hospital-Based, Home Care, Research Institutions, Training Centers Technology: Advanced Materials, Inflatable Devices, Robotics, Visualization Tools |
| Companies Covered | Teleflex Incorporated, Cook Medical, Fuji Systems Corporation, Edwards Lifesciences, ETView Medical Ltd., Daiken Medical Co. Ltd., Smiths Medical, Medtronic plc, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchial Blocker Devices Market Evolving Landscape
Device architecture is converging with visualization modalities and disposable economics, compressing the traditional separation between airway hardware and imaging systems.
Multi-lumen bronchial blocker catheter designs are miniaturizing cuff inflation channels while preserving central ventilation lumens, enabling lower-profile insertion through standard single-lumen endotracheal tubes. Thoracic surgery departments at tertiary referral centers are adopting these configurations for patients with marginal airway anatomy. The technology is miniaturizing procedural footprints and displacing larger-bore alternatives in ambulatory surgical settings where rapid emergence protocols predominate.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are mandating systematic collection of real-world performance data for airway devices with novel materials. Manufacturers must now maintain active implant registries or equivalent follow-up systems for Class IIa and above classifications. Bronchial blocker platforms incorporating absorbable cuff materials or antimicrobial coatings face disproportionate documentation burdens, slowing European launch sequences relative to FDA-cleared US introductions.
Hospital purchasing consortia are consolidating anesthesia device procurement under single-source agreements that bundle bronchial blockers with laryngoscopes, breathing circuits, and airway exchange catheters. Independent distributors and specialized surgical supply intermediaries are losing share to direct manufacturer-contracted arrangements with integrated delivery networks. The behavioral shift is most visible in the United States, where health system consolidation has concentrated buying power among ten to fifteen national purchasing organizations.
Bronchial Blocker Devices Market Segmentation
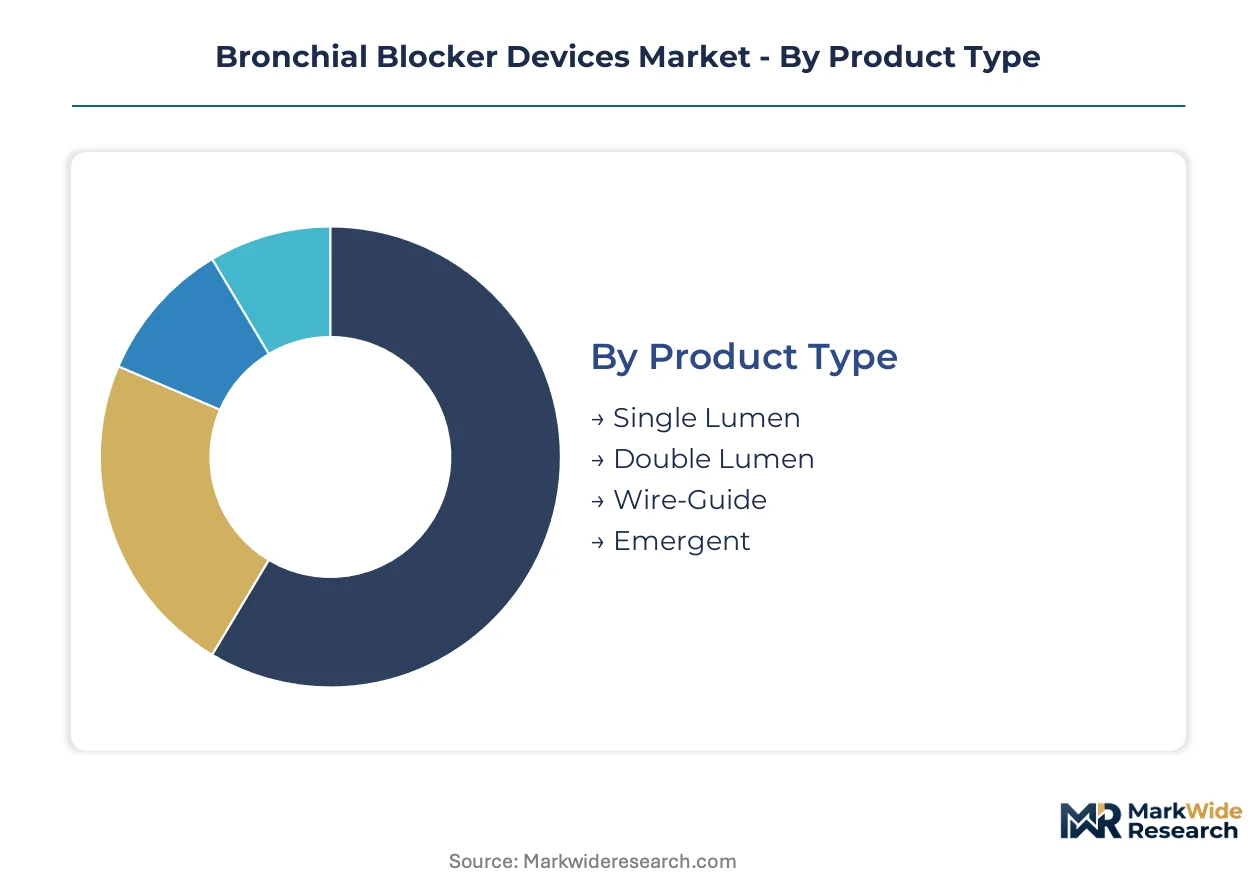
Bronchial blocker procurement patterns diverge sharply across clinical settings and technological sophistication tiers. Understanding these fault lines reveals where manufacturers must anchor R&D investment versus where commodification pressures dominate purchasing decisions.
Product Type:
Margin pools concentrate in configurations that reduce procedural failure rates and enable premium positioning through integrated visualization capabilities.
- Single Lumen:Standard catheter designs with central ventilation channels and low-profile inflatable cuffs dominate high-volume thoracic surgery programs. Demand clusters at academic medical centers in the United States where bundled anesthesia procurement agreements favor standardized, disposable formats.
- Double Lumen:Parallel-channel architectures enable simultaneous ipsilateral suction and contralateral ventilation, commanding price premiums in complex airway reconstruction cases. Adoption concentrates among fellowship-trained thoracic anesthesiologists at tertiary referral hospitals managing marginal pulmonary reserve patients.
- Wire-Guide:Steerable catheter systems with integrated stylets for difficult airway navigation.
- Emergent:Pre-hospital deployment configurations with rapid-deployment packaging for trauma and mass casualty protocols.
Single Lumen holds installed capacity. Emergent is rotating up the share rankings.
End User:
Procurement authority and volume scale determine contract structure complexity across institutional buyer types.
- Hospitals:Integrated delivery networks with centralized anesthesia supply chains negotiate multi-year agreements covering bronchial blockers alongside laryngoscopes and breathing circuits. The United States health system consolidation has concentrated purchasing power among fifteen national purchasing organizations, compressing distributor margins.
- Ambulatory Surgical Centers:Freestanding facilities performing video-assisted thoracoscopic procedures favor single-use disposable blockers with minimal capital equipment requirements. Demand is climbing fastest in metropolitan markets where outpatient thoracic surgery volumes are expanding.
- Specialty Clinics:Pulmonology-focused centers performing interventional bronchoscopy procedures.
- Emergency Departments:Trauma centers piloting selective lung isolation for penetrating chest injuries.
Hospitals anchor procurement volume. Ambulatory Surgical Centers are gaining share fastest.
Deployment:
Regulatory classification burden and reimbursement pathway clarity shape market entry economics by setting.
- Hospital-Based:Operating room and intensive care unit deployment under anesthesiologist supervision represents the mature revenue base. FDA premarket notification pathways for novel cuff materials or robotic-assisted placement features dictate clinical evidence requirements before commercialization.
- Home Care:Post-discharge ventilation management in palliative care contexts.
- Research Institutions:Academic medical centers conducting device innovation trials.
- Training Centers:ACGME-accredited simulation facilities with competency-based thoracic anesthesia curricula.
Hospital-Based deployment maintains volume leadership. Training Centers are climbing the fastest.
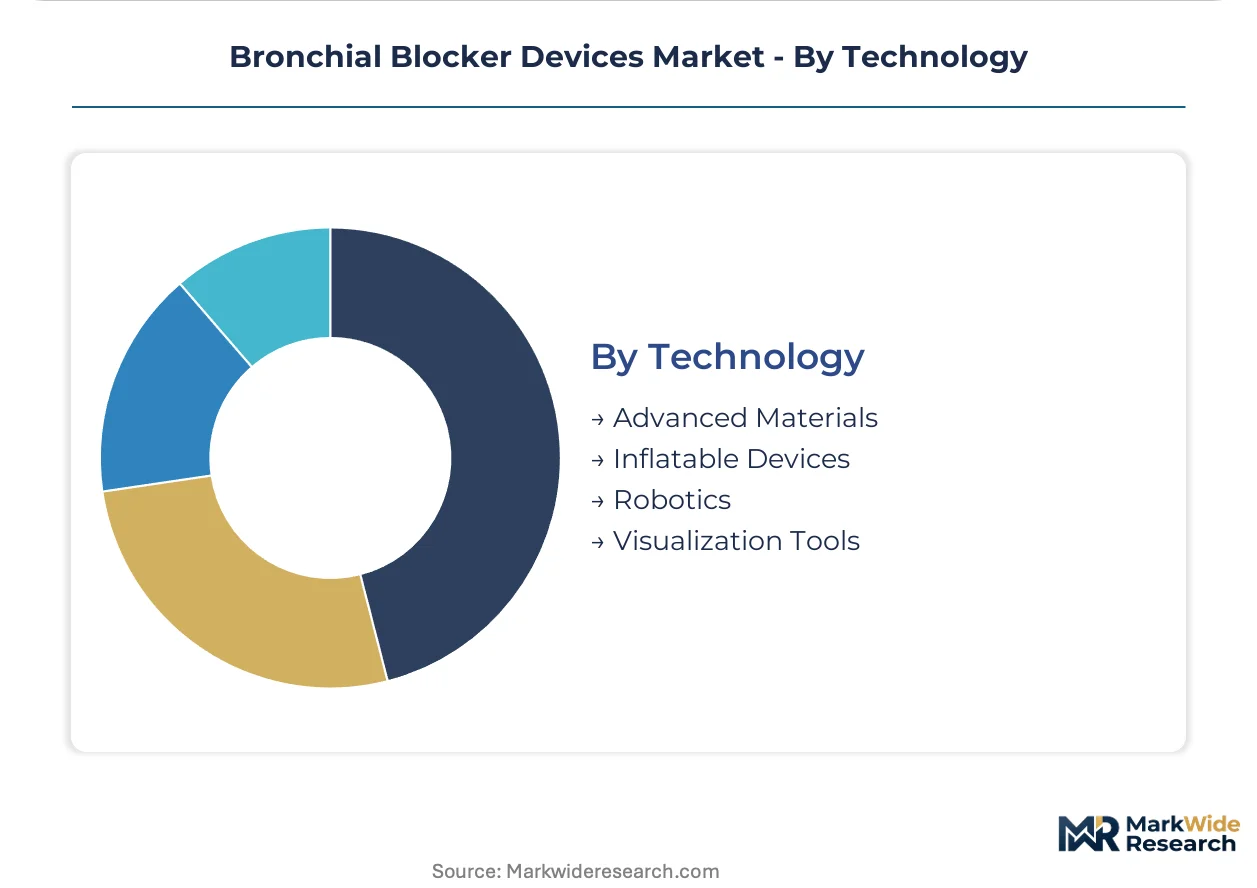
Technology:
Patent-protected material science and integrated imaging capabilities defend margin structures against generic substitution.
- Advanced Materials:Medical-grade silicone and thermoplastic elastomer formulations with antimicrobial surface coatings face heightened EU MDR post-market surveillance documentation burdens. The conformity assessment requirements extend European launch timelines relative to FDA-cleared United States introductions.
- Visualization Tools:Fiberoptic-integrated and video-assisted placement systems reduce first-attempt failure rates and support premium pricing. Demand concentrates at United States academic centers where simulation-based training mandates institutionalize device-specific purchasing criteria.
- Inflatable Devices:Cuff mechanism designs with pressure-regulated inflation systems.
- Robotics:Robotic-assisted placement platforms with haptic feedback and automated positioning.
Inflatable Devices hold installed capacity. Visualization Tools are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States thoracic centers deploy bronchial blockers predominantly for complex video-assisted procedures, while German and Japanese hospitals favor them for routine lung isolation in high-volume academic settings. This procedural-intensity differential shapes purchasing criteria and premium-tier adoption rates.
United States
Academic medical centers in Boston, Houston, and Cleveland drive demand through expanding minimally invasive thoracic surgery programs. FDA premarket notification pathways for novel cuff materials compress development timelines and front-load clinical evidence requirements. The Texas Medical Center cluster anchors volume leadership for complex cardiothoracic procedures.
Germany
Tertiary hospitals in Munich and Heidelberg integrate bronchial blockers into standardized difficult airway algorithms for thoracic anesthesia training. EU MDR conformity assessment extends launch timelines for devices with antimicrobial coatings or advanced materials. The Baden-Württemberg medical device corridor concentrates manufacturing and clinical validation partnerships.
Japan
Tokyo and Osaka metropolitan hospitals favor single-use disposable formats aligned with infection control protocols and aging population thoracic surgery volumes. PMDA quality management requirements harmonize with ISO 13485 standards for streamlined multi-regional certification. The Kansai region clusters simulation-based competency training for thoracic anesthesiologists.
China
Shanghai and Beijing tertiary hospitals pilot robotic-assisted placement platforms for complex airway reconstruction cases. NMPA regulatory pathways for Class IIa airway devices mandate domestic clinical trials before commercialization. The Yangtze River Delta medical technology corridor attracts joint ventures for localized production.
United Kingdom
London and Manchester teaching hospitals concentrate procurement through NHS Supply Chain centralized agreements for anesthesia devices. MHRA post-Brexit regulatory alignment with EU MDR maintains conformity assessment burdens for novel materials. The Oxford-Cambridge-London golden triangle anchors academic device innovation trials.
Bronchial Blocker Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in bronchial blocker supply. Teleflex Incorporated and Medtronic plc leverage anesthesia and critical care portfolio breadth for bundled contracting with hospital purchasing consortia. Specialized catheter producers including Cook Medical and Ambu A/S compete on deep pulmonology expertise and disposable single-use economics. Dominant competitive moves center on strategic partnerships for fiberoptic-video integration and geographic expansion through distributor consolidation.
Within the integrated-device tier, Teleflex Incorporated and Medtronic plc represent bundled-procurement anchors, while Ambu A/S exemplifies the disposable-specialist archetype addressing infection-control priorities. Cook Medical occupies a position bridging deep catheter specialization with interventional radiology cross-selling. Fuji Systems Corporation and Daiken Medical Co. Ltd. sit within the Asia-Pacific manufacturing cluster, serving regional demand through localized quality management certification.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Cook Medical |
| Fuji Systems Corporation |
| Edwards Lifesciences |
| ETView Medical Ltd. |
| Daiken Medical Co. Ltd. |
| Smiths Medical |
| Medtronic plc |
| Ambu A/S |
| Others |
Value Network & Pricing Analysis
ISO 13485 quality management certification gates both supplier qualification and price tiering in bronchial blocker procurement, as hospitals demand documented process controls before awarding multi-year anesthesia supply contracts. The regulatory burden concentrates purchasing power among integrated device manufacturers who can absorb compliance costs, while specialized catheter producers compete on disposable economics at lower price points.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with integrated delivery networks negotiating bundled contracts covering bronchial blockers alongside laryngoscopes and breathing circuits. Price differentiation rests on certification tier and after-sales service bundling, with FDA-cleared visualization-integrated systems commanding premiums over standard single-lumen formats. Cost compression in the single-use disposable tier is intensifying because Ambu A/S and similar specialists are scaling automated production lines. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize performance metrics over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asian petrochemical processors through the Port of Los Angeles and Rotterdam container terminals expose manufacturers to vessel availability constraints and demurrage risk. Medical-grade silicone and thermoplastic elastomer formulations draw from concentrated supply bases in China, South Korea, and Japan, with cuff material fabrication tethered to regional polymer processing clusters. Single-source vulnerability runs through Japanese silicone suppliers serving premium visualization-integrated product lines. Distribution runs through direct manufacturer contracts with hospital purchasing consortia, displacing independent surgical supply intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bronchial blocker supply constitutes a defensive-moat market where regulatory entrenchment creates switching costs that lock hospital systems into validated supplier relationships. The ISO 13485 and FDA premarket notification pathways embed incumbent advantages through multi-year certification timelines that new entrants cannot compress.
For Market Incumbents: Shield market position by deepening backward integration into medical-grade silicone compounding to offset Asian petrochemical price volatility, while expanding simulation-based training partnerships with ACGME-accredited residency programs to embed device-specific purchasing criteria. The double-lumen endotracheal tube substitution threat demands continuous visualization technology investment to maintain procedural outcome differentiation. For New Entrants and Emerging Players: Lead with fiberoptic-video convergence platforms targeting ambulatory surgical centers in metropolitan United States markets where outpatient thoracic surgery volumes are expanding fastest and capital equipment constraints favor disposable integrated solutions. Pre-hospital emergency deployment configurations represent the most penetrable white-space segment, with trauma center pilot programs creating new utilization contexts outside traditional operating room procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable single-use bronchial blocker manufacturing as automated catheter production lines achieve scale economies previously reserved for reusable device formats. Acquisition targets should display deep pulmonology catheter specialization with established ISO 13485 quality systems and existing GPO contract access. The signal to monitor is FDA premarket notification backlog duration, as extended review timelines compress valuation multiples for development-stage platforms awaiting clearance.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Front-loaded clinical evidence requirements compress development timelines for novel cuff materials. |
| CE Marking Pathway | EU MDR conformity assessment burdens extend European launch sequences for antimicrobial-coated platforms. |
| Hospital System Partnership | Bundled anesthesia procurement agreements with integrated delivery networks displace distributor intermediaries. |
| Software Companion Development | EMR integration modules for blocker placement documentation reduce implementation friction in entrenched hospital systems. |
| Reimbursement Strategy | One-lung ventilation procedure coding alignment with CMS Medicare data supports volume expansion in academic centers. |
Research Methodology
Initial hypotheses were tested against primary input from thoracic anesthesiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, ISO 13485 audit records, hospital procurement databases, and CMS Medicare procedure volume data. Bottom-up segment sizing triangulated with top-down macroeconomic elasticity checks across the analysis window.
Variance decomposition across product type, end user, deployment setting, and technology tier enabled identification of growth contribution by segment. CAGRs were derived from logistic diffusion curves fitted to procedural volume data and equipment replacement cycles. Forecast inputs incorporated ACGME training mandate implementation schedules and EU MDR transition timelines for post-market surveillance requirements.
The analysis sits within stated boundaries; outcomes outside sustained FDA review bandwidth, stable medical-grade silicone supply, and continued health system consolidation would require recalibration. Forecasts reflect documented assumptions regarding procedural volume trajectories and regulatory pathway durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Hemostats Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Cryoablation System Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Cytology Brush Market