
 Skin Traction Kits Market | 2026-2036
Skin Traction Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Traction Kits Market Analytics
Polyester webbing is broadening its share against cotton straps in skin traction kits by offering superior moisture resistance and longer service life. Chattanooga Group leverages extensive distribution networks across North American rehabilitation centers to sustain its market presence. Medtronic anchors its position through R&D intensity focused on integrated orthopedic solutions. Suzhou Texnet competes on manufacturing scale, supplying cost-competitive traction components to Asian hospital networks.
Skin traction kits comprise adjustable belts, calibrated weight systems, adhesive skin interfaces, and pulley mechanisms designed to apply controlled longitudinal force to fractured or postoperative limbs without surgical intervention. These devices typically specify load capacities, skin contact surface areas, and angle adjustment ranges to ensure safe ambulatory or bed-bound traction therapy. Traction belts and pulley systems represent the established revenue core, while smart devices within the technology dimension signal the fastest structural expansion as sensor-enabled load monitoring gains clinical traction. Home care as an end-user channel is maturing rapidly, though hospitals retain the dominant margin pool due to bulk procurement contracts and specialized orthopedic department requirements.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access thresholds for skin traction kit manufacturers. ISO 13485 quality management standards further govern production consistency across international supply chains. Stakeholders must monitor evolving reimbursement codes for outpatient traction therapy and assess when sensor-integrated systems justify premium positioning against manual alternatives.
Market Dynamics
Orthopedic caseloads among aging populations are compressing hospital discharge timelines and elevating ambulatory traction protocols as the dominant care pathway. This demographic pressure is restructuring procurement volumes toward outpatient-compatible kit configurations.
Growth Catalysts
- FDA 510(k) clearance standardization:Streamlined premarket notification pathways for Class II orthopedic devices are reducing time-to-market for modified traction systems. Manufacturers leveraging predicate device strategies gain faster commercial traction.
- Polyester webbing material transition:Moisture-resistant synthetic straps are displacing cotton interfaces in humid climates and extended-use scenarios. Hospital materials management departments prioritize durability metrics in bulk purchasing decisions.
- Japan surgical infrastructure density:High per-capita orthopedic specialist concentration supports consistent kit utilization rates. Aging demographics in Japanese prefectures sustain procedure volume stability.
Market Restraints
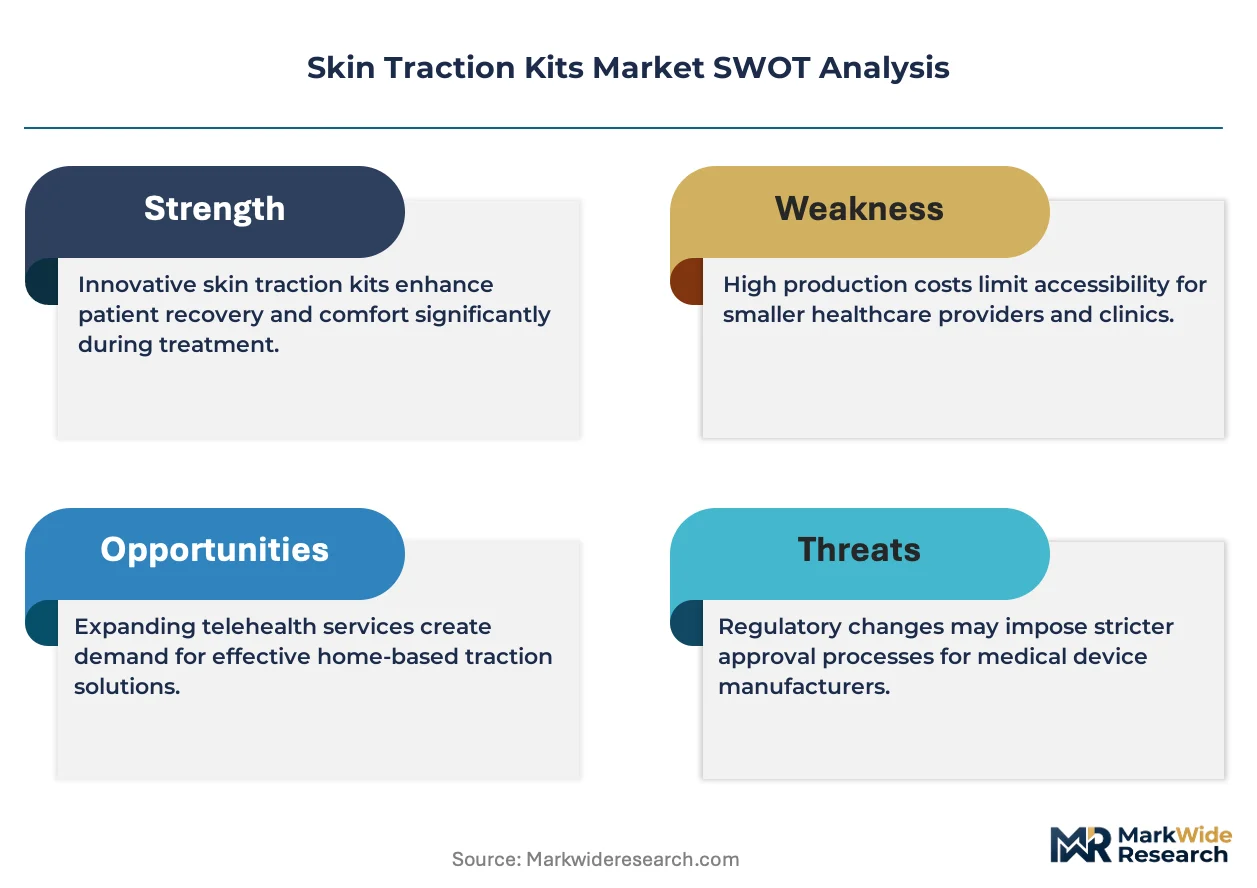
- EU MDR conformity assessment costs:Expanded clinical evidence requirements for legacy orthopedic devices are elevating compliance expenditures. Small-scale manufacturers face disproportionate notified body fee burdens.
- Adhesive skin interface supply concentration:Medical-grade adhesive sourcing clusters in German and Swiss chemical processing hubs. Geopolitical friction or logistics disruption threatens component availability.
- External fixation substitution:Minimally invasive surgical stabilization techniques are narrowing the addressable patient pool for prolonged skin traction therapy. Orthopedic surgeons increasingly favor immediate operative intervention.
Strategic Opportunities
- Home care channel maturation:Post-acute traction therapy outside institutional settings remains underdeveloped relative to inpatient saturation. Durable home-use kit configurations with simplified patient interfaces capture this white space.
- Sensor-load convergence:Integration of calibrated strain gauges with traditional pulley mechanisms enables real-time tension monitoring. This technology pairing supports remote patient management reimbursement frameworks.
- German outpatient procedure expansion:Ambulatory surgery center accreditation growth creates procurement entry points for portable traction systems. Regional hospital networks are consolidating orthopedic service lines.
Industry Challenges
- ISO 13485 quality system maintenance:Sustained certification demands specialized regulatory affairs personnel that mid-tier manufacturers struggle to retain. Audit preparation cycles consume engineering resources.
- Legacy hospital IT integration:Smart traction devices with data transmission capabilities face interoperability friction with established electronic health record architectures. Custom interface development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Traction Kits Market |
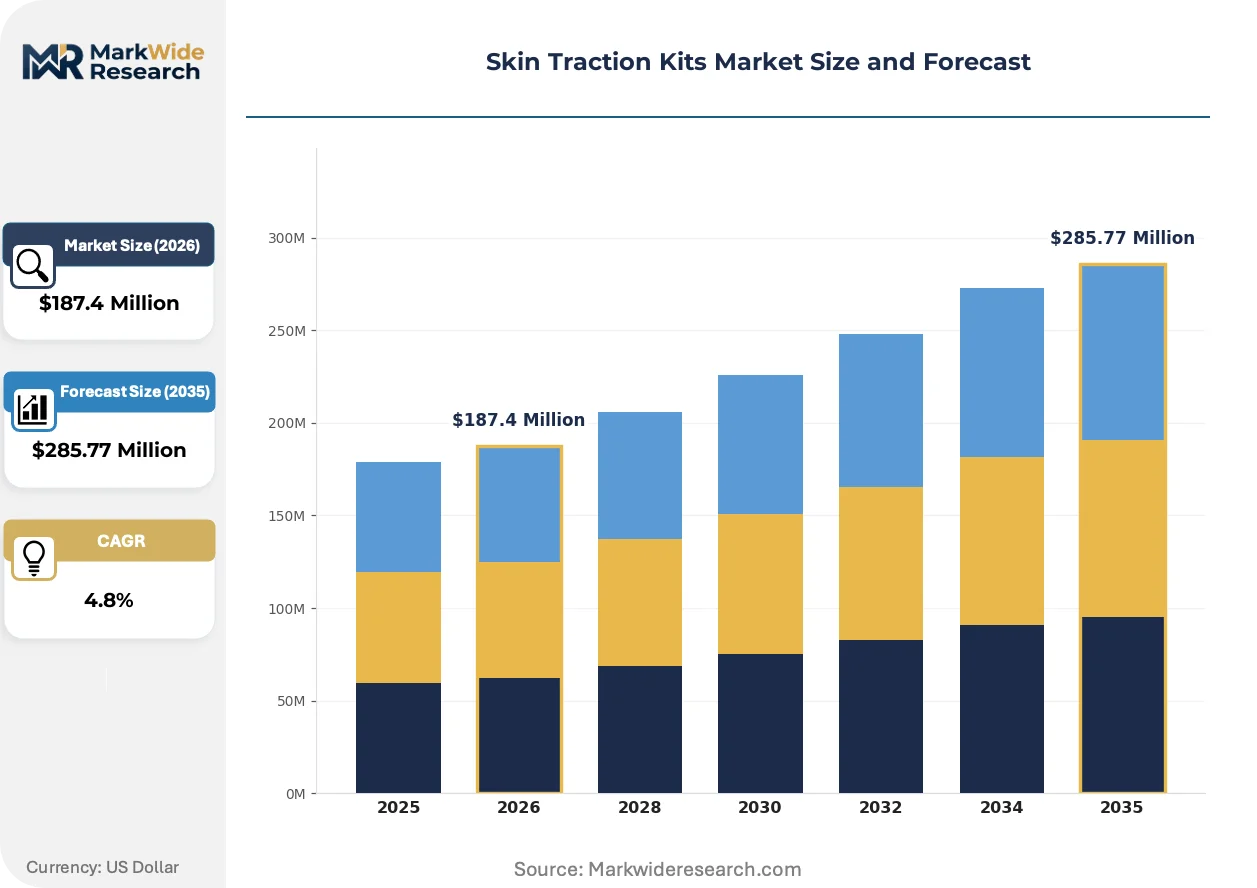
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traction Belts, Traction Weights, Adhesive Strips, Pulley Systems End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics Technology: Manual Systems, Electric Systems, Smart Devices, Traditional Kits Application: Bone Fractures, Postoperative Care, Sports Injuries, Pain Management |
| Companies Covered | The Saunders Group, Chattanooga Group, North American Medical, Spinetronics, Dentsply International, Medtronic, Spinal Designs International, Endure Industries, Suzhou Texnet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Traction Kits Market Evolving Landscape
Digital load monitoring is penetrating traction therapy protocols, compressing the gap between manual mechanical systems and integrated orthopedic care platforms. This convergence is redefining value capture points across the supply chain.
Sensor-enabled weight calibration systems are absorbing clinical validation investment that previously flowed toward pulley mechanism refinements. Academic medical centers in the United States are piloting Bluetooth-connected traction frames for remote tension adjustment. This technology absorption is compressing price premiums for conventional manual kits and elevating software-enabled service contracts as margin anchors.
EU MDR Article 10 technical documentation requirements are extending design dossier preparation timelines for orthopedic device manufacturers. Notified body capacity constraints are creating submission backlogs that delay market access. Traction kit suppliers with existing CE certificates under the Medical Devices Directive face compressed transition windows to maintain European market presence.
Hospital group purchasing organizations are consolidating orthopedic supply contracts and unbundling after-sales technical support from hardware procurement. This purchasing behavior shift is compressing distributor margins and favoring manufacturers with direct field service capabilities. The transformation is most visible in United States integrated delivery networks where standardization mandates span multi-state facility footprints.
Skin Traction Kits Market Segmentation
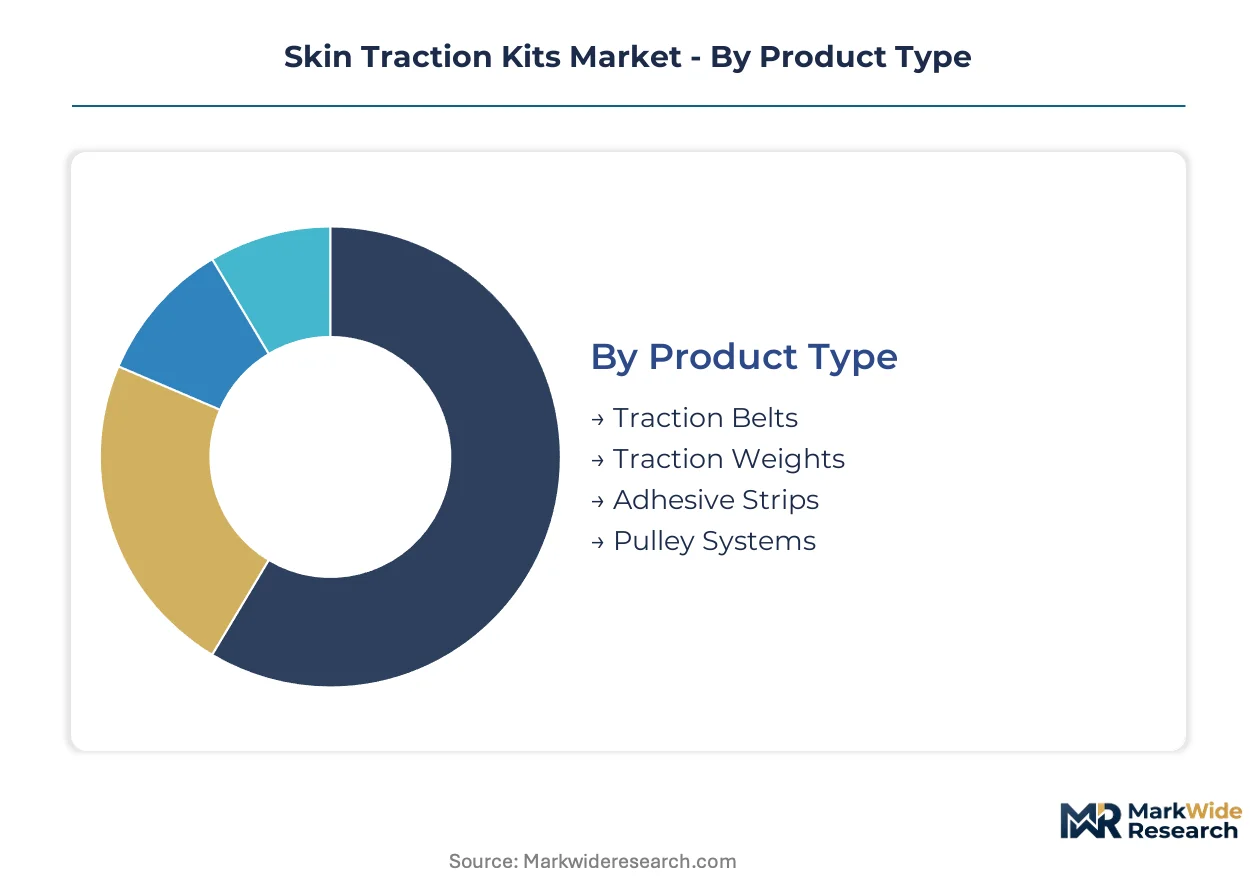
Skin traction kit procurement varies sharply across clinical settings and technical specifications. Manufacturers configure production lines around these segment boundaries to capture volume contracts and margin premiums.
Product Type:
Supply concentration for mechanical components shapes competitive positioning across product categories.
- Traction Belts:Polyester webbing and cotton straps with adjustable fastening mechanisms constitute the core load-bearing interface. Hospital procurement departments in the United States prioritize moisture-resistant synthetic variants for extended wear protocols.
- Pulley Systems:Calibrated wheel assemblies with angle adjustment ranges enable controlled force vectoring. German rehabilitation centers specify precision-machined aluminum housings for ambulatory traction setups.
- Traction Weights:Standardized mass sets with graduated increments permit progressive loading adjustments.
- Adhesive Strips:Medical-grade skin interfaces with hypoallergenic coatings secure traction attachment points.
Traction belts absorb the bulk of installed capacity; smart-enabled pulley configurations are expanding most quickly.
End User:
Channel economics diverge between institutional procurement and patient-directed purchasing.
- Hospitals:Bulk orthopedic department contracts drive volume concentration. Japanese prefectural hospital networks maintain standardized kit inventories across multi-facility systems.
- Home Care:Simplified patient interfaces with reduced mechanical complexity address post-discharge traction needs. Medicare reimbursement code expansions in the United States accelerate channel development.
- Rehabilitation Centers:Outpatient-focused configurations prioritize portability and rapid setup protocols.
- Sports Clinics:Acute injury management protocols favor lightweight, field-deployable traction systems.
Hospitals command the dominant procurement volume; home care channels are climbing the fastest.
Technology:
Regulatory clearance pathways stratify development investment across technical tiers.
- Manual Systems:Mechanical weight-and-pulley configurations without electronic components. FDA 510(k) predicate device strategies accelerate clearance timelines for established manufacturers.
- Smart Devices:Sensor-integrated systems with Bluetooth load monitoring and remote adjustment capabilities. Academic medical centers in the United States pilot these platforms for remote patient management frameworks.
- Electric Systems:Motorized tension control with programmable load profiles.
- Traditional Kits:Conventional designs meeting baseline clinical requirements without connectivity features.
Manual systems retain the largest installed base; smart devices are gaining share fastest.
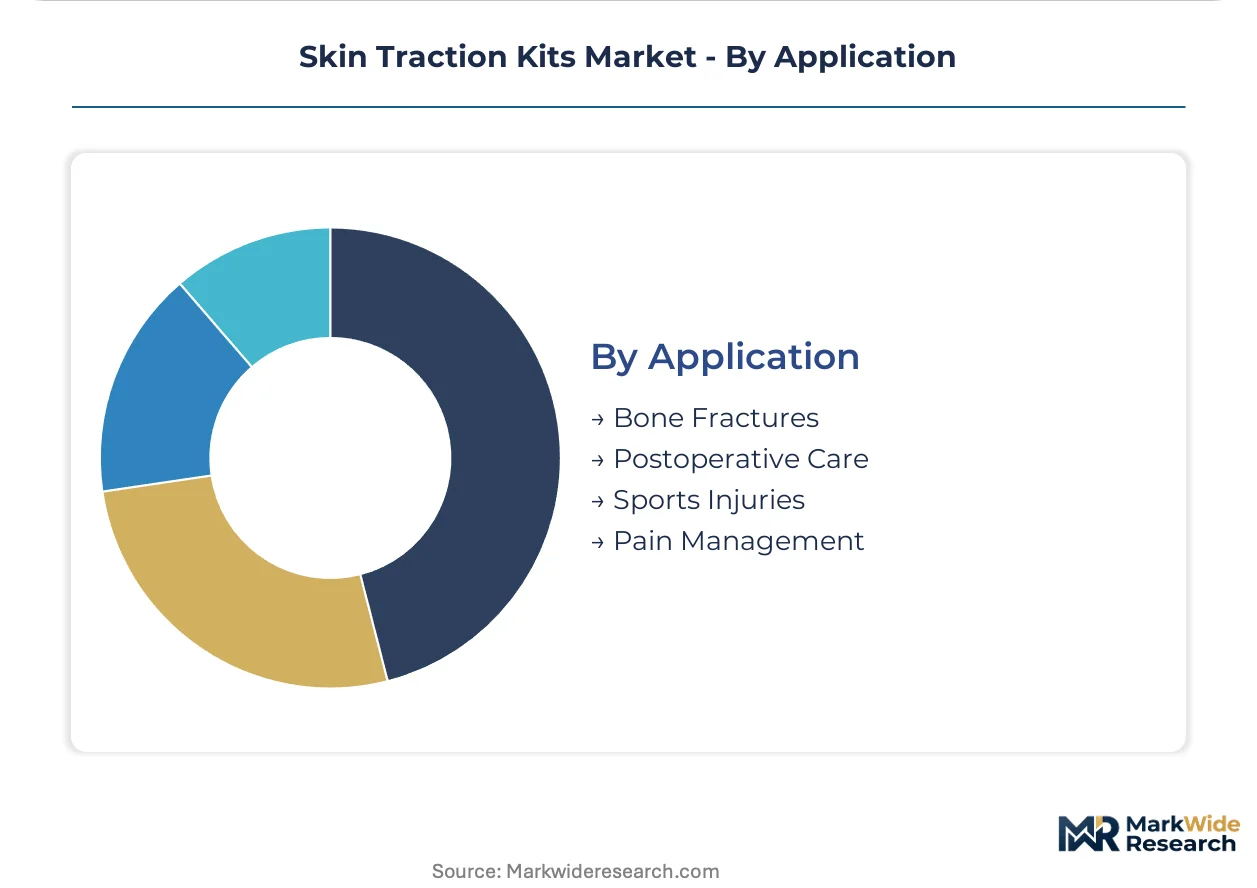
Application:
Procedure volume distribution across orthopedic subspecialties determines kit configuration demand.
- Bone Fractures:Longitudinal force application for femoral and tibial shaft injuries. Aging demographics in Japan sustain consistent utilization for hip fracture protocols.
- Postoperative Care:Traction therapy following joint replacement or spinal procedures. German ambulatory surgery center expansion creates procurement entry points for portable systems.
- Sports Injuries:Acute ligament and soft tissue trauma management.
- Pain Management:Non-surgical decompression protocols for chronic conditions.
Fracture applications anchor procurement volume; postoperative care is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of skin traction kits concentrates in aging economies with dense orthopedic specialist networks and established rehabilitation infrastructure. The United States, Germany, and Japan absorb the dominant share of installed capacity. Regulatory frameworks in these markets elevate compliance thresholds while regional manufacturing clusters compete on cost and proximity.
United States
Bulk orthopedic department contracts from integrated delivery networks drive procurement volume concentration. FDA 510(k) clearance pathways for Class II devices streamline market access for modified traction systems. The Southeast region, particularly Florida and Georgia, sustains elevated utilization rates among retirement-age demographics.
Germany
Ambulatory surgery center accreditation expansion creates procurement entry points for portable traction configurations. EU MDR conformity assessments and notified body oversight govern product development timelines. The Baden-Württemberg medical technology cluster around Stuttgart anchors precision component manufacturing for pulley mechanisms.
Japan
High per-capita orthopedic specialist concentration supports consistent kit utilization across prefectural hospital networks. PMDA regulatory oversight aligns with international quality standards through harmonized review processes. The Kanto region surrounding Tokyo maintains standardized inventory systems across multi-facility healthcare networks.
China
Domestic hospital network expansion and aging demographic pressure elevate traction therapy demand in tier-one cities. NMPA medical device registration requirements shape product localization strategies. The Yangtze River Delta manufacturing corridor supplies cost-competitive traction components to Asian hospital procurement channels.
United Kingdom
NHS orthopedic pathway standardization influences bulk purchasing decisions across regional hospital trusts. MHRA post-Brexit regulatory autonomy maintains alignment with international standards while streamlining conformity routes. The Midlands medical device manufacturing base supports component sourcing for rehabilitation equipment distributors.
Skin Traction Kits Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from mechanical components into sensor-integrated systems. The vendor base fragments across three tiers: multinational orthopedic conglomerates with integrated care platforms, regional specialists in traction mechanism fabrication, and Asian contract manufacturers supplying private-label components. Strategic archetypes include technology licensors seeking software-enabled service contracts, scale-driven fabricators competing on unit economics, and compliance-focused suppliers leveraging regulatory expertise as a moat. M&A activity and capacity expansion in polyester webbing production represent the dominant competitive moves.
Among North American rehabilitation equipment specialists, Chattanooga Group and The Saunders Group occupy positions within the premium-tier supply chain, while Suzhou Texnet represents the scale-driven manufacturing archetype from Chinese production bases. These anchors illustrate the geographic bifurcation between design-intensive markets and cost-optimized supply origins.
| Leading Market Players |
|---|
| The Saunders Group |
| Chattanooga Group |
| North American Medical |
| Spinetronics |
| Dentsply International |
| Medtronic |
| Spinal Designs International |
| Endure Industries |
| Suzhou Texnet |
| Others |
Value Network & Pricing Analysis
EU MDR Article 10 technical documentation mandates gate qualified supply access and premium-tier pricing power for skin traction kit manufacturers, compressing margins for non-compliant producers while elevating certified suppliers into higher-margin procurement tiers. Hospital group purchasing organizations leverage this compliance bifurcation to consolidate contracts around vendors with direct field service capabilities, reshaping how value distributes across mechanical and sensor-integrated product tiers.
Pricing Analysis
Volume concentrates in manual traction belts and pulley systems while margins concentrate in smart-enabled configurations with Bluetooth load monitoring. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared sensor-integrated systems from CE-marked mechanical kits and uncertified private-label alternatives. Pricing pressure stems from polyester webbing commoditization as Chinese manufacturers scale synthetic strap production. Home care channels exhibit highest price sensitivity due to direct patient purchasing; hospital orthopedic departments show lowest sensitivity where bulk contracts bundle after-sales technical support.
Supply Chain Analysis
Reverse-logistics flows for traction weight refurbishment and pulley mechanism recalibration anchor aftermarket revenue streams for established manufacturers serving extended-warranty contracts. Component sourcing concentrates in China for polyester webbing and machined aluminum housings, Germany for precision pulley assemblies, and Switzerland for medical-grade adhesive strips. Raw material dependencies include petroleum-derived synthetic fibers, aluminum billet stock, and hypoallergenic polymer coatings. Single-source vulnerability clusters in German and Swiss chemical processing hubs for skin-contact adhesives. Distribution runs through North American rehabilitation equipment distributors and Asian hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-load convergence is displacing legacy manual traction systems, redefining competitive advantage around software-enabled service contracts rather than hardware durability metrics. This technology transition compresses timelines for manufacturers to secure FDA 510(k) clearance for connected orthopedic devices.
For Market Incumbents: Extend sensor-integration roadmaps to capture remote patient management reimbursement frameworks before manual kit margins erode further. Chattanooga Group and Medtronic should deepen backward integration into strain gauge manufacturing to control component costs against Asian contract manufacturers. Prioritize ISO 13485 quality system maintenance as a compliance moat against mid-tier competitors facing notified body capacity constraints. For New Entrants and Emerging Players: Begin with home care channel configurations featuring simplified patient interfaces and Medicare-compatible reimbursement coding. The United States Southeast retirement corridors and German ambulatory surgery center networks represent the most penetrable white spaces. A direct-to-patient digital marketing angle, bypassing hospital procurement committees, accelerates initial traction against entrenched institutional suppliers. For Investors and Strategic Acquirers: FDA 510(k) submission volume acceleration for Class II orthopedic devices is the leading indicator that sensor-integrated traction platforms are approaching commercial inflection. Target acquisition profiles center on mid-scale manufacturers with existing CE marking under MDR transition timelines and captive polyester webbing production. Long-term viability over the next decade hinges on software service contract attach rates rather than hardware shipment volumes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates sensor-integrated traction system commercialization timelines. |
| CE Marking Transition | MDR conformity assessment completion preserves European market access for legacy orthopedic device portfolios. |
| Hospital System Partnership | Integrated delivery network contracts anchor volume procurement across multi-state rehabilitation service lines. |
| Software Companion Development | Bluetooth-connected load monitoring platforms capture recurring service revenue beyond hardware margins. |
| Reimbursement Strategy | Medicare code expansion for outpatient traction therapy unlocks home care channel payment pathways. |
Research Methodology
Multi-period observation of orthopedic procedure volumes, regulatory submission timelines, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with orthopedic surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary fieldwork drew from FDA 510(k) databases, EU notified body clearance registries, CMS Medicare reimbursement code filings, and orthopedic device import customs records. Bottom-up demand modeling across end-user channels triangulated against top-down market sizing from manufacturer revenue disclosures.
Segment-weighting approaches distributed analytical emphasis across product type, technology tier, end-user channel, and application category dimensions. CAGRs were derived from procedure volume elasticity to aging demographic projections and traction therapy protocol substitution rates across inpatient, outpatient, and home care settings. Modeled inputs included orthopedic caseload density per capita, ambulatory surgery center accreditation expansion trajectories, and sensor-integrated device pricing premium sustainability.
Regulatory timeline delays, adhesive component supply disruptions, and external fixation surgical substitution rates are the dominant revision risks to modeled forecasts. Practitioners should monitor FDA 510(k) clearance backlogs, notified body capacity constraints, and orthopedic surgeon protocol preference shifts for early signals of trajectory divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Nursing Breast Pads Market