
 Trach Care Trays Market | 2026-2036
Trach Care Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Trach Care Trays Market Analytics
The gap between premium specialty trays and commodity disposable configurations is expanding as procurement teams split purchasing decisions by clinical risk tier. Medtronic leverages its critical care portfolio to anchor high-acuity hospital contracts across North America. Smiths Group competes through airway management specialization, while Teleflex Incorporated extends its interventional platform into bundled tray solutions.
Trach care trays are sterile procedure kits containing suction catheters, inner cannulas, gauze, and cleaning supplies assembled to support peristomal maintenance and airway clearance in tracheostomy patients. Most configurations employ gamma-irradiated polypropylene components sealed in Tyvek-backed pouches to maintain sterility through shelf life. Disposable plastic trays dominate hospital procurement due to infection control protocols, though silicone and biodegradable alternatives are gaining traction in European sustainability-focused tenders. Home care segments show faster volume acceleration as post-acute discharge protocols lengthen, while sterile individual packs command margin premiums over bulk configurations in emergency services.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product registration timelines and clinical evidence thresholds for tray manufacturers. ISO 13485 quality management systems and EN 556 sterilization validation standards further constrain supplier qualification in regulated markets. Stakeholders must monitor evolving reimbursement codes for home-based tracheostomy care and anticipate how sustainability mandates will alter material specifications before the next procurement cycle.
Market Dynamics
EU MDR sterilization documentation requirements are forcing tray manufacturers to reconfigure supply chains around validated gamma-irradiation facilities and Tyvek-backed pouch specifications.
Growth Catalysts
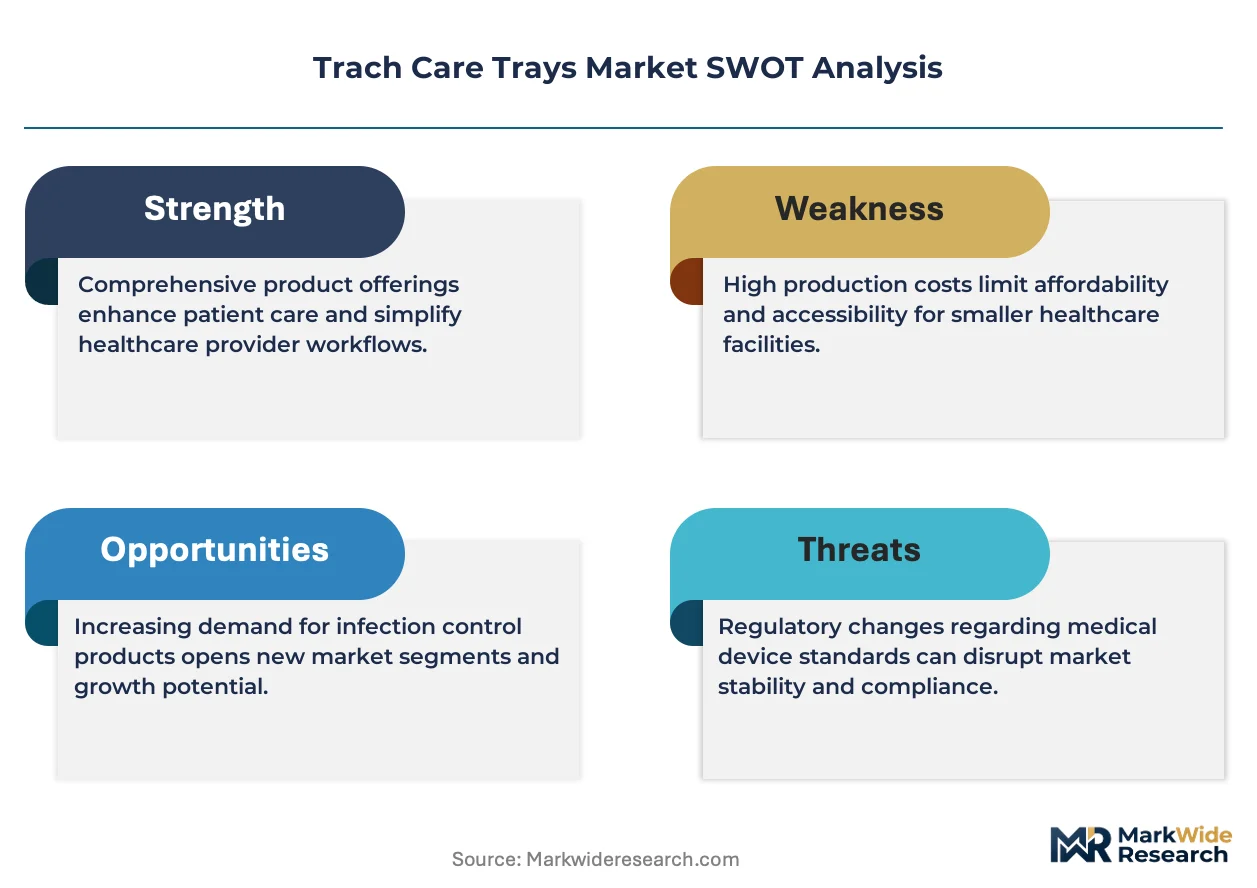
- EU MDR Technical Documentation:Stricter clinical evidence thresholds for sterile procedure kits are consolidating procurement toward pre-qualified suppliers with ISO 13485 certification.
- Post-Acute Discharge Protocols:Extended home care mandates in tertiary care systems are expanding recurring consumption of individual sterile packs outside hospital settings.
- Gamma-Irradiated Polypropylene:Shelf-stable sterilization technology is enabling just-in-time inventory models that reduce waste in high-turnover critical care units.
Market Restraints
- Gamma-Irradiation Facility Concentration:Validated sterilization capacity clusters in Germany and the United States, creating geographic supply vulnerability for distant markets.
- Tyvek Raw Material Dependency:DuPont's control over medical-grade spunbonded olefin supply exposes tray manufacturers to input cost volatility and allocation constraints.
- Biodegradable Alternative Performance Gap:European sustainability-focused tenders face technical limitations as PLA-based trays fail to match polypropylene's moisture barrier properties through shelf life.
Strategic Opportunities
- Japan's Aging Critical Care Infrastructure:Underpenetrated home tracheostomy segments present volume acceleration potential as post-acute protocols lengthen.
- Silicone Component Integration:Reusable inner cannula technology converging with disposable tray formats creates premium positioning in German sustainability tenders.
- CMS Home-Based Reimbursement Expansion:Evolving reimbursement codes for tracheostomy care in United States Medicare are unlocking new channel economics for sterile individual packs.
Industry Challenges
- ISO 13485 Auditor Scarcity:Qualified quality management system assessors face backlog delays extending supplier qualification timelines by 8-14 months.
- FDA 510(k) Clinical Evidence Requirements:Tray configuration modifications trigger substantial equivalence review cycles that compress product refresh cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trach Care Trays Market |
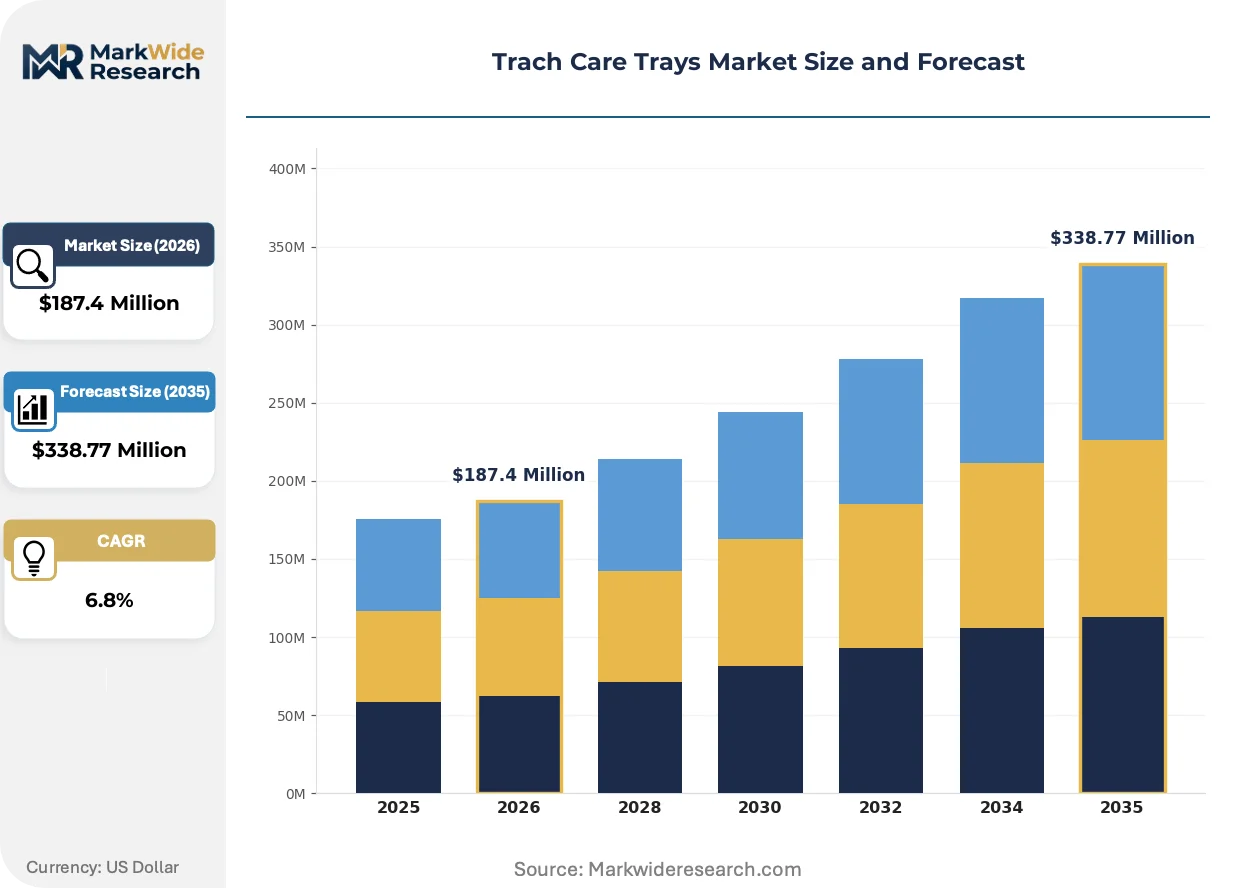
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Trays, Specialty Trays, Custom Trays, Disposable Trays Material: Plastic, Stainless Steel, Biodegradable, Silicone End User: Hospitals, Home Care, Emergency Services, Clinics Packaging Type: Sterile Packs, Bulk Packs, Individual Packs, Combo Packs |
| Companies Covered | Medtronic, Smiths Group, Teleflex Incorporated, TRACOE Medical GmbH, Fisher & Paykel Healthcare, Cook Group, ConvaTec Group, Boston Medical Products, Pulmodyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trach Care Trays Market Evolving Landscape
Sterile kit assembly is migrating from manual packaging lines toward automated vision-guided systems that reduce particulate contamination risk while compressing lot release timelines.
Machine vision inspection is automating defect detection in Tyvek pouch sealing operations, with tertiary care hospital suppliers adopting inline verification to preempt FDA Form 483 observations. The technology compresses quality assurance headcount requirements while tightening sterility assurance level documentation.
EU MDR Annex I general safety and performance requirements are mandating updated clinical evaluation reports for all sterile procedure kits, with notified bodies in Germany and Ireland extending review timelines. Tray manufacturers are responding by pre-submission engagement with BSI and TÜV SÜD to de-risk registration pathways.
Hospital procurement teams are consolidating supplier panels around vendors offering bundled airway management portfolios, displacing standalone tray purchasing. Group purchasing organizations in the United States are steering contracts toward critical care platform suppliers, compressing margins for single-category manufacturers.
Trach Care Trays Market Segmentation
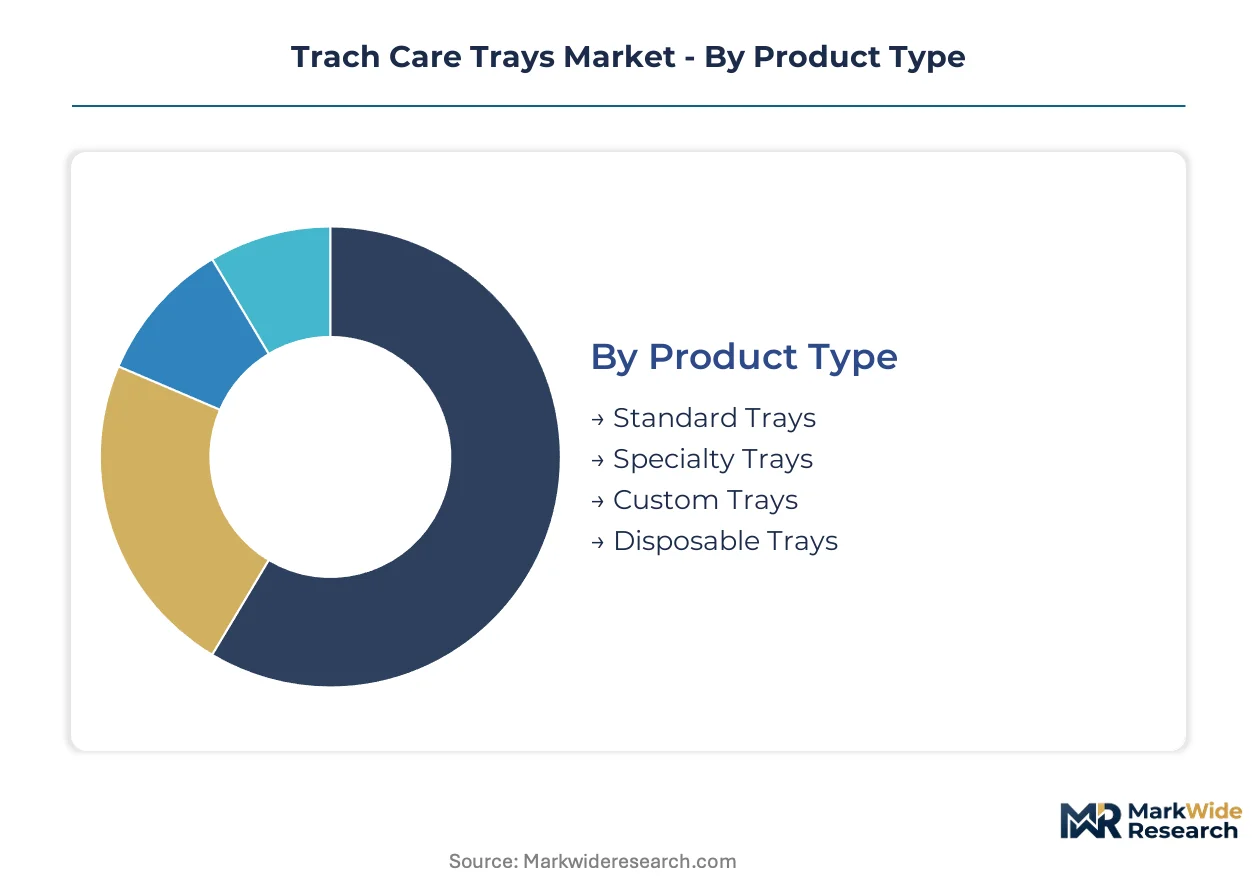
Tray configuration decisions cascade through sterilization validation, inventory economics, and clinical workflow integration. Procurement teams segment purchases across risk tiers, with high-acuity settings demanding validated sterile packs while cost-sensitive channels absorb bulk configurations.
Product Type:
Upgrade cycles differentiate between commodity replacement and protocol-driven standardization mandates in tertiary care systems.
- Standard Trays:Pre-configured kits containing suction catheters, inner cannulas, gauze, and cleaning supplies in gamma-irradiated polypropylene. Demand concentrates in United States tertiary care hospitals where Joint Commission audit protocols enforce consistent airway management documentation.
- Specialty Trays:Procedure-specific assemblies incorporating silicone inner cannulas or pediatric-calibrated components for complex airway cases. German university hospitals drive adoption as EU MDR technical documentation requirements favor pre-validated specialty configurations over in-house assembly.
- Custom Trays:Hospital-specific configurations assembled through GPO-directed contracts with modified component ratios.
- Disposable Trays:Single-use polypropylene kits dominating infection-control-focused procurement in Japan's aging critical care infrastructure.
Volume placements concentrate in Standard Trays; the faster expansion belongs to Specialty Trays.
Material:
Material selection trades barrier performance against sustainability mandates and reprocessing economics across end-use settings.
- Plastic:Gamma-irradiated polypropylene dominates shelf-stable sterilization applications with Tyvek-backed pouch compatibility. United States hospital procurement favors plastic for high-turnover critical care units where just-in-time inventory models reduce waste.
- Biodegradable:PLA-based alternatives targeting European sustainability-focused tenders. Technical limitations in moisture barrier properties through shelf life constrain adoption despite regulatory pressure from EU Green Deal procurement guidelines.
- Stainless Steel:Reusable tray chassis for institutional sterilization departments in German acute care systems.
- Silicone:Reusable inner cannula components converging with disposable tray formats for premium positioning.
Plastic captures the dominant placement share; biodegradable alternatives are climbing the fastest as tender specifications harden.
End User:
Channel economics diverge between capital-intensive hospital contracts and distributed home care consumption patterns.
- Hospitals:Tertiary care systems with established critical care infrastructure sustain recurring consumption through standardized airway management protocols. United States academic medical centers anchor volume through bundled critical care platform contracts.
- Home Care:Post-acute discharge protocols in Japan and the United States lengthen care timelines outside institutional settings. CMS reimbursement code evolution for home-based tracheostomy care is unlocking new channel economics for sterile individual packs.
- Emergency Services:Mobile units requiring compact sterile configurations for field airway management.
- Clinics:Ambulatory settings with lower throughput favoring bulk pack economics over sterile individual units.
Hospitals retain the volume base; home care is gaining share fastest as post-acute protocols extend.
Packaging Type:
Packaging configuration directly determines sterilization validation pathways and inventory carrying costs.
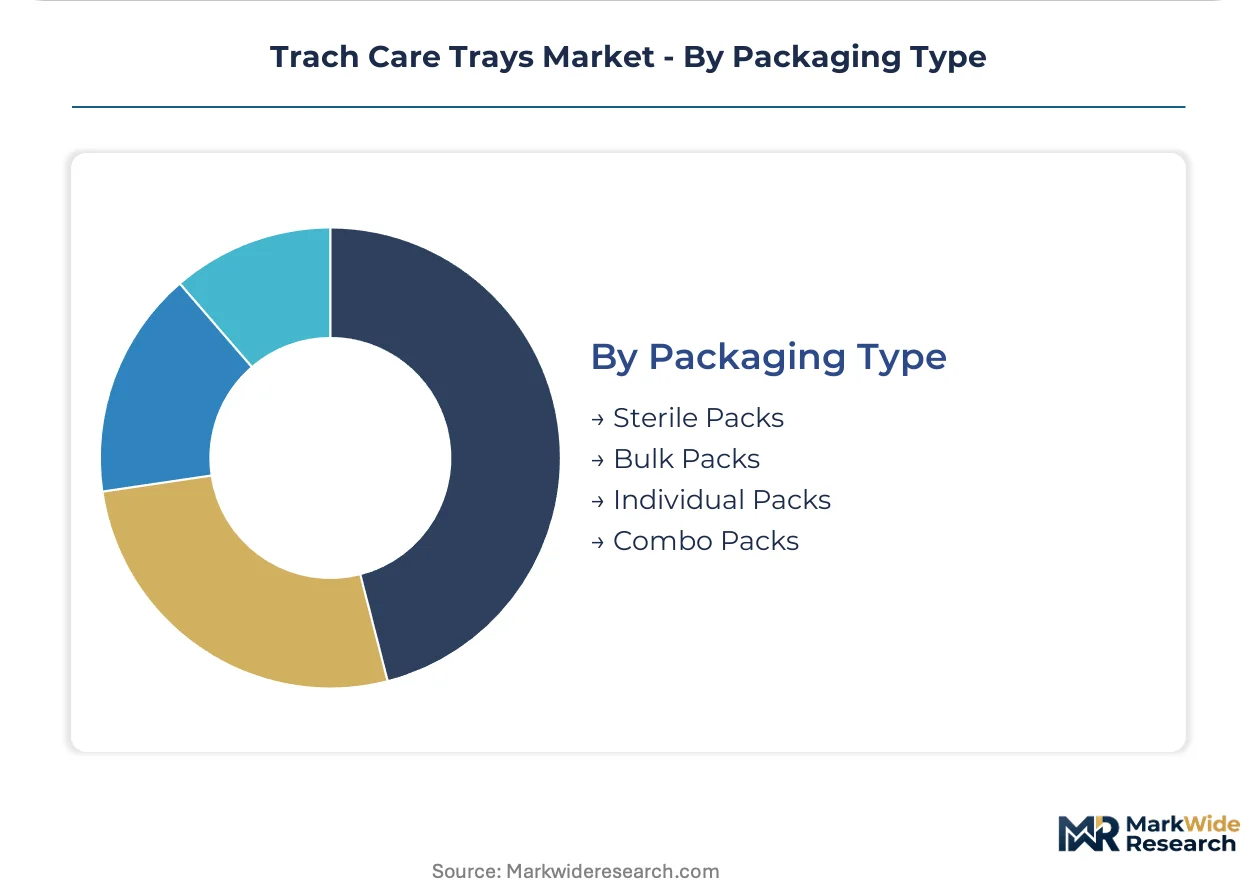
- Sterile Packs:Tyvek-backed pouches with gamma-irradiated contents meeting FDA 510(k) and EU MDR documentation requirements. German and United States tertiary care procurement mandates sterile packs for all invasive airway procedures.
- Individual Packs:Unit-dose configurations supporting just-in-time dispensing in high-turnover critical care units. Emergency services in the United States command margin premiums for sterile individual packs over bulk alternatives.
- Bulk Packs:Multi-unit configurations reducing per-procedure cost in non-sterile cleaning applications.
- Combo Packs:Hybrid configurations bundling sterile and non-sterile components for integrated airway management workflows.
Sterile Packs dominate placement volume; Individual Packs show the steepest expansion trajectory as inventory models tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American critical care supply chains through Medtronic's operational footprint, while gamma-irradiation clusters in Germany and Japan concentrate sterilization capacity for airway management kits.
United States
Academic medical centers in Boston and Houston drive standardized airway protocol adoption through Joint Commission audit requirements. FDA 510(k) clearance pathways shape product registration timelines for tray configurations. Gamma-irradiation facilities in Illinois and California serve as sterilization hubs for domestic distribution networks.
Germany
University hospitals in Munich and Heidelberg favor pre-validated specialty tray configurations over in-house assembly. EU MDR technical documentation obligations extend review timelines through notified bodies in Berlin and Dublin. Tyvek-backed pouch manufacturing concentrates in the Rhine-Ruhr industrial corridor.
Japan
Tokyo's aging critical care infrastructure sustains recurring consumption of disposable polypropylene trays through extended post-acute discharge protocols. PMDA quality management requirements align with ISO 13485 standards for sterile procedure kits. Osaka-based distributors manage just-in-time inventory for tertiary care networks.
United Kingdom
NHS procurement frameworks in London and Manchester consolidate supplier panels around bundled airway management portfolios. MHRA post-Brexit regulatory alignment maintains EU MDR documentation standards for sterilization validation. Cambridge medical technology clusters influence specialty tray design specifications.
India
Corporate hospital chains in Delhi-NCR and Mumbai expand critical care bed capacity requiring standardized tracheostomy protocols. CDSCO medical device registration rules are tightening clinical evidence requirements for imported sterile kits. Hyderabad's pharmaceutical manufacturing corridor is attracting gamma-irradiation facility investments.
Trach Care Trays Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sterilization validation and GPO contract access. The vendor base stratifies between critical care platform suppliers with bundled portfolios and standalone tray manufacturers serving cost-sensitive channels. Three archetypes dominate: diversified medical technology conglomerates, airway management specialists, and regional disposable kit fabricators. M&A activity targets sterilization facility access, while strategic partnerships secure Tyvek supply allocations.
Within the diversified conglomerate tier, Medtronic and Smiths Group occupy positions anchored by critical care platform breadth. Teleflex Incorporated exemplifies the interventional specialist archetype extending into bundled solutions. TRACOE Medical GmbH represents German-engineered airway specialization within European procurement frameworks.
| Leading Market Players |
|---|
| Medtronic |
| Smiths Group |
| Teleflex Incorporated |
| TRACOE Medical GmbH |
| Fisher & Paykel Healthcare |
| Cook Group |
| ConvaTec Group |
| Boston Medical Products |
| Pulmodyne |
| Others |
Value Network & Pricing Analysis
Polypropylene resin indices and Tyvek spunbonded olefin pricing cascades through tray manufacturing tiers, compressing margins for commodity disposable configurations while validated sterile packs retain pricing power through EU MDR certification premiums. Procurement teams in German university hospitals and United States academic medical centers absorb cost pass-throughs more readily than cost-sensitive clinic channels.
Pricing Analysis
Throughput-linked value pricing anchors specialty tray premiums to Joint Commission audit compliance and infection control outcomes in tertiary care settings. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated specialty configurations from commodity disposable kits and unbranded bulk alternatives. Pricing pressure stems from group purchasing organization consolidation steering contracts toward bundled critical care platforms. Home care segments exhibit highest price sensitivity as CMS reimbursement code evolution lags cost inflation.
Supply Chain Analysis
ISO 13485 certification gates supplier qualification, extending lead times for new entrants while consolidating procurement toward pre-validated manufacturers in Germany, the United States, and Japan. Gamma-irradiated polypropylene, Tyvek-backed pouches, and silicone inner cannulas constitute critical input dependencies. Single-source vulnerability concentrates in DuPont's medical-grade spunbonded olefin supply. Distribution runs through hospital system contracts, GPO-administered panels, and regional distributors serving post-acute channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation obligations and ISO 13485 auditor scarcity are forcing sub-scale manufacturers toward exit, creating consolidation opportunities for qualified incumbents.
For Market Incumbents: Hedge sterilization capacity exposure by securing dual-source gamma-irradiation relationships in Illinois and Germany. Deepen backward integration into Tyvek pouch converting to reduce DuPont allocation dependency. Defend GPO contract access through bundled airway management portfolio expansion rather than standalone tray price competition. For New Entrants and Emerging Players: Launch via direct-to-home-care distribution models targeting Japan's underpenetrated post-acute segments where PMDA quality requirements align with ISO standards. Bypass hospital procurement consolidation by specializing in silicone-reusable hybrid formats for German sustainability tenders. Prioritize CMS reimbursement code navigation over sterile pack margin capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap tray fabricators with captive sterilization relationships in the United States Midwest. Long-term viability hinges on EU MDR technical documentation capabilities and GPO contract tenure. Watch ISO 13485 auditor queue lengths as inflection signal for supplier qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Pre-submission engagement with BSI and TÜV SÜD de-risks notified body review timelines for sterile kits. |
| Gamma-Irradiation Facility Partnership | Dual-source sterilization capacity in Germany and Illinois reduces geographic supply vulnerability. |
| Silicone Component Integration | Reusable inner cannula technology captures premium positioning in European sustainability tenders. |
| Home Care Channel Development | CMS reimbursement code evolution unlocks new economics for sterile individual packs outside hospitals. |
| Automated Vision-Guided Assembly | Machine vision inspection compresses lot release timelines while preempting FDA Form 483 observations. |
Research Methodology
Independent corroboration across hospital procurement managers, GPO contracts specialists, biomedical engineers, and sterile processing department heads underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital supply chain procurement records. Bottom-up volume estimates triangulate against top-down spending analysis across the analysis window.
Comparable-period anchoring to historical surgical volume trends and critical care bed capacity expansion frames the projection horizon. Segmentation modeling spans product type, material specification, end-user channel, and packaging configuration dimensions. CAGRs derive from procedure volume elasticity to aging demographics and post-acute protocol extension. Forecast inputs incorporate gamma-irradiation facility capacity utilization and notified body review timeline trends.
Regulatory submission delays, sterilization facility outages, and reimbursement code revisions are the dominant revision risks. Forecasts reflect assumptions on EU MDR implementation consistency and CMS policy continuity. A model refresh is warranted upon material change in notified body capacity or gamma-irradiation supply allocation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Amniotic Products Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Filter Needles Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Global Absorbent Dressings Market