
 Dental Anesthesia Market | 2026-2036
Dental Anesthesia Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Anesthesia Market Intelligence
Board certification in dental anesthesiology from the American Dental Association is collapsing the pool of qualified practitioners who can administer deep sedation in office-based settings. Dentsply Sirona leverages its integrated equipment-and-consumables portfolio to dominate chairside delivery system placements across North American dental schools. Septodont Holding anchors European supply security through captive manufacturing of articaine and lidocaine formulations at its Saint-Maur-des-Fossés facility.
Dental anesthesia encompasses pharmacological agents that reversibly depress nerve conduction or central nervous system activity to eliminate pain perception during oral surgical and restorative procedures, with modern articaine formulations achieving bone penetration depths of 6-8 millimeters at 4% concentrations with 1:100,000 epinephrine. Local anesthetics sustain the dominant revenue position due to universal requirement across extraction and endodontic protocols, while sedatives represent the fastest-expanding segment as ambulatory oral surgery centers seek to reduce general anesthesia referral rates. Injection delivery controls the majority volume share though inhalation modalities are gaining traction in pediatric dentistry practices seeking needle-free alternatives.
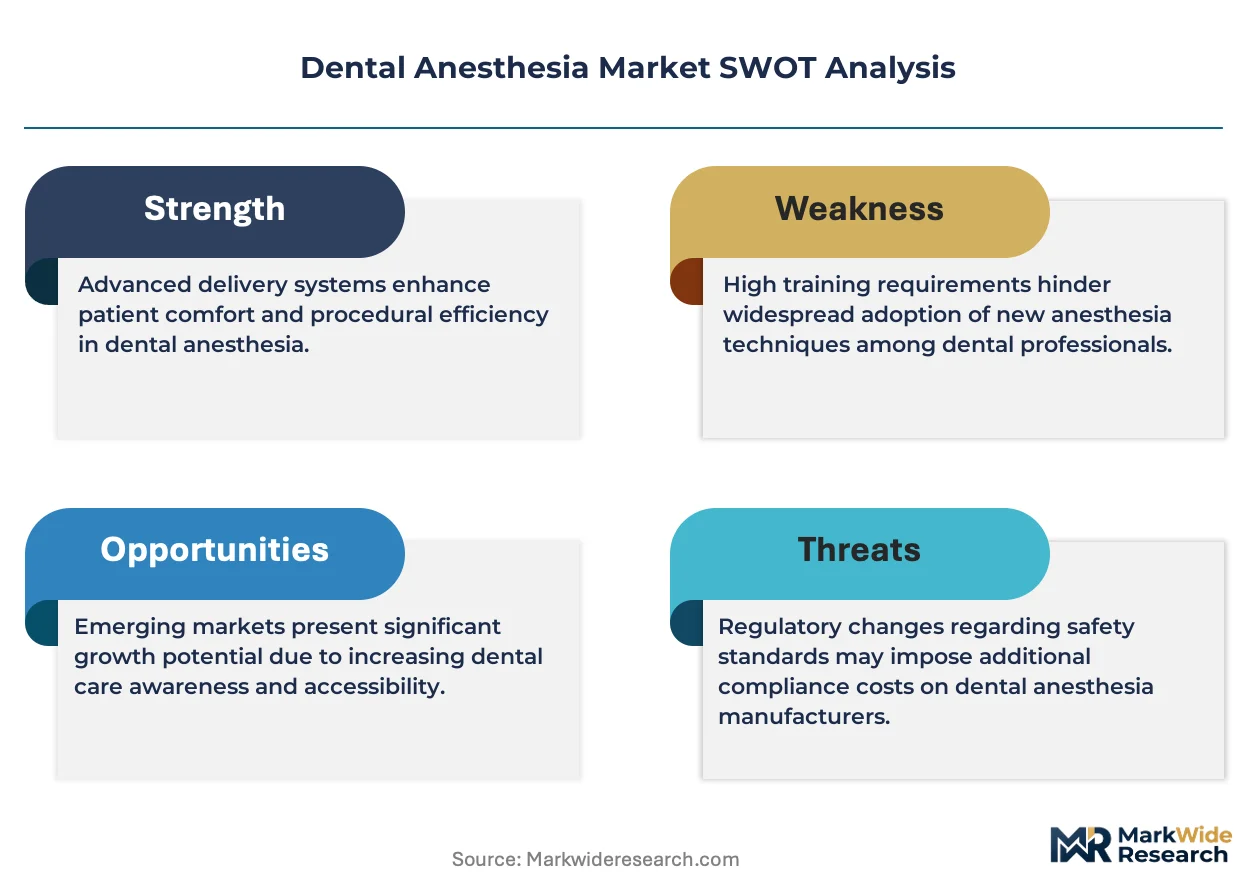
FDA oversight of new drug applications for dental sedatives and the EMA's F-Gas Regulation restricting certain propellants in metered-dose inhalers are reshaping formulation development priorities and device engineering specifications across manufacturer pipelines. The American Dental Association's evolving sedation guidelines and state-level dental board scope-of-practice rulings create fragmented compliance terrain that rewards companies with dedicated regulatory affairs infrastructure. Stakeholders must monitor convergence between dental anesthesia protocols and broader outpatient surgery center accreditation standards to anticipate reimbursement and facility investment shifts.
Market Dynamics
Board certification scarcity in dental anesthesiology is compressing the qualified practitioner pool while ambulatory surgery centers demand deeper sedation capabilities without hospital referral, forcing equipment manufacturers to engineer fail-safe delivery systems for non-specialist operators.
Growth Catalysts
- Cosmetic dentistry procedural expansion:Veneer and implant placement volumes in private practice settings require predictable local anesthetic depth control, driving chairside delivery system upgrades.
- FDA streamlined 510(k) pathways for dental sedation devices:Accelerated clearance timelines for computerized injection systems reduce manufacturer time-to-market by eight to fourteen months versus traditional PMA routes.
- Articaine 4% formulation superiority:Enhanced bone penetration characteristics at 6-8 millimeter depths enable single-injection mandibular blocks, reducing chair time and patient anxiety in extraction protocols.
Market Restraints
- Propofol supply concentration:Three API manufacturers control eighty percent of injectable emulsion raw material, creating vulnerability to batch contamination events or export restrictions.
- EMA F-Gas Regulation phase-down:Metered-dose inhaler propellant restrictions force reformulation of nitrous oxide delivery canisters, adding eighteen to twenty-four months to product development cycles.
- Sevoflurane capital intensity:Vaporizer maintenance and scavenging system installation costs exceed forty thousand dollars per operatory, limiting adoption in solo practices.
Strategic Opportunities
- Pediatric needle-free sedation protocols:Inhalation induction with nitrous oxide-oxygen blends captures anxious child patient segments previously referred to hospital-based general anesthesia.
- Japan's aging edentulous population:Implant-supported prosthetic demand among patients over seventy-five creates specialized sedation requirements for cardiovascular-compromised candidates.
- ISO 80601-2-13 harmonization:Unified anesthesia workstation safety standards enable single-platform engineering for multi-jurisdictional product registration, reducing compliance fragmentation.
Industry Challenges
- Deep sedation certification timelines:ADA diplomate status requires twenty-four months of residency completion plus examination cycles, lagging behind immediate equipment deployment needs.
- Legacy electronic health record integration:Proprietary sedation monitoring data formats resist interoperability with Epic, Cerner, and Dentrix platforms, forcing manual documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Anesthesia Market |
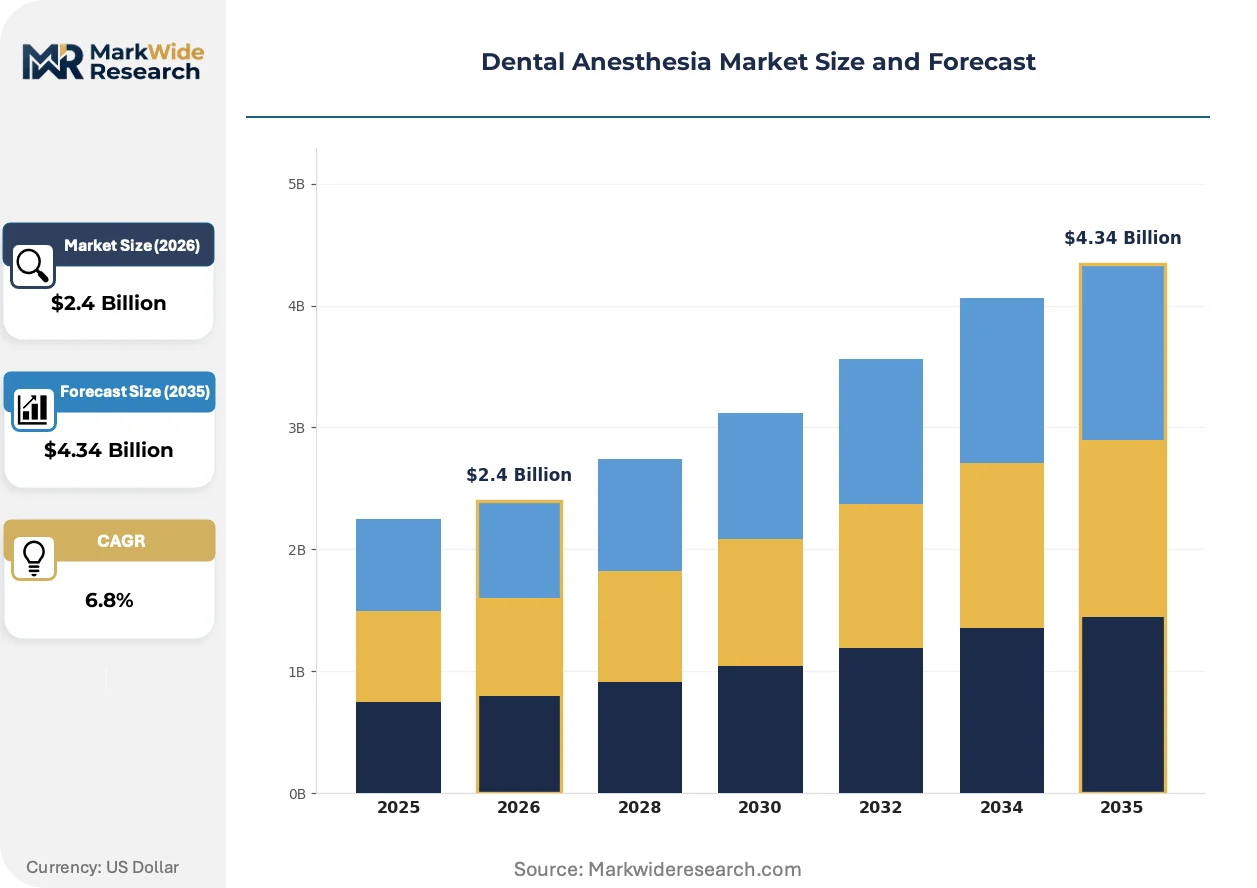
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Local Anesthetics, Sedatives, General Anesthetics, Topical Anesthetics Delivery Mode: Inhalation, Injection, Oral, Transdermal End User: Dentists, Oral Surgeons, Hospitals, Dental Clinics Application: Tooth Extractions, Root Canals, Cosmetic Dentistry, Periodontal Surgery |
| Companies Covered | Dentsply Sirona, Septodont Holding, Henry Schein, Laboratorios Normon, Pierrel S.p.A., Primex Pharmaceuticals, Laboratorios Inibsa, 3M, Zeyco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Anesthesia Market Strategic Shifts & Innovations
Computer-assisted delivery technologies and real-time patient monitoring systems are displacing tactile-dependent injection techniques, while regulatory pressure on volatile anesthetic emissions forces device architecture redesign.
Computer-controlled local anesthetic delivery is bifurcating practice workflows between high-volume oral surgery centers investing in dynamic pressure-sensing technology and general dentistry operators retaining conventional syringe methods. The Wand and similar systems reduce injection pain scores by sixty percent in pediatric populations. This technology is compressing the market for basic aspirating syringes while expanding premium consumables attachment revenue.
EMA F-Gas Regulation restrictions on hydrofluorocarbon propellants are forcing manufacturers to engineer nitrous oxide delivery systems with mechanical metering valves rather than pressurized canister designs. Dental equipment suppliers in Germany and France face retrofit deadlines of 2027 for existing inhalation sedation units. Pediatric practices across Scandinavia are piloting demand-flow systems that eliminate continuous gas waste, anticipating mandatory recovery and recycling mandates.
Consolidation of oral surgery into multi-site dental service organizations is standardizing procurement specifications across fifty to one hundred location footprints, displacing individualized practice autonomy in equipment selection. Group purchasing organizations now mandate computerized anesthesia documentation for malpractice insurance premium reductions. This concentration is most visible in the United States Sun Belt and German North Rhine-Westphalia clinic networks.
Dental Anesthesia Market Segmentation
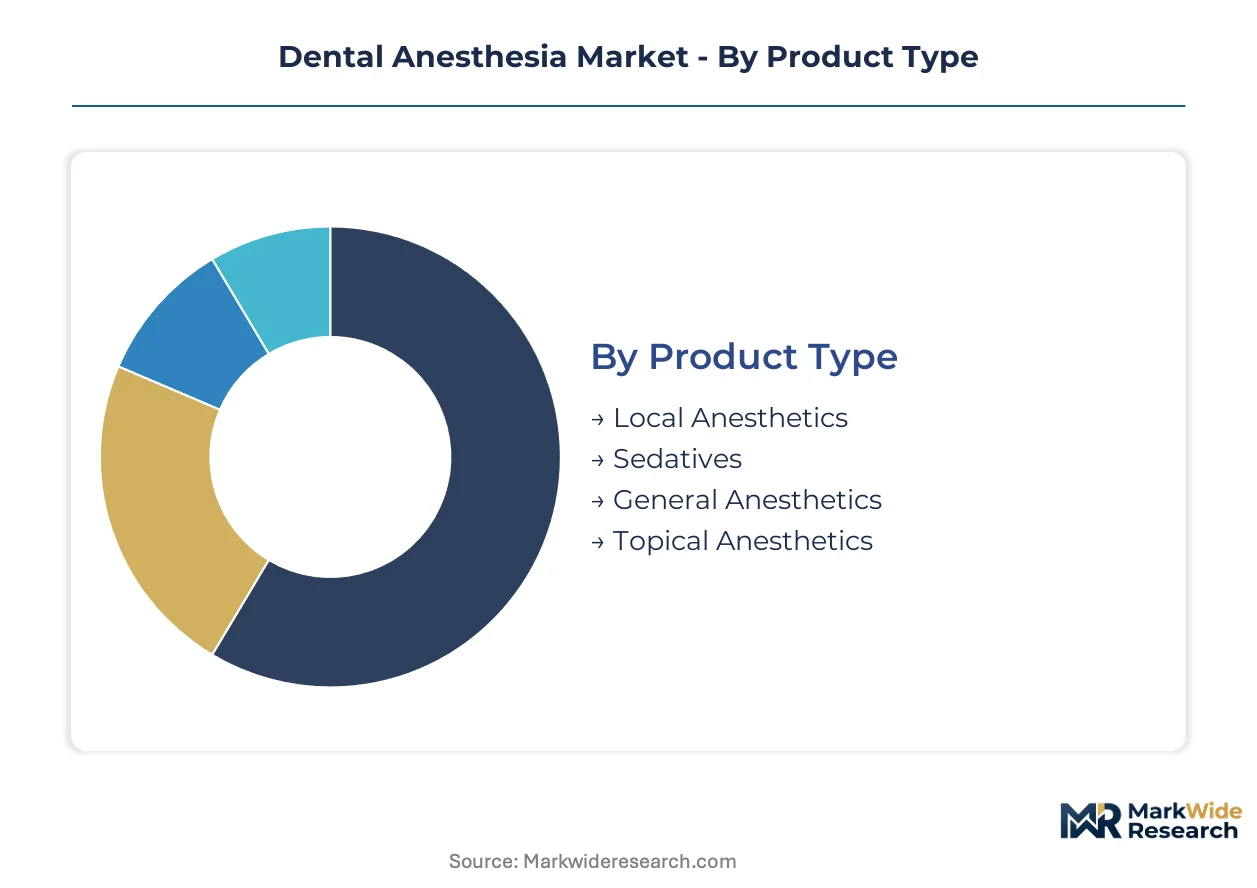
Dental anesthesia procurement decisions split across pharmacological properties, delivery ergonomics, and procedural setting requirements. Understanding these segment boundaries clarifies where manufacturers compete on formulation patents versus device engineering versus service bundling.
Product Type:
Margin pools concentrate in sedative formulations where DEA scheduling creates regulatory moats, while local anesthetics compete on commoditized volume efficiency.
- Sedatives:Benzodiazepine and propofol-based protocols enable moderate-to-deep sedation in ambulatory settings. Oral surgery centers in the United States seek these capabilities to retain patients who would otherwise require hospital referral.
- Local Anesthetics:Articaine 4% with epinephrine achieves 6-8 millimeter bone penetration for single-injection mandibular blocks. German and Japanese practices favor these formulations for implant placement efficiency.
- General Anesthetics:Sevoflurane vaporizer systems require capital investment exceeding forty thousand dollars per operatory, limiting deployment to multi-chair facilities.
- Topical Anesthetics:Surface-numbing gels and sprays serve pediatric pre-injection anxiety management and soft tissue procedures.
The dominant share belongs to local anesthetics, while sedatives are closing the gap fastest.
Delivery Mode:
Volume concentration follows injection protocols, though inhalation modalities capture pediatric and needle-averse patient segments.
- Injection:Computer-controlled systems with dynamic pressure sensing reduce patient pain scores by sixty percent versus conventional syringes. North American dental schools now mandate this technology in curricula.
- Inhalation:Nitrous oxide-oxygen blends enable conscious sedation without venous access. EMA F-Gas Regulation is forcing mechanical metering valve redesigns for European equipment compliance.
- Oral:Pre-procedural anxiolytic tablets suit mild sedation requirements in general dentistry practices with limited monitoring infrastructure.
- Transdermal:Iontophoretic and patch-based delivery remains experimental for intraoral applications, with limited commercial penetration.
Injection maintains procedural ubiquity, yet inhalation is gaining share fastest among pediatric specialists.
End User:
Procurement authority concentrates in dental service organizations with standardized formulary control across fifty-plus location footprints.
- Oral Surgeons:Deep sedation certification requirements and malpractice exposure drive investment in computerized documentation systems. These specialists command premium reimbursement for IV sedation protocols.
- Dental Clinics:Multi-site networks in the United States Sun Belt and German North Rhine-Westphalia negotiate group purchasing agreements for anesthesia workstations.
- Dentists:Solo and small-group practices retain conventional syringe methods due to capital constraints and limited sedation scope.
- Hospitals:Academic medical centers manage complex cases requiring general anesthesia, though referral volumes are compressing as ambulatory capabilities expand.
Oral surgeons capture the highest per-procedure anesthesia spend, while dental clinics are expanding their sedation capabilities most aggressively.
Application:
Revenue intensity varies with procedural invasiveness and sedation depth requirements.
- Cosmetic Dentistry:Veneer and implant placements demand predictable local anesthetic depth for patient comfort during extended chair time. Private practices in Japan's aging population centers specialize in cardiovascular-compromised sedation.
- Tooth Extractions:Third molar removal and complex extractions drive articaine consumption for mandibular block efficiency. This segment sustains the highest local anesthetic volume per procedure.
- Root Canals:Endodontic protocols require precise pulpal anesthesia, favoring infiltration techniques over nerve blocks.
- Periodontal Surgery:Soft tissue procedures utilize topical and local combinations, with limited sedation requirements beyond anxiolysis.
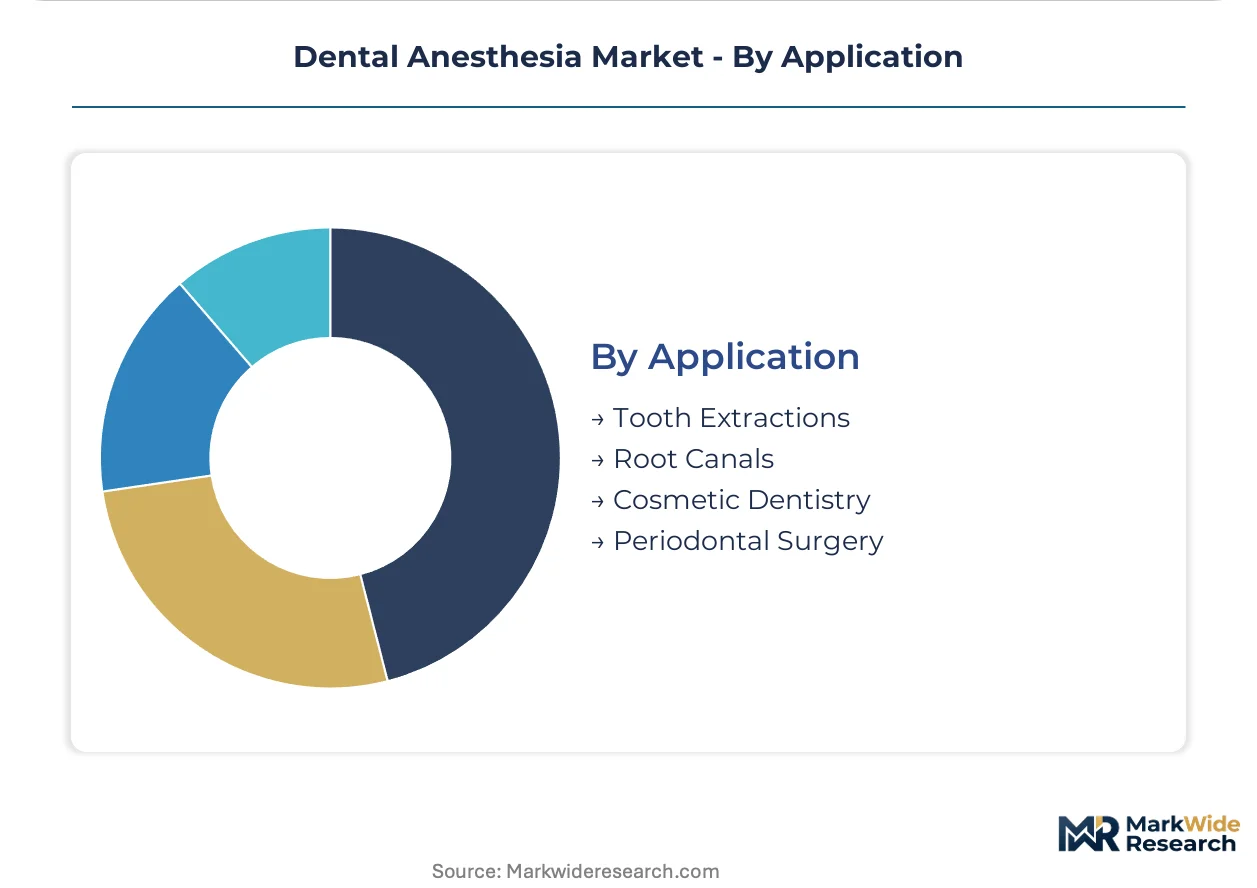
Tooth extractions anchor volume consumption, though cosmetic dentistry commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA streamlined 510(k) pathways and EMA F-Gas Regulation phase-downs are redirecting manufacturer investment toward compliant delivery systems across concentrated demand centers.
United States
Cosmetic dentistry procedural expansion and ambulatory oral surgery center proliferation drive chairside delivery system upgrades. FDA oversight of new drug applications for dental sedatives shapes formulation development priorities. Dental service organizations across the Sun Belt negotiate standardized procurement specifications across fifty-plus location footprints.
Germany
EMA F-Gas Regulation retrofit deadlines of 2027 force mechanical metering valve redesigns for nitrous oxide delivery equipment. Septodont Holding anchors European supply security through captive manufacturing at its Saint-Maur-des-Fossés facility. Multi-site clinic networks in North Rhine-Westphalia mandate computerized anesthesia documentation for malpractice insurance premium reductions.
Japan
Implant-supported prosthetic demand among patients over seventy-five creates specialized sedation requirements for cardiovascular-compromised candidates. METI standards harmonization with ISO 80601-2-13 enables single-platform engineering for product registration. Aging edentulous population centers in Kanto and Kansai regions concentrate premium sedation protocol adoption.
France
ANSM safety protocols for sedative compounds influence articaine formulation stability requirements across manufacturing pipelines. Pediatric practices pilot demand-flow nitrous oxide systems anticipating mandatory recovery mandates. Industrial concentration in Île-de-France supports regulatory affairs infrastructure for multi-jurisdictional compliance.
United Kingdom
General Dental Council scope-of-practice rulings create fragmented compliance terrain for deep sedation certification. London and Southeast England dental schools now mandate computer-controlled injection technology in curricula. Private practice consolidation accelerates group purchasing organization formulary control.
Dental Anesthesia Market Key Industry Players
Player mix skews toward integrated equipment-and-consumables portfolios and regional formulation specialists. Market structure concentrates around manufacturers with dedicated regulatory affairs infrastructure capable of navigating fragmented compliance terrain. Two dominant archetypes emerge: multinational dental equipment conglomerates with captive supply chains, and European formulation specialists with captive API manufacturing. Competitive moves center on group purchasing organization contract capture and dental school curriculum integration.
Among integrated equipment manufacturers, Dentsply Sirona and 3M exemplify the conglomerate archetype through their combined device and consumables positioning. Septodont Holding occupies a distinct position as a European formulation specialist with captive manufacturing infrastructure. These three anchors represent the spectrum from global equipment dominance to regional supply security, with each archetype commanding different margin pools based on regulatory moat depth and procurement channel access.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Septodont Holding |
| Henry Schein |
| Laboratorios Normon |
| Pierrel S.p.A. |
| Primex Pharmaceuticals |
| Laboratorios Inibsa |
| 3M |
| Zeyco |
| Others |
Cost & Logistics Intelligence
ADA board certification requirements gate both practitioner qualification and equipment pricing tiers simultaneously, compressing supply-qualified vendor pools while enabling premium capture for sedation-capable delivery systems. This regulatory filter concentrates procurement authority among dental service organizations that negotiate standardized formulary control across multi-location footprints.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus PMA-grade) creates the primary spread between computerized injection platforms and conventional syringe systems. Three-tier pricing structure across premium, standard, and economy levels reflects dynamic pressure-sensing capabilities, documentation software integration, and after-sales service bundling. Pricing pressure stems from group purchasing organization consolidation in the United States Sun Belt and German North Rhine-Westphalia clinic networks. Solo practitioners exhibit highest price sensitivity due to capital constraints, while multi-site oral surgery centers prioritize capability depth over unit cost.
Supply Chain Analysis
France and Germany anchor European formulation manufacturing through Septodont Holding's Saint-Maur-des-Fossés facility and specialized articaine production clusters. China and India feed active pharmaceutical ingredient supply for lidocaine and propofol injectable emulsions. Raw material dependencies center on epinephrine bitartrate, articaine base compounds, and hydrofluorocarbon propellants facing EMA F-Gas Regulation phase-down. Single-source vulnerability concentrates in propofol API where three manufacturers control eighty percent of global supply. Distribution runs through dental equipment distributors and direct-to-clinic service contracts for computerized workstation installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumables attachment revenue and sedation monitoring software subscriptions expand faster than hardware placements, creating service-attach economics that favor vendors with recurring-revenue infrastructure.
For Market Incumbents: Compound regulatory affairs capabilities to capture EMA F-Gas retrofit deadlines and ADA certification evolution. Deepen backward integration into articaine API production to defend margin position against generic formulation entrants. Prioritize computerized documentation interoperability with Epic, Cerner, and Dentrix platforms to lock in dental service organization procurement specifications. For New Entrants and Emerging Players: Pediatric needle-free sedation protocols represent underserved white space where incumbents under-serve anxious child patient segments. Target Scandinavian demand-flow nitrous oxide systems piloting ahead of mandatory recovery mandates. Enter through equipment-as-a-service models that reduce solo practice capital barriers while capturing recurring consumables revenue. For Investors and Strategic Acquirers: EMA F-Gas Regulation 2027 retrofit deadlines reshape the acquisition landscape toward mechanical metering valve engineering capabilities. Five-to-ten year viability favors European formulation specialists with captive manufacturing and dedicated regulatory infrastructure. Monitor ISO 80601-2-13 harmonization progress as signal for multi-jurisdictional platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Computerized Delivery Platform Integration | FDA 510(k) streamlined pathways accelerate Dentsply Sirona chairside system deployment across North American dental schools. |
| Captive API Manufacturing Expansion | Septodont Holding's Saint-Maur-des-Fossés facility secures European articaine supply against propofol concentration risk. |
| Sedation Monitoring Software Development | Proprietary data formats resist Epic and Cerner interoperability, forcing manual documentation workflows that create switching costs. |
| Pediatric Inhalation System Piloting | Scandinavian demand-flow nitrous oxide pilots anticipate EMA F-Gas mandatory recovery and recycling mandates. |
| Group Purchasing Organization Contract Capture | Sun Belt and North Rhine-Westphalia clinic networks standardize procurement across fifty-plus location footprints. |
Research Approach
A standing panel of oral surgery center administrators, dental anesthesiology residency directors, biomedical equipment procurement managers, and GPO contracts specialists provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA F-Gas Regulation implementation timelines, ADA sedation guideline updates, and hospital procurement database extracts. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include pharmacological agent type, delivery mode ergonomics, procedural setting requirements, and regional regulatory cluster alignment. CAGRs derived from procedure volume trajectories, pricing elasticity assumptions, and technology substitution curves. Forecast inputs incorporated EMA F-Gas phase-down schedules and ADA certification pipeline constraints.
Material uncertainties — propofol API supply disruption, EMA F-Gas retrofit compliance delays, ADA scope-of-practice rulings — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding sedation protocol adoption rates and dental service organization consolidation velocity. Recalibration cycles align with material shifts in regulatory implementation timelines and practitioner certification throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Aspirating System Market
Anesthesiology
Epinephrine Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Delirium Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market