
 Nursing Breast Pads Market | 2026-2036
Nursing Breast Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Nursing Breast Pads Market Analytics
Plant-based absorbent core technology is fragmenting traditional polymer-dependent supply chains in nursing breast pad manufacturing. Medela leverages its clinical-grade R&D pipeline to sustain premium positioning across European maternity wards. Lansinoh Laboratories anchors North American retail distribution through pharmacy and big-box channel control. Pigeon Corporation dominates Asian home-care segments with localized sizing and humidity-adapted materials.
Nursing breast pads are absorbent, skin-contact hygiene products engineered with multi-layer constructions—typically a fluid-wicking top sheet, a superabsorbent polymer or cellulose core, and a breathable waterproof backing—to capture breast milk leakage and maintain epidermal integrity during lactation. Disposable variants lead absolute volume due to convenience-driven hospital procurement and travel use cases, while organic cotton reusable segments capture margin pools from eco-conscious direct-to-consumer buyers. Bamboo fiber material grades are expanding fastest as manufacturers respond to chemical-sensitization concerns and landfill-reduction mandates.
FDA biocompatibility standards and EPA disposable product guidelines shape material selection and labeling requirements in the United States, while REACH chemical restrictions in Europe limit certain adhesive and fragrance compounds. China's GB standards and NMPA hygiene product classifications govern import access and domestic manufacturing compliance. Stakeholders must monitor evolving absorbent polymer regulations and channel-specific reimbursement policies to calibrate portfolio mixes between clinical and retail endpoints.
Market Dynamics
Plant-based absorbent core technology is fragmenting polymer-dependent supply chains as manufacturers reformulate around FDA biocompatibility standards and EPA disposable product guidelines. This material transition compresses legacy procurement relationships while opening margin pools for certified organic producers.
Growth Catalysts
- REACH chemical restrictions:European adhesive and fragrance compound limits accelerate R&D investment in bio-based bonding agents. Manufacturers with pre-certified formulations capture shelf space in German and French pharmacy networks.
- Direct-to-consumer platform expansion:Home care channels absorb volume shifts as subscription models bypass traditional retail markup structures. Digital-native brands leverage humidity-adapted material claims to convert eco-conscious buyers.
- Bamboo fiber grade advancement:Cellulose processing improvements reduce production cost gaps versus synthetic superabsorbent polymers. Asian manufacturers with captive bamboo supply integrate forward into finished pad assembly.
Market Restraints
- Superabsorbent polymer price volatility:Petroleum-derived input costs swing with crude oil benchmarks, compressing margins for disposable-variant producers locked into hospital procurement contracts.
- China NMPA hygiene product classification:Import registration timelines extend 18-24 months for foreign manufacturers, creating domestic incumbent protection in the world's largest birth-rate market.
- Reusable cotton pad substitution:Organic cotton laundering infrastructure spreads through European municipal programs, threatening repeat-purchase frequency for single-use segments.
Strategic Opportunities
- Insurance reimbursement policy expansion:United States Medicaid programs in 12 states now classify nursing pads as durable medical equipment, creating institutional procurement channels previously reserved for clinical-grade suppliers.
- Sizing localization for Asian anatomy:Japanese and South Korean market entry requires diameter and contour adjustments that Western incumbents have underinvested in, leaving white space for regional specialists.
- Dual carbon goal alignment:China's MEE landfill-reduction mandates favor compostable backing materials, rewarding manufacturers with certified biodegradability credentials in domestic retail placement.
Industry Challenges
- FDA 510(k) biocompatibility documentation:Skin-contact device classification requires cytotoxicity and sensitization testing protocols that extend product development cycles by 8-14 months for novel material introductions.
- Multi-layer lamination skill scarcity:Fluid-wicking top sheet to waterproof backing integration demands precision coating expertise concentrated in Japanese and German equipment supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nursing Breast Pads Market |
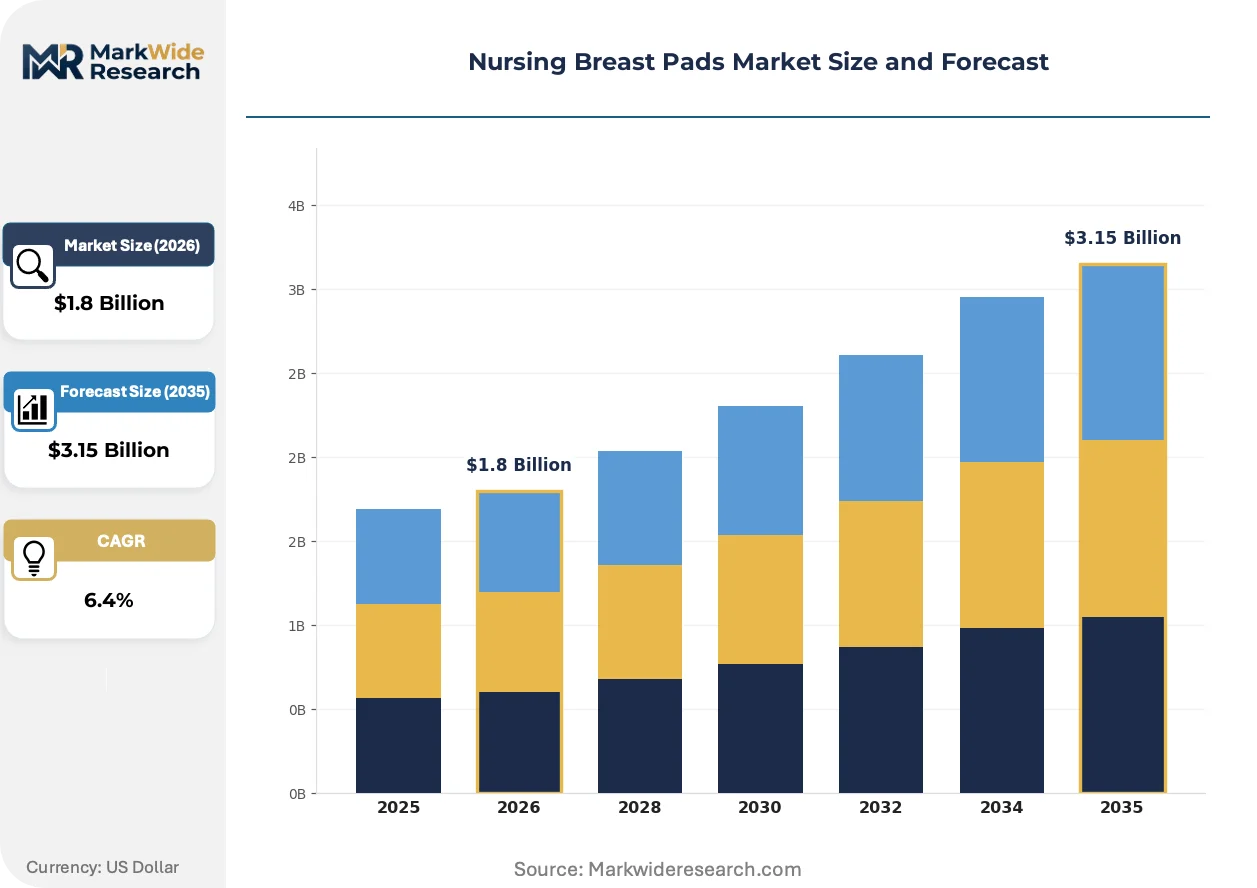
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Organic Cotton, Waterproof Material: Polyethylene, Bamboo Fiber, Cotton, Microfiber Design: Contoured, Flat, Ultra-Thin, Adjustable End User: Hospitals, Maternity Clinics, Home Care, Retail |
| Companies Covered | Medela, Cardinal Health, Lansinoh Laboratories, Ameda, Pigeon Corporation, NUK USA, Bamboobies, LilyPadz, KINDRED BRAVELY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nursing Breast Pads Market Evolving Landscape
Digital manufacturing and regulatory chemistry are converging to compress product development timelines while fragmenting traditional material supply relationships. Three forces dominate this transformation.
Biodegradable superabsorbent polymers derived from modified starch and polylactic acid are virtualizing the functional performance of petroleum-based sodium polyacrylate cores. European maternity ward procurement teams now specify compostability certifications in tender documents, forcing contract manufacturers to dual-source conventional and bio-based inputs. This virtualization is compressing the premium pricing power historically held by synthetic polymer suppliers.
EPA disposable product guidelines are tightening labeling requirements around landfill decomposition timelines and marine biodegradability claims. Manufacturers must now substantiate environmental marketing with third-party ASTM testing, raising compliance costs for mid-tier brands. The United States retail channel bears the heaviest documentation burden as big-box retailers impose supplier sustainability scorecards ahead of federal mandate deadlines.
Subscription-based replenishment models are displacing pharmacy and supermarket stock-up purchasing among millennial and Generation Z lactating consumers. Direct-to-consumer platforms capture recurring revenue through algorithmic sizing recommendations and humidity-adapted seasonal product rotations. This behavioral shift concentrates most visibly in United States coastal metropolitan markets where same-day delivery infrastructure supports just-in-time hygiene product logistics.
Nursing Breast Pads Market Segmentation
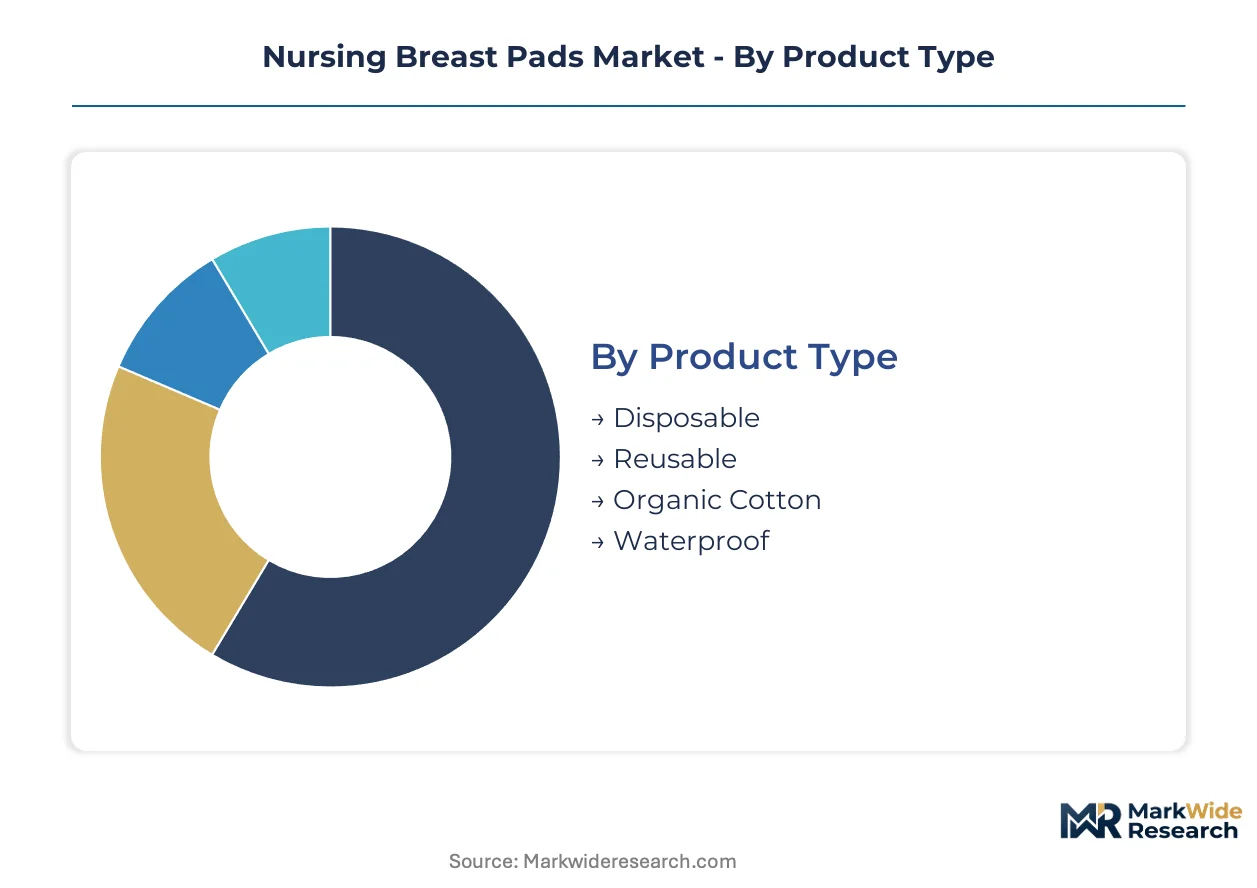
Nursing breast pad segmentation separates high-velocity disposable procurement from slower-turn reusable inventory cycles. Material and design specifications further stratify margins across clinical and home-care channels.
Product Type:
Disposable variants rotate through hospital supply chains in 30-60 day cycles, while reusable organic cotton pads sustain 12-18 month replacement intervals.
- Disposable:Multi-layer constructions with superabsorbent polymer cores dominate hospital procurement tenders. United States Medicaid reimbursement in 12 states drives institutional volume through durable medical equipment classifications.
- Reusable:Machine-washable bamboo or cotton layers capture eco-conscious direct-to-consumer buyers. European municipal composting infrastructure accelerates adoption in German and French urban markets.
- Organic Cotton:Certified chemical-free absorbent cores command pharmacy channel placement. Supply concentrates with vertically integrated textile processors in India.
- Waterproof:Thermoplastic polyurethane backing layers prevent leakage during extended wear. Travel and overnight use cases sustain premium positioning in airport retail and maternity clinic dispensing.
Disposable anchors the volume base while reusable gains share at the steepest rate.
Material:
Petroleum-derived inputs face margin compression against rapidly scaling cellulose alternatives.
- Polyethylene:Waterproof backing films remain standard in hospital-contracted disposables. EPA disposable product guidelines tighten landfill decomposition documentation requirements for manufacturers.
- Bamboo Fiber:Rapid-growth cellulose processing yields absorbent cores with competitive fluid retention. Asian manufacturers with captive bamboo plantations integrate forward into finished assembly.
- Cotton:Conventional bleached cotton retains cost advantage in mass-market retail tiers. Indian and Egyptian long-staple varieties supply premium organic segments.
- Microfiber:Synthetic fine-denier fabrics enable ultra-thin profile pads for discretion under fitted clothing. Moisture-wicking performance drives adoption in humid climate markets.
Bamboo fiber climbs the fastest as REACH chemical restrictions accelerate bio-based formulation shifts.
Design:
Contour engineering separates clinical-grade specifications from commodity flat-pad alternatives.
- Contoured:Anatomically shaped 3D constructions with adhesive strips secure positioning during movement. Japanese and South Korean sizing localization requirements favor regional specialists over Western incumbents.
- Flat:Uniform thickness profiles minimize production complexity for high-volume disposable contracts. Hospital bulk procurement favors standardized SKUs across maternity ward distribution.
- Ultra-Thin:Sub-2mm compressed cores target professional workplace discretion. Microfiber and advanced cellulose processing enable performance without bulk.
- Adjustable:Modular diameter settings accommodate lactation-stage breast volume changes. Direct-to-consumer platforms leverage algorithmic sizing recommendations for subscription retention.
Contoured designs sustain premium pricing while ultra-thin expands most quickly among millennial urban professionals.
End User:
Channel concentration determines procurement rhythm and margin structure.
- Hospitals:Centralized purchasing departments negotiate multi-year disposable supply agreements. FDA 510(k) biocompatibility documentation requirements filter supplier pools to established clinical-grade manufacturers.
- Maternity Clinics:Dispensing-based models combine product with lactation consultation services. Bundled reimbursement codes in select United States markets support integrated care delivery.
- Home Care:Direct-to-consumer platforms and pharmacy retail absorb volume as birth-rate differentials shift demand toward United States, China, and Germany. Subscription replenishment models displace stock-up purchasing among digital-native consumers.
- Retail:Big-box and pharmacy chains impose sustainability scorecards ahead of federal mandate deadlines. Private-label penetration concentrates in price-sensitive mass-market tiers.
Home care channels anchor volume while maternity clinics gain share at the steepest rate through service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss clinical-grade manufacturers export premium absorbent core technologies to maternity wards across the United States and China, while Asian bamboo fiber processors supply raw cellulose inputs to European compostable pad producers.
United States
Medicaid reimbursement expansion across twelve states now classifies nursing pads as durable medical equipment, opening institutional procurement channels. FDA biocompatibility standards under 510(k) pathways filter supplier pools to established clinical-grade manufacturers. Boston and Minneapolis medical device clusters concentrate R&D investment in skin-contact adhesive formulations.
China
Domestic birth-rate concentration and dual carbon goal mandates drive demand for compostable backing materials. NMPA hygiene product classification extends import registration timelines to eighteen months, protecting domestic incumbents. Yangtze River Delta manufacturers with captive bamboo plantations integrate forward into finished pad assembly.
Germany
REACH chemical restrictions on adhesive and fragrance compounds accelerate bio-based bonding agent development. Pharmacy network procurement teams specify compostability certifications in tender documents. Baden-Württemberg precision coating equipment suppliers concentrate multi-layer lamination expertise.
Japan
Localized sizing requirements for Asian anatomy create white space for regional specialists over Western incumbents. METI industrial standards govern absorbent performance testing protocols. Osaka-based material scientists advance humidity-adapted cellulose processing for tropical climate markets.
India
Vertically integrated textile processors in Gujarat and Tamil Nadu supply certified organic cotton cores to European pharmacy channels. CDSCO medical device rules tighten import documentation for skin-contact products. Mumbai direct-to-consumer platforms experiment with algorithmic sizing for subscription retention models.
Nursing Breast Pads Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: clinical-grade manufacturers with FDA 510(k) clearances, eco-conscious direct-to-consumer brands with compostable certifications, and mass-market disposable producers with hospital contract scale. The competitive terrain rewards dual capabilities in regulatory documentation and sustainable material sourcing. Dominant moves include backward integration into captive bamboo fiber production and strategic partnerships with pharmacy distribution networks.
Among Swiss and American clinical specialists, Medela and Cardinal Health exemplify the regulatory-documentation tier, while Lansinoh Laboratories occupies a position bridging retail pharmacy scale with lactation consultation service integration. These three anchors represent divergent pathways to margin defense: clinical-grade certification, channel control, and service bundling.
| Leading Market Players |
|---|
| Medela |
| Cardinal Health |
| Lansinoh Laboratories |
| Ameda |
| Pigeon Corporation |
| NUK USA |
| Bamboobies |
| LilyPadz |
| KINDRED BRAVELY |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese bamboo fiber processing is compressing raw material premiums while amplifying bargaining power for finished-goods assemblers in the Yangtze River Delta. This utilization imbalance propagates through contract negotiations, forcing European and North American brands to absorb cost volatility or accelerate backward integration into captive cellulose supply.
Pricing Analysis
Current-generation petroleum-based superabsorbent polymer cores command 15-25% price premiums over prior-generation bleached cotton alternatives, while next-generation modified starch and polylactic acid formulations remain cost-disadvantaged pending scale. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel control, with FDA 510(k)-cleared clinical variants sustaining the highest price points. Pricing pressure stems from petroleum input cost volatility and compressed hospital procurement cycles, with mass-market retail tiers exhibiting the greatest price sensitivity while maternity clinic bundled service models demonstrate the least.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Yangtze River Delta assemblers serving global brands, Baden-Württemberg precision coating specialists supplying multi-layer lamination equipment, and Gujarat textile processors providing certified organic cotton cores. Raw material dependencies center on petroleum-derived superabsorbent polymers, bamboo cellulose from captive Asian plantations, and thermoplastic polyurethane waterproof films. Single-source vulnerability in Japanese fluid-wicking top sheet coating expertise creates chokepoint exposure. Distribution runs through pharmacy network procurement in Germany, direct-to-consumer subscription platforms in the United States, and hospital centralized purchasing departments across Medicaid expansion states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as birth-rate stabilization in the United States and Germany drives replacement demand for disposable and reusable segments alike.
For Market Incumbents: Entrench clinical-grade positioning through accelerated FDA 510(k) biocompatibility documentation for novel plant-based cores, while securing pharmacy channel exclusivity in German and French networks. Reusable cotton pad substitution through European municipal composting programs threatens repeat-purchase frequency; defend against this through subscription-based replenishment models with algorithmic sizing retention.
For New Entrants and Emerging Players: South Korean market underpenetration by Western sizing standards creates immediate white space for regional specialists with localized contour engineering. Japan's humidity-adapted material requirements and METI industrial standards governance favor domestic incumbents, but direct-to-consumer platforms can bypass traditional retail markup structures through digital-native brand building. Target maternity clinic dispensing models with bundled lactation consultation services for fastest reimbursement code capture.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with subscription retention infrastructure and compostable certification credentials. Long-term viability across the 5-10 year window favors manufacturers with backward integration into captive bamboo fiber production and dual carbon goal alignment for Chinese domestic placement. Monitor NMPA hygiene product classification timeline compression as the inflection signal for foreign manufacturer market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Certification Investment | European pharmacy procurement teams now specify biodegradability credentials in tender documents. |
| Direct-to-Consumer Platform Launch | Subscription models bypass retail markup structures and capture recurring revenue from millennial buyers. |
| Backward Integration into Bamboo Fiber | Asian manufacturers with captive plantations compress cost gaps versus synthetic polymer suppliers. |
| FDA 510(k) Biocompatibility Pathway | Clinical-grade clearance filters supplier pools for institutional procurement in Medicaid expansion states. |
| Sizing Localization for Asian Anatomy | Japanese and South Korean contour adjustments favor regional specialists over Western incumbents. |
Research Methodology
Operator-level perspectives from maternity ward procurement managers, lactation consultant service directors, GPO contracts specialists, and direct-to-consumer platform operators anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, NMPA hygiene product registrations, European pharmacy procurement databases, and REACH chemical restriction compliance records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verified volume and value estimates.
Scenario-bracketing around birth-rate trajectories, petroleum price volatility bands, and regulatory timeline compression framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, material grade, design specification, and end-user channel. CAGRs derived from weighted average of historical trend extrapolation and structural shift elasticity coefficients, with absorbent polymer substitution rates and subscription model penetration curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian contract manufacturers into branded finished goods or accelerated REACH chemical restriction expansion would shift outcomes. Quarterly review of NMPA import registration timelines, Medicaid reimbursement state expansion patterns, and bamboo fiber processing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
US N95 Mask Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Global Syringe Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Hospital Consumables Market