
 Hydrogel Dressing Market | 2026-2036
Hydrogel Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogel Dressing Market Intelligence
Germany is fragmenting hydrogel dressing manufacturing capacity as regional producers challenge incumbent supply chains. Smith & Nephew leverages its European distribution infrastructure to sustain clinical trial partnerships across burn centers. Coloplast A/S anchors its position through specialized urology and wound care channels. Mölnlycke Health Care AB competes via Mepitel-branded silicone-hydrogel hybrid platforms that dominate Nordic procurement frameworks.
Hydrogel dressings comprise cross-linked hydrophilic polymer networks containing 90% water content, designed to maintain moist wound environments that accelerate re-epithelialization and reduce pain during removal. Transparent film hydrogels lead the product type category through their optical clarity that permits wound monitoring without dressing changes, while smart hydrogels with embedded pH-responsive indicators represent the fastest-growing technology segment as clinicians demand real-time infection signaling. Hospital end users command the largest procurement volumes, though home care channels are expanding fastest as post-acute wound management shifts toward outpatient settings.
The FDA's 510(k) clearance framework governs hydrogel dressing commercialization in the United States, while the EU MDR requires clinical evidence for Class IIa wound care devices across European markets. Japan's PMDA maintains distinct biocompatibility testing protocols that shape product development priorities for Asian market entry. Stakeholders must monitor evolving reimbursement thresholds for advanced wound dressings as payors tighten evidence requirements for moist healing modalities.
Market Dynamics
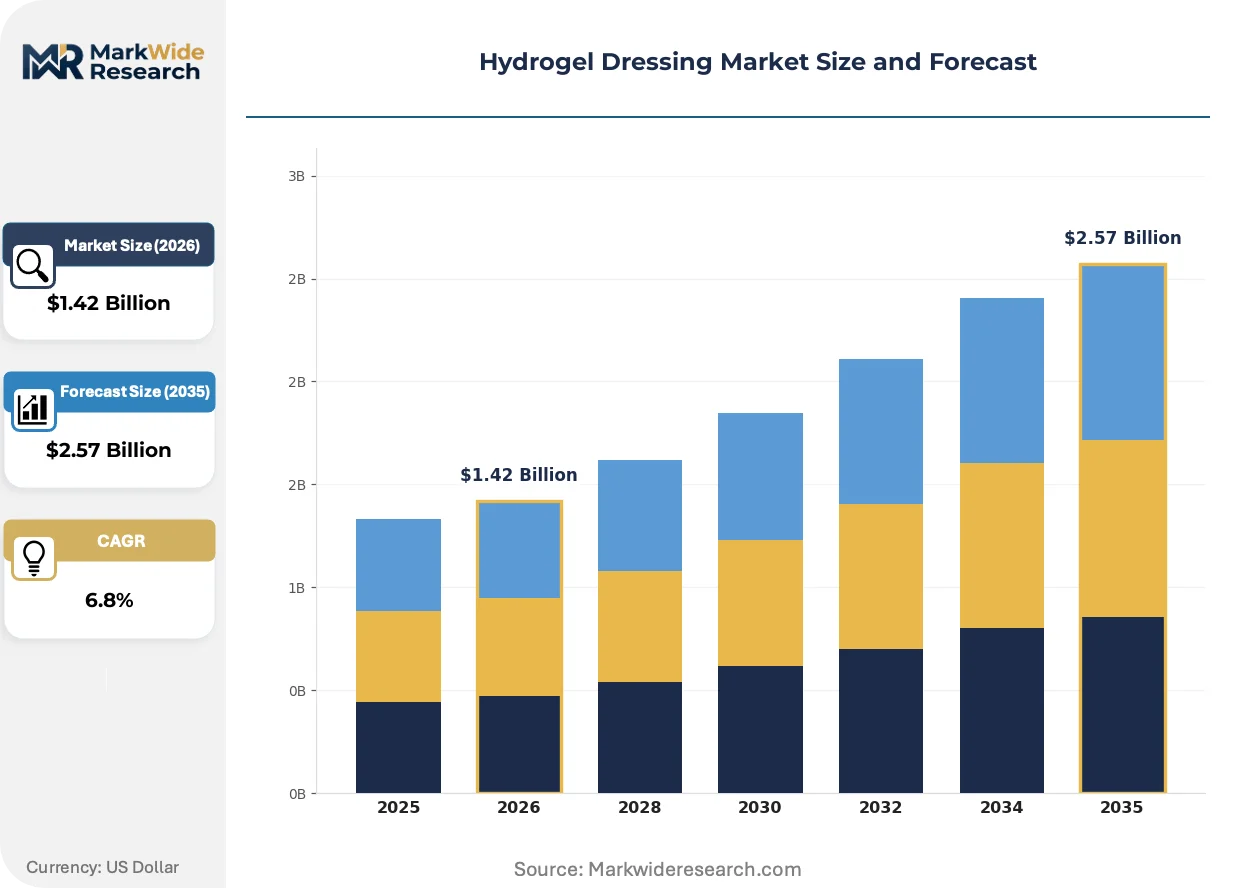
The hydrogel dressing market is undergoing structural recalibration as reimbursement gatekeepers tighten evidence requirements for moist wound healing modalities, forcing manufacturers to restructure clinical trial investments around real-world outcome data rather than traditional bench-top performance metrics.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated pathway for advanced wound dressings accelerates commercialization timelines for hydrophilic polymer technologies, reducing regulatory friction for novel cross-linked formulations entering US hospital procurement networks.
- Burn Center Protocol Standardization:Specialized burn units are institutionalizing hydrogel-based moist healing as first-line therapy for partial-thickness thermal injuries, creating dedicated demand channels resistant to commodity dressing substitution.
- Silicone-Hydrogel Hybridization:Convergence of silicone adhesion layers with hydrogel matrices enables extended wear times and reduced dressing change frequency, addressing labor cost pressures in acute care settings.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic acid and vinyl pyrrolidone monomer prices fluctuate with crude oil derivatives, compressing margin stability for commodity hydrogel sheet producers.
- Single-Country Supply Concentration:Germany's fragmented manufacturing base lacks scale economies enjoyed by consolidated US and UK production hubs, elevating unit costs for regional European supply.
- Silver-Impregnated Foam Substitution:Antimicrobial foam dressings with ionic silver challenge hydrogel adoption in exuding wound categories where infection risk dominates clinical decision-making.
Strategic Opportunities
- Home Care Channel Expansion:Post-acute wound management migration toward outpatient settings creates demand for patient-applied hydrogel systems with simplified application protocols.
- pH-Responsive Smart Formulations:Embedded chromogenic indicators that signal infection through color change represent unpenetrated premium segments commanding reimbursement premiums.
- Japan's PMDA Biocompatibility Pathway:Streamlined testing protocols for hydrophilic polymers reduce market entry costs for Western manufacturers targeting Asia-Pacific expansion.
Industry Challenges
- Clinical Evidence Generation Burden:EU MDR Class IIa requirements demand prospective clinical data for wound care devices, extending certification timelines and elevating trial costs for mid-cap manufacturers.
- Legacy Electronic Health Record Integration:Smart dressing data outputs lack standardized interoperability with hospital information systems, limiting adoption of connected wound monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogel Dressing Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Impregnated Sheets, Alginate Dressings, Foams End User: Clinics, Hospitals, Home Care, Long-term Care Facilities Technology: Hydrophilic Polymers, Cross-linked Structures, Biodegradable Materials, Smart Hydrogels Distribution Channel: Online Retail, Pharmacies, Hypermarkets, Direct Sales |
| Companies Covered | 3M, Smith & Nephew, Coloplast A/S, ConvaTec Group PLC, Integra LifeSciences, Cardinal Health, Mölnlycke Health Care AB, B. Braun Melsungen AG, Laboratoires Urgo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogel Dressing Market Strategic Shifts & Innovations
Material science convergence with digital health capabilities is redefining competitive differentiation in advanced wound care, shifting value capture from commodity moisture management toward data-integrated therapeutic monitoring systems.
Transparent film hydrogels are migrating from passive moisture retention toward active optical sensing platforms. Burn centers in the United States are piloting these systems for remote wound assessment, reducing clinic visit frequency for chronic wound patients. The technology is migrating from hospital-exclusive supply chains toward home care distribution networks as reimbursement frameworks adapt to telehealth-integrated care models.
EU MDR implementation is compressing the wound care device approval landscape across European markets. Class IIa reclassification demands clinical performance data for hydrogel dressings previously cleared through equivalence pathways, forcing manufacturers to sponsor prospective studies. German and Nordic hospital procurement frameworks are responding by consolidating supplier lists around MDR-compliant portfolios, disadvantaging smaller regional producers lacking trial infrastructure.
Hospital purchasing consortiums are consolidating vendor relationships around full-category suppliers capable of spanning moist to absorbent dressing portfolios. Group purchasing organizations in the United States are displacing single-product contracts with integrated wound care agreements that bundle hydrogels, alginates, and foams under single-source terms. This concentration is most visible in the southeastern United States, where regional health systems are reducing active supplier counts by forty percent to streamline logistics and standardize nursing protocols.
Hydrogel Dressing Market Segmentation
Hydrogel dressing procurement patterns diverge sharply across clinical settings and product formats. Understanding these segment boundaries clarifies where manufacturers must align R&D investments with reimbursement pathways versus where commodity positioning suffices.
Product Type:
Cycle times vary dramatically by format—transparent films turn over fastest through burn center protocols while alginate variants sit longer in inventory awaiting specialized wound presentations.
- Transparent Films:Cross-linked hydrophilic polymer sheets with optical clarity enabling wound visualization without dressing removal. Demand concentrates in United States burn centers where FDA-cleared moist healing protocols drive standardized procurement volumes.
- Impregnated Sheets:Hydrogel matrices pre-saturated with antimicrobial or debriding agents, requiring tighter cold-chain logistics. Nordic hospital networks favor these for partial-thickness thermal injuries where infection risk elevates clinical priority.
- Alginate Dressings:Calcium-sodium fiber gels forming hydrophilic gels upon exudate contact.
- Foams:Hydrogel-impregnated polyurethane structures balancing moisture retention with absorbency.
Transparent films anchor the volume base while smart hydrogel variants gain share at the steepest rate.
End User:
Cost tier stratification separates acute care capital expenditure from outpatient operating budgets, with home care occupying the most price-sensitive band.
- Hospitals:Command procurement volumes through centralized purchasing committees negotiating multi-year supply agreements. United States group purchasing organizations bundle hydrogels with broader advanced wound care portfolios, squeezing single-product vendors.
- Home Care:Fastest-expanding channel as post-acute wound management migrates toward outpatient settings. Simplified application protocols and patient-applied systems dominate reimbursement-eligible demand in Germany's regional health networks.
- Clinics:Outpatient wound care centers with mixed acute-chronic case loads.
- Long-term Care Facilities:Pressure ulcer prevention and management in skilled nursing environments.
Hospitals anchor the volume base while home care gains share at the steepest rate.
Technology:
Application requirements dictate material selection—chronic wounds demand biodegradability while acute burns prioritize structural integrity under mechanical stress.
- Smart Hydrogels:pH-responsive chromogenic indicators embedded within polymer matrices enabling real-time infection signaling. United States burn centers pilot these for remote wound assessment, reducing clinic visit frequency through telehealth-integrated reimbursement frameworks.
- Hydrophilic Polymers:Conventional polyvinyl alcohol and polyethylene oxide networks forming the commodity backbone of moist wound healing. Manufacturing concentrates in consolidated United States and United Kingdom production hubs benefiting from scale economies.
- Cross-linked Structures:Covalently bonded polymer networks optimizing gel strength and water retention.
- Biodegradable Materials:Collagen and chitosan-based matrices eliminating dressing removal trauma.
Hydrophilic polymers anchor the volume base while smart hydrogels expand most quickly.
Distribution Channel:
Customer type determines channel preference—institutional buyers favor direct relationships while individual patients default to retail accessibility.
- Direct Sales:Manufacturer-to-hospital contracts governing bulk procurement of FDA-cleared advanced dressings. United States procurement networks increasingly mandate MDR-compliant documentation even for domestic suppliers.
- Online Retail:Patient-direct platforms expanding fastest for home care hydrogel systems with simplified application protocols. Germany's fragmented regional producer base leverages these channels to bypass incumbent distributor markups.
- Pharmacies:Community and hospital outpatient dispensaries with pharmacist counseling.
- Hypermarkets:Mass retail channels for consumer-grade first-aid hydrogel products.
Direct sales anchor the volume base while online retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States burn centers deploy hydrogel dressings for continuous moist healing protocols, while German outpatient networks favor patient-applied systems for post-acute wound management. This consumption-mix differential shapes divergent regulatory and procurement priorities across markets.
United States
FDA-cleared advanced dressings dominate hospital procurement through group purchasing organization bundling. The FDA's 510(k) pathway accelerates commercialization for hydrophilic polymer technologies. Texas Medical Center burn units in Houston anchor clinical trial partnerships for next-generation moist healing systems.
Germany
Regional health networks drive demand for reimbursement-eligible home care hydrogel systems with simplified protocols. The EU MDR Class IIa reclassification demands prospective clinical data for wound care devices. North Rhine-Westphalia's fragmented manufacturing base challenges incumbent supply chains through specialized regional production.
Japan
PMDA biocompatibility testing protocols shape product development priorities for hydrophilic polymer entry. METI streamlines regulatory pathways for Western manufacturers targeting Asia-Pacific expansion. Kanto region burn centers pilot smart hydrogel platforms with embedded infection signaling for remote wound assessment.
United Kingdom
NHS procurement frameworks consolidate supplier lists around MDR-compliant wound care portfolios. The MHRA maintains alignment with EU MDR requirements post-Brexit, preserving clinical evidence standards. Greater London hospital trusts anchor volume demand through centralized advanced dressing contracts.
China
NMPA medical device registration drives localization requirements for imported hydrogel technologies. The country's dual carbon goals accelerate biodegradable hydrogel material development priorities. Yangtze River Delta manufacturing clusters scale domestic production of polyvinyl alcohol-based wound care products.
Hydrogel Dressing Market Key Industry Players
Capability concentration sits with specialized wound care innovators; scale advantage sits with diversified health care conglomerates. The market structures around three tiers: integrated multinationals with full-category portfolios, mid-cap specialists with regional clinical partnerships, and emerging regional producers challenging incumbent pricing. Dominant competitive moves include M&A for technology acquisition and strategic partnerships with burn center networks for clinical evidence generation.
Within the integrated multinational tier, 3M and Smith & Nephew exemplify scale-driven positioning through diversified health care platforms spanning multiple wound care modalities. Coloplast A/S occupies a specialist position anchored in urology and wound care channel integration. These three entities represent contrasting archetypes: conglomerate diversification, clinical partnership depth, and specialized therapeutic focus.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Coloplast A/S |
| ConvaTec Group PLC |
| Integra LifeSciences |
| Cardinal Health |
| Mölnlycke Health Care AB |
| B. Braun Melsungen AG |
| Laboratoires Urgo |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors govern landed cost differentials for acrylic acid monomers entering European hydrogel manufacturing, concentrating margin pressure on Germany's fragmented regional producers while consolidating pricing power with United States and United Kingdom scale hubs that command volume-based procurement leverage.
Pricing Analysis
United States hospital procurement networks pay fifteen to twenty percent premiums over German outpatient channels for FDA-cleared transparent film hydrogels. Three-tier pricing structure across premium smart formulations, standard silicone-hybrid platforms, and economy hydrophilic polymer sheets separates reimbursement-eligible advanced dressings from commodity moist healing alternatives. Cost compression in economy tiers is intensifying because petrochemical feedstock volatility compresses margins for acrylic acid-dependent producers. Home care channels exhibit highest price sensitivity, while burn centers demonstrate lowest sensitivity due to protocol standardization and clinical outcome prioritization.
Supply Chain Analysis
Tariff exposure between United States and Chinese polymer precursor suppliers dominates supply chain risk assessment for Western hydrogel manufacturers. Manufacturing concentrates in United States, United Kingdom, and Germany, with acrylic acid, vinyl pyrrolidone, and medical-grade silicone elastomers forming critical input dependencies. Single-source vulnerability in ionic silver antimicrobial additives creates procurement fragility for impregnated sheet variants. Distribution runs through hospital group purchasing organizations in United States, direct manufacturer contracts in Germany, and online retail platforms expanding fastest for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver-impregnated foam dressings threaten hydrogel positioning in exuding wound categories, forcing incumbents to defend through clinical evidence differentiation and smart formulation premiumization.
For Market Incumbents: Build regulatory moat through prospective EU MDR clinical trial investments that mid-cap competitors cannot fund, while securing backward integration into acrylic acid polymerization to offset petrochemical volatility. Coloplast A/S and Smith & Nephew demonstrate this through captive supply partnerships with Nordic procurement frameworks. Defend against antimicrobial foam substitution by embedding pH-responsive infection signaling in premium tier offerings. For New Entrants and Emerging Players: Build out patient-applied home care systems for Germany's regional health networks, where reimbursement eligibility for simplified protocols creates white-space opportunity absent from saturated United States GPO channels. Target online retail distribution to bypass incumbent distributor markups. Position biodegradable collagen-hydrogel hybrids for Japan's PMDA streamlined biocompatibility pathway as lower-cost Asia-Pacific entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health care conglomerates seeking to divest non-core wound care divisions lacking MDR compliance infrastructure. Long-term viability hinges on smart hydrogel platform ownership with embedded sensing capabilities and telehealth integration. Monitor FDA 510(k) clearance velocity for hydrophilic polymer innovations as inflection signal for competitive repositioning timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Trial Investment | Prospective outcome data secures Class IIa certification ahead of equivalence pathway elimination. |
| Silicone-Hydrogel Hybrid Development | Extended wear times address labor cost pressures in United States acute care settings. |
| Home Care Channel Expansion | Patient-applied systems capture Germany's fastest-expanding reimbursement-eligible segment. |
| pH-Responsive Smart Formulation Launch | Real-time infection signaling commands premium pricing in United States burn center protocols. |
| Japan PMDA Market Entry | Streamlined biocompatibility testing reduces Asia-Pacific expansion costs for Western manufacturers. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and hospital procurement contract filings preceded structured interviews with burn center clinical directors, wound care nurse specialists, GPO contracts managers, and biomedical engineers. Secondary validation drew from CMS Medicare reimbursement schedules, German regional health network tender records, and Japanese PMDA biocompatibility testing protocols. Bottom-up demand modeling triangulated against top-down market sizing across hydrophilic polymer production capacity estimates.
Assumptions held fixed include current FDA 510(k) pathway timelines and EU MDR Class IIa clinical evidence requirements, while variables tested included petrochemical feedstock price scenarios and home care reimbursement expansion rates. Segmentation modeling spanned product format, end-user setting, technology tier, and geographic regulatory cluster. CAGRs derived from weighted average of historical volume trends and elasticity-adjusted demand projections, incorporating burn center protocol adoption curves and smart hydrogel pilot program conversion rates as industry-specific inputs.
Practitioners should monitor EU MDR implementation delays, silver nanoparticle regulatory restrictions, and telehealth reimbursement code expansions for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Global Needles Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Swabs Collection Kit Market