
 Surgical Collagen Powders Market | 2026-2036
Surgical Collagen Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Collagen Powders Market Insights
China is tilting toward expanded collagen processing capacity to serve domestic surgical biomaterial needs. Baxter International leverages its hemostasis portfolio to sustain leadership in intraoperative powder applications. Johnson & Johnson MedTech anchors North American hospital supply chains through its broad surgical portfolio. Integra LifeSciences specializes in regenerative matrices that compete directly with powdered collagen formats for wound bed preparation.
Surgical collagen powders consist of purified, milled extracellular matrix proteins—primarily Type I collagen sourced from mammalian tissues—processed to particle sizes between 100 and 500 microns for topical or injectable deployment. These powders activate platelet aggregation and provide scaffold architecture for cellular infiltration during wound closure and tissue reconstruction. Bovine-derived formulations dominate hospital procurement due to established supply chains and lower immunogenicity profiles, while marine collagen represents the fastest-growing source category as aquaculture byproduct utilization improves. Wound healing applications capture the largest volume share, though tissue regeneration commands premium pricing in orthopedic and dental surgical settings.
The FDA enforces 21 CFR Part 820 quality system regulations and ISO 13485 compliance for collagen-based medical devices, creating barriers for unvalidated suppliers while accelerating 510(k) clearance timelines for established manufacturers. The EU Medical Device Regulation (MDR) demands enhanced clinical evidence for absorbable hemostats, reshaping market access requirements for exporters serving European hospitals. Stakeholders must monitor evolving biocompatibility testing standards and source traceability mandates as regulators tighten scrutiny on xenogeneic tissue origins.
Market Dynamics
FDA's 21 CFR Part 820 quality system regulations and ISO 13485 compliance requirements are compressing vendor margins while accelerating 510(k) clearance advantages for established manufacturers with validated biocompatibility testing infrastructure.
Growth Catalysts
- Biocompatibility standardization:The EU Medical Device Regulation mandates enhanced clinical evidence for absorbable hemostats, creating compliance moats that favor scaled collagen processors with dedicated regulatory affairs teams.
- Orthopedic surgical volume:Hospital systems in the United States are standardizing collagen powder protocols for arthroscopic procedures, driving recurrent procurement contracts for Type I collagen hemostatic agents.
- Aquaculture byproduct utilization:Marine collagen extraction from fish processing waste is expanding raw material availability beyond traditional bovine supply chains concentrated in North American and European livestock sectors.
Market Restraints
- Xenogeneic tissue traceability mandates:Source documentation requirements for mammalian-derived collagen impose batch-level tracking costs that erode margin structures for mid-scale processors lacking integrated supply chain visibility.
- Recombinant protein substitution:Synthetic collagen analogs produced through bacterial fermentation are capturing research-phase procurement in academic medical centers, threatening long-term category displacement.
- Bovine spongiform encephalopathy screening protocols:Extended quarantine and testing timelines for bovine tissue sourced from non-certified herds create inventory volatility and working capital pressure.
Strategic Opportunities
- Dental implantology expansion:Oral surgery suites in Germany and Switzerland are adopting collagen powder for ridge preservation procedures, opening premium pricing tiers outside traditional hospital procurement.
- Green chemistry incentives:The EU Green Deal's bio-based materials procurement preferences are creating tender advantages for marine-sourced collagen suppliers with certified sustainable extraction processes.
- Point-of-care compounding:Ambulatory surgery centers are requesting sterile collagen powder in unit-dose configurations, enabling direct-to-facility distribution models that bypass traditional distributor markups.
Industry Challenges
- ISO 10993 biocompatibility testing capacity:Cytotoxicity and sensitization assay backlogs at certified laboratories are extending product development timelines by six to twelve months for novel collagen formulations.
- Legacy ERP integration:Batch record systems designed for pharmaceutical manufacturing require costly customization to accommodate collagen powder particle size variability and moisture specification tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Collagen Powders Market |
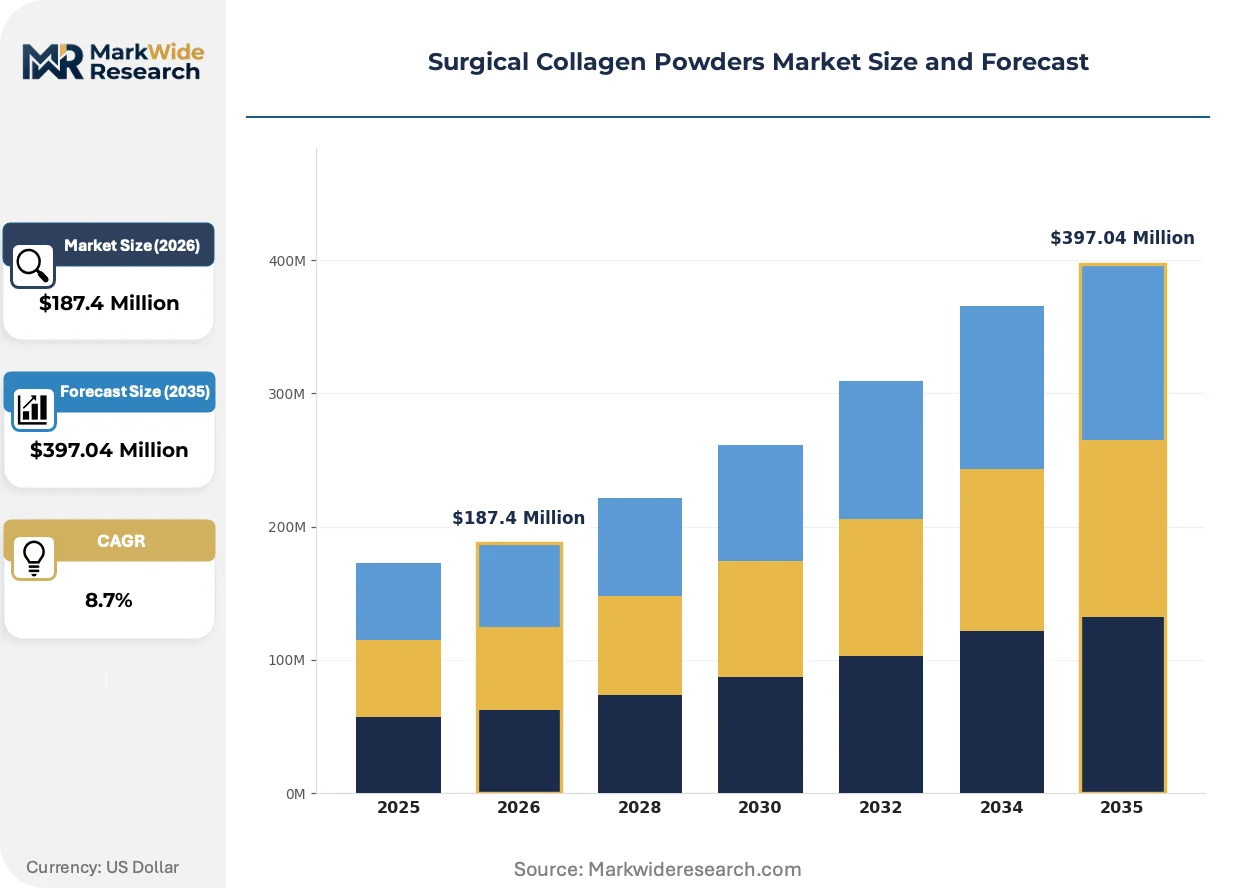
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcine, Bovine, Equine, Marine Application: Wound Healing, Tissue Regeneration, Hemostasis, Dermatology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Form: Powder, Spray, Sheet, Gel |
| Companies Covered | Becton, Dickinson and Company, Baxter International, Johnson & Johnson MedTech, Integra LifeSciences, B. Braun Melsungen AG, Smith+Nephew, Sanara MedTech, Advanced BioMatrix, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Collagen Powders Market Trends and Innovations
Collagen powder formulations are converging with advanced delivery mechanisms and digital surgical workflows, reshaping how hemostatic agents integrate into operative protocols and post-procedure documentation systems.
Electrospun collagen nanofiber matrices are hybridizing with traditional powder formats to create dual-action hemostatic products combining immediate particle-based clotting with sustained scaffold architecture. Academic medical centers in the United States are piloting these hybrid formats in cardiothoracic procedures where both rapid hemorrhage control and tissue integration are critical. The structural consequence is compression of standalone powder market share as surgeons demand multifunctional biomaterials that reduce operative product exchanges.
The EU Medical Device Regulation's enhanced clinical evidence requirements for absorbable hemostats are forcing manufacturers to conduct prospective registry studies rather than rely on predicate device equivalence. This regulatory friction is elevating development costs by two to threefold for novel collagen sources while accelerating market exit of suppliers lacking post-market surveillance infrastructure. European orthopedic distributors are consolidating supplier relationships to manage compliance documentation burden, concentrating procurement among three to four validated manufacturers.
Hospital value analysis committees are unbundling hemostat procurement from broad surgical supply contracts, creating standalone category management with dedicated clinical evidence review. This behavioral shift disrupts traditional distributor bundled pricing and forces collagen powder manufacturers to maintain direct clinical specialist teams. The United States exhibits the most pronounced committee autonomy, with integrated delivery networks in Texas and California establishing independent biomaterial evaluation boards that override legacy vendor relationships based on outcomes data submissions.
Surgical Collagen Powders Market Segmentation
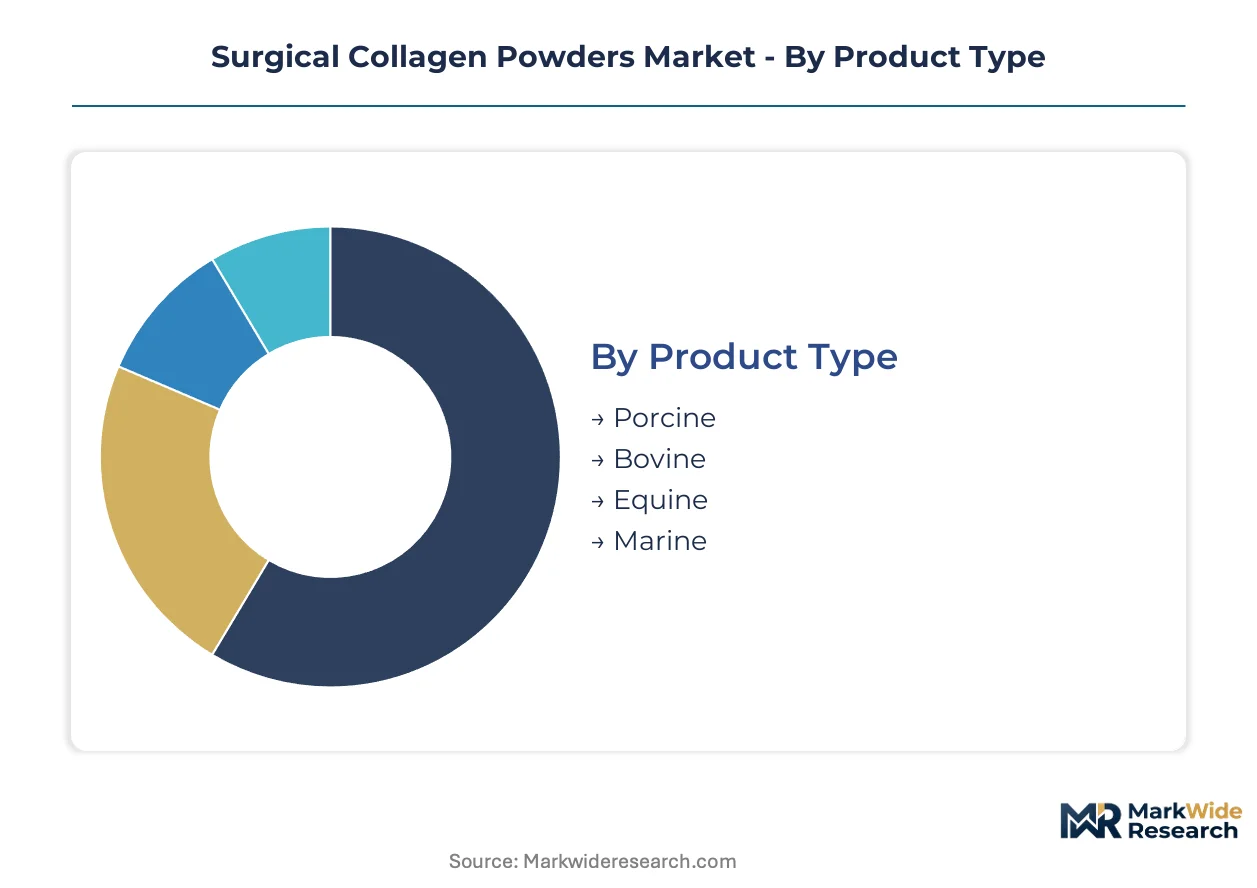
Collagen powder procurement patterns diverge sharply across source species, clinical application, and delivery format. Hospital value analysis committees now unbundle hemostat purchasing by segment, forcing suppliers to build discrete evidence packages for each category.
Product Type:
Cost tier stratification separates established mammalian sources from emerging marine alternatives with divergent supply chain economics and regulatory clearance pathways.
- Bovine:Type I collagen derived from closed-herd cattle dominates hospital procurement due to established FDA Master File documentation and lower immunogenicity profiles. United States surgical suites standardize bovine powders for arthroscopic hemostasis, though BSE screening protocols create inventory volatility for non-certified suppliers.
- Marine:Fish-scale and skin-derived collagen extraction from aquaculture byproducts is expanding raw material availability beyond traditional livestock supply chains. German oral surgery clinics are adopting marine-sourced powders for ridge preservation procedures, capitalizing on EU Green Deal procurement preferences for certified sustainable biomaterials.
- Porcine:Dermal and tendon-sourced porcine collagen offers intermediate immunogenicity profiles with established 510(k) predicate pathways.
- Equine:Tendon-derived equine collagen serves niche orthopedic applications requiring specific fiber architecture.
Bovine holds installed capacity. Marine is rotating up the share rankings.
Application:
Clinical utility determines pricing power, with regenerative matrices commanding premium tiers over commodity hemostasis.
- Hemostasis:Intraoperative bleeding control represents the highest-volume deployment, with Type I collagen powders activating platelet aggregation within seconds of topical application. United States hospital systems are standardizing protocols for arthroscopic procedures, driving recurrent procurement contracts through integrated delivery networks.
- Tissue Regeneration:Scaffold architecture for cellular infiltration commands premium pricing in orthopedic and dental surgical settings. Swiss and German implantology centers pay differential pricing for collagen powders specified for ridge preservation and guided bone regeneration.
- Wound Healing:Chronic wound management absorbs significant powder volume through outpatient clinic channels.
- Dermatology:Aesthetic and reconstructive applications utilize collagen powders for dermal matrix support.
Hemostasis captures procurement volume. Tissue regeneration is climbing the fastest.
End User:
Customer type dictates packaging requirements, regulatory documentation depth, and distribution channel economics.
- Hospitals:Academic medical centers and community hospital systems drive category volume through standardized formulary protocols. Texas and California integrated delivery networks maintain independent biomaterial evaluation boards that override legacy vendor relationships based on outcomes data submissions.
- Ambulatory Surgical Centers:Freestanding surgical facilities are requesting sterile collagen powder in unit-dose configurations, enabling direct-to-facility distribution models that bypass traditional distributor markups.
- Specialty Clinics:Oral surgery and dermatology practices purchase smaller lot sizes with specialized particle size specifications.
- Research Institutions:Academic laboratories procure research-grade collagen for preclinical device development.
Hospitals anchor procurement volume. Ambulatory Surgical Centers are gaining share fastest.
Form:
Delivery mechanism determines manufacturing complexity, sterilization validation requirements, and point-of-care workflow integration.
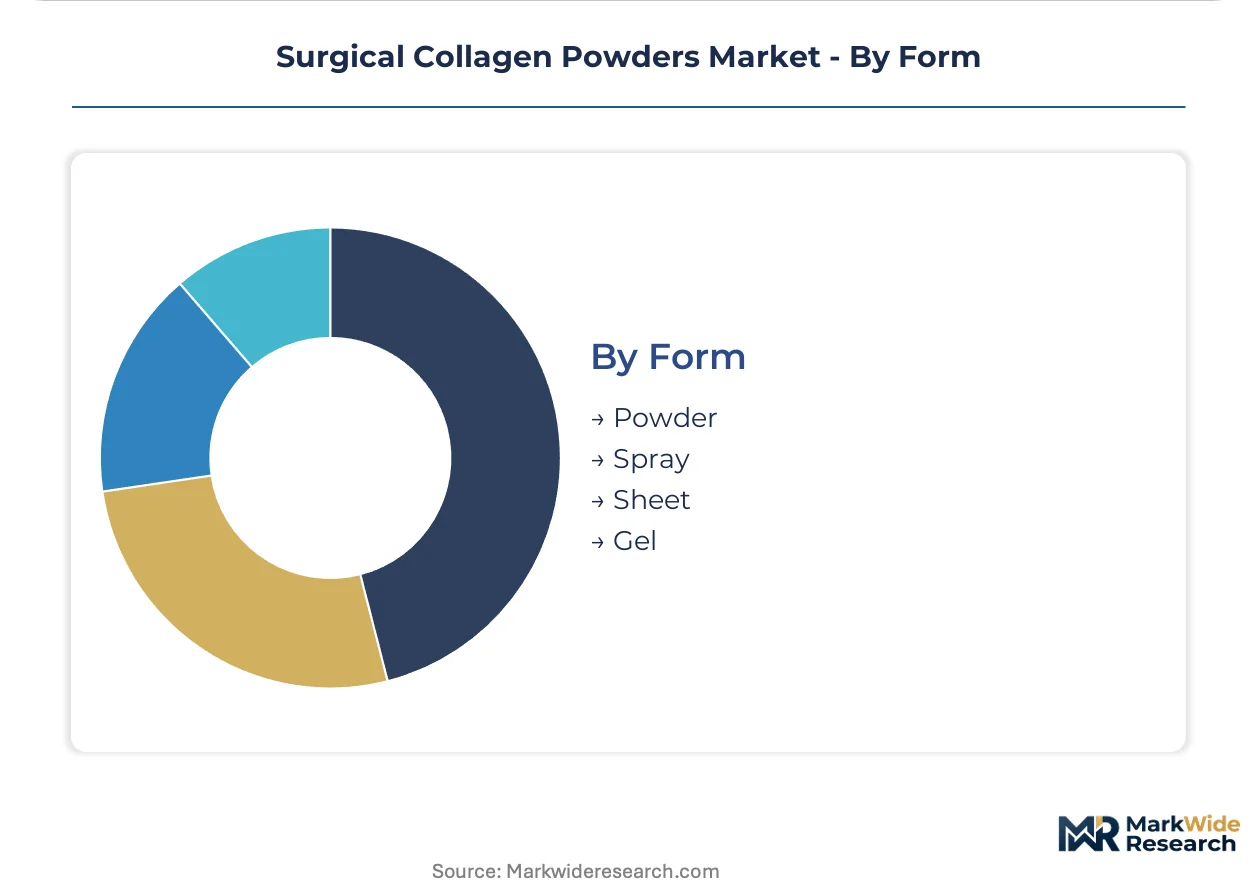
- Powder:Milled extracellular matrix proteins processed to 100-500 micron particle sizes enable topical or injectable deployment with immediate scaffold architecture formation. Powder formats dominate hospital procurement due to flexible dosing and compatibility with existing surgical workflows.
- Spray:Aerosolized delivery systems integrate powder with propellant mechanisms for uniform wound bed coverage.
- Sheet:Pre-formed collagen matrices provide mechanical stability for larger defect coverage.
- Gel:Hydrated collagen formulations offer flowable characteristics for irregular wound geometries.
Powder maintains manufacturing scale. Spray is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bovine tissue processing clusters in the United States and Germany supply the bulk of Type I collagen raw material, while marine extraction facilities in China and Norway expand alternative sourcing channels for surgical-grade powders.
United States
Academic medical centers in Texas and California drive procurement volume through independent biomaterial evaluation boards that override legacy vendor relationships based on outcomes data. FDA 21 CFR Part 820 quality system regulations compress margins for unvalidated suppliers while accelerating 510(k) clearance timelines for established manufacturers. The Research Triangle Park corridor in North Carolina hosts contract testing laboratories specializing in ISO 10993 biocompatibility assays for collagen hemostats.
Germany
Oral surgery clinics in Munich and Stuttgart adopt collagen powders for ridge preservation procedures, capitalizing on premium pricing tiers outside traditional hospital procurement. EU Medical Device Regulation mandates enhanced clinical evidence for absorbable hemostats, reshaping market access requirements for exporters. The Baden-Württemberg medical technology cluster concentrates sterile powder manufacturing and MDR compliance documentation services.
China
Domestic surgical biomaterial demand tilts toward expanded collagen processing capacity to reduce import dependence for hemostatic agents. NMPA biocompatibility requirements for implantable materials elevate product standards and compliance costs for local manufacturers. The Yangtze River Delta aquaculture processing hubs near Shanghai develop marine collagen extraction from fish-scale byproducts for surgical-grade applications.
Switzerland
Swiss implantology centers in Zurich and Geneva pay differential pricing for collagen powders specified for guided bone regeneration and tissue engineering matrices. Swissmedic maintains stringent xenogeneic tissue traceability mandates that favor suppliers with integrated supply chain visibility. The Basel pharmaceutical corridor hosts specialized collagen formulation facilities serving orthopedic and dental surgical markets.
Japan
PMDA regulatory pathways for novel collagen sources require extended clinical validation timelines that favor established bovine-derived predicate devices. Metropolitan Tokyo hospital systems standardize hemostatic protocols for arthroscopic procedures, driving recurrent procurement contracts through centralized purchasing organizations. The Osaka-Kobe medical device manufacturing zone concentrates powder milling and terminal sterilization capacity for domestic surgical supply chains.
Surgical Collagen Powders Market Competitive Landscape
Diversified medical technology conglomerates and specialized regenerative medicine firms split the market into distinct capability tiers. Baxter International leverages its hemostasis portfolio to sustain leadership in intraoperative powder applications, while Johnson & Johnson MedTech anchors North American hospital supply chains through broad surgical portfolios. Three strategic archetypes dominate: integrated surgical supply conglomerates with diversified hemostasis portfolios, regenerative medicine specialists competing on scaffold architecture, and contract manufacturers supplying private-label collagen formulations. Competitive moves concentrate on M&A to secure validated biocompatibility testing infrastructure and capacity expansion into marine-sourced extraction to diversify beyond bovine supply chains.
Within the diversified conglomerate tier, Baxter International and Johnson & Johnson MedTech exemplify scale-driven positioning through established 510(k) predicate pathways and hospital formulary penetration. Integra LifeSciences occupies a specialist position, representing the regenerative medicine archetype with matrices competing directly with powdered collagen formats for wound bed preparation. Among European-based suppliers, B. Braun Melsungen AG and Smith+Nephew sit within the surgical hemostasis tier, leveraging regional MDR compliance capabilities and orthopedic distributor relationships to maintain procurement presence in German and Swiss hospital systems.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Baxter International |
| Johnson & Johnson MedTech |
| Integra LifeSciences |
| B. Braun Melsungen AG |
| Smith+Nephew |
| Sanara MedTech |
| Advanced BioMatrix |
| DSM-Firmenich |
| Others |
Pricing and Supply Chain Analysis
BSE screening protocol volatility for bovine tissue determines both the premium-mid-economy pricing differentiation across source categories and the geographic diversification of collagen extraction capacity. FDA Master File documentation costs and EU MDR clinical evidence requirements compress margins for unvalidated suppliers while rewarding established processors with validated biocompatibility infrastructure.
Pricing Analysis
FDA 21 CFR Part 820 quality system regulations dictate the pricing tier structure across bovine, marine, and porcine collagen sources. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-certified marine extraction from commodity bovine powders. Cost compression in the standard tier intensifies because mid-scale processors lack integrated batch-level traceability systems. Ambulatory surgical centers exhibit highest price sensitivity due to direct procurement models, while German oral surgery clinics show lowest sensitivity for ridge preservation applications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for marine collagen processors serving North American hospital systems. Raw material extraction concentrates in the United States, Germany, and China, with bovine tissue processing anchored in closed-herd cattle operations. The supply chain draws from aquaculture byproducts, mammalian tendon stock, and recombinant protein fermentation feedstocks. Single-source vulnerability in ISO 10993-certified testing laboratories creates six-to-twelve month development bottlenecks. Distribution runs through orthopedic and dental distributor networks with direct-to-facility channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-market surveillance and clinical registry services represent a recurring-revenue layer expanding faster than powder hardware sales as EU MDR compliance mandates intensify documentation requirements.
For Market Incumbents: Harden biocompatibility testing infrastructure against recombinant protein substitution threats by acquiring certified ISO 10993 laboratory capacity. Expand backward integration into marine collagen extraction in Norwegian and Chinese aquaculture processing hubs to diversify beyond bovine supply chain volatility. Secure hospital formulary lock-in through outcomes-based contracting with Texas and California integrated delivery networks. For New Entrants and Emerging Players: Build out sterile unit-dose packaging capabilities for ambulatory surgical center direct distribution, bypassing traditional distributor markups. Target German and Swiss oral surgery clinics for ridge preservation collagen powders, where premium pricing tolerance exceeds hospital procurement benchmarks. Pursue EU Green Deal sustainability certification as a tender wedge against established bovine suppliers. For Investors and Strategic Acquirers: EU MDR enhanced clinical evidence requirements reshape the acquisition landscape toward processors with dedicated regulatory affairs teams and post-market surveillance infrastructure. Viable targets include marine-sourced collagen specialists with certified sustainable extraction and mid-scale manufacturers with validated 510(k) predicate pathways. Watch for NMPA biocompatibility standardization in China as a signal for domestic consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Documentation Buildout | EU Medical Device Regulation mandates elevate barriers for unvalidated collagen suppliers while accelerating procurement consolidation. |
| Marine Collagen Extraction Capacity | Aquaculture byproduct utilization in China and Norway diversifies raw material beyond bovine supply chain volatility. |
| ISO 10993 Testing Infrastructure Acquisition | Certified biocompatibility laboratory capacity compresses product development timelines by six to twelve months. |
| Direct-to-Facility Distribution Models | Ambulatory surgery center unit-dose configurations bypass traditional orthopedic distributor markups. |
| Hospital System Outcomes Partnerships | Texas and California integrated delivery networks override legacy vendor relationships based on clinical data submissions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital value analysis committees, orthopedic surgeons, dental implantologists, collagen processing plant managers, and regulatory affairs specialists. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and ISO 13485 certification records. Bottom-up volume estimates triangulated with top-down market sizing across source species, application, and end-user segments.
Calibration against historical procurement patterns and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include collagen source species, clinical application category, delivery format, and geographic regulatory cluster. CAGRs derived from procedure volume growth rates, reimbursement trajectory analysis, and biomaterial substitution elasticity. Forecast inputs incorporated arthroscopic surgery utilization trends and marine collagen extraction yield improvements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese marine processors or accelerated recombinant protein adoption by academic medical centers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Microcarrier Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Anti Venom Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Human Acellular Dermis Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Micro Vials Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market