
 Safety Needles Market | 2026-2036
Safety Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Needles Market Intelligence
Stainless steel is broadening its role as a cost-competitive substrate against advanced polymer composites in high-volume safety needle production. Becton Dickinson and Company leverages integrated manufacturing across multiple continents to sustain supply security for retractable and shielded platforms. Terumo Corporation anchors its position through concentrated R&D investment in passive activation mechanisms that reduce clinician error rates. B. Braun Melsungen AG differentiates via specialized catheter-compatible safety needle systems for European hospital networks.
Safety needles are medical injection devices incorporating engineered injury-prevention features such as retractable cannulas, protective shields, or self-blunting tips, typically manufactured through precision metal forming and automated assembly to achieve activation forces below 15 Newtons. Their primary purpose is eliminating percutaneous exposure to bloodborne pathogens during therapeutic injections, vaccinations, and specimen collection. Retractable needles occupy the largest value share among product types due to their irreversible disablement after use, while passive safety needles represent the fastest-expanding category as zero-step activation reduces training burden. Blood collection applications generate concentrated margin pools compared to high-volume vaccination segments where pricing pressure from public procurement dominates.
The US OSHA Bloodborne Pathogens Standard and the EU MDR together mandate safety-engineered sharp device adoption across hospital and clinic environments, with FDA 510(k) clearance pathways governing product market access. Health Canada and Japan's PMDA maintain aligned but distinct premarket review frameworks that shape regional product configuration requirements. Stakeholders must monitor evolving harmonization between ISO 23908 needle-based injury prevention performance standards and national procurement specifications to anticipate compliance-driven replacement cycles.
Market Dynamics
OSHA enforcement of the Bloodborne Pathogens Standard is compressing replacement cycles for conventional sharps across US hospital systems, forcing capital allocation toward passive-activation safety platforms that eliminate clinician-dependent steps.
Growth Catalysts
- US OSHA Bloodborne Pathogens Standard:Federal workplace safety mandates drive mandatory conversion from conventional to safety-engineered devices across acute care facilities and outpatient clinics.
- Passive activation mechanisms:Zero-step safety designs reduce training burden and activation failure rates compared to active user-dependent systems.
- European hospital networks:EU MDR compliance timelines accelerate procurement of ISO 23908-certified safety needle platforms.
Market Restraints
- Stainless steel price volatility:Raw material cost fluctuations compress margins for high-volume disposable safety needle manufacturers.
- Single-source supply concentration:Precision cannula forming equipment concentrates among German and Japanese machine tool suppliers.
- Activation force thresholds:ISO 23908's sub-15 Newton specification limits design flexibility for high-gauge needle applications.
Strategic Opportunities
- Indian outpatient clinic expansion:CDSCO regulatory alignment with ISO standards creates entry pathways for cost-optimized safety platforms.
- Home healthcare self-injection:Diabetes and biologic therapy administration shifts toward patient-operated devices requiring foolproof safety features.
- EU Green Deal procurement criteria:Sustainability-linked public tenders favor single-material recyclable safety needle constructions over multi-component assemblies.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization protocols extend FDA 510(k) clearance cycles for novel polymer shield materials.
- Legacy EMR integration:Safety needle lot tracking and activation verification systems require middleware development for hospital inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Needles Market |
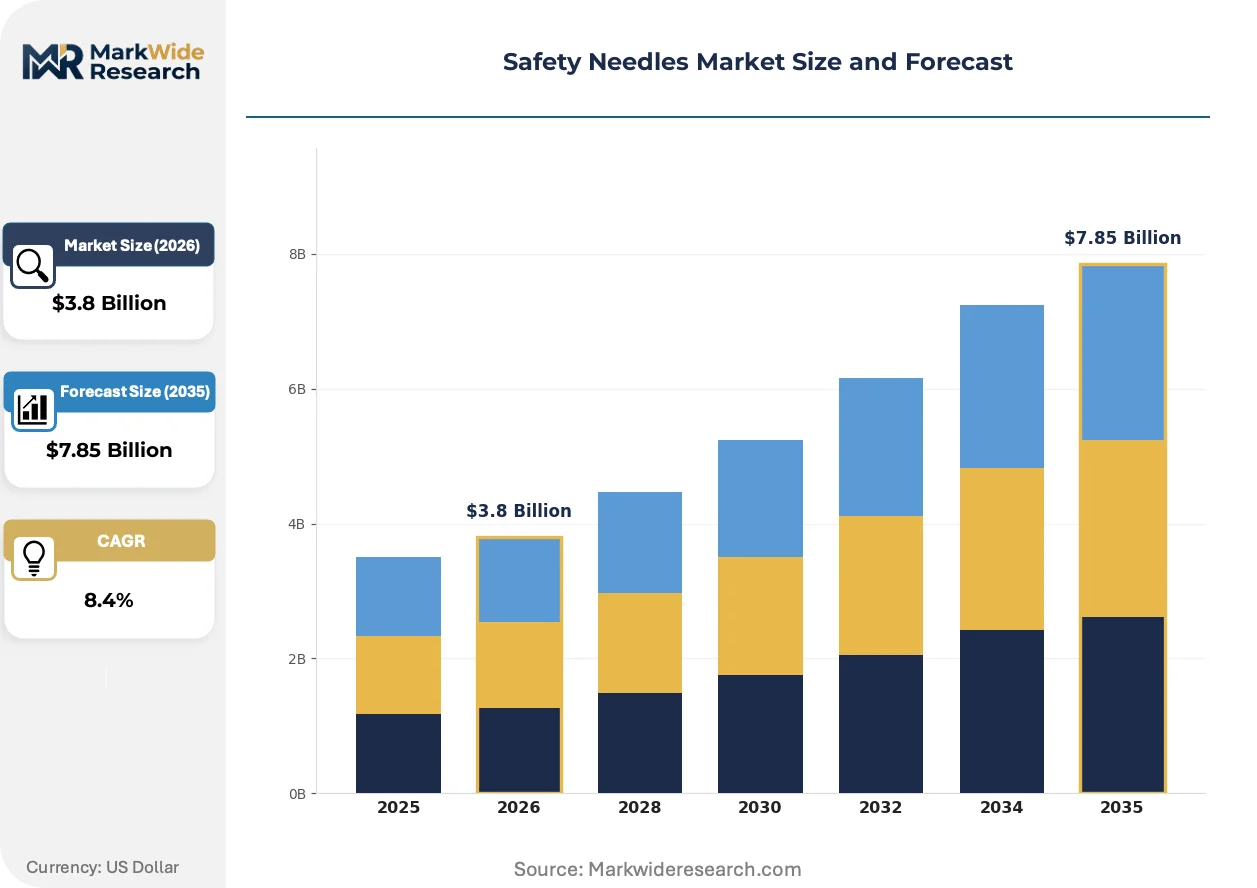
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable Needles, Shielded Needles, Passive Safety Needles, Active Safety Needles Application: Vaccination, Insulin Delivery, Blood Collection, Infusion Therapy End User: Hospitals, Clinics, Homecare Settings, Research Institutes Material: Plastic, Stainless Steel, Silicone, Rubber |
| Companies Covered | Becton Dickinson and Company, Terumo Corporation, Nipro Corporation, B. Braun Melsungen AG, Cardinal Health, Smiths Medical, Medtronic, Johnson & Johnson, Retractable Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Needles Market Strategic Shifts & Innovations
Device miniaturization and materials science are converging to eliminate the trade-off between clinician ergonomics and patient safety, collapsing the historical gap between high-performance shielded systems and cost-engineered alternatives.
Automated needle retraction mechanisms are automating the injury-prevention sequence through spring-loaded or vacuum-assisted cannula withdrawal triggered by plunger completion. Large integrated delivery networks are standardizing on these platforms to reduce variability in sharps injury reporting. The technology is automating compliance documentation by embedding radio-frequency identification tags that log activation events for OSHA record-keeping.
EU MDR technical documentation requirements are expanding premarket clinical evaluation obligations for safety needle manufacturers seeking CE marking. Device sponsors must now submit usability validation data demonstrating error rates across simulated clinical scenarios. European notified bodies are prioritizing review resources toward passive safety submissions, creating clearance bottlenecks for active-mechanism legacy products.
Group purchasing organization consolidation is compressing supplier lists to three to five contracted safety needle vendors per therapeutic category. Hospital systems are unbundling safety device procurement from pharmaceutical contracts to capture separate line-item savings. This pattern is most pronounced in United States metropolitan markets where IDN merger activity has concentrated purchasing authority.
Safety Needles Market Segmentation
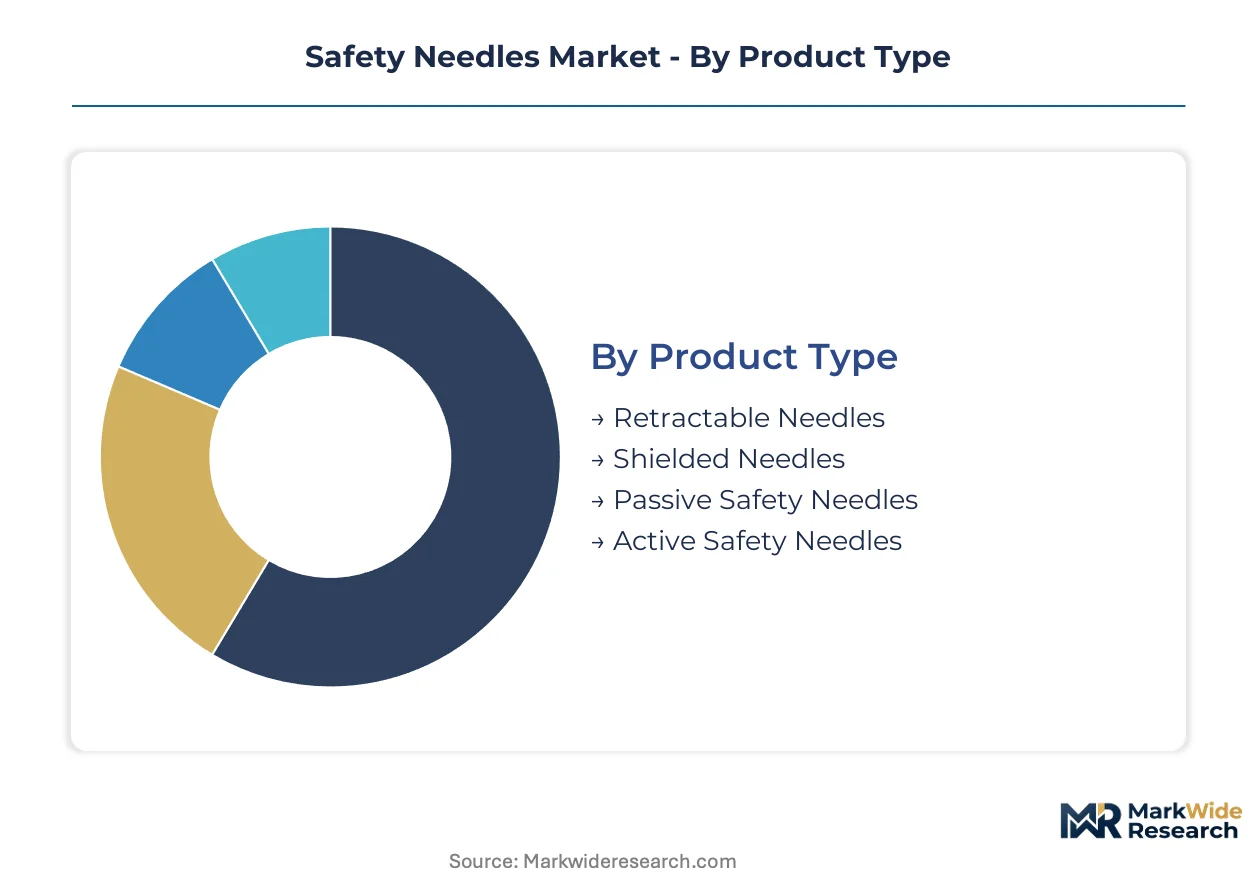
Safety needle procurement patterns diverge sharply across clinical settings, with infection control protocols and activation mechanism preferences reshaping supplier-customer relationships. Material selection and product architecture decisions cascade through manufacturing footprints, regulatory filing strategies, and sterilization validation requirements.
Product Type:
Supply concentration for precision retraction mechanisms centers on automated assembly lines in Germany and Japan, constraining capacity expansion for high-complexity platforms.
- Retractable Needles:Spring-loaded or vacuum-assisted cannula withdrawal triggers upon plunger completion, permanently disabling the device. United States hospital systems absorb the dominant share as OSHA record-keeping requirements favor irreversible safety features with embedded RFID activation logging.
- Passive Safety Needles:Zero-step activation eliminates clinician-dependent steps through automatic shield deployment upon needle withdrawal. European hospital networks under EU MDR compliance timelines are expanding procurement fastest as usability validation requirements favor fail-safe designs.
- Shielded Needles:External protective barriers manually or automatically cover the cannula post-use.
- Active Safety Needles:Require deliberate user action to engage protective mechanisms.
Retractable needles absorb the bulk of installed capacity; passive safety needles are expanding most quickly.
Application:
Margin structures vary dramatically across therapeutic categories, with specimen collection commanding premium pricing against commoditized high-volume immunization programs.
- Blood Collection:Multi-sample venipuncture systems integrate safety-engineered winged sets and evacuated tube holders with precision luer connections. United States reference laboratories and European hospital networks concentrate demand where contamination risk protocols justify premium device expenditure.
- Vaccination:Fixed-needle syringes with integrated safety features dominate mass immunization campaigns. Public procurement programs in India and Brazil impose severe pricing pressure, compressing margins for manufacturers dependent on stainless steel cannula supply chains.
- Insulin Delivery:Pen needles and safety syringes for diabetes management target homecare self-injection scenarios.
- Infusion Therapy:Safety-engineered access devices for intravenous medication administration.
Blood collection commands the steepest margin premiums; vaccination volumes dominate unit throughput.
End User:
Customer concentration patterns determine distribution economics, with integrated delivery networks consolidating purchasing authority faster than fragmented outpatient channels.
- Hospitals:Acute care facilities with comprehensive infection control departments mandate safety-engineered sharps across all invasive procedures. United States metropolitan IDNs and European hospital networks drive standardization toward passive-activation platforms to reduce variability in sharps injury reporting.
- Homecare Settings:Patient-operated injection devices for diabetes and biologic therapies require foolproof safety features with minimal training burden. Japan's aging population and United States Medicare home health expansion are accelerating demand for single-use autodisabling designs.
- Clinics:Outpatient facilities with lower procedure volumes and constrained capital budgets.
- Research Institutes:Preclinical and clinical trial settings with specialized biosafety requirements.
Hospitals anchor procurement volume; homecare settings are gaining share fastest.
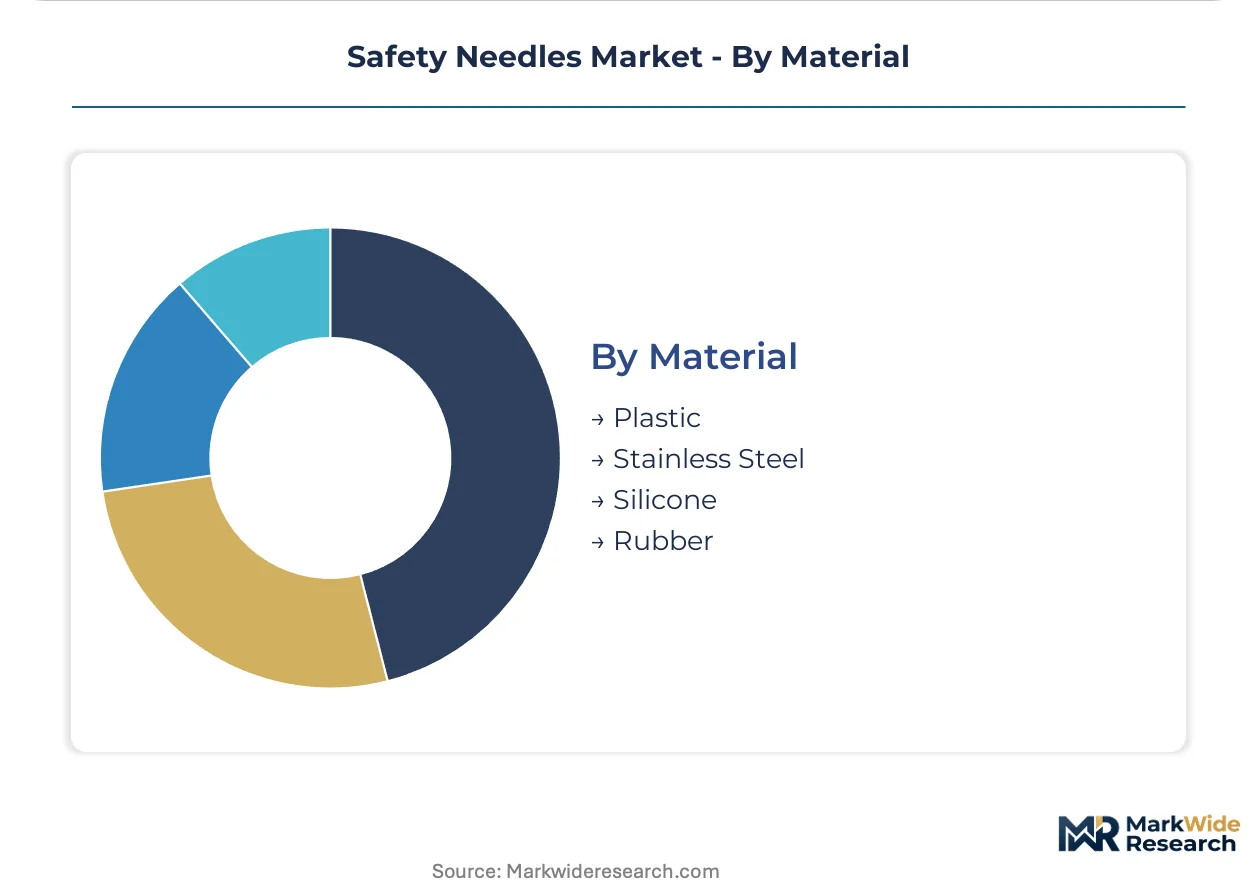
Material:
Raw material cost trajectories and biocompatibility validation timelines shape platform economics across disposable and durable device categories.
- Stainless Steel:Medical-grade 304 and 316L alloys form precision-drawn cannulas through multi-stage forming and electropolishing. Price volatility in nickel and chromium markets compresses margins for high-volume disposable manufacturers serving United States and Indian procurement programs.
- Plastic:Polypropylene and polycarbonate housings enable complex geometries for shield and retraction mechanisms. EU Green Deal procurement criteria favoring single-material recyclable constructions are accelerating substitution for multi-component assemblies in European tenders.
- Silicone:Lubricious coatings reduce penetration force and patient discomfort.
- Rubber:Elastomer components for plunger seals and gasket assemblies.
Stainless steel commands the dominant input cost share; plastic housings are climbing the fastest on sustainability-linked procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems concentrate the dominant share of safety needle procurement volume, with federal workplace safety mandates and needlestick injury litigation creating the world's most advanced replacement cycle for conventional sharps.
United States
OSHA enforcement of the Bloodborne Pathogens Standard compresses replacement cycles across acute care facilities, forcing capital allocation toward passive-activation platforms. Federal procurement preferences under the Federal Supply Schedule favor ISO 23908-certified devices. Metropolitan integrated delivery networks in Chicago, Houston, and Atlanta drive standardization toward RFID-enabled retractable systems for automated compliance documentation.
Germany
Precision cannula forming equipment suppliers cluster in Baden-Württemberg and Bavaria, constraining capacity expansion for high-complexity safety platforms. EU MDR technical documentation requirements expand premarket clinical evaluation obligations for CE marking. Stuttgart's medical technology corridor anchors automated assembly line development for spring-loaded retraction mechanisms serving European hospital networks.
Japan
Aging population demographics accelerate demand for single-use autodisabling designs in home healthcare self-injection scenarios. PMDA maintains aligned but distinct premarket review frameworks that shape regional product configuration requirements. Osaka-Kobe's medical device manufacturing belt concentrates passive activation mechanism R&D investment targeting reduced clinician error rates.
India
Outpatient clinic expansion in Maharashtra and Gujarat creates entry pathways for cost-optimized safety platforms serving mass immunization campaigns. CDSCO regulatory alignment with ISO standards streamlines market access for disposable manufacturers. Ahmedabad's stainless steel processing hub faces margin compression from nickel and chromium price volatility affecting high-volume production economics.
United Kingdom
NHS procurement frameworks prioritize infection control protocols across secondary care trusts, consolidating purchasing authority toward standardized safety-engineered sharps. MHRA operates under EU MDR transitional arrangements with distinct UKCA marking requirements. London's hospital network merger activity concentrates demand for catheter-compatible safety needle systems in tertiary referral centers.
Safety Needles Market Key Industry Players
Strategic partnerships dominate the current landscape as device manufacturers seek to secure precision forming capacity and automated assembly expertise. The vendor base organizes around three tiers: multinational integrated suppliers with continental manufacturing footprints, regional specialists in passive activation technologies, and cost-engineered disposable producers serving public procurement programs. Two archetypes define competitive positioning: technology licensors controlling proprietary retraction mechanisms, and scale operators optimizing stainless steel cannula supply chains. M&A activity targets precision metal forming assets in Germany and Japan, while portfolio diversification into home healthcare self-injection devices accelerates.
Among multinational integrated suppliers, Becton Dickinson and Company and Terumo Corporation exemplify the technology-licensor archetype through concentrated manufacturing footprints across multiple continents. B. Braun Melsungen AG occupies a position within the European specialist tier, while Retractable Technologies represents the North American innovation-focused segment. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic positioning: US-based corporations emphasize federal compliance integration, Japanese entities prioritize error-reduction engineering, and German operations leverage regional machine tool access for catheter-compatible system development.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Terumo Corporation |
| Nipro Corporation |
| B. Braun Melsungen AG |
| Cardinal Health |
| Smiths Medical |
| Medtronic |
| Johnson & Johnson |
| Retractable Technologies |
| Others |
Cost & Logistics Intelligence
Nickel and chromium price volatility cascades from stainless steel mills through three distinct pricing tiers for disposable safety needle manufacturers, with high-volume public procurement programs in India and Brazil absorbing the steepest cost compression while ISO 23908-certified premium platforms serving United States hospital networks retain pricing power through activation reliability guarantees.
Pricing Analysis
Volume throughput concentrates in mass immunization vaccination programs where public procurement imposes severe pricing pressure, while blood collection applications command premium margins through contamination risk protocols. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled retractable systems with automated compliance documentation from passive-activation platforms and basic shielded alternatives. Pricing pressure stems from stainless steel input cost fluctuations compressing margins for disposable manufacturers dependent on spot market metal purchases. Government tenders in emerging markets exhibit the highest price sensitivity, whereas United States integrated delivery networks prioritize activation failure rates over unit cost.
Supply Chain Analysis
Sharps waste return flows and autoclave sterilization logistics for reusable components create reverse-logistics complexity that shapes distribution economics for safety needle platforms. Precision cannula forming equipment concentrates in Germany and Japan, constraining capacity expansion for high-complexity retractable mechanisms. Raw material dependencies center on medical-grade 304 and 316L stainless steel alloys, polypropylene housings, and silicone lubricious coatings. Single-source vulnerability in German and Japanese machine tool suppliers exposes manufacturers to equipment lead time volatility. Distribution runs through group purchasing organizations consolidating hospital procurement authority toward three to five contracted vendors per therapeutic category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passive activation mechanisms are displacing active user-dependent safety designs across regulatory jurisdictions, compressing the window for legacy platform conversion before EU MDR compliance deadlines and OSHA enforcement patterns lock in procurement standards.
For Market Incumbents: Hedge against stainless steel price volatility through backward integration into precision cannula forming capacity or long-term offtake agreements with Baden-Württemberg equipment suppliers. Accelerate RFID-enabled activation logging development to capture United States federal procurement preferences before metropolitan integrated delivery networks finalize vendor consolidation. For New Entrants and Emerging Players: Begin with cost-optimized passive safety platforms targeting Indian outpatient clinic expansion in Maharashtra and Gujarat, where CDSCO regulatory alignment with ISO standards streamlines market access. Capture share in home healthcare self-injection devices for diabetes management, where patient-operated safety requirements create white-space outside established hospital procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision metal forming assets in Germany and Japan during stainless steel margin compression phases, when disposable manufacturers face working capital strain. Monitor EU Green Deal procurement criteria adoption as the inflection signal for single-material recyclable construction premiums over multi-component assemblies.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 23908 Certification Investment | CE marking pathways under EU MDR expand premarket clinical evaluation obligations for passive activation submissions. |
| RFID Activation Logging Integration | OSHA record-keeping automation embeds compliance documentation into United States hospital procurement specifications. |
| Precision Metal Forming Acquisition | Captive supply of cannula forming equipment in Baden-Württemberg insulates against Japanese machine tool lead times. |
| Home Healthcare Device Diversification | Japan's aging population and United States Medicare expansion accelerate demand for autodisabling self-injection platforms. |
| Single-Material Recyclable Construction | EU Green Deal procurement criteria favor polypropylene housings over multi-component assemblies in European tenders. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. FDA 510(k) clearance databases, EU MDR technical documentation submissions, OSHA enforcement records, and ISO standard revision histories provided structured validation. Bottom-up unit shipment estimates triangulated against top-down healthcare expenditure allocations across acute care and outpatient settings.
Segment-level modeling captured product type splits between retractable, passive, shielded, and active mechanisms; application differentiation across blood collection, vaccination, insulin delivery, and infusion therapy; end-user concentration in hospitals, homecare settings, clinics, and research institutes; and material composition trajectories for stainless steel, plastic, silicone, and rubber components. CAGRs derived from regression analysis against infection control protocol adoption curves and regulatory compliance timeline assumptions. Forecast inputs incorporated OSHA enforcement intensity projections, EU MDR transition completion patterns, and nickel price volatility scenarios.
Regulatory harmonization delays, stainless steel commodity price spikes, and group purchasing organization vendor consolidation decisions are the dominant revision risks to shipment and value assumptions. Practitioners should monitor CDSCO alignment progress with ISO 23908, EU notified body review resource allocation toward passive safety submissions, and metropolitan integrated delivery network merger activity for early signals of procurement pattern shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Foley Trays Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Micro Vials Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Pressure Redistribution Pads Market