
 Americas Spandex Market | 2026-2036
Americas Spandex Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Spandex Market Analysis
The U.S. EPA textile waste reduction framework is repositioning spandex demand toward recycled-content and bio-based elastane alternatives. INVISTA leverages its integrated polymer-to-fiber pipeline to supply certified recycled spandex grades across North American apparel mills. HYOSUNG TNC anchors its Americas presence through a dedicated Virginia manufacturing complex serving regional sportswear brands with reduced lead times. The LYCRA Company differentiates via its COOLMAX and THERMOLITE branded fiber platforms that combine spandex with functional moisture-management polymers.
Spandex is a segmented polyurethane fiber typically composed of at least 85% segmented polyurethanes by weight, produced through solution dry spinning or melt extrusion processes that yield filaments with elongation at break exceeding 400% and elastic recovery above 95%. Its primary commercial purpose is to impart controlled stretch and shape retention to woven, knitted, and nonwoven textiles across apparel and medical applications. Raw Fiber and Textiles segments dominate current volume flows, with Raw Fiber capturing the majority of upstream margin pools due to polymer formulation proprietary control. Apparel and Activewear applications are expanding fastest within the End User and Application dimensions, driven by performance-wear specifications requiring higher elastane percentages.
The U.S. FTC's Textile Fiber Products Identification Act shapes spandex labeling compliance and enforcement actions across imported and domestic finished goods. Brazil's ANVISA medical device regulations govern spandex-containing compression garments and therapeutic hosiery sold through clinical channels. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York that could impose fiber-recovery obligations on elastane suppliers.
Market Dynamics
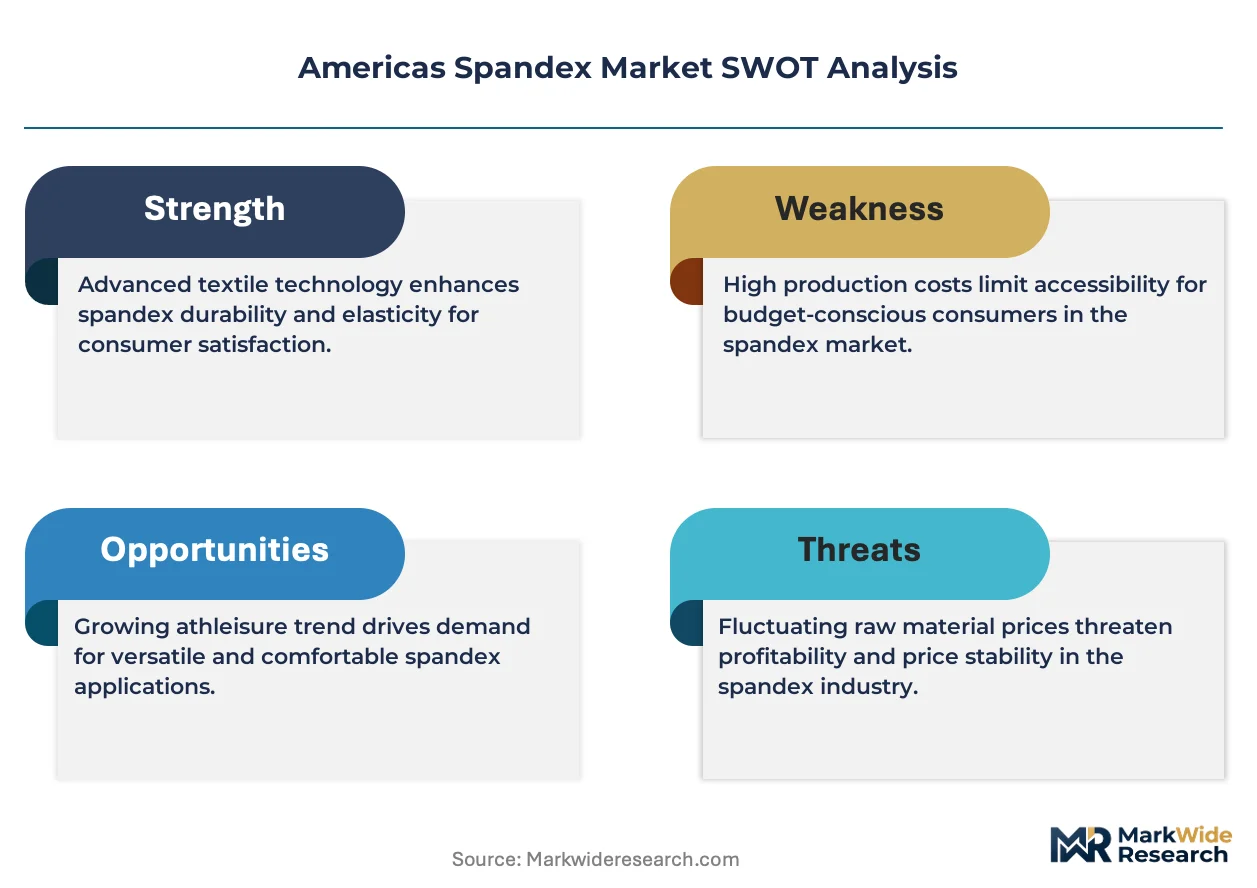
Spandex demand across the Americas is undergoing a structural pivot as the U.S. EPA textile waste reduction framework redirects procurement toward recycled-content and bio-based elastane alternatives. This regulatory pressure is compressing lead times for certified fiber grades while reshaping supplier qualification criteria across North American apparel mills.
Growth Catalysts
- Activewear specification escalation:Sportswear brands are elevating elastane percentages in compression garments and performance base layers, creating sustained volume pull from Brazilian and U.S. manufacturing clusters.
- Medical channel expansion:ANVISA-regulated therapeutic hosiery and compression garment categories in Brazil are absorbing higher spandex content as clinical distribution deepens.
- Recycled fiber certification:The U.S. FTC's tightened Textile Fiber Products Identification Act enforcement is accelerating mill-level demand for certified recycled spandex grades with verified chain-of-custody documentation.
Market Restraints
- Polymer feedstock concentration:MDI and PTMEG supply for polyurethane elastane production concentrates among Asian chemical producers, exposing Americas-based fiber manufacturers to input cost volatility and freight exposure.
- Mechanical recycling limitations:Current thermomechanical reprocessing technologies degrade spandex polymer chains below virgin-grade performance thresholds, constraining closed-loop circularity claims.
- Extended producer responsibility uncertainty:Draft state-level EPR legislation in California and New York threatens to impose fiber-recovery obligations on elastane suppliers without established collection infrastructure.
Strategic Opportunities
- Bio-based elastane R&D:Fermentation-derived diol precursors and plant-based polyols are advancing toward commercial scale, offering regulatory-compliant pathways for brands targeting California's SB 54 plastic pollution reduction mandates.
- Regional manufacturing densification:Virginia-based production complexes are capturing sportswear brand relationships through reduced ocean freight exposure and faster replenishment cycles versus Asian supply alternatives.
- Medical-grade fiber specialization:ANVISA-registered compression garment producers in São Paulo state present untapped demand for high-tenacity, biocompatible spandex grades with documented cytotoxicity testing.
Industry Challenges
- Polymer formulation expertise scarcity:Segmented polyurethane chemistry specialization concentrates among legacy fiber producers, constraining new entrant capacity expansion and quality consistency.
- Multi-jurisdictional labeling compliance:Divergent U.S. FTC, Health Canada, and Brazil ANVISA fiber-content disclosure requirements force SKU proliferation and testing cost multiplication for cross-border apparel brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Spandex Market |
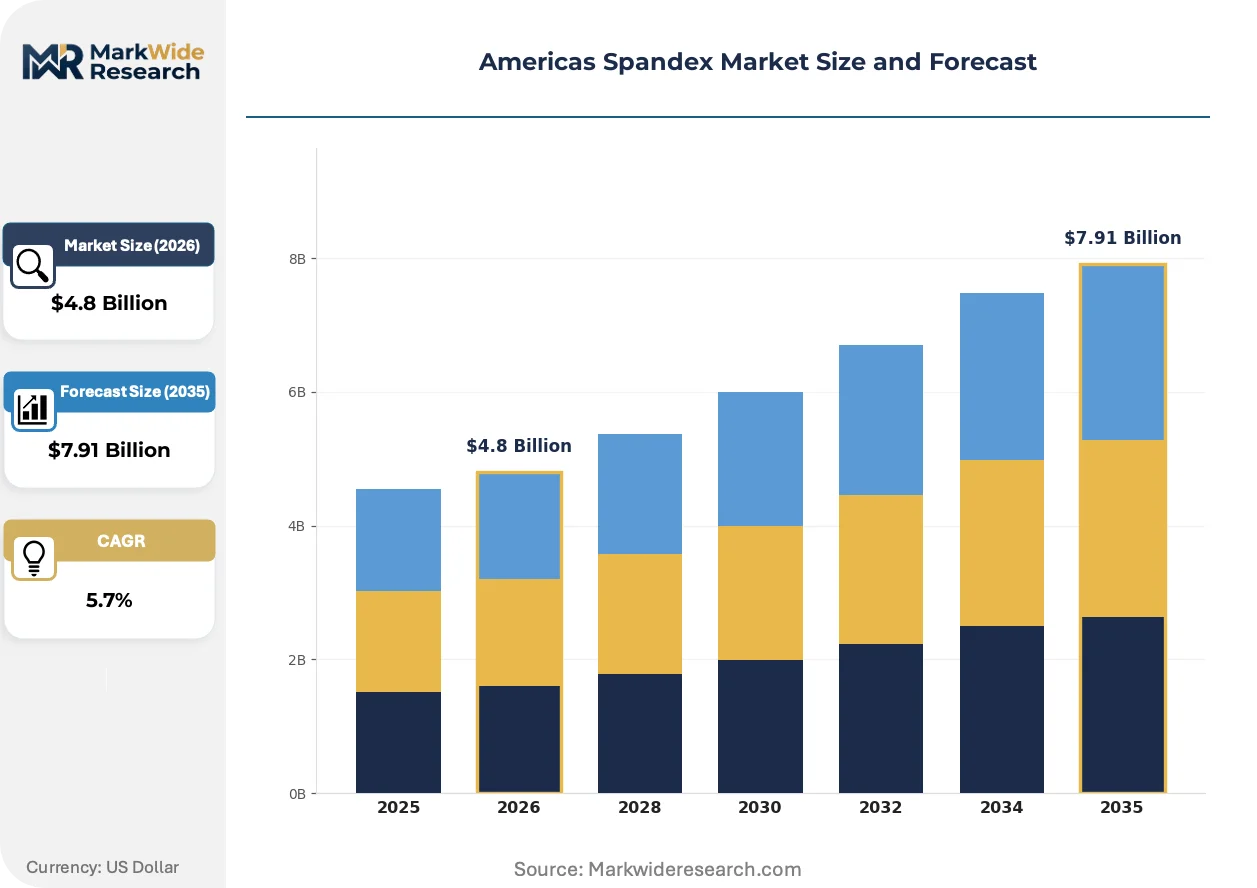
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Fiber, Textiles, Fabrics, Apparel End User: Fashion, Sportswear, Underwear, Medical Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Activewear, Swimwear, Hosiery, Loungewear |
| Companies Covered | INVISTA, DuPont de Nemours, Inc., HYOSUNG TNC, Asahi Kasei Corporation, TK Chemical Corp., Taekwang Industrial Co. Ltd., The LYCRA Company, Mitsubishi Chemical Corporation, Indorama Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Spandex Market Emerging Trajectories
Solution dry spinning technology is losing its historical dominance as melt extrusion and alternative polymerization methods advance. These process innovations are compressing capital requirements and enabling regional production footprints closer to end-use demand centers.
Bio-based polyurethane feedstocks derived from agricultural waste streams are decentralizing raw material sourcing for spandex manufacturers. Apparel mills in the U.S. Southeast and São Paulo state are piloting these grades at 15-20% blend ratios. The technology is decentralizing supply chain risk concentration away from petrochemical hubs toward distributed biorefinery networks.
The U.S. FTC's textile labeling enforcement actions are tightening disclosure requirements for elastic fabric content claims. Apparel brands now face civil penalties for overstated recycled content or undisclosed fiber blends. U.S.-imported activewear SKUs are most affected, with brands accelerating third-party certification adoption to preempt enforcement exposure.
Direct-to-mill procurement contracts are displacing traditional distributor intermediaries for volume spandex buyers. Large North American sportswear brands are negotiating polymer-to-fiber supply agreements with integrated producers, compressing margin capture for independent traders. This pattern is most visible in compression garment supply chains serving the U.S. and Brazilian markets.
Americas Spandex Market Segmentation
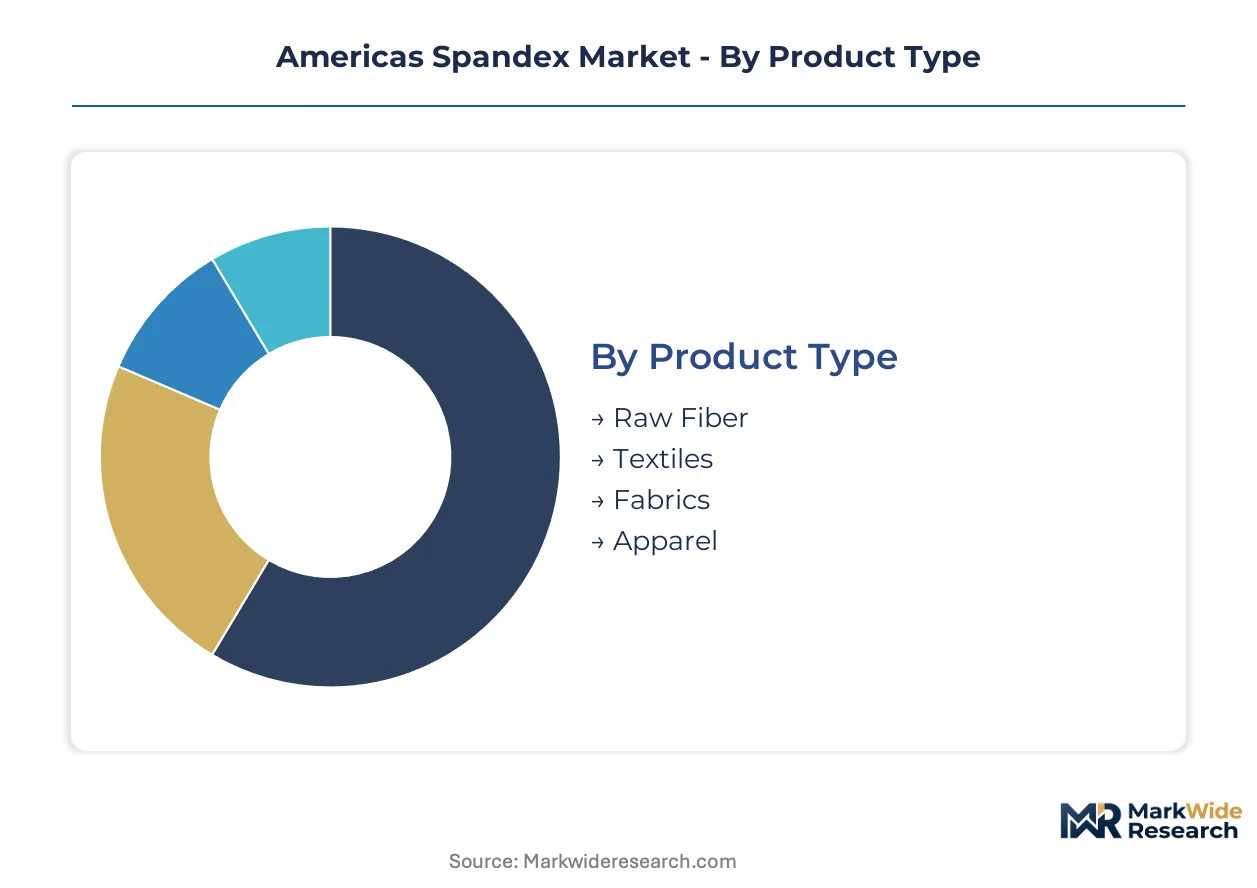
Segmentation in the Americas Spandex Market reveals divergent margin structures and specification requirements across fiber formats and end-use channels. Understanding these divides allows suppliers to align polymer formulation investments with the highest-return demand pockets.
Product Type:
Standardization dominates upstream segments where polymer chemistry is fixed, while downstream categories allow increasing customization through blend ratios and finishing treatments.
- Raw Fiber:Virgin and recycled spandex filaments produced through solution dry spinning or melt extrusion, containing minimum 85% segmented polyurethanes by weight with elongation exceeding 400%. Demand concentrates in North American apparel mills serving sportswear brands with FTC-compliant fiber-content disclosure requirements compressing lead times for certified grades.
- Textiles:Knitted and woven fabrics integrating spandex with cotton, polyester, or nylon for controlled stretch and recovery. Brazilian manufacturing clusters in São Paulo state absorb rising volumes for local activewear production as domestic apparel brands expand elastane percentages.
- Fabrics:Finished textile substrates ready for garment cutting, spanning single-jersey, interlock, and tricot constructions. Medical device producers source ANVISA-registered compression fabric grades for therapeutic hosiery applications.
- Apparel:Cut-and-sewn finished goods where spandex content varies by garment type and performance specification. Direct-to-mill procurement contracts are displacing distributor intermediaries for volume buyers in this segment.
Leading the category by volume: Raw Fiber. Growing fastest: Apparel.
End User:
Cost tiers separate commodity-driven volume segments from premium channels where technical certification and brand positioning command margin premiums.
- Fashion:Ready-to-wear and fast-fashion applications using 2-5% spandex blends for comfort stretch. Brazilian and U.S. mass-market retailers drive volume through seasonal replenishment cycles with compressed lead time requirements.
- Sportswear:Performance garments with 15-30% elastane content in compression base layers and athletic tights. Virginia-based manufacturing complexes capture brand relationships through reduced ocean freight exposure versus Asian supply alternatives.
- Underwear:Intimate apparel requiring soft hand-feel and durable recovery through repeated laundering. Mills in the U.S. Southeast pilot bio-based polyurethane grades at 15-20% blend ratios to meet emerging sustainability procurement criteria.
- Medical:ANVISA-regulated compression garments and therapeutic hosiery with documented cytotoxicity testing and biocompatibility certification. São Paulo state clinical distribution channels absorb higher spandex content as healthcare access deepens.
Volume leadership: Fashion. Steepest expansion trajectory: Sportswear.
Distribution Channel:
Customer type and purchase scale determine channel selection, with procurement patterns diverging between fragmented small-lot buyers and consolidated volume accounts.
- Online Retail:Direct-to-consumer platforms for finished spandex apparel, where U.S. FTC labeling enforcement actions target imported activewear SKUs with overstated recycled content claims.
- Supermarkets:Mass-market hosiery and basic underwear through grocery and big-box retail chains, concentrated in price-sensitive Brazilian and U.S. consumer segments.
- Specialty Stores:Premium sportswear and performance boutiques where technical fiber branding (COOLMAX, THERMOLITE) supports price positioning.
- Wholesale:Business-to-business fiber and fabric distribution, facing margin compression as integrated producers negotiate polymer-to-fiber supply agreements directly with large North American brands.
Fastest-growing channel: Online Retail. Dominant by transaction volume: Wholesale.
Application:
Maturity gradients separate established categories with fixed specifications from emerging segments where performance innovation drives specification escalation.
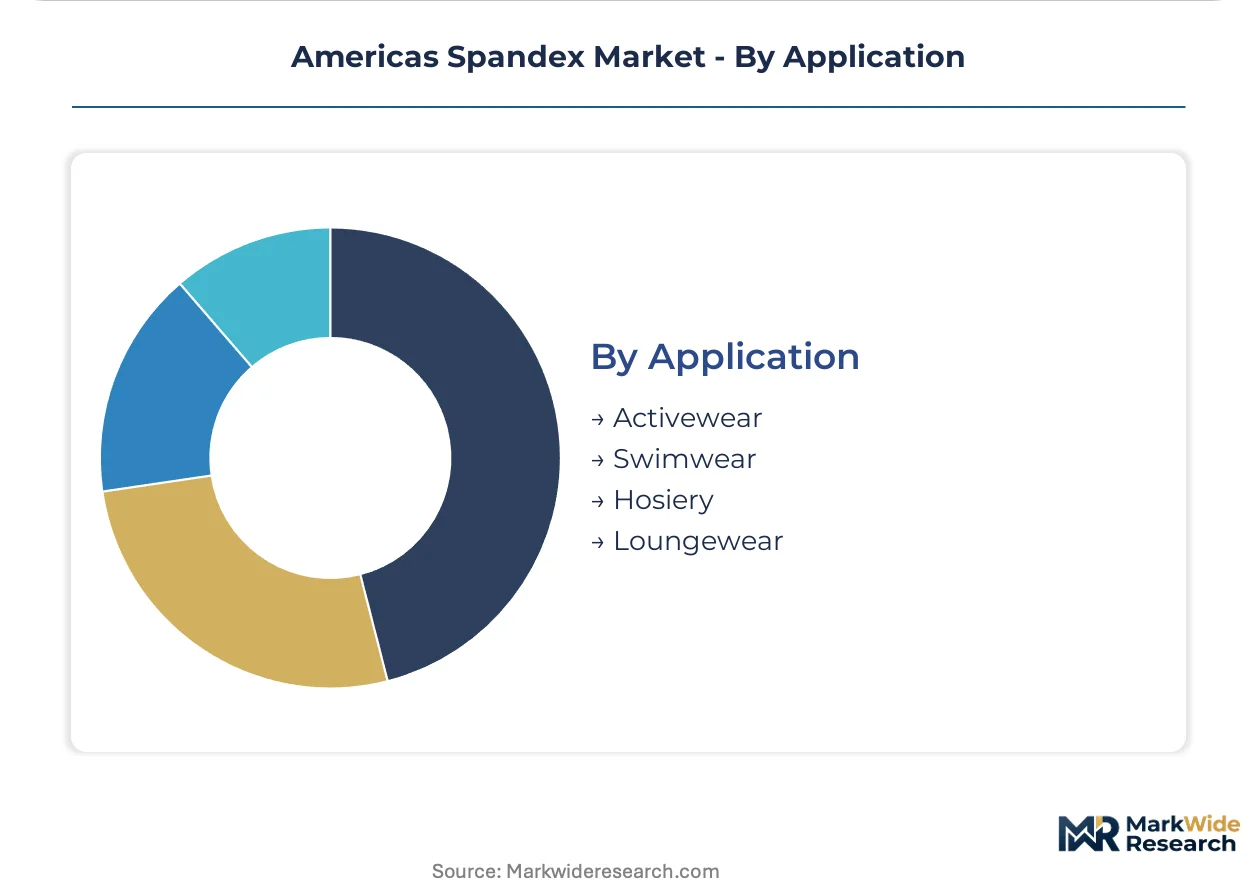
- Activewear:Compression garments and performance base layers with elevated elastane percentages, where U.S. and Brazilian manufacturing clusters compete on lead time and certification compliance.
- Swimwear:Chlorine-resistant spandex blends for competitive and recreational aquatic apparel, requiring UV degradation resistance and saltwater durability specifications.
- Hosiery:Sheer and opaque tights with graduated compression profiles, concentrated in ANVISA-regulated Brazilian therapeutic channels and U.S. clinical distribution.
- Loungewear:Comfort-oriented stretch fabrics for work-from-home and casual segments, where pandemic-era demand shifts have stabilized into sustained category expansion.
Gaining share fastest: Activewear. Mature volume base: Hosiery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's apparel manufacturing corridor anchors spandex consumption across the Americas, with domestic mills sourcing increasing fiber volumes for compression garment and activewear production serving Brazilian and export markets.
United States
Virginia-based manufacturing complexes capture sportswear brand relationships through reduced ocean freight exposure versus Asian supply alternatives. The U.S. FTC's Textile Fiber Products Identification Act shapes labeling compliance and enforcement actions across imported and domestic finished goods. Mills in the U.S. Southeast pilot bio-based polyurethane grades at 15-20% blend ratios to meet emerging sustainability procurement criteria.
Brazil
ANVISA-regulated therapeutic hosiery and compression garment categories absorb higher spandex content as clinical distribution deepens across São Paulo state. Brazil's ANVISA medical device regulations govern spandex-containing compression garments sold through clinical channels. São Paulo state manufacturing clusters source increasing volumes of spandex fiber for local activewear production as domestic apparel brands expand.
Canada
Health Canada fiber-content disclosure requirements force SKU proliferation and testing cost multiplication for cross-border apparel brands serving North American markets. The country's textile labeling standards align with U.S. FTC frameworks while maintaining distinct bilingual disclosure mandates. Ontario-based apparel distributors manage compliance complexity for brands operating across the U.S.-Canada border.
Mexico
Nearshoring apparel production for U.S. sportswear brands elevates spandex demand in northern border states and central Mexico manufacturing corridors. The country's proximity advantages compress replenishment cycles for North American activewear supply chains. Guanajuato and Puebla textile clusters integrate spandex into denim and knitwear exports serving U.S. mass-market retailers.
Americas Spandex Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and polymer formulation capabilities. Integrated producers with captive polymer-to-fiber pipelines capture upstream margin pools through proprietary segmented polyurethane chemistry control. Three archetypes dominate: chemical conglomerates with diversified elastomer portfolios, specialized fiber producers with branded technology platforms, and regional manufacturers leveraging geographic proximity. Capacity expansion and direct-to-mill procurement contracts constitute the dominant competitive moves reshaping distributor intermediation.
Among integrated chemical producers, INVISTA, HYOSUNG TNC, and The LYCRA Company exemplify contrasting geographic and technological positioning. INVISTA represents North American-anchored supply chain integration with certified recycled fiber grades. HYOSUNG TNC occupies a position as a Korea-origin producer with dedicated Virginia manufacturing infrastructure. The LYCRA Company sits within the branded fiber platform tier, combining spandex with functional moisture-management polymer technologies.
| Leading Market Players |
|---|
| INVISTA |
| DuPont de Nemours, Inc. |
| HYOSUNG TNC |
| Asahi Kasei Corporation |
| TK Chemical Corp. |
| Taekwang Industrial Co. Ltd. |
| The LYCRA Company |
| Mitsubishi Chemical Corporation |
| Indorama Industries Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FTC-compliant recycled spandex and uncertified commodity grades creates divergent margin pools that reshape both supplier qualification costs and procurement contract structures across North American apparel mills.
Pricing Analysis
Value-based pricing anchors on verified chain-of-custody documentation for recycled-content grades, with contract-based long-term offtake agreements dominating volume relationships between integrated producers and sportswear brands. Price differentiation rests on certification level and volume scale, with ANVISA-registered medical grades commanding premiums over fashion-tier blends. Cost compression in commodity virgin fiber is intensifying because Asian MDI and PTMEG feedstock volatility transmits downstream. Mass-market fashion retailers exhibit highest price sensitivity, while medical device producers demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
MDI and PTMEG supply for polyurethane elastane production rests on South Korea, China, and Japan as the dominant specialty chemical sources. Raw material dependencies center on petrochemical-derived diisocyanates, polyether glycols, and chain extenders. Single-source vulnerability concentrates in Asian polymer precursor manufacturing, exposing Americas-based fiber producers to freight cost volatility and tariff exposure. Distribution runs through direct-to-mill procurement contracts displacing traditional wholesale intermediaries for large North American sportswear brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas spandex market functions as a cost-of-compliance story where the U.S. FTC's Textile Fiber Products Identification Act enforcement creates a barrier-to-entry moat for suppliers with verified certification infrastructure.
For Market Incumbents: Deepen captive polymer-to-fiber pipeline control through backward integration into MDI precursor supply or regional compounding capacity in Virginia. Defend margin position against emerging bio-based elastane entrants by accelerating ANVISA-registered medical-grade fiber specialization. Certification investment represents the critical lever for sustaining premium positioning. For New Entrants and Emerging Players: Regional manufacturing clusters in São Paulo state present the most penetrable white-space target given ANVISA-registered compression garment demand growth and limited local high-tenacity fiber supply. Bio-based polyurethane R&D partnerships with U.S. Southeast apparel mills offer a defensible go-to-market angle through California SB 54 compliance positioning. For Investors and Strategic Acquirers: Re-rating potential sits with integrated producers possessing captive recycled-content certification and direct-to-mill brand relationships given tightening FTC enforcement and brand sustainability mandates. Long-term viability favors polymer formulation specialists with demonstrated cytotoxicity testing capabilities. Watch ANVISA regulatory harmonization with U.S. FDA medical device frameworks as the inflection signal for medical-grade fiber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursors | Captive MDI and PTMEG supply shields Virginia-based fiber producers from Asian feedstock volatility. |
| Recycled-Content Certification Program | FTC-compliant chain-of-custody documentation secures direct-to-mill contracts with North American sportswear brands. |
| ANVISA Medical Device Registration | Biocompatibility certification unlocks São Paulo state therapeutic hosiery and compression garment channels. |
| Bio-Based Polyurethane R&D Partnership | Fermentation-derived diol development aligns with California SB 54 plastic pollution reduction procurement criteria. |
| Regional Manufacturing Densification | Virginia production expansion captures replenishment cycle advantages versus Asian supply alternatives. |
Methodological Framework
Independent corroboration across fiber producer technical directors, apparel mill procurement leads, and ANVISA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with sportswear brand sustainability officers, chemical distribution channel partners, and medical device quality managers combined with secondary validation from U.S. FTC enforcement records, Brazilian customs trade data, and SEC chemical company filings. Bottom-up volume modeling and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical fiber shipment data and apparel production indices established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product type, end user category, distribution channel, and application with regional production cluster overlays. CAGRs derive from trend extrapolation adjusted for regulatory inflection points. Key inputs incorporate polymer feedstock cost trajectories and certification adoption curves.
Several conditions sit outside the modeled scope, including unforeseen tariff regime shifts, breakthrough mechanical recycling technologies, and state-level extended producer responsibility legislation outcomes. Forecasts reflect documented assumptions about FTC enforcement intensity and ANVISA harmonization timelines. Supply disruption in Asian MDI production, bio-based precursor commercialization delays, and medical device reimbursement policy changes warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market