
 Sic Fibers Market | 2026-2036
Sic Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Sic Fibers Market Intelligence
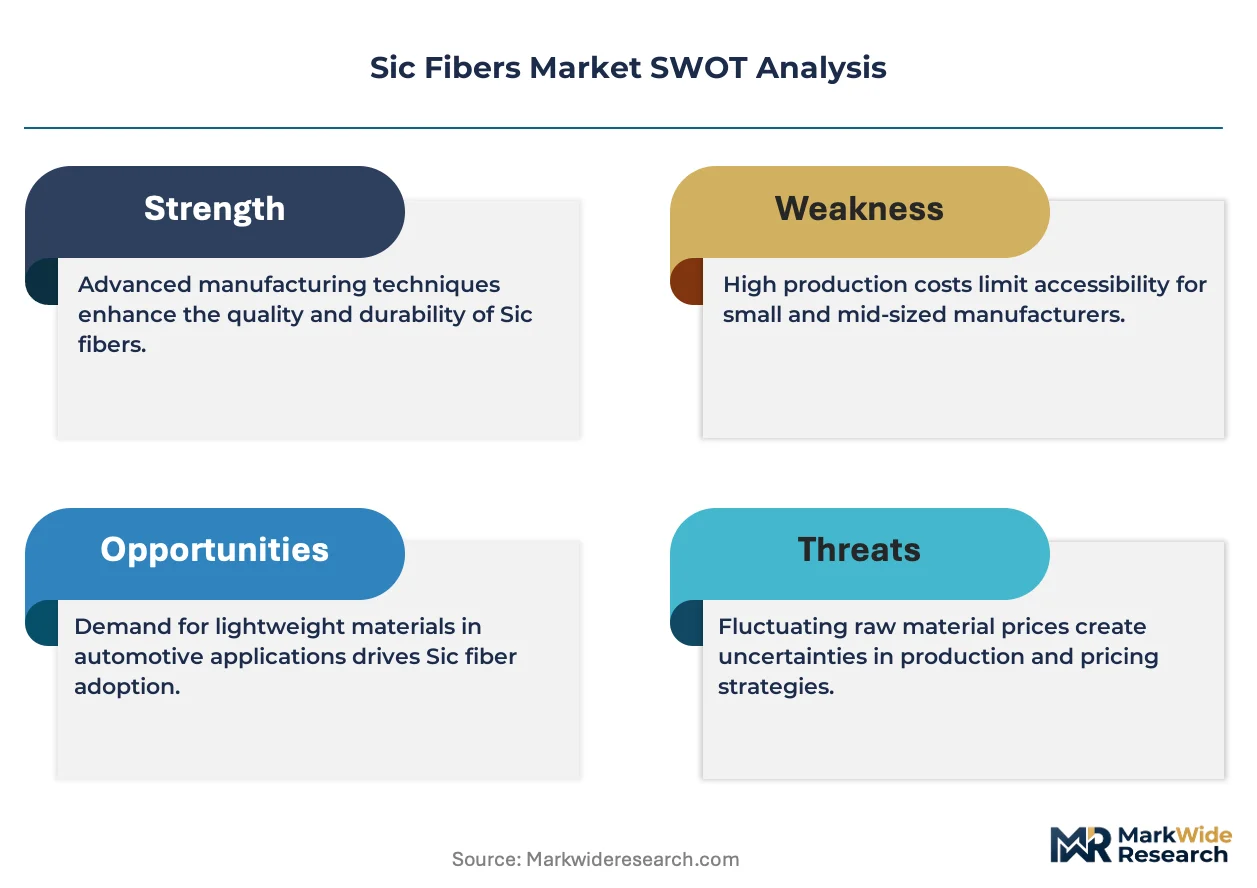
REACH compliance is rebalancing the cost-of-entry calculus for European SiC fiber suppliers, forcing reformulation of precursor chemistries and third-party certification spend. NGS Advanced Fibers Co., Ltd. leverages its vertically integrated precursor-to-fiber production to sustain margin control amid regulatory escalation. Specialty Materials, Inc. anchors North American supply security through domestic chemical vapor deposition capacity. UBE Corporation competes on polymeric precursor purity, differentiating its feedstock for aerospace-grade continuous fiber output.
SiC fibers are polycrystalline or amorphous ceramic filaments composed primarily of silicon carbide, typically manufactured via chemical vapor deposition onto carbon or tungsten cores or through polymer-derived ceramic routes involving pyrolysis of polycarbosilane precursors at temperatures exceeding 1,000°C; they deliver exceptional thermal stability, oxidation resistance, and strength-to-weight ratios for structural reinforcement in extreme environments. Continuous fiber forms command premium positioning in aerospace hot-section components where creep resistance under sustained thermal load determines component life. Chopped fiber segments serve industrial furnace lining and automotive brake applications where shorter fiber lengths reduce material cost while maintaining adequate thermal shock performance. Woven and fabric architectures concentrate margin pools in defense contractor supply chains requiring bespoke preform geometries for ceramic matrix composite infiltration.
FAA airworthiness standards for ceramic matrix composite engine components, EU ETS aviation emissions benchmarks, and Japan's METI industrial technology roadmaps collectively shape product qualification timelines and end-user procurement specifications across major manufacturing jurisdictions. China's GB standards for advanced ceramics and MIIT new materials industry plans further condition market access for imported SiC fiber products. Stakeholders must monitor evolving precursor chemical classifications under ECHA and EPA frameworks, as regulatory reclassification would cascade through certification requirements and customer qualification protocols.
Market Dynamics
FAA engine efficiency mandates are compressing qualification timelines for ceramic matrix composite components, forcing fiber suppliers to synchronize precursor chemistry development with airworthiness certification cycles rather than traditional materials innovation schedules.
Growth Catalysts
- CMC Substitution Mandates:FAA airworthiness standards for turbine hot-section components are accelerating displacement of nickel superalloys in next-generation propulsion systems, creating pull-through demand for continuous fiber architectures.
- Defense Procurement Concentration:United States military aviation programs are consolidating supplier qualifications around domestic chemical vapor deposition capacity, locking in multi-year offtake agreements for aerospace-grade filament.
- REACH Precursor Reformulation:ECHA chemical classifications are compelling European suppliers to redesign polycarbosilane synthesis pathways, opening qualification windows for compliant feedstock producers.
Market Restraints
- Polycarbosilane Supply Concentration:Precursor manufacturing clusters in Japan and Germany create input vulnerability for non-integrated fiber producers lacking captive pyrolysis feedstock.
- Pyrolysis Energy Intensity:Furnace operations exceeding 1,000°C require sustained electricity inputs that expose margin structures to European industrial power pricing volatility.
- Carbon Core Availability:Specialized carbon filament substrates for chemical vapor deposition routes face allocation constraints from aerospace carbon fiber producers prioritizing composite laminate output.
Strategic Opportunities
- Industrial Furnace Retrofit Cycles:Japanese METI industrial technology roadmaps are incentivizing high-temperature kiln lining replacements, creating demand for chopped fiber thermal shock applications.
- Automotive Brake System Adoption:Copper-free friction material mandates from EPA and state-level regulations are positioning silicon carbide reinforcement as a performance-compliant substitute in heavy-duty vehicle braking.
- Additive Manufacturing Convergence:Ceramic matrix composite three-dimensional printing is integrating chopped fiber feedstock with binder jetting platforms, enabling near-net-shape preform production for complex turbine geometries.
Industry Challenges
- Materials Scientist Talent Scarcity:Polymer-derived ceramic expertise resides in limited academic and industrial clusters, constraining scale-up velocity for new precursor-to-fiber production lines.
- Customer Qualification Duration:Aerospace OEM validation protocols for continuous fiber lots extend eighteen to thirty-six months, freezing working capital in inventory before revenue recognition.
- Cross-Jurisdictional Certification Complexity:Parallel FAA, EASA, and CAAC airworthiness submissions require redundant testing campaigns, multiplying compliance expenditure for global fiber suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sic Fibers Market |
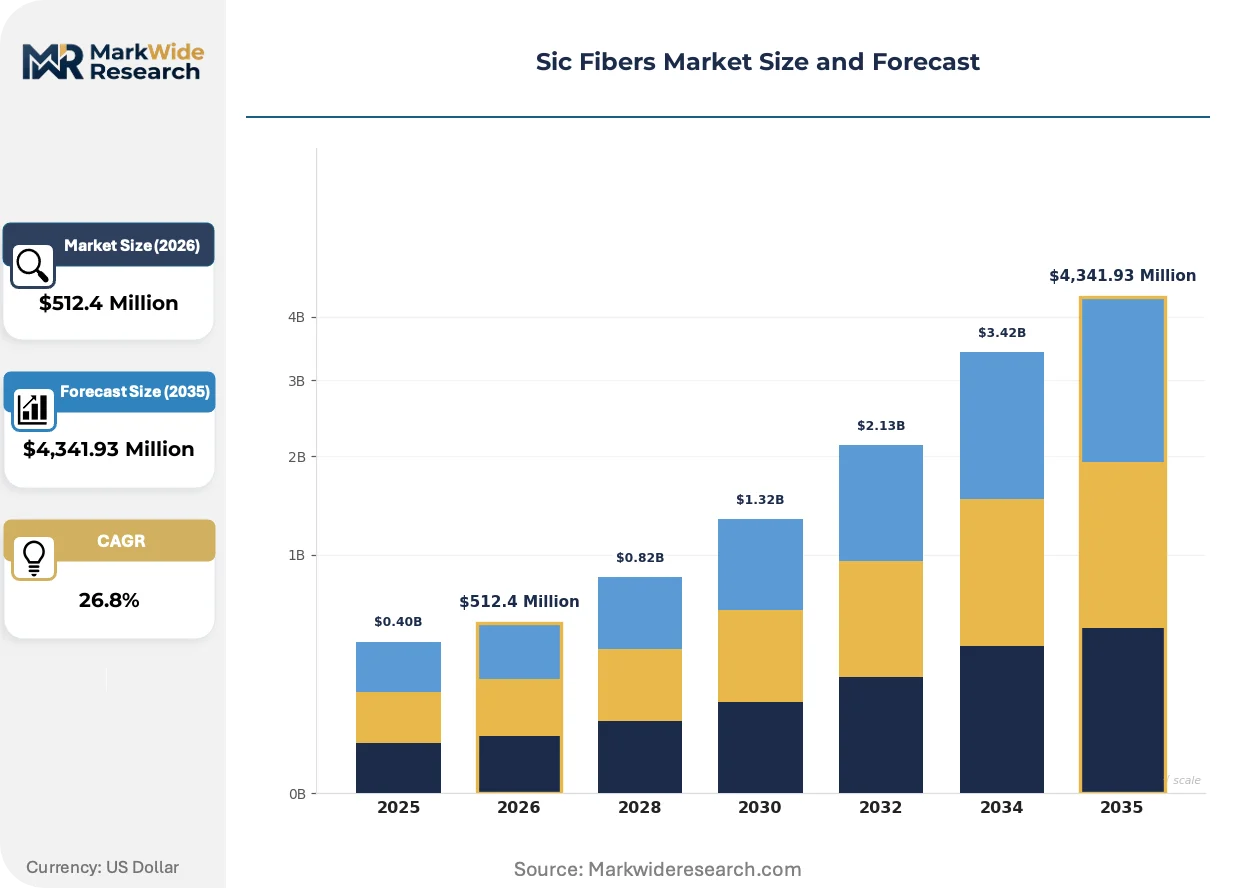
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $4,341.93 Million |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sic Fiber Yarns, Sic Fiber Fabrics, Sic Fiber Mats, Sic Fiber Reinforcement Application: Aerospace, Automotive, Industrial, Electronics End User: Aerospace Manufacturers, Automotive OEMs, Defense Contractors, Chemical Processing Form: Continuous, Chopped, Woven, Non-woven |
| Companies Covered | NGS Advanced Fibers Co., Ltd., Specialty Materials, Inc., UBE Corporation, COI Ceramics, Inc., American Elements, BJS Ceramics GmbH, Matech, Suzhou Saifei Group Ltd., GE Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sic Fibers Market Strategic Shifts & Innovations
Silicon carbide fiber manufacturing is bifurcating between chemical vapor deposition precision routes for aerospace hot-section components and polymer-derived ceramic scale paths for industrial thermal management applications, with process selection increasingly determined by end-use certification requirements rather than unit economics alone.
Near-stoichiometric chemical vapor deposition filament is integrating tungsten-core substrate technology with refined silicon carbide lattice structures to achieve creep resistance thresholds demanded by next-generation turbine blade inserts. Aerospace OEMs in the United States are qualifying these architectures under accelerated FAA timelines. This integration is compressing the supplier base to producers with in-house precursor synthesis and deposition capacity.
REACH precursor reclassification is forcing reformulation of polycarbosilane chemistries to eliminate chlorinated solvent residues from traditional synthesis pathways. European suppliers face third-party certification expenditure before market access restoration. Chopped fiber segments serving industrial furnace applications are absorbing the steepest compliance cost escalation.
Defense contractor procurement is consolidating around domestic qualified suppliers with captive chemical vapor deposition infrastructure, displacing spot-market purchasing for continuous fiber lots. Long-term agreements now specify volume floors and technical audit rights rather than transactional pricing. This pattern concentrates most visibly in United States military aviation supply chains.
Sic Fibers Market Segmentation
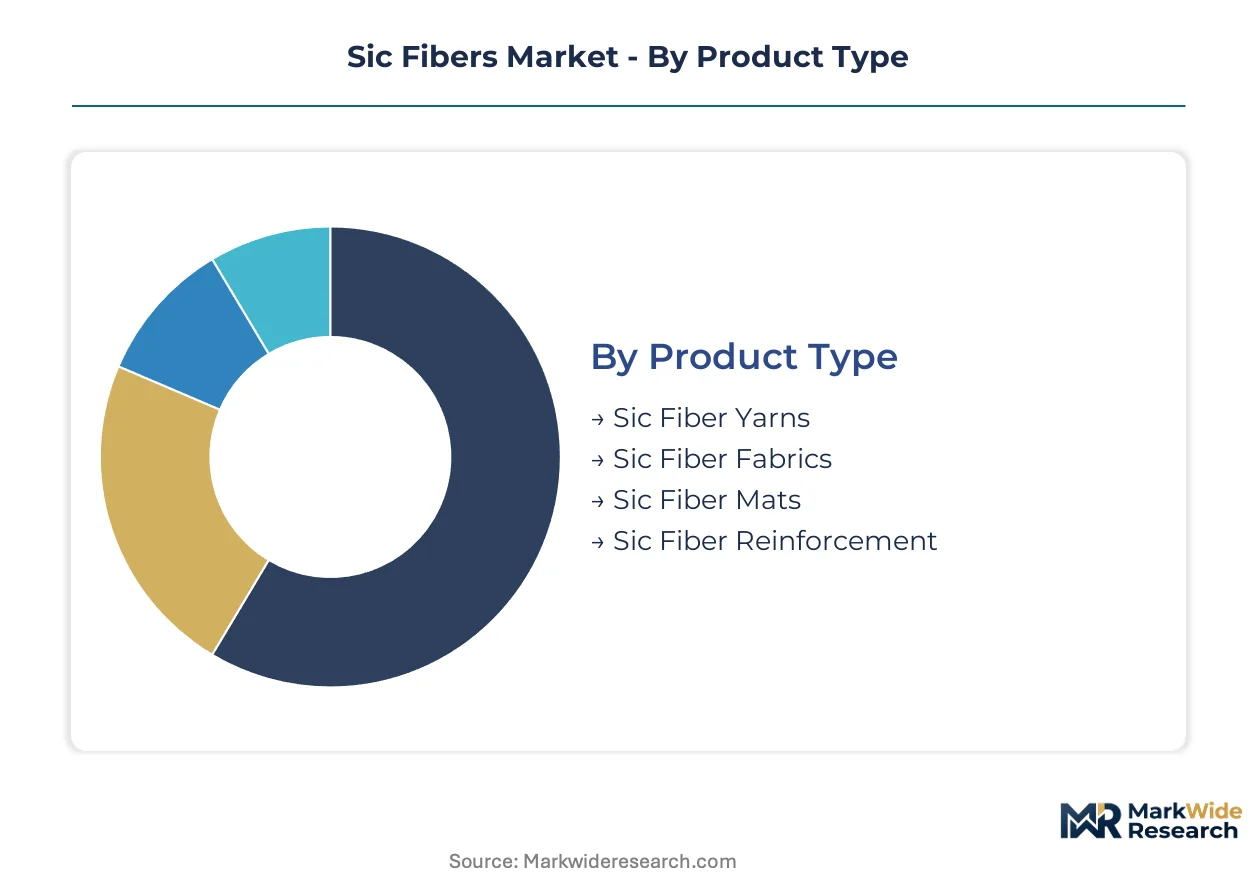
SiC fiber producers configure product architectures around certification requirements and thermal load specifications. Segment selection determines furnace investment scale, precursor chemistry pathways, and customer qualification timelines.
Product Type:
Chemical vapor deposition capacity requirements vary sharply across product architectures, with continuous filament routes demanding the steepest capital deployment.
- Sic Fiber Yarns:Continuous filament bundles spun from chemical vapor deposition or polymer-derived ceramic routes. Aerospace hot-section component manufacturers in the United States specify these for turbine blade reinforcement under accelerated FAA qualification timelines.
- Sic Fiber Fabrics:Woven architectures produced on modified carbon fiber looms with ceramic-compatible tension controls. Defense contractor preform specifications in the United States absorb the bulk of premium fabric output for ceramic matrix composite infiltration.
- Sic Fiber Mats:Non-woven entangled structures for furnace lining and thermal barrier applications. Japanese METI industrial technology roadmaps are incentivizing kiln retrofit demand.
- Sic Fiber Reinforcement:Chopped and milled segments for polymer matrix and metal matrix composite integration. EPA copper-free brake friction mandates are opening automotive offtake channels.
Sic Fiber Yarns absorb the bulk of installed capacity; Sic Fiber Reinforcement is expanding most quickly.
Application:
End-use thermal environments dictate fiber purity thresholds and architecture selection, with sustained load requirements filtering supplier capabilities.
- Aerospace:Turbine hot-section components and combustor liners requiring creep resistance above 1,200°C. FAA engine efficiency mandates are compressing qualification cycles for ceramic matrix composite substitution of nickel superalloys.
- Automotive:Friction materials and exhaust system components leveraging thermal shock resistance. State-level copper-free brake regulations are positioning SiC as a compliant reinforcement alternative.
- Industrial:High-temperature furnace linings and kiln furniture for steel and ceramics processing. Japanese industrial energy efficiency standards are accelerating lining replacement cycles.
- Electronics:Semiconductor processing fixtures and thermal management substrates. Cleanroom-compatible fiber grades command qualification premiums.
Aerospace commands the deepest supplier integration; Automotive is climbing the fastest as friction material compliance deadlines approach.
End User:
Procurement concentration patterns separate long-term qualification partnerships from spot-market volume purchasing.
- Aerospace Manufacturers:Commercial aviation OEMs with multi-year ceramic matrix composite roadmaps. United States-based producers dominate qualified supplier lists for next-generation propulsion programs.
- Automotive OEMs:Heavy-duty vehicle brake system suppliers and exhaust component manufacturers. Tier-1 friction material producers are qualifying SiC grades for copper-free formulations.
- Defense Contractors:Military aviation and hypersonic vehicle programs with captive supply chain security requirements. Domestic chemical vapor deposition capacity anchors United States procurement specifications.
- Chemical Processing:Reactor vessel and heat exchanger fabricators requiring corrosion-resistant reinforcement. Specialty corrosion grades absorb smaller volume pools.
Defense Contractors lock in the longest agreement structures; Automotive OEMs are gaining share fastest as brake regulation deadlines compress.
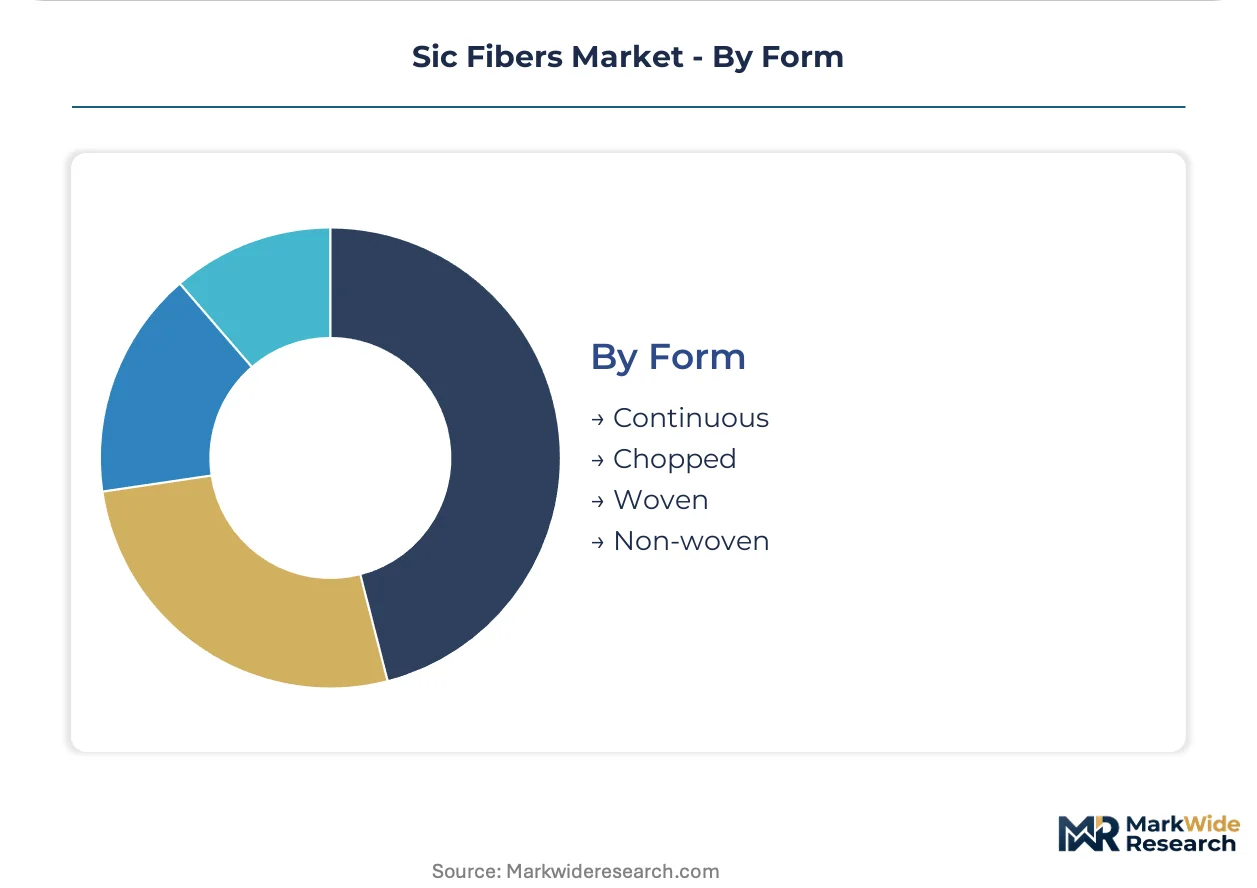
Form:
Physical architecture determines precursor conversion yield and downstream processing compatibility.
- Continuous:Uninterrupted filament lengths for structural composite preforms. Aerospace hot-section applications in the United States specify these for creep-critical turbine components.
- Chopped:Short-cut segments for thermoset and thermoplastic matrix dispersion. Binder jetting additive manufacturing platforms are integrating these for near-net-shape ceramic matrix composite preforms.
- Woven:Fabric architectures from modified carbon fiber looms. Bespoke preform geometries for defense contractor ceramic matrix composite infiltration concentrate margin pools.
- Non-woven:Entangled mat structures for thermal insulation and filtration. Industrial furnace lining retrofits in Japan absorb steady volume.
Continuous forms tie up the most working capital in qualification inventory; Chopped fiber is expanding most quickly through additive manufacturing convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Carolina and Alabama concentrate aerospace-grade chemical vapor deposition capacity, attracting defense contractor procurement offices and FAA certification laboratories into tax-advantaged manufacturing corridors.
United States
Defense procurement and commercial aviation programs drive premium fiber offtake, with military aviation supply chains consolidating around domestic qualified suppliers. FAA engine efficiency mandates compress qualification timelines for ceramic matrix composite components. Greenville-Spartanburg anchors chemical vapor deposition infrastructure serving turbine hot-section applications.
Japan
Industrial furnace retrofit cycles and METI technology roadmaps create demand for chopped fiber thermal shock applications. Polymeric precursor purity standards differentiate feedstock for aerospace-grade continuous fiber output. Nagoya-Osaka corridor hosts vertically integrated precursor-to-fiber production facilities.
Germany
REACH compliance obligations force reformulation of polycarbosilane precursor chemistries and third-party certification expenditure. Pyrolysis energy intensity exposes margin structures to industrial power pricing volatility. Bavaria and North Rhine-Westphalia concentrate ceramic matrix composite research clusters.
China
GB standards for advanced ceramics and MIIT new materials industry plans condition market access for imported SiC fiber products. Domestic precursor manufacturing capacity expands to reduce input vulnerability. Yangtze River Delta hosts emerging chemical vapor deposition facilities for aerospace qualification.
United Kingdom
Defense contractor supply chains require bespoke preform geometries for ceramic matrix composite infiltration, concentrating woven fabric margin pools. EASA parallel certification requirements multiply compliance expenditure for suppliers serving European aerospace OEMs. Midlands region maintains specialty ceramics research infrastructure.
Sic Fibers Market Key Industry Players
United States producers anchor one tier; Japanese specialists hold precursor chemistry dominance. The supplier base compresses around three structural positions: vertically integrated precursor-to-fiber manufacturers, domestic chemical vapor deposition capacity holders, and polymeric precursor purity specialists. Consolidation accelerates through long-term offtake agreements with volume floors and technical audit rights, while REACH-driven reformulation opens qualification windows for compliant feedstock producers.
Within the integrated manufacturing tier, NGS Advanced Fibers Co., Ltd. exemplifies captive precursor synthesis and deposition capacity. Specialty Materials, Inc. represents North American supply security positioning through domestic infrastructure. UBE Corporation occupies the polymeric precursor specialization vector, differentiating feedstock purity for aerospace-grade output.
| Leading Market Players |
|---|
| NGS Advanced Fibers Co., Ltd. |
| Specialty Materials, Inc. |
| UBE Corporation |
| COI Ceramics, Inc. |
| American Elements |
| BJS Ceramics GmbH |
| Matech |
| Suzhou Saifei Group Ltd. |
| GE Aerospace |
| Others |
Cost & Logistics Intelligence
EPA copper-free brake friction mandates gate qualified supply access and premium-tier pricing for automotive-grade chopped fiber, compressing margin pools for non-compliant producers while concentrating pricing power among REACH-certified European suppliers and domestic CVD capacity holders in the United States.
Pricing Analysis
Lead-time-driven pricing stratification rewards aerospace OEMs securing eighteen-to-thirty-six-month qualified inventory with contract stability, while spot-market continuous fiber lots trade at volatility premiums reflecting pyrolysis energy cost exposure. Three-tier pricing structure across aerospace-qualified, industrial-grade, and automotive-compliant levels separates fiber purity thresholds and certification investment recovery. Price differentiation centers on FAA airworthiness qualification status and captive precursor synthesis capability. Pricing pressure stems from European industrial electricity volatility feeding through pyrolysis furnace operations. Automotive friction material suppliers exhibit highest price sensitivity amid regulatory compliance cost absorption.
Supply Chain Analysis
Dual-sourcing requirements from United States defense contractors mandate multi-supplier qualification for continuous filament lots, fragmenting procurement concentration despite geographic supply clustering in Japan, Germany, and the United States. Raw material dependencies center on polycarbosilane precursor purity, tungsten-core substrate availability, and specialized carbon filament feedstock. Single-source vulnerability concentrates in Japanese precursor manufacturing clusters serving non-integrated fiber producers. Distribution runs through defense contractor preform specifications and aerospace OEM direct qualification channels rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic matrix composite substitution of nickel superalloys in turbine hot-section components represents a technology-transition phase, with polymer-derived ceramic routes displacing legacy metal superalloy casting for sustained thermal load applications.
For Market Incumbents: Lock in long-term offtake agreements with volume floors and technical audit rights before REACH reformulation windows close, anchoring defense contractor procurement consolidation around domestic chemical vapor deposition capacity. Backward integration into captive polycarbosilane synthesis mitigates precursor supply concentration risk from Japanese and German feedstock clusters. Accelerate FAA qualification cycle synchronization to compress eighteen-to-thirty-six-month validation timelines. For New Entrants and Emerging Players: Additive manufacturing convergence for near-net-shape ceramic matrix composite preforms offers technology-first wedge positioning, exploiting binder jetting platform integration gaps among established CVD specialists. Industrial furnace lining retrofit cycles in Japan present most penetrable volume pool under METI technology roadmap incentives. Qualify chopped fiber grades for EPA-compliant automotive friction materials through Tier-1 brake system supplier partnerships rather than direct OEM engagement. For Investors and Strategic Acquirers: First commercial aerospace CMC turbine blade insertion into next-generation propulsion platforms is the leading indicator that qualification inventory monetization is accelerating across the analysis window. Vertically integrated precursor-to-fiber manufacturers with captive pyrolysis capacity represent priority acquisition archetypes. Monitor ECHA chemical reclassification enforcement as inflection signal for compliant feedstock producer valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive polycarbosilane production insulates margin structures from Japanese supply concentration. |
| FAA Qualification Cycle Compression | Accelerated airworthiness certification synchronizes fiber development with turbine component roadmaps. |
| REACH-Compliant Feedstock Reformulation | Chlorinated solvent elimination restores European market access for reformulated precursor chemistries. |
| Defense Contractor Long-Term Agreement | Volume floors with technical audit rights anchor procurement consolidation around domestic CVD capacity. |
| Additive Manufacturing Platform Integration | Binder jetting convergence enables near-net-shape preform production for complex turbine geometries. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews involving ceramic matrix composite engineers, defense procurement officers, precursor chemists, and FAA certification specialists. FAA airworthiness directives, ECHA substance classifications, METI industrial technology roadmaps, and MIIT new materials industry plans provided regulatory boundary conditions. Bottom-up fiber production capacity modeling reconciled with top-down aerospace OEM procurement forecasts.
Data-stream reconciliation across continuous fiber qualification timelines, chopped fiber industrial furnace retrofit cycles, and automotive friction material compliance deadlines shaped analytical framework segmentation by product architecture, application thermal environment, and end-user procurement concentration. CAGRs derived from pyrolysis furnace capacity expansion schedules, defense budget appropriation patterns, and EPA regulatory enforcement timelines across the projection horizon.
Several conditions sit outside the modeled scope, including hypothetical ECHA reclassification of silicon carbide fiber itself as a substance of very high concern, abrupt FAA suspension of CMC airworthiness certification acceleration, and geopolitical disruption of tungsten-core substrate supply chains. Deviation in European industrial electricity pricing volatility would shift margin structure outlook materially for pyrolysis-dependent producers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Textile Fibers Market