
 Extruded PLA Fiber Market | 2026-2036
Extruded PLA Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded PLA Fiber Market Foresight
The EU Green Deal is repositioning extruded PLA fiber from niche biomaterial to mainstream textile input. NatureWorks leverages its captive corn-feedstock supply chain to dominate North American biopolymer fiber precursor output. Braskem anchors Latin American production through its sugarcane-derived bio-based polyethylene platform, extending into PLA-compatible polymer systems. BASF competes on specialty additive formulations that improve PLA fiber heat resistance for industrial textile applications.
Extruded PLA fiber consists of polylactic acid polymer melt-spun or extruded into continuous filaments, staple fibers, or non-woven mats, typically exhibiting tensile strengths of 2.5–4.5 cN/dtex and biodegradation timelines under industrial composting conditions of 90–180 days. Its primary commercial purpose is to substitute petroleum-based polyester and polypropylene in disposable and durable textile applications where end-of-life composting is specified. Filament and non-woven product types lead current output volumes, with non-woven segments capturing margin pools in medical and hygiene disposables where single-use compostability commands premium positioning. The 3D printing application segment sustains the fastest structural expansion, driven by fused deposition modeling filament demand from prototyping services and distributed manufacturing networks.
REACH registration requirements in Europe govern chemical safety documentation for PLA fiber imports, while the EU F-Gas Regulation indirectly shapes competitive positioning by restricting fluorinated performance treatments that PLA alternatives displace in technical textiles. FDA food-contact clearance pathways in the United States enable PLA fiber migration into primary food packaging meshes and filtration media. Stakeholders must monitor composting infrastructure build-out rates in target geographies, as industrial composting availability determines whether biodegradability claims translate into realized end-of-life value for downstream buyers.
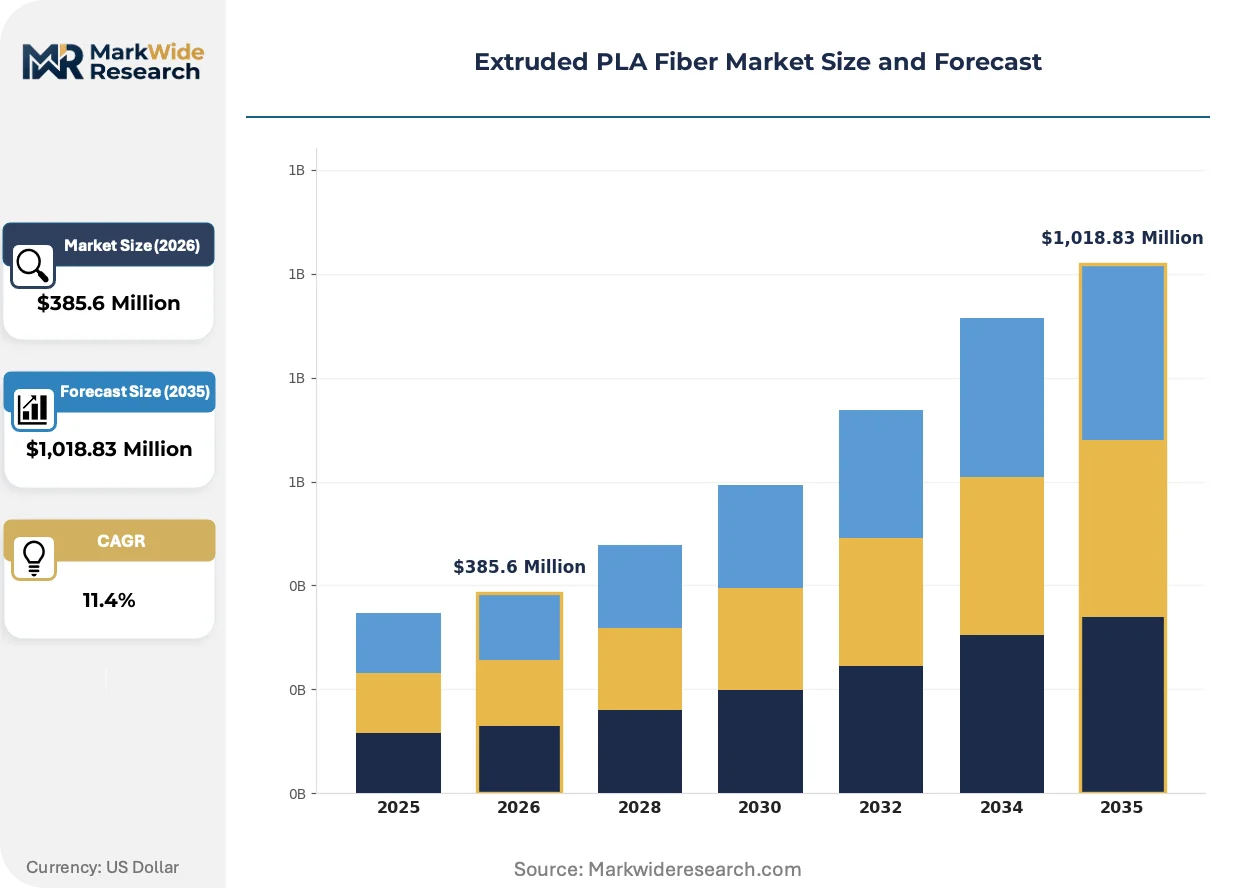
Market Dynamics
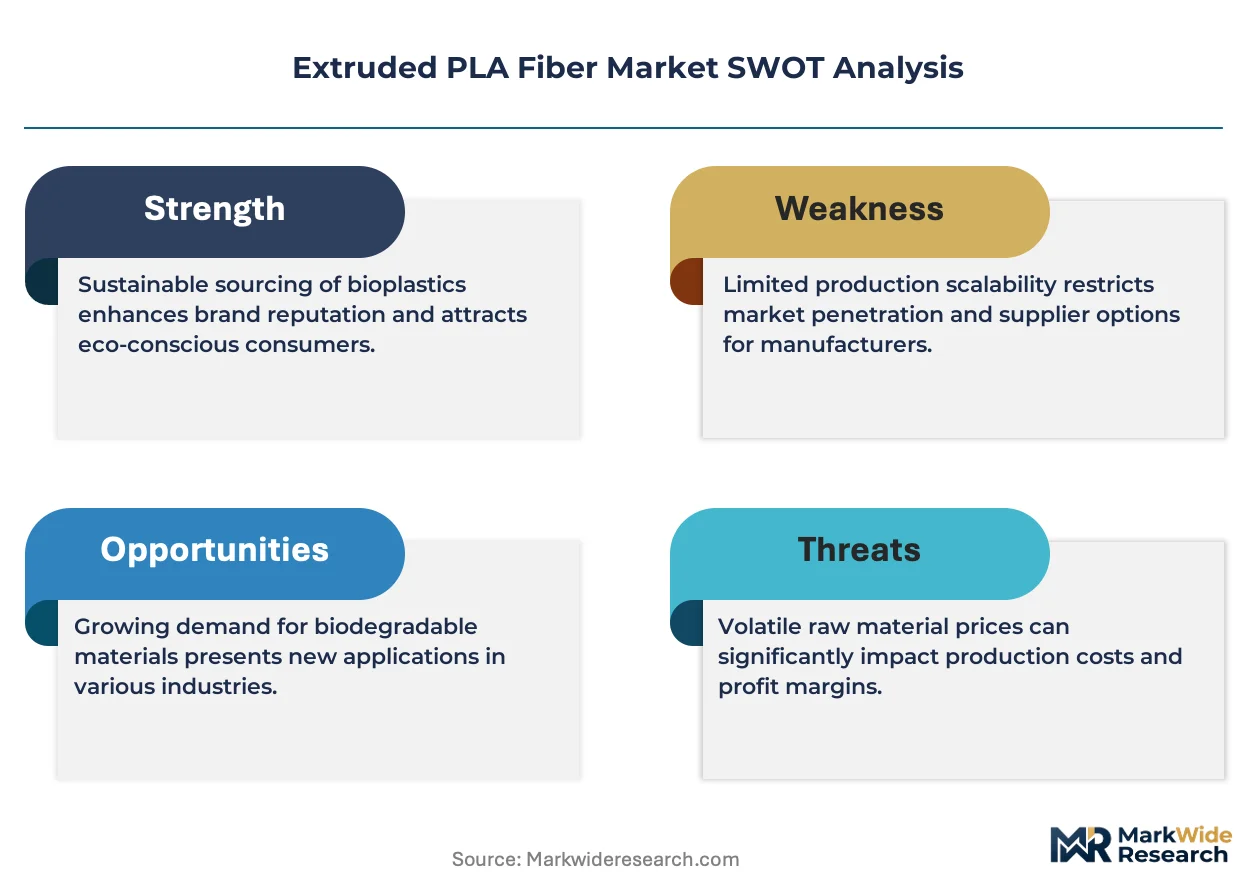
The EU Green Deal's mandatory textile sustainability requirements are forcing rapid substitution of petroleum-based synthetics, compressing procurement timelines for certified compostable alternatives across European fashion supply chains.
Growth Catalysts
- EU Green Deal textile mandates:Binding sustainability requirements under the EU's circular economy action plan are eliminating virgin polyester from public procurement specifications, redirecting institutional buyers toward certified biopolymer alternatives.
- Industrial composting infrastructure build-out:Germany's technical textile clusters in Baden-Württemberg and North Rhine-Westphalia now host integrated composting facilities that validate end-of-life claims for brand owners.
- Fused deposition modeling filament demand:Distributed manufacturing networks and rapid prototyping services are absorbing specialty-grade PLA fiber at volumes that justify dedicated production lines.
Market Restraints
- Corn and sugarcane feedstock volatility:Agricultural commodity price swings directly compress biopolymer precursor margins, exposing producers to weather-driven supply shocks in Midwest US and Brazilian growing regions.
- Heat resistance technical ceiling:PLA fiber's softening point below 60°C restricts adoption in automotive interior and industrial filtration applications where thermal stability is non-negotiable.
- REACH registration documentation burden:ECHA chemical safety dossier requirements impose fixed compliance costs on non-EU fiber importers, favoring incumbent European compounders with established registration portfolios.
Strategic Opportunities
- Medical and hygiene non-wovens:Single-use compostability specifications in German and French healthcare procurement are creating premium positioning for PLA-based surgical drapes and wound care materials.
- 3D printing material convergence:Hybrid filament formulations combining PLA with conductive or magnetic additives are automating functional prototyping workflows in aerospace component design.
- US FDA food-contact clearance pathway:Approved mesh and filtration applications for primary food packaging enable migration into beverage and processed food supply chains where petroleum-based alternatives face consumer rejection.
Industry Challenges
- Industrial composting certification timeline:ASTM D6400 and EN 13432 validation protocols require 90-180 day biodegradation documentation cycles that delay product launches and freeze working capital.
- Melt-processing equipment reconfiguration:Legacy polyester extrusion lines demand screw geometry modifications and cooling system upgrades to handle PLA's narrower thermal processing window without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded PLA Fiber Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Sheet, Granule, Non-woven Application: Textiles, 3D Printing, Packaging, Automotive Components End User: Fashion Industry, Consumer Goods, Construction, Healthcare Providers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Braskem, Sinopec, NatureWorks, Toray, Bayer, BASF, Eastman Chemical, Futerro, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded PLA Fiber Market Shifts & Advancements
Active automation of production workflows and regulatory harmonization around compostability standards are compressing development cycles while fragmenting competitive advantage across specialized feedstock and additive domains.
Closed-loop solvent recovery systems in PLA fiber extrusion are automating virgin-quality polymer regeneration from post-industrial waste streams. Technical textile manufacturers in Italy and Japan are deploying these systems to meet circularity audit requirements from luxury fashion houses. The capital intensity of solvent purification infrastructure is concentrating this capability among multi-facility compounders with captive chemical processing expertise.
REACH registration requirements for polymer imports are tightening documentary evidence standards for biodegradation claims and additive safety profiles. ECHA's 2024 updated guidance on microplastic labeling is forcing reformulation of surface treatments previously used to improve PLA fiber handle and dye uptake. German technical textile suppliers are responding by accelerating in-house additive synthesis to maintain formulation confidentiality.
Brand-led material specification is displacing distributor-driven procurement in fashion and hygiene supply chains. H&M Group and Inditex are mandating direct mill relationships with fiber producers holding third-party compostability certification, bypassing traditional yarn traders. This concentration of buying power is most visible in Nordic markets where consumer-facing sustainability scoring drives assortment decisions.
Extruded PLA Fiber Market Segmentation
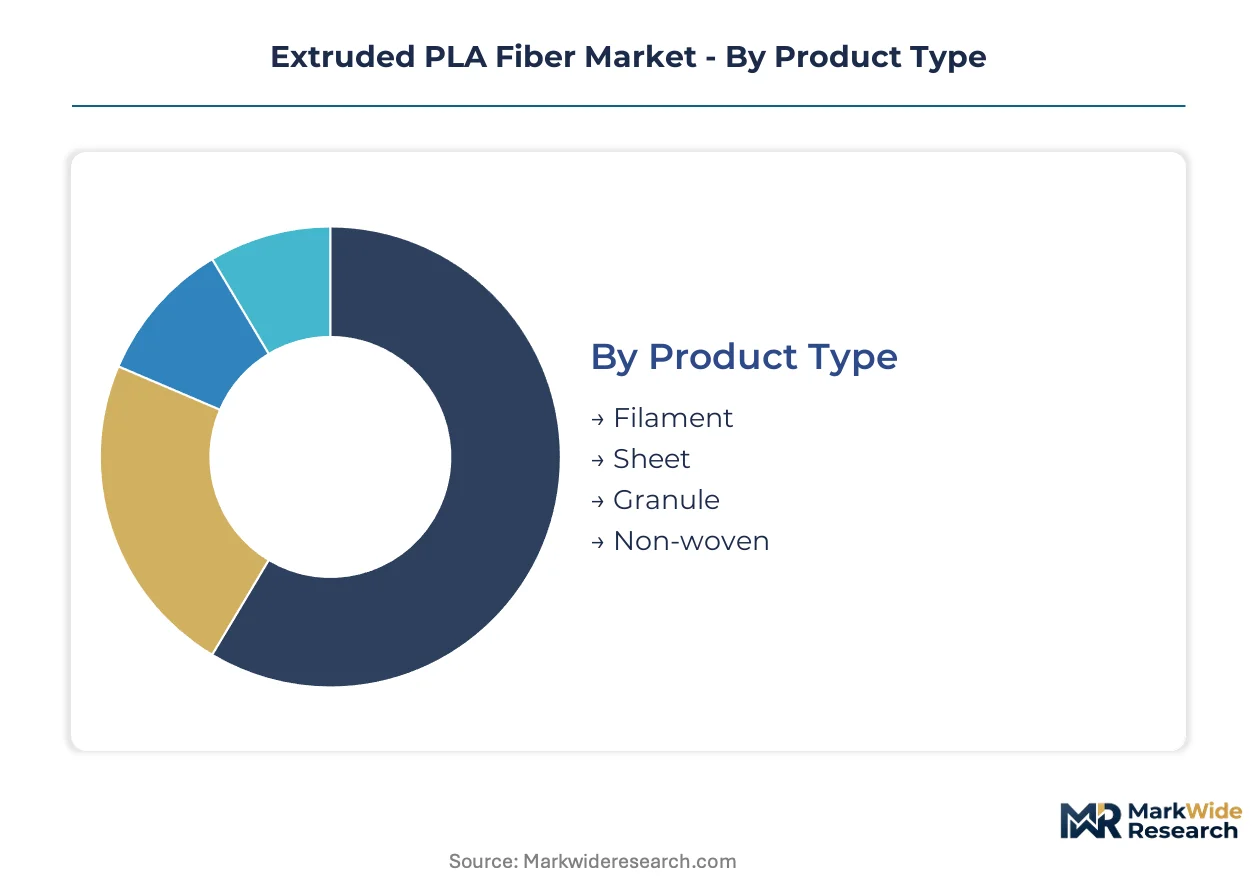
Segmentation in the extruded PLA fiber market reveals how procurement priorities diverge across technical specifications, application requirements, and channel access. Buyers sort into distinct groups based on compostability certification needs, thermal performance thresholds, and supply chain integration depth.
Product Type:
Buyers differentiate by processing method and end-form requirements, with filament purchasers prioritizing diameter consistency for downstream extrusion while non-woven buyers emphasize loft and tensile uniformity for disposable applications.
- Filament:Continuous monofilament and multifilament structures extruded to precise denier specifications serve fused deposition modeling feedstock and technical textile weaving. German 3D printing service bureaus in Bavaria and Baden-Württemberg specify tight diameter tolerances for automated filament feeding systems.
- Non-woven:Random-laid fiber mats produced via melt-blown or spun-bond processes deliver the loft and absorbency required for medical disposables and hygiene products. French healthcare procurement mandates for single-use compostable surgical drapes are concentrating demand in this segment.
- Sheet:Calendered PLA films and fiber-reinforced laminates provide thermoformable substrates for food packaging and agricultural mulch applications.
- Granule:Pelletized resin feedstock enables downstream compounders to customize additive packages for specialty fiber extrusion.
Non-woven leads volumes today; filament is gaining share fastest.
Application:
Application segmentation tracks how thermal limitations and compostability specifications filter adoption across industries with divergent performance requirements.
- Textiles:Woven and knitted fabrics for apparel, home furnishings, and technical applications substitute PLA fiber for petroleum-based polyester where industrial composting infrastructure validates end-of-life claims. Italian luxury fashion houses in Milan and Florence specify PLA blends for circularity-audited capsule collections.
- 3D Printing:Fused deposition modeling filament demands specialty-grade PLA with controlled crystallinity and color consistency for prototyping and distributed manufacturing. Rapid prototyping services in Austin, Texas and Eindhoven, Netherlands absorb dedicated production lines.
- Packaging:Mesh structures and non-woven sheets for primary food contact applications leverage FDA clearance pathways for beverage filtration and processed food containment.
- Automotive Components:Interior trim and insulation applications remain constrained by PLA's sub-60°C softening point, limiting penetration to non-structural, climate-controlled cabin elements.
Textiles anchor current procurement volumes; 3D printing shows the steepest expansion trajectory.
End User:
End user categories reflect how sustainability mandates and composting infrastructure availability shape procurement authority within organizational buying centers.
- Fashion Industry:Brand-led material specification is displacing distributor-driven procurement as H&M Group and Inditex mandate direct mill relationships with certified fiber producers. Nordic consumer-facing sustainability scoring drives assortment decisions.
- Healthcare Providers:German and French hospital systems specify single-use compostable surgical drapes and wound care materials, creating premium positioning for certified PLA non-wovens.
- Consumer Goods:Disposable tableware, wipes, and personal care products target home-composting claims where municipal infrastructure lags industrial standards.
- Construction:Geotextiles and erosion control meshes exploit biodegradability for temporary applications where removal costs exceed material value.
Fashion industry buyers command the largest contract volumes; healthcare procurement is climbing the fastest.
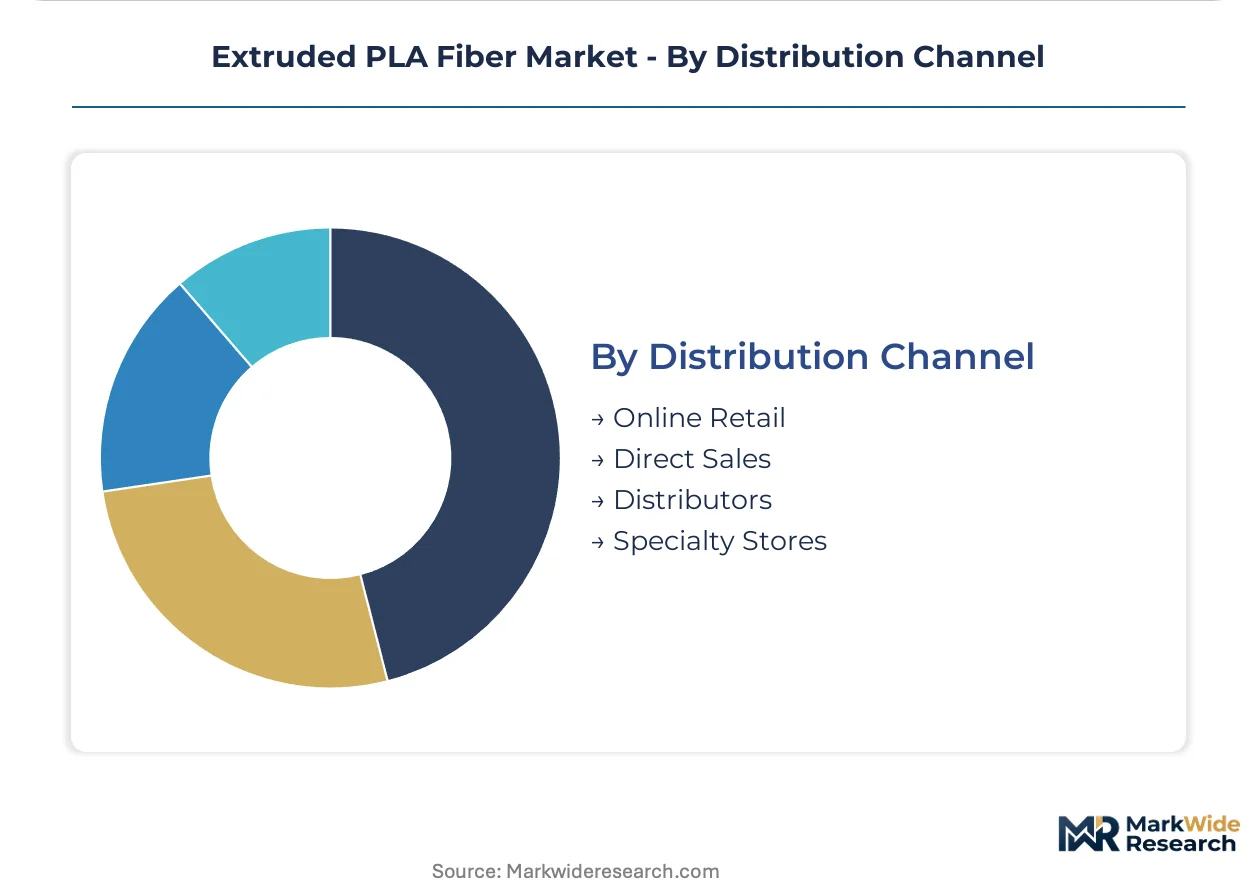
Distribution Channel:
Channel selection tracks customer scale, technical service requirements, and the shift from distributor intermediation to direct producer relationships.
- Direct Sales:Large-volume textile mills and 3D printing filament compounders negotiate directly with NatureWorks and Braskem for captive feedstock supply and technical formulation support.
- Distributors:Regional polymer distributors serve mid-volume compounders and converters requiring smaller lot sizes and just-in-time delivery.
- Online Retail:E-commerce platforms supply hobbyist 3D printing markets and small-scale prototyping services with standardized filament SKUs.
- Specialty Stores:Dedicated additive manufacturing and textile supply retailers provide technical consultation for niche applications.
Direct sales channels capture the largest transaction values; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polylactic acid fiber manufacturing originated in North American corn-belt chemistry during the 1990s, with NatureWorks scaling the first commercial production in Blair, Nebraska. European technical textile clusters subsequently integrated PLA fiber into circular fashion supply chains, while Asian compounders developed specialty grades for additive manufacturing feedstock.
Germany
Baden-Württemberg and North Rhine-Westphalia host integrated technical textile clusters where composting infrastructure validates end-of-life claims for brand owners. The EU Green Deal's binding textile sustainability requirements under the circular economy action plan redirect institutional procurement toward certified biopolymer alternatives. Munich-based 3D printing service bureaus specify tight filament diameter tolerances for automated feeding systems.
United States
Midwest agricultural feedstock supply chains anchor biopolymer precursor output, with corn price volatility directly compressing producer margins. FDA food-contact clearance pathways enable PLA fiber migration into primary food packaging meshes and beverage filtration media. Austin, Texas rapid prototyping services absorb specialty-grade PLA at volumes justifying dedicated production lines.
Japan
METI's bioeconomy strategy targets petroleum-based synthetic substitution in domestic textile manufacturing. Osaka and Nagoya industrial districts deploy closed-loop solvent recovery systems to meet circularity audit requirements from luxury fashion houses. JIS standards for industrial compostability certification create documentary barriers for non-domestic fiber importers.
Italy
Milan and Florence luxury fashion houses specify PLA blends for circularity-audited capsule collections, with brand-led material specification displacing distributor-driven procurement. ECHA's 2024 updated guidance on microplastic labeling forces reformulation of surface treatments previously used to improve fiber handle. Technical textile manufacturers accelerate in-house additive synthesis to maintain formulation confidentiality.
Brazil
Sugarcane-derived bio-based polyethylene platforms extend into PLA-compatible polymer systems through São Paulo-state chemical processing infrastructure. Agricultural commodity price swings in Brazilian growing regions expose producers to weather-driven supply shocks. ANVISA medical device regulations govern PLA fiber incorporation into surgical drape and wound care applications for domestic healthcare procurement.
Extruded PLA Fiber Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the extruded PLA fiber value chain. Integrated compounders with captive agricultural feedstock operations and in-house additive synthesis capabilities command margin pools in certified compostable grades. Three strategic archetypes dominate: corn and sugarcane feedstock-integrated biopolymer specialists, petrochemical majors leveraging specialty chemical additive portfolios, and distributed manufacturing-focused filament compounders. Competitive dynamics center on backward integration into agricultural supply chains and geographic expansion of composting infrastructure partnerships.
Among North American feedstock-integrated producers, NatureWorks and Cargill exemplify the biopolymer specialist archetype through corn-belt supply chain positioning. Braskem represents the Latin American sugarcane-derived platform model. BASF and Eastman Chemical occupy positions within the specialty additive and formulation tier, leveraging established chemical safety documentation portfolios for REACH compliance. Toray and Sinopec anchor Asian technical fiber manufacturing scale, with Japanese and Chinese compounders respectively emphasizing medical-grade certification and distributed manufacturing feedstock output. Futerro sits within the European fermentation-to-polymer integrated production segment.
| Leading Market Players |
|---|
| Braskem |
| Sinopec |
| NatureWorks |
| Toray |
| Bayer |
| BASF |
| Eastman Chemical |
| Futerro |
| Cargill |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ASTM D6400-validated industrial compostable fiber and uncertified commodity-grade PLA creates divergent margin pools that reshape both procurement premiums and feedstock sourcing geography. Premium-grade producers command dedicated corn-belt supply contracts in Nebraska and Iowa, while commodity compounders absorb spot-market agricultural volatility through Brazilian sugarcane derivatives.
Pricing Analysis
Three-tier pricing structure across premium-certified, standard-industrial, and economy-commodity levels segments buyers by compostability documentation depth and thermal performance thresholds. Price differentiation rests on EN 13432 certification status and captive corn-feedstock integration, with German technical textile mills showing lowest sensitivity due to EU Green Deal procurement mandates, while Asian filament compounders face acute pressure from agricultural commodity swings in Midwest US growing regions.
Supply Chain Analysis
Specialized fermentation technicians and polymer extrusion engineers concentrate in Nebraska's Blair corridor, Germany's Baden-Württemberg technical textile clusters, and São Paulo-state chemical processing districts. Raw material flows draw from Iowa corn belt, Brazilian Center-South sugarcane regions, and Thai cassava plantations. Single-source vulnerability in lactic acid fermentation capacity feeds from NatureWorks' captive Blair facility. Distribution runs through direct mill relationships with H&M Group and Inditex displacing traditional yarn traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Green Deal-mandated procurement premiums and Midwest US feedstock cost bases creates margin capture opportunities for transatlantic supply chain configurations. The regulatory differential between binding European textile sustainability requirements and voluntary North American compostability standards enables tiered market positioning.
For Market Incumbents: To counter emerging sugarcane-derived PLA platforms from Brazilian producers, secure backward integration into Iowa and Nebraska corn supply cooperatives while accelerating in-house additive synthesis for heat-resistance formulation confidentiality. Prioritize EN 13432 certification maintenance as REACH documentation requirements tighten. For New Entrants and Emerging Players: Conductive-magnetic hybrid filament formulations for aerospace prototyping workflows offer technology-first entry with lower incumbent saturation than medical non-wovens. Target Austin, Texas and Eindhoven, Netherlands 3D printing service bureaus through direct technical sales partnerships emphasizing diameter tolerance guarantees. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-facility compounders with captive chemical processing expertise concentrate solvent recovery capabilities. Five-to-ten year viability favors feedstock-integrated biopolymer specialists over asset-light distributors. Watch German technical textile cluster expansion rates as inflection indicator for premium-grade demand validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Supply Cooperatives | Iowa and Nebraska agricultural partnerships insulate NatureWorks from commodity price volatility. |
| EN 13432 Certification Investment | European compostability validation unlocks H&M Group and Inditex direct procurement relationships. |
| Conductive Filament Formulation Development | Hybrid PLA additives penetrate aerospace prototyping workflows in Austin and Eindhoven bureaus. |
| Solvent Recovery System Deployment | Closed-loop purification meets circularity audit requirements from Milan and Florence fashion houses. |
| Direct Mill Relationship Establishment | Bypassing traditional yarn traders captures premium positioning in Nordic sustainability-scored assortments. |
Research Methodology
Bottom-up textile and 3D printing end-use modeling reconciled against top-down biopolymer precursor supply tracking forms the analytical core of this study. Primary interviews with filament compounders, technical textile procurement managers, additive manufacturing service operators, and composting facility engineers combined with secondary validation from ECHA REACH guidance documents, EU Green Deal textile strategy publications, FDA food-contact clearance databases, and customs trade flow records.
Input-output matrices map lactic acid fermentation capacity through polymer extrusion to downstream filament and non-woven offtake across product type, application, and end-user dimensions. CAGRs derive from segmented demand elasticity modeling against industrial composting infrastructure build-out trajectories. Forecast inputs incorporate German technical textile cluster expansion rates and FDM filament diameter tolerance specifications from Bavarian service bureaus.
The model holds under sustained EU Green Deal enforcement and stable Midwest agricultural yields; deviation in REACH microplastic labeling timelines or Brazilian sugarcane harvest shocks would shift premium-grade margin distribution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Melt Spun Fibers Market
Synthetic Fibers
Synthetic Fiber Market