
 Fiber Blends Market | 2026-2036
Fiber Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Blends Market Analytics
The gap between premium performance blends and commodity-grade fiber mixes is realigning procurement patterns across the value chain. Toray Industries leverages its carbon fiber composite expertise to command premium positioning in automotive interior applications. Lenzing AG anchors its competitive stance through proprietary wood-based cellulosic fiber technologies that reduce petrochemical dependency. Reliance Industries Limited dominates bulk synthetic fiber production at scale, competing primarily on feedstock integration and volume throughput.
Fiber blends combine two or more distinct fiber types—typically cotton-polyester, wool-synthetic, or cellulosic-manmade combinations engineered to specific denier counts, tenacity ratings, and moisture-management profiles—to achieve performance characteristics unobtainable from single-source materials. Blended fibers and specialty fibers concentrate margin pools where technical specifications command specification-driven premiums in automotive and technical textile applications. Natural fibers retain structural importance in fashion industry sourcing despite synthetic fibers capturing volume leadership in mass-market textiles and home furnishings.
REACH regulations in Europe mandate chemical disclosure across textile supply chains, while the EU Green Deal's circular economy action plan pressures fiber blend recyclability and recycled content thresholds. China's GB standards and dual carbon goals enforce energy efficiency benchmarks at domestic production facilities, reshaping export competitiveness for blended fiber outputs. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in chemical recycling infrastructure or redesign blend compositions for mechanical recyclability.
Market Dynamics
Automotive lightweighting mandates are compressing fiber blend specifications toward higher tenacity-to-weight ratios, forcing suppliers to reconfigure denier counts and moisture-management profiles for interior component applications. This technical escalation is redrawing procurement relationships between compounders and Tier 1 seating suppliers.
Growth Catalysts
- EU Green Deal Ecodesign requirements:Material traceability obligations are pulling fiber blend producers toward certified recycled content and blockchain-enabled supply chain documentation across European automotive and fashion verticals.
- China's dual carbon goals:Energy efficiency benchmarks at domestic production facilities are accelerating consolidation among polyester-cotton blend manufacturers, concentrating export capacity in state-sanctioned industrial clusters.
- Automotive interior lightweighting:Seat fabric and headliner specifications are migrating toward high-tenacity cellulosic-synthetic hybrids that reduce mass without sacrificing abrasion resistance or flame-retardant performance.
Market Restraints
- Petrochemical feedstock volatility:Polyester staple fiber production remains exposed to paraxylene and MEG price swings, compressing margin predictability for commodity-grade cotton-polyester blenders.
- China supply concentration risk:Over 60% of global polyester-cotton spinning capacity sits in Zhejiang and Jiangsu provinces, creating single-geography vulnerability to energy rationing or export policy shifts.
- Mechanical recyclability ceiling:Intimate fiber blends with disparate melting points resist conventional shredding and re-extrusion, limiting circular economy participation under EU extended producer responsibility frameworks.
Strategic Opportunities
- India technical textile expansion:PLI scheme incentives for man-made fiber and technical textile investments are attracting blend compounders to Gujarat and Tamil Nadu manufacturing corridors.
- Chemical recycling infrastructure:Pyrolysis and solvolysis approaches promise to depolymerize blended waste streams into virgin-grade raw materials, unlocking circular business models previously blocked by mechanical sorting limitations.
- Digital textile printing compatibility:Fiber blends engineered for dye sublimation and reactive ink adhesion are capturing specification share in fast-fashion supply chains requiring shorter run lengths and design agility.
Industry Challenges
- Color fastness certification timelines:ISO 105 and AATCC testing protocols for automotive interior applications require 12-18 month validation cycles, delaying new blend commercialization and freezing formulation innovation.
- Cross-facility quality standardization:Multi-plant producers struggle to maintain consistent tenacity and elongation profiles across spinning assets with varying vintage and automation levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Blends Market |
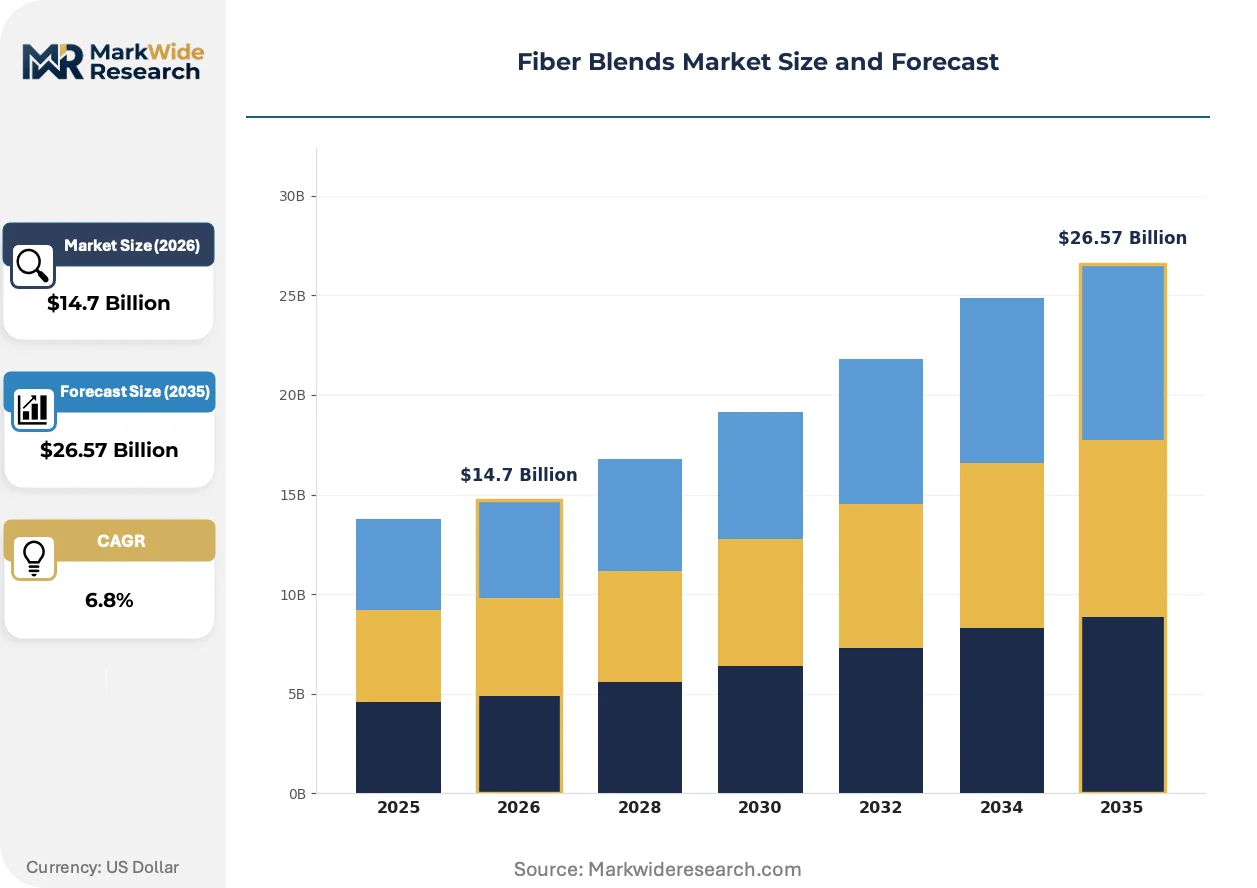
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fibers, Synthetic Fibers, Blended Fibers, Specialty Fibers Application: Textiles, Composites, Automotive Interiors, Home Furnishings End User: Fashion Industry, Automotive Sector, Construction Sector, Home Goods Manufacturers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Toray Industries, Lenzing AG, Teijin Limited, Reliance Industries Limited, Indorama Ventures Public Company Limited, Asahi Kasei Corporation, Unifi, Far Eastern New Century Corporation, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Blends Market Evolving Landscape
Digital traceability infrastructure and next-generation recycling chemistry are converging to reshape how fiber blend producers demonstrate compliance and recover value from end-of-life textiles. These shifts are compressing the gap between laboratory innovation and commercial-scale deployment.
Bio-based polyester synthesis is unifying agricultural waste feedstocks with conventional polymerization infrastructure. Automotive seating suppliers in Germany and Japan are qualifying these materials for interior applications at accelerated timelines. The technology is unifying sustainability credentials with existing processing equipment, reducing retooling barriers for compounders serving OEM specification programs.
REACH SVHC candidate list expansion is tightening disclosure obligations for flame retardants and antimicrobial finishes in textile applications. European compounders are reformulating blend compositions to eliminate halogenated and organophosphorus chemistries ahead of sunset dates. Technical textile segments serving rail and aviation interiors face the steepest compliance ramps and are driving substitution toward phosphorus-nitrogen intumescent systems.
Specification-driven procurement is consolidating buyer power among automotive OEMs and large-format retail chains. Tier 1 suppliers are responding by pre-certifying blend platforms across multiple end-use categories rather than maintaining discrete product lines. This concentration is most visible in South Carolina and Lower Saxony automotive corridors, where seating manufacturers are reducing qualified supplier lists from twelve to four approved compounders.
Fiber Blends Market Segmentation
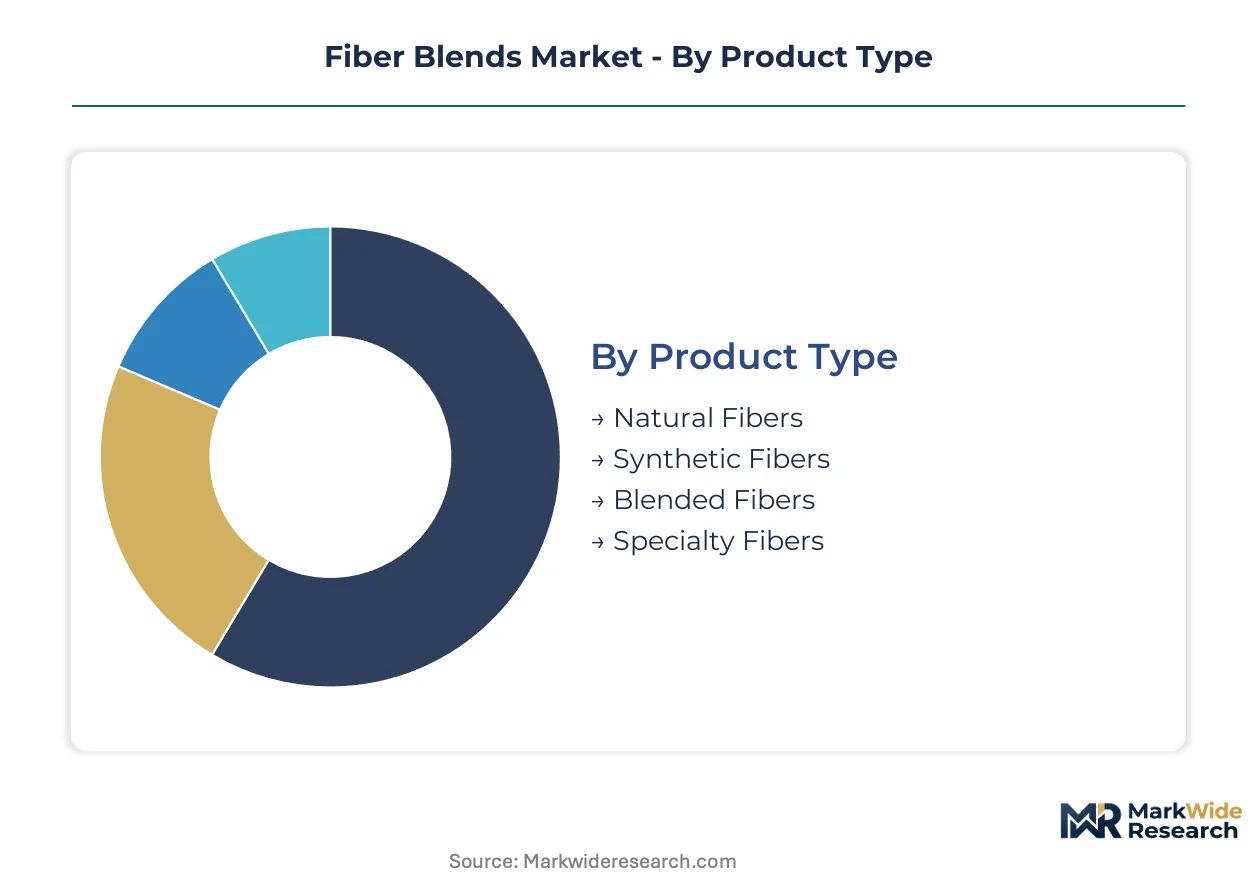
Fiber blend producers configure production assets around distinct specification tiers, with capital deployment varying dramatically between commodity spinning and technical compound operations. Understanding where fixed costs concentrate illuminates margin vulnerability and competitive moat durability across the value chain.
Product Type:
Capital intensity escalates sharply from natural fiber processing through specialty fiber synthesis, with polymerization infrastructure and precision denier control systems driving the steepest upfront outlays.
- Natural Fibers:Cotton and wool processing requires ginning, scouring, and carding equipment with moderate capital thresholds. Indian spinning clusters in Gujarat absorb the largest share of ginning capacity expansion as PLI scheme incentives redirect investment from China.
- Synthetic Fibers:Polyester and nylon staple production demands continuous polymerization lines, melt spinning towers, and draw-texturing machinery representing the heaviest capital commitments in the segment. Zhejiang province hosts the densest concentration of these assets globally.
- Blended Fibers:Intimate mixing of disparate fiber types requires precision opening, blending, and drafting systems calibrated to prevent component separation.
- Specialty Fibers:Carbon fiber and aramid blends command specification premiums in automotive and aerospace applications.
Blended fibers absorb the bulk of installed capacity; specialty fibers are expanding most quickly.
Application:
Application-driven segmentation reveals divergent performance thresholds, with automotive and composite specifications enforcing the most rigorous tenacity and flame-retardant certification barriers.
- Automotive Interiors:Seat fabric, headliner, and carpet applications mandate high-tenacity constructions with abrasion resistance exceeding 50,000 Martindale cycles and flame-retardant ratings under FMVSS 302. German OEMs in Lower Saxony are consolidating qualified supplier lists to four approved compounders per seating program.
- Composites:Fiber-reinforced polymer applications in construction and transportation infrastructure require aligned fiber architectures and matrix compatibility engineering. Japanese automotive suppliers are qualifying bio-based polyester hybrids for interior panels at accelerated timelines.
- Textiles:Apparel and industrial fabric applications span the widest specification range from commodity shirting to technical sportswear.
- Home Furnishings:Upholstery and decorative applications prioritize color fastness and pilling resistance over structural performance.
Textiles absorb the bulk of installed capacity; automotive interiors are expanding most quickly.
End User:
End-user concentration determines contract structure and pricing power, with automotive sector procurement consolidating fastest toward platform-based qualification systems.
- Automotive Sector:Tier 1 seating manufacturers in South Carolina and Lower Saxony drive specification migration toward lightweight cellulosic-synthetic hybrids. OEM lightweighting mandates compress fiber blend specifications toward higher tenacity-to-weight ratios.
- Fashion Industry:Fast-fashion supply chains prioritize digital textile printing compatibility and shorter run-length flexibility. European brands are pulling suppliers toward blockchain-enabled supply chain documentation under EU Green Deal traceability requirements.
- Construction Sector:Geotextile and reinforcement applications demand UV stability and creep resistance certification.
- Home Goods Manufacturers:Mass-market furnishings producers compete on volume throughput and feedstock integration.
Fashion industry absorbs the bulk of installed capacity; automotive sector is expanding most quickly.
Distribution Channel:
Channel economics reflect customer scale and technical service intensity, with direct sales capturing the highest-margin technical accounts and distributors serving fragmented regional demand.
- Direct Sales:Technical textile and automotive compounders maintain captive sales engineering teams for specification development and color-matching support. Toray Industries and Lenzing AG deploy direct channels for premium positioning in automotive interior applications.
- Distributors:Regional stocking distributors serve mid-tier textile mills with inventory financing and just-in-time delivery. China's polyester-cotton blend exports flow heavily through distributor networks serving Southeast Asian garment manufacturers.
- Online Retail:Specialty fiber and small-lot blend sales migrate toward platform-based procurement for design studios and craft manufacturers.
- Specialty Stores:Premium natural fiber blends reach consumers through curated retail channels emphasizing provenance and sustainability credentials.
Distributors absorb the bulk of installed capacity; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors polyester-cotton blend production globally, concentrating spinning capacity in Shaoxing and Jinhua industrial clusters that supply downstream textile processors across multiple end-use verticals.
China
Automotive lightweighting specifications from German OEMs pull Zhejiang blenders toward higher tenacity cellulosic-synthetic hybrids. MIIT energy efficiency benchmarks under dual carbon goals enforce consolidation among polyester staple producers. Shaoxing Chemical Fiber Industry Association members are migrating capacity to state-sanctioned green manufacturing parks in Ningbo.
Germany
Lower Saxony seating manufacturers consolidate qualified supplier lists to four approved compounders per automotive program. EU Green Deal Ecodesign requirements mandate blockchain-enabled material traceability across Tier 1 procurement. Wolfsburg and Hanover industrial corridors host specification development centers for next-generation seat fabric platforms.
United States
South Carolina automotive textile corridors attract technical compounders serving BMW and Volvo seating operations. EPA chemical disclosure rules intersect with NHTSA FMVSS 302 flame-retardant standards for interior applications. Greenville-Spartanburg manufacturing zone concentrates North American capacity for high-tenacity blended constructions.
India
PLI scheme incentives redirect man-made fiber investment from China toward Gujarat and Tamil Nadu technical textile corridors. BIS quality certification requirements tighten for automotive-grade blend exports to European OEMs. Surat and Coimbatore spinning clusters absorb ginning capacity expansion as cotton-polyester demand shifts southward.
Japan
METI carbon neutrality roadmaps accelerate qualification timelines for bio-based polyester hybrids in automotive interiors. Nagoya and Toyota City manufacturing zones concentrate Tier 1 supplier engineering centers for OEM specification programs. Japanese compounders are pre-certifying blend platforms across multiple vehicle segments to reduce supplier list complexity.
Fiber Blends Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across specification tiers, with polymerization infrastructure and precision denier control systems separating integrated compounders from regional blenders. The market structure concentrates margin pools where technical certification barriers limit qualified supplier counts. Three archetypes dominate: petrochemical-integrated volume leaders, wood-based cellulosic specialists, and carbon fiber composite innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure feedstock integration and automotive qualification pathways.
Within the cellulosic specialist tier, Lenzing AG anchors Austrian positioning through proprietary wood-based fiber technologies. Toray Industries exemplifies the carbon fiber composite archetype in Japanese automotive supply chains. Reliance Industries Limited represents petrochemical-integrated scale leadership from Indian manufacturing corridors. These three occupy positions across distinct specification tiers without direct overlap in procurement relationships.
| Leading Market Players |
|---|
| Toray Industries |
| Lenzing AG |
| Teijin Limited |
| Reliance Industries Limited |
| Indorama Ventures Public Company Limited |
| Asahi Kasei Corporation |
| Unifi |
| Far Eastern New Century Corporation |
| DuPont de Nemours |
| Others |
Value Network & Pricing Analysis
Automotive OEM lightweighting mandates compressing fiber blend specifications toward higher tenacity-to-weight ratios are forcing compounders to reconfigure production assets and absorb premium input costs, redrawing margin structures across specification tiers. Tier 1 seating suppliers in Lower Saxony and South Carolina are consolidating qualified supplier lists to four approved compounders per program, concentrating procurement power and compressing pricing flexibility for mid-tier blenders.
Pricing Analysis
Automotive qualification premiums anchor value-based pricing for fiber blends, with seat fabric and headliner specifications commanding substantial markups over commodity textile grades due to FMVSS 302 flame-retardant certification and 50,000+ Martindale cycle abrasion requirements. Price differentiation separates certified automotive-grade cellulosic-synthetic hybrids from commodity cotton-polyester shirting, with volume scale and feedstock integration determining competitiveness at the standard tier. Cost compression in commodity blends is intensifying because polyester staple production remains exposed to paraxylene and MEG price swings, while fashion industry buyers exhibit highest price sensitivity and automotive OEMs demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Container freight volatility from Zhejiang province to European automotive corridors has elevated logistics costs as a decisive factor in total delivered cost calculations for polyester-cotton blend exports. Supply concentrates in China, India, and Germany, with raw material flows drawing from PTA-MEG petrochemical streams, dissolving pulp for cellulosic fibers, and cotton lint from Gujarat ginning clusters. Single-geography vulnerability to energy rationing in Zhejiang and Jiangsu provinces poses structural supply chain risk, while distribution runs through direct sales channels for automotive compounders and regional distributors for mid-tier textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber blends market operates as a cost-of-compliance story where EU Green Deal Ecodesign requirements and REACH SVHC candidate list expansions erect formidable barrier-to-entry moats for compounders with certified traceability infrastructure and reformulated halogen-free flame-retardant portfolios.
For Market Incumbents: Deepen automotive qualification pathways by pre-certifying blend platforms across multiple vehicle segments simultaneously, reducing supplier list vulnerability to OEM consolidation. Invest in chemical recycling infrastructure partnerships to unlock circular business models ahead of extended producer responsibility framework deadlines, defending margin position against mechanical recyclability limitations that block commodity-grade competitors. For New Entrants and Emerging Players: Begin with India's PLI scheme corridors in Gujarat and Tamil Nadu, where technical textile incentives and shifting cotton-polyester demand create penetrable white space absent from saturated Zhejiang clusters. Target digital textile printing compatibility specifications for fast-fashion supply chains, leveraging shorter run-length flexibility as the go-to-market angle against incumbent volume-optimized assets. For Investors and Strategic Acquirers: The window for entry favors wood-based cellulosic specialists with proprietary fiber technologies and established automotive qualification timelines, positioning ahead of bio-based polyester synthesis scale-up. Monitor pyrolysis and solvolysis infrastructure deployment announcements as the inflection signal for circular economy business model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Expansion | Pre-certification across multiple OEM programs in Lower Saxony and South Carolina corridors reduces supplier list risk. |
| Chemical Recycling Infrastructure Partnership | Pyrolysis and solvolysis deployment unlocks circular business models blocked by mechanical sorting limitations. |
| Backward Integration into Dissolving Pulp | Captive wood-based cellulosic fiber supply reduces petrochemical dependency and secures Lenzing-competitive positioning. |
| Digital Traceability Platform Deployment | Blockchain-enabled supply chain documentation satisfies EU Green Deal material traceability mandates for European automotive procurement. |
| Bio-based Polyester Hybrid Qualification | Accelerated timelines for automotive interior applications unify sustainability credentials with existing processing equipment. |
Research Methodology
Trade flow databases, automotive production registries, and chemical industry association publications formed the secondary backbone for this analysis, cross-referenced with primary interviews conducted with Tier 1 seating supplier procurement directors, textile mill technical managers, and polymerization plant operations heads. Bottom-up and top-down triangulation validated volume estimates across natural fiber, synthetic fiber, blended fiber, and specialty fiber segments.
Bottom-up modeling anchored fiber blend demand to automotive interior content-per-vehicle specifications, fashion industry digital printing adoption curves, and construction sector geotextile deployment rates, while top-down analysis cross-checked against regional production capacity data and feedstock integration patterns. CAGRs were derived from regression analysis of specification migration trends and regulatory compliance cost trajectories across the projection horizon.
Underlying measurement precision varies by segment; automotive interior and specialty fiber categories carry tighter precision than commodity-grade cotton-polyester blends due to consolidated procurement data availability. Forecasts reflect assumptions regarding energy efficiency benchmark enforcement under China's dual carbon goals and REACH SVHC sunset date adherence, with stakeholders encouraged to weight these assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
High Performance Polyester Market