
 Polyester Tire Cord Fabrics Market | 2026-2036
Polyester Tire Cord Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Tire Cord Fabrics Market Outlook
ISO 9001 qualification is rotating as the baseline gating standard for Tier 1 tire cord fabric suppliers seeking OEM validation. Hyosung Corporation leverages its integrated PET resin-to-fiber operations to sustain cost leadership across Asian manufacturing bases. Teijin Limited anchors its position through advanced polymer R&D facilities in Japan. Kordsa Teknik Tekstil A.S. competes via specialized coating technologies that enhance adhesion performance in high-speed tire applications.
Polyester tire cord fabrics are high-tenacity woven textiles manufactured from polyethylene terephthalate filaments with linear densities typically ranging from 1100 to 2200 decitex, engineered to provide dimensional stability and fatigue resistance as reinforcement layers in pneumatic tires. Flat fabrics dominate current volume shipments due to their established processing compatibility with standard calendering lines. High tenacity fabrics represent the fastest-expanding product category as tire producers pursue weight reduction targets without sacrificing durability. The tire application segment captures the largest margin pool, while conveyor belts and industrial fabrics offer defensive diversification for suppliers exposed to automotive cyclicality.
REACH registration requirements in Europe, EPA emissions protocols in the United States, and China's GB standards for tire labeling collectively elevate barrier-to-entry thresholds for new polyester tire cord entrants. Tire labeling mandates in multiple jurisdictions directly link fabric performance metrics to consumer-facing fuel efficiency ratings, intensifying pressure on suppliers to certify tensile retention and heat resistance parameters. Stakeholders must monitor regulatory convergence between automotive emissions frameworks and material sustainability disclosures to anticipate qualification timelines for next-generation reinforcement textiles.
Market Dynamics
Radial tire construction standards are forcing polyester tire cord suppliers to recalibrate tenacity specifications upward, compressing qualification timelines for Tier 2 fabricators while OEMs consolidate approved vendor lists.
Growth Catalysts
- REACH registration mandates:European ECHA compliance requirements for chemical traceability are filtering out subscale coating compound suppliers, concentrating volume among qualified fabricators.
- High-speed tire applications:Premium passenger vehicle segments in Germany and Japan are specifying 2200 decitex constructions for run-flat tire platforms.
- China's tire labeling GB standards:Mandatory fuel efficiency ratings linked to reinforcement material performance are pulling domestic tire producers toward certified high-tenacity polyester cords.
Market Restraints
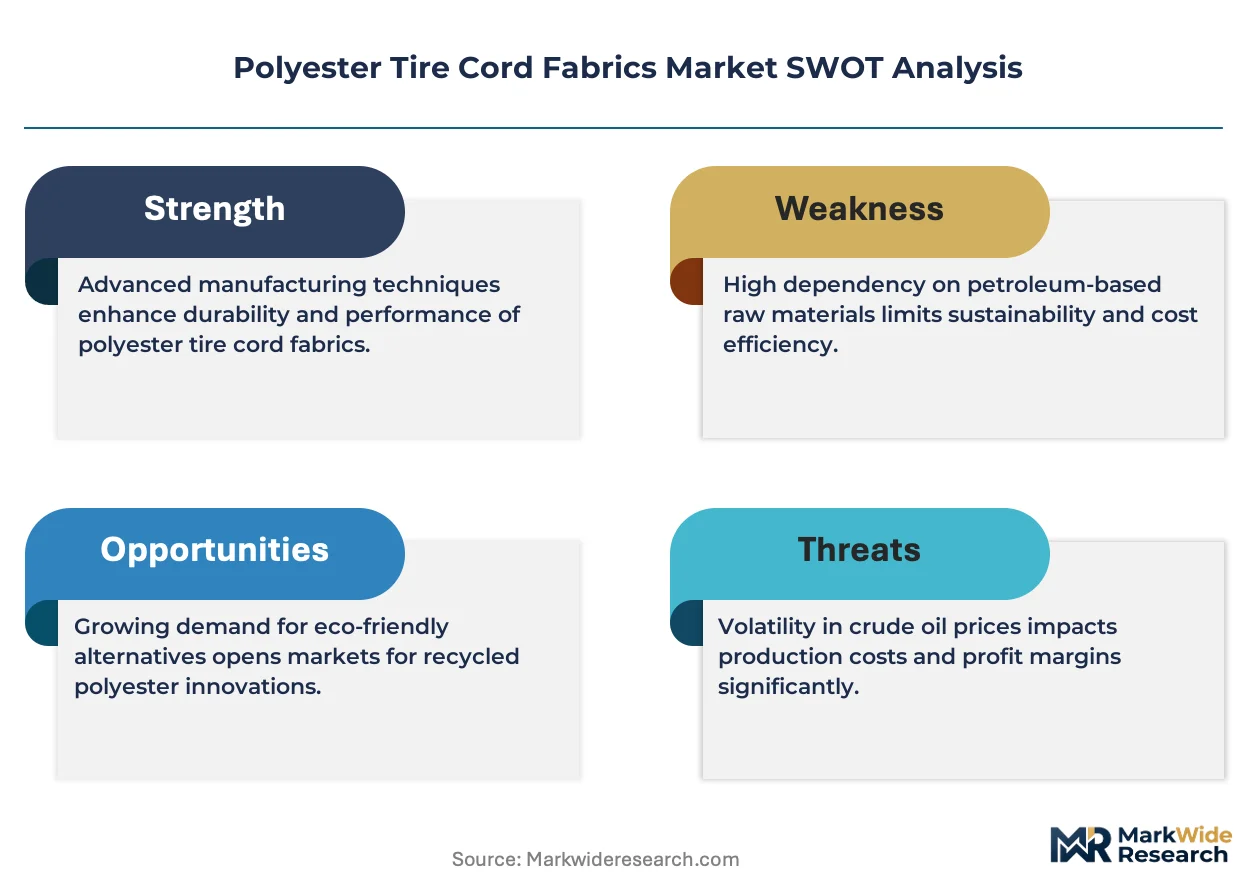
- Purified terephthalic acid volatility:Crude-linked PTA feedstock costs swing polyester chip pricing unpredictably, squeezing margin predictability for non-integrated weavers.
- Korea-China supply concentration:Over half of global high-tenacity PET filament capacity sits within 500 kilometers of Seoul and Shanghai, creating geographic vulnerability to regional logistics disruptions.
- Aramid hybrid substitution:Ultra-high-performance tire lines in motorsport and aviation applications are specifying aramid-polyester blends or full aramid reinforcement, capping polyester's addressable premium segment.
Strategic Opportunities
- India tire manufacturing expansion:Chennai and Pune production clusters are adding radial capacity for export markets, creating localized demand for qualified domestic cord suppliers.
- Conveyor belt industrialization:Mining sector expansion in Australia and Brazil is pulling technical textile demand toward heavy-duty polyester reinforcement with specialized adhesion coatings.
- EU Green Deal material passports:Upcoming CSRD-aligned sustainability disclosure requirements will favor suppliers with verified recycled-PET content and carbon footprint documentation.
Industry Challenges
- ISO 9001-IATF 16949 dual certification timelines:Tire OEM validation cycles now stretch 18-24 months for new fabric entrants, freezing working capital in qualification inventory.
- Calendering line integration complexity:Legacy tire plants in Eastern Europe and Latin America run incompatible equipment, forcing costly line modifications or exclusion from supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Tire Cord Fabrics Market |
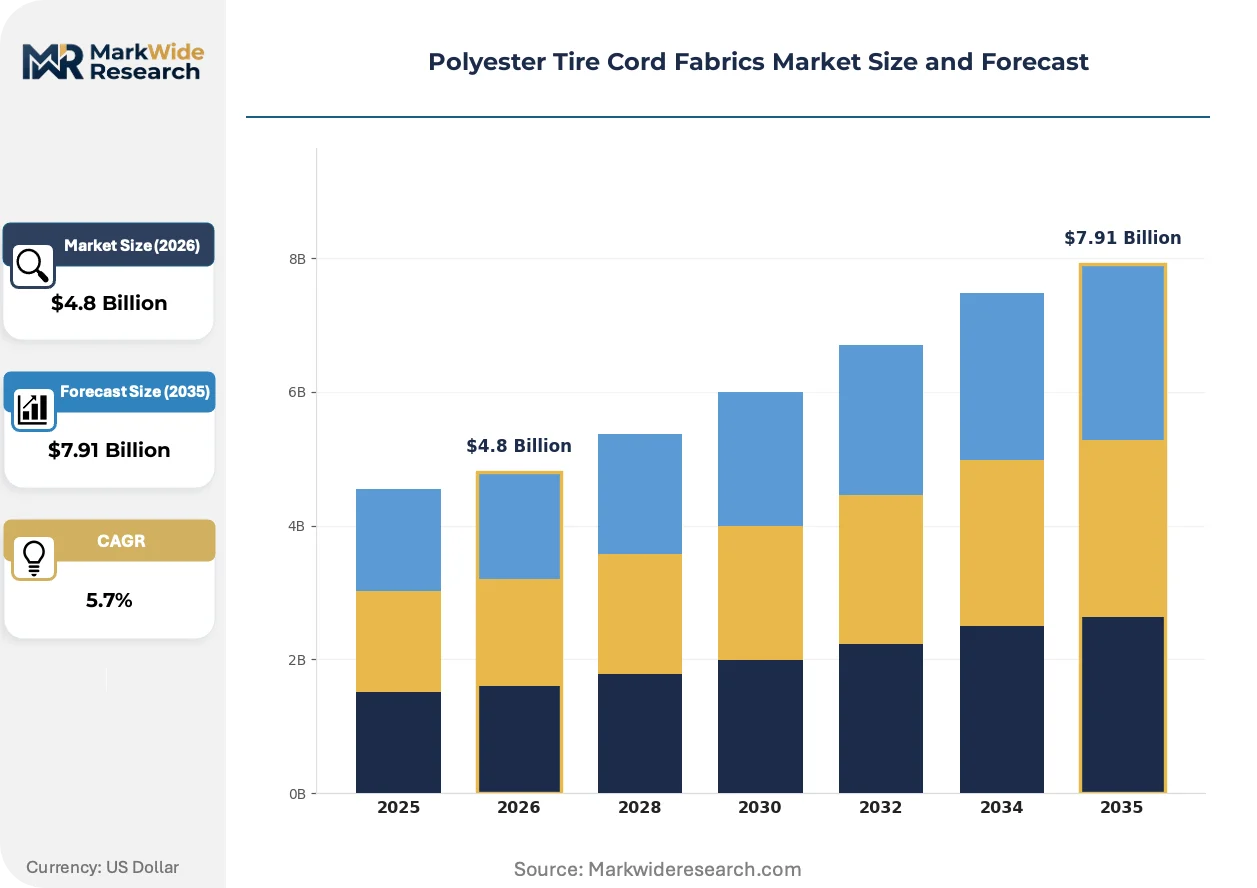
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Fabrics, High Tenacity Fabrics, Coated Fabrics, Specialty Fabrics Application: Tires, Conveyor Belts, Ropes, Industrial Fabrics End User: Automotive Manufacturers, Tire Producers, Aerospace, Industrial Equipment Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | Hyosung Corporation, Teijin Limited, Kordsa Teknik Tekstil A.S., Century Enka Limited, SRF Limited, Indorama Ventures Public Company Limited, Toray Industries Inc., Cordenka GmbH & Co. KG, Kolon Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Tire Cord Fabrics Market Strategic Shifts
Digital thread monitoring systems and bio-based PET development paths are converging to redefine how tire cord quality assurance and feedstock provenance get verified through the supply chain.
Closed-loop recycled PET filament technology is supplanting virgin chip inputs in select European tire cord specifications. Continental and Michelin procurement teams in Germany are piloting 30% rPET content fabrics for non-structural tire layers. This shift is compressing reliance on fossil-derived PTA while creating parallel certification tracks for mechanical property equivalence.
EPA emissions protocols under the Clean Air Act are tightening volatile organic compound limits on fabric finishing operations. Calendering adhesive application processes in US-based tire plants now require thermal oxidizer installations or water-based coating substitutions. Southeast Asian suppliers targeting North American OEM contracts are reconfiguring coating lines to meet these NESHAP standards.
Direct mill-to-tire-plant consignment inventory models are displacing traditional distributor-held stock in high-volume supply relationships. Bridgestone and Goodyear procurement organizations in the United States are mandating vendor-managed inventory with weekly consumption reporting. This compression of buffer stocks is most visible in just-in-time radial tire facilities across Ohio and Tennessee.
Polyester Tire Cord Fabrics Market Segmentation
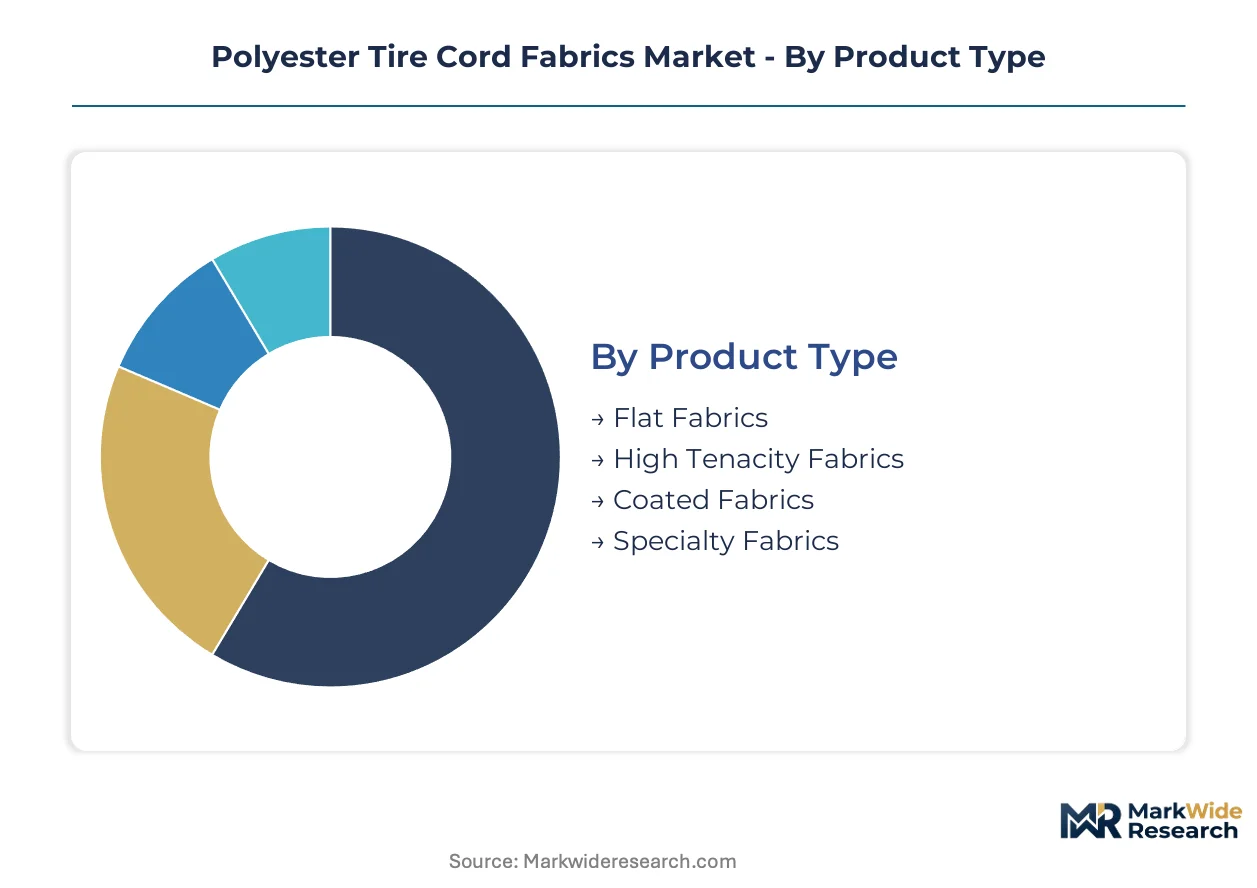
Segmentation in polyester tire cord fabrics determines qualification pathways, margin structures, and inventory models. Tire OEMs segment suppliers by certification tier, while industrial buyers prioritize coating specifications over tenacity ratings.
Product Type:
Direct sales channels dominate high-tenacity and coated fabric volumes, while distributors handle flat fabric spot purchases for smaller tire retreaders.
- Flat Fabrics:Standard woven constructions with 1100-1670 decitex filaments serve established calendering lines at legacy tire plants. Demand concentrates in Eastern European retread operations where equipment compatibility constraints block migration to higher-tenacity alternatives.
- High Tenacity Fabrics:Premium constructions utilizing 2200 decitex PET filaments enable radial tire weight reduction without fatigue degradation. German and Japanese passenger tire producers specify these for run-flat platforms, pulling volume toward certified Asian weavers with IATF 16949 validation.
- Coated Fabrics:RFL-dipped or alternative adhesive-treated textiles enhance rubber-to-cord bonding in high-speed applications. Mining conveyor belt manufacturers in Australia specify heavy-duty coated variants for abrasion resistance.
- Specialty Fabrics:Custom-engineered constructions including hybrid polyester-aramid blends target aviation and motorsport tire segments with extreme heat resistance requirements.
By volume, flat fabrics leads. By growth pace, high tenacity fabrics is climbing the fastest.
Application:
Cost tier segmentation separates tire applications—where certification costs dominate pricing—from industrial uses where raw material efficiency drives supplier selection.
- Tires:Reinforcement layers in radial passenger, truck, and off-road tires consume the majority of high-tenacity output. China's GB tire labeling standards now link fabric performance metrics to fuel efficiency ratings, intensifying certification pressure on domestic suppliers.
- Conveyor Belts:Heavy-duty longitudinal and transverse reinforcement for mining and bulk material handling. Brazilian iron ore operations specify polyester cord fabrics over steel cables for corrosion resistance in humid environments.
- Ropes:Marine and industrial cordage applications utilize lower-tenacity constructions with specialized UV stabilization packages. Demand fragments across regional rope manufacturers with limited scale for direct mill relationships.
- Industrial Fabrics:Flexible tank, geomembrane, and architectural membrane reinforcement. European technical textile producers source coated polyester cords for potable water containment applications requiring FDA-compliant adhesive systems.
Tire applications command premium pricing tiers. Conveyor belts deliver defensive volume during automotive downturns.
End User:
Customer type segmentation distinguishes automotive OEMs with 18-24 month qualification cycles from industrial equipment buyers with transactional purchasing patterns.
- Automotive Manufacturers:Vehicle OEMs specify tire cord performance parameters indirectly through tire supplier contracts. German premium automakers mandate rPET content disclosures through CSRD-aligned supply chain audits.
- Tire Producers:Bridgestone, Goodyear, and Continental procurement organizations dominate volume allocation through vendor-managed inventory programs. Weekly consumption reporting requirements favor suppliers with integrated resin-to-fiber operations.
- Aerospace:Aircraft tire manufacturers specify aramid-polyester hybrid constructions for nose gear and main landing gear applications. FAA certification timelines extend qualification cycles beyond standard automotive norms.
- Industrial Equipment:Mining, agriculture, and construction machinery OEMs purchase conveyor belt and hose reinforcement through distributor networks with limited technical specification involvement.
Tire producers represent the deepest volume concentration. Aerospace specifications carry the steepest margin premiums.
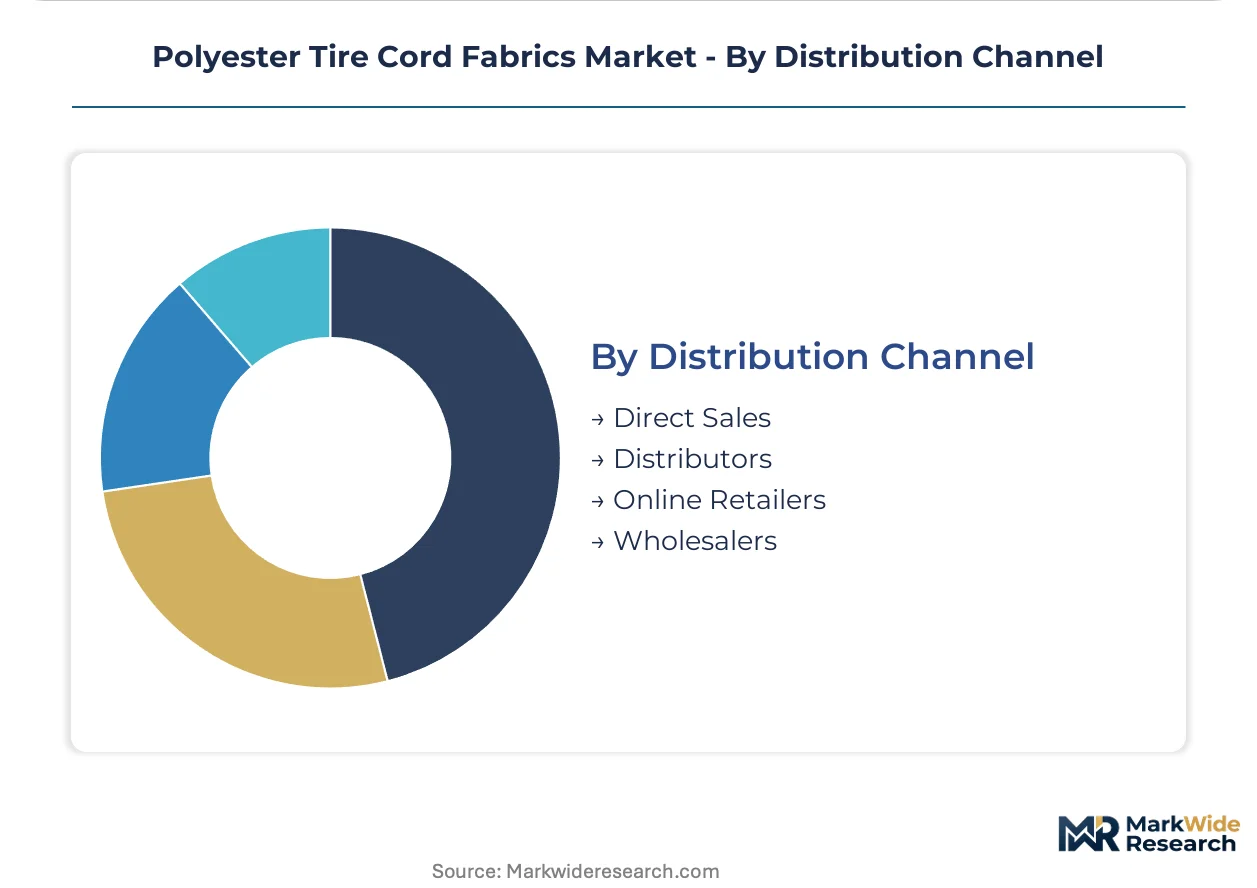
Distribution Channel:
Supply concentration shapes channel selection—integrated manufacturers favor direct relationships while fragmented weavers rely on distributor financing.
- Direct Sales:Mill-to-plant consignment models with weekly consumption reporting now dominate high-volume radial tire supply. Southeast Asian suppliers configure coating lines to meet EPA NESHAP standards for US direct contracts.
- Distributors:Regional textile distributors hold buffer stock for retreaders and smaller tire producers lacking just-in-time infrastructure. Eastern European distributors face margin compression from calendering line incompatibility issues.
- Online Retailers:Limited to specialty and small-lot industrial fabric sales where technical specifications are standardized and certification documentation is not required.
- Wholesalers:Bulk purchasers of flat fabrics for rope and general industrial applications with minimal value-added services.
Direct sales channels capture the highest value tier. Distributors retain relevance in fragmented geographic pockets lacking integrated supply chain infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration mandates in Europe and China's GB tire labeling standards are redirecting procurement toward certified high-tenacity suppliers. Tire production clusters in East Asia and Western Europe anchor volume concentration, while India's radial capacity expansion creates new qualification opportunities for domestic fabricators.
China
Domestic tire producers are upgrading to 2200 decitex constructions under GB standards that link fabric performance to fuel efficiency ratings. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions protocols for PET filament production. Shandong Province hosts the densest concentration of radial tire plants, where local fabricators compete for OEM validation against Korean integrated suppliers.
Germany
Premium automakers mandate recycled-PET content disclosures through CSRD-aligned supply chain audits, pulling procurement toward verified sustainable sources. ECHA maintains strict REACH registration requirements for chemical traceability in coating compounds. The Cologne-Düsseldorf industrial corridor concentrates Continental and Michelin procurement operations that pilot 30% rPET fabrics for non-structural tire layers.
United States
EPA NESHAP standards under the Clean Air Act now require thermal oxidizer installations for calendering adhesive applications. Ohio and Tennessee host just-in-time radial tire facilities where Bridgestone and Goodyear mandate vendor-managed inventory with weekly consumption reporting. Southeast Asian suppliers reconfigure coating lines to qualify for direct mill-to-plant contracts.
India
Chennai and Pune production clusters are adding radial capacity for export markets, generating localized demand for qualified domestic cord suppliers. The Bureau of Indian Standards enforces material certification protocols that extend qualification timelines for new entrants. Tamil Nadu's tire manufacturing belt is attracting coating technology partnerships from Turkish and Korean fabricators seeking regional production footholds.
South Korea
Integrated PET resin-to-fiber operations sustain cost leadership across Asian manufacturing bases for Seoul-headquartered suppliers. The Ministry of Trade, Industry and Energy supports advanced polymer R&D facilities that anchor high-tenacity development. The Gumi-Daegu textile corridor concentrates filament capacity within 500 kilometers of Shanghai, creating geographic leverage for China-facing supply contracts.
Polyester Tire Cord Fabrics Market Competitive Environment
Player mix skews toward integrated petrochemical-to-textile conglomerates with captive PTA and chip operations. Korean and Japanese groups anchor the premium tier through IATF 16949-validated facilities, while Indian and Turkish specialists compete on coating differentiation and regional proximity. Three archetypes dominate: backward-integrated resin producers, specialized adhesion technology developers, and scale-driven filament weavers serving distributor networks. Competitive moves concentrate on resin-to-fiber integration and EPA-compliant coating line reconfiguration for North American access.
Among Korea-based integrated suppliers, Hyosung Corporation and Kolon Industries Inc. exemplify the backward-integrated archetype with captive PET resin operations. Toray Industries Inc. anchors the Japanese premium tier through advanced polymer R&D positioning. Kordsa Teknik Tekstil A.S. occupies the specialized coating technology segment, while Century Enka Limited and SRF Limited represent India's scale-driven domestic qualification push.
| Leading Market Players |
|---|
| Hyosung Corporation |
| Teijin Limited |
| Kordsa Teknik Tekstil A.S. |
| Century Enka Limited |
| SRF Limited |
| Indorama Ventures Public Company Limited |
| Toray Industries Inc. |
| Cordenka GmbH & Co. KG |
| Kolon Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Recycled-PET filament substitution for virgin chip inputs is compressing fossil-derived PTA dependence while simultaneously shifting procurement geography toward European weavers with verified carbon documentation and flattening historical Asian cost advantages. This feedstock transition reconfigures margin pools as certification premiums for mechanical property equivalence offset raw material savings.
Pricing Analysis
Certification level creates the primary spread between IATF 16949-validated suppliers and uncertified weavers, with contract-based long-term offtake dominating high-volume tire OEM relationships. Price differentiation hinges on tenacity grade and REACH-compliant coating compound traceability, while flat fabric spot purchases through distributors face cost compression from calendering line incompatibility in Eastern Europe. Margins are tightening for non-integrated fabricators due to purified terephthalic acid volatility, with retread operations showing highest price sensitivity and German premium tire producers least.
Supply Chain Analysis
Just-in-time vendor-managed inventory with weekly consumption reporting now dominates high-volume radial tire supply, displacing distributor-held buffer stock. Geographic concentration centers on China, South Korea, and Germany, with raw material dependencies on purified terephthalic acid, PET resin chips, and RFL coating compounds. Single-source vulnerability runs through the Gumi-Daegu to Shanghai corridor where over half of high-tenacity filament capacity sits within 500 kilometers. Distribution runs through direct mill-to-plant consignment for certified volumes, with regional distributors serving fragmented retread and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyester tire cord fabrics constitute a high-growth disruption as EU Green Deal material passports and China's dual carbon goals force simultaneous feedstock transition and certification reinvestment across the supply base.
For Market Incumbents: Consolidate backward integration into captive PET resin operations to buffer PTA volatility exposure, while accelerating IATF 16949 dual certification timelines to defend against Korean integrated suppliers expanding into India's radial capacity buildout. Lock in vendor-managed inventory partnerships with Bridgestone and Goodyear procurement teams before coating line reconfiguration costs escalate for EPA NESHAP compliance. For New Entrants and Emerging Players: Lead with specialized adhesion coating technologies targeting conveyor belt mining applications in Australia and Brazil, where certification barriers sit lower than automotive tiers and abrasion-resistant specifications command defensive margins. Pursue coating technology licensing partnerships with Tamil Nadu tire belt fabricators to establish regional production footholds ahead of domestic qualification completion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Turkish and Korean coating specialists seeking geographic diversification into India's radial expansion zones. Long-term viability hinges on verified rPET content capabilities and carbon footprint documentation aligned with CSRD disclosure trajectories. Watch for Continental and Michelin procurement pilots crossing 50% rPET content thresholds as the inflection signal for sustainable feedstock lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Captive PTA supply buffers margin volatility for high-tenacity weavers competing on Korean cost benchmarks. |
| EPA NESHAP Coating Line Reconfiguration | Thermal oxidizer installations unlock direct mill-to-plant contracts with Ohio and Tennessee radial facilities. |
| IATF 16949 Dual Certification Investment | Eighteen-month validation cycles freeze working capital but secure vendor-managed inventory with tier-one tire OEMs. |
| rPET Content Verification Program | CSRD-aligned carbon documentation meets German premium automaker supply chain audit requirements. |
| Regional Coating Technology Licensing | Partnerships with Tamil Nadu fabricators establish production presence ahead of India's radial capacity ramp. |
Study Parameters
Operator-level perspectives from tire OEM procurement directors, textile plant managers, RFL coating compound formulators, and ECHA regulatory compliance officers anchored the qualitative base. Primary interview findings triangulated against secondary sources including EPA NESHAP enforcement records, ECHA REACH registration databases, China GB tire labeling standard filings, and customs trade data for PTA and PET chip flows. Bottom-up volume modeling across fabric tenacity tiers and top-down macroeconomic validation ensured cross-verification of demand assumptions.
Sensitivity analysis tested forecast robustness across the projection horizon, with segmentation dimensions spanning product type, application end-use, and regional production cluster. CAGRs derived from weighted capacity expansion schedules, OEM qualification pipeline visibility, and substitution elasticity estimates for aramid-polyester hybrid constructions. Key inputs included radial tire production forecasts by manufacturing belt, rPET feedstock availability curves, and coating technology adoption rates for water-based adhesive systems.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance enforcement or abrupt PTA feedstock cost dislocation would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and dual carbon policy implementation consistency. Revision becomes warranted when aramid hybrid substitution rates in premium tire segments cross materiality thresholds or when India's domestic qualification success rates diverge from baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Clothing Fibers Market