
 Nanofibers Market | 2026-2036
Nanofibers Market Size, Share, and Industry Trends Forecast 2026-2036
Nanofibers Market Intelligence
The ISO 13485 certification for medical-grade materials is bifurcating the supplier landscape between bulk industrial producers and specialized biomedical-focused firms. DuPont de Nemours Inc. leverages its broad polymer science expertise to serve multiple end-markets. Toray Industries, Inc. specializes in advanced carbon and composite nanofibers for aerospace and industrial filtration. Asahi Kasei Corporation focuses on high-performance materials for electronics and healthcare applications, competing on material purity and consistency.
Nanofibers are fibrous structures with diameters typically under 100 nanometers, produced through processes like electrospinning. Their extremely high surface-area-to-volume ratio makes them ideal for applications requiring high efficiency and reactivity, such as advanced filtration media. Polymer nanofibers constitute the largest product segment due to their versatility and lower production cost. In contrast, carbon nanofibers and applications in tissue engineering are high-growth areas, driven by R&D in aerospace and regenerative medicine.
Market access is governed by stringent regulations, including the US FDA's guidelines for medical devices and Europe's REACH framework managed by ECHA for chemical safety. In China, the NMPA oversees approvals for nanofibers used in biomedical applications. Future success for manufacturers depends on navigating these diverse international regulatory pathways while scaling production technologies to meet cost targets.
Market Dynamics
The central structural force shaping the market is the bifurcation of the supply base, driven by stringent medical-grade certifications. Compliance with standards like ISO 13485 is creating a clear divide between high-volume industrial producers and specialized biomedical firms.
Growth Catalysts
- Electrospinning Advances:Improvements in electrospinning technology are increasing production yields and enhancing fiber consistency, making nanofibers more viable for large-scale applications in sectors like advanced filtration and performance textiles.
- Regenerative Medicine Demand:The medical sector's focus on tissue engineering and advanced wound care is a primary catalyst, with nanofibers providing ideal scaffolds for cell growth. This demand is concentrated in advanced economies like Germany and Japan.
- Environmental Regulations:Stricter emissions and water quality standards, such as those under the US EPA, are driving adoption of high-efficiency nanofiber filters in industrial air and liquid filtration systems to meet compliance mandates.
Market Restraints
- High Production Costs:The capital expenditure for electrospinning equipment and the cost of high-purity polymers remain significant barriers, limiting adoption in price-sensitive, commodity applications and slowing broader market penetration.
- Scalability Limitations:Transitioning from lab-scale production to consistent, high-volume industrial manufacturing presents technical hurdles in maintaining uniform fiber diameter and mechanical properties, restricting use in mass-market products.
- Complex Regulatory Pathways:Navigating disparate regulatory frameworks for medical devices, such as the FDA in the US and the MDR in Europe, creates long and costly approval cycles for new biomedical nanofiber products.
Strategic Opportunities
- Energy Storage Applications:Developing nanofibers for use as separators and electrodes in next-generation batteries presents a significant opportunity, driven by the shift towards electrification in the automotive and electronics industries.
- Bio-based Polymers:Creating nanofibers from biodegradable and bio-based polymers opens new markets in sustainable packaging and disposable medical products, aligning with circular economy initiatives like the EU Green Deal.
- Electronics Manufacturing:Targeting electronics clusters in South Korea and Taiwan for applications in flexible displays, high-performance sensors, and advanced semiconductor filtration offers a path for growth beyond established markets.
Industry Challenges
- Lack of Material Standards:The absence of universally accepted standards for nanofiber characterization and performance testing creates inconsistencies, making it difficult for end-users to compare products from different suppliers and ensure quality.
- Intellectual Property Hurdles:A dense and overlapping patent landscape, particularly around electrospinning processes and functionalization techniques, creates significant IP risks and licensing complexities for new entrants into the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanofibers Market |
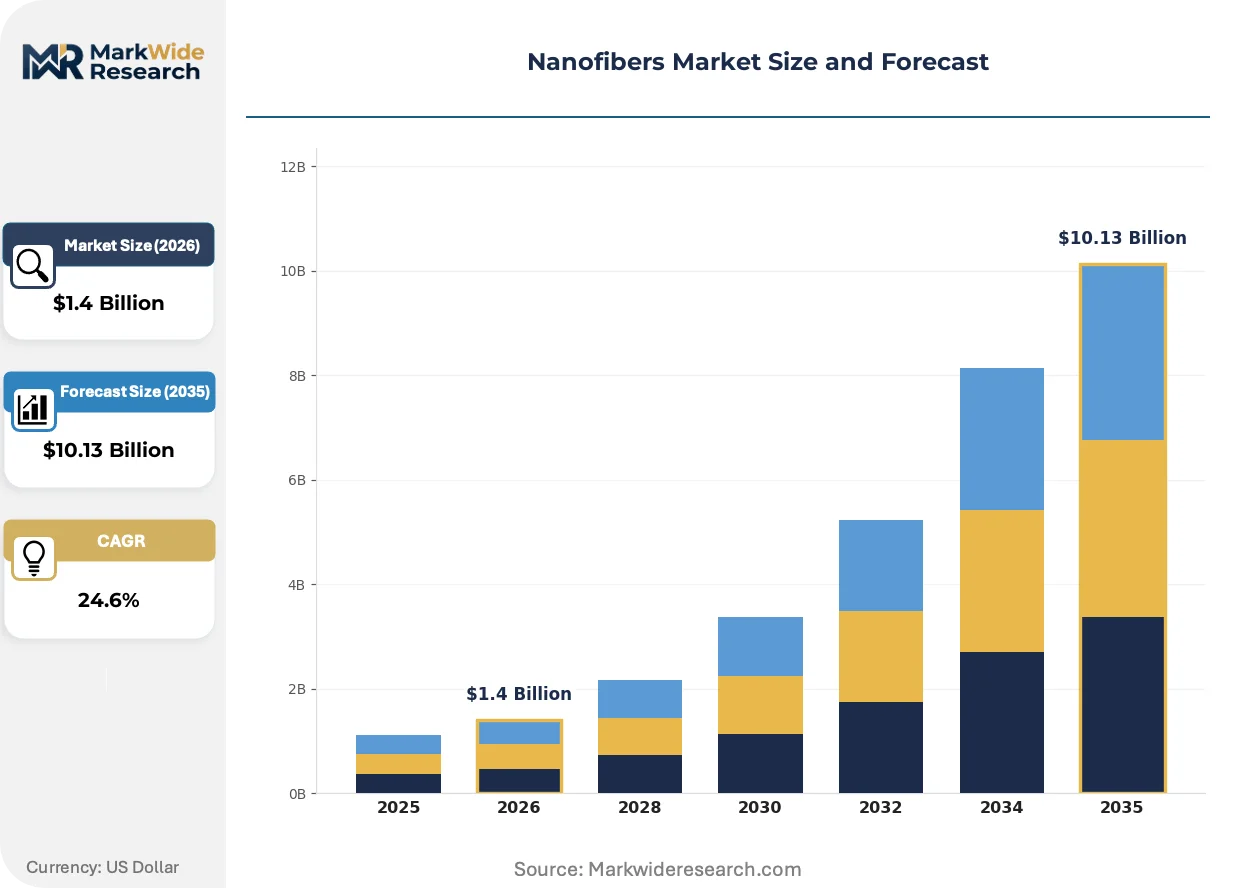
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $10.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Nanofibers, Polymer Nanofibers, Ceramic Nanofibers, Composite Nanofibers, Cellulose Nanofibers Application: Filtration, Tissue Engineering, Energy Storage, Protective Clothing, Catalyst Support Technology: Electrospinning, Solution Blow Spinning, Phase Separation, Self-Assembly, Template Synthesis End User: Research Laboratories, Cosmetics Manufacturers, Aerosol Producers, Textile Fabricators, Electronics Developers |
| Companies Covered | Toray Industries, Inc., DuPont de Nemours Inc., Teijin Limited, Donaldson Company, Inc., Asahi Kasei Corporation, Nippon Paper Industries Co., Ltd., eSpin Technologies Inc., Hollingsworth & Vose, Ahlstrom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanofibers Market Strategic Shifts & Innovations
Material science advancements are pushing nanofibers from laboratory research into commercially viable industrial and medical applications. The convergence of manufacturing process control and demand for high-performance materials defines the current trajectory, with regulations creating specialized, high-value niches.
Advanced functionalization allows for embedding active agents like antimicrobials directly into nanofibers during electrospinning. Medical and specialty filtration manufacturers are adopting these materials for products with enhanced performance, such as self-sterilizing masks. This capability is bifurcating the market between suppliers of basic polymer nanofibers and those offering high-margin, functionalized materials.
Europe's REACH regulation, managed by ECHA, imposes stringent requirements on chemicals used in nanofiber production. This framework forces manufacturers to invest in comprehensive safety data, increasing compliance costs and favoring suppliers with toxicological expertise. The regulation particularly affects carbon nanofibers, pushing producers to prioritize materials with established safety profiles to avoid lengthy ECHA approvals.
A distinct shift in purchasing criteria is evident, with buyers prioritizing material certification over raw cost in regulated end-markets. Biomedical and aerospace end-users are bypassing non-certified bulk suppliers for specialists providing full traceability and compliance documentation like ISO 13485. This trend is most pronounced in Germany’s medical technology sector and Japan’s advanced materials industry.
Nanofibers Market Segmentation
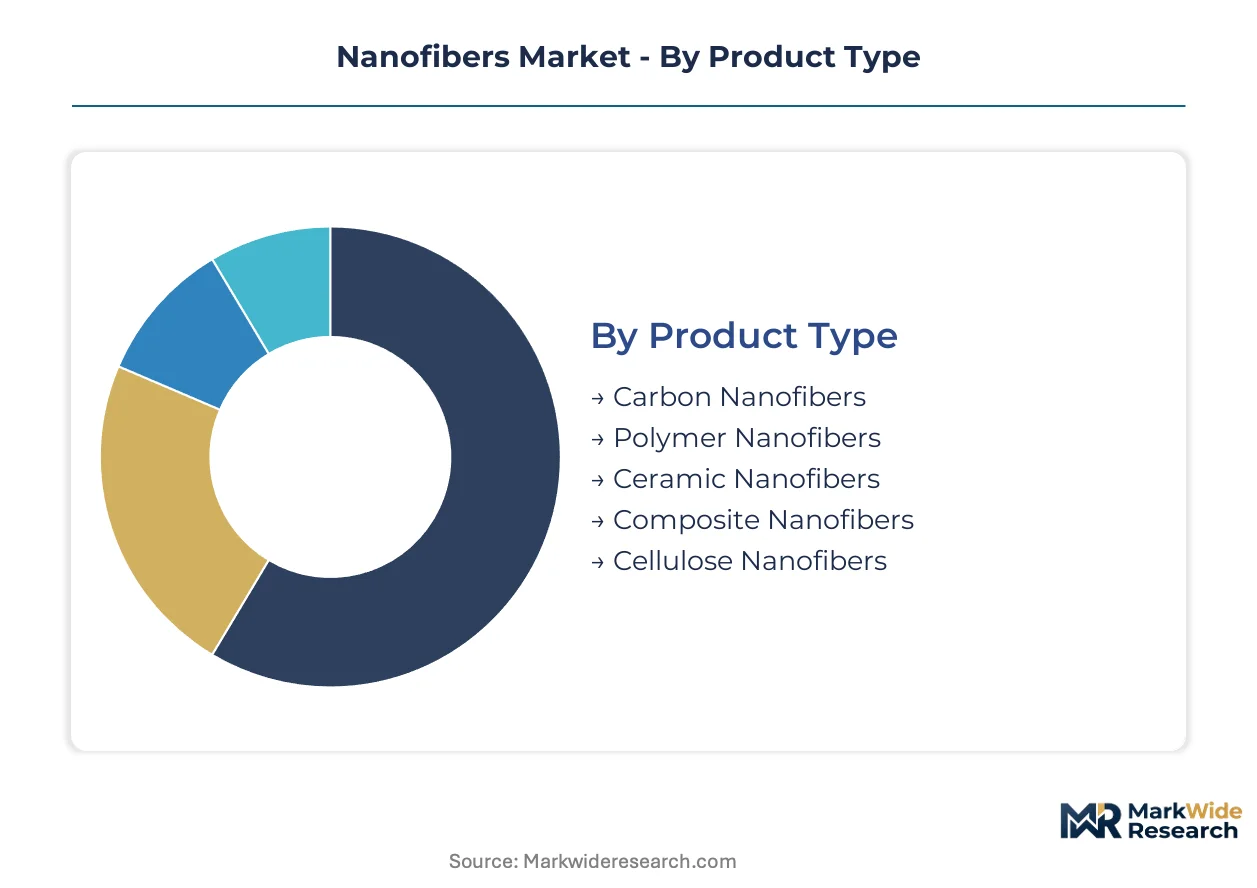
The Nanofibers Market segmentation provides crucial insights into the diverse product categories, applications, manufacturing technologies, and end-user industries driving market evolution. Understanding these distinct segments helps manufacturers tailor product development and market strategies to specific demand pockets and regulatory requirements. This granular analysis illuminates the varied growth trajectories across different nanofiber types and their commercial applications.
Product Type:
The geographic distribution of nanofiber product types varies, with some materials seeing broader industrial adoption globally while others target specialized regional markets.
- Polymer Nanofibers:These fibrous structures are produced from various synthetic and natural polymers, offering versatility in properties and cost-effectiveness. Demand concentrates in advanced filtration and medical textiles due to their adaptability and lower production costs.
- Carbon Nanofibers:Composed primarily of carbon atoms arranged in a cylindrical nanostructure, these materials offer exceptional electrical conductivity and mechanical strength. R&D in aerospace and energy storage applications drives their high-growth trajectory, particularly in economies like Japan and the United States.
- Ceramic Nanofibers:These inorganic fibers exhibit high thermal stability and chemical resistance, finding niche applications in high-temperature filtration and catalyst supports.
- Composite Nanofibers:Combining two or more distinct materials, these nanofibers leverage synergistic properties for enhanced performance in structural components and advanced sensors.
- Cellulose Nanofibers:Derived from plant materials, these biodegradable fibers offer sustainable solutions for packaging, paper, and biomedical applications, aligning with environmental initiatives.
Polymer Nanofibers holds the largest share; momentum sits with Carbon Nanofibers.
Application:
Application segments differentiate significantly based on the value proposition and required performance characteristics, influencing pricing and market access.
- Tissue Engineering:Nanofibers provide ideal scaffolds for cell proliferation and tissue regeneration due to their high surface area and porous structure, mimicking the extracellular matrix. This application commands high value in advanced economies like Germany and Japan, driven by regenerative medicine research and stringent medical device regulations.
- Filtration:Utilizing nanofibers' high surface-area-to-volume ratio, these media achieve superior efficiency in air and liquid filtration, capturing ultrafine particles. Stricter environmental regulations, such as those imposed by the US EPA, are increasing demand for these high-performance filters in industrial settings.
- Energy Storage:Nanofibers function as separators and electrodes in batteries and supercapacitors, enhancing energy density and charge-discharge rates for electric vehicles and portable electronics.
- Protective Clothing:Incorporating nanofibers improves the barrier properties and breathability of garments, offering enhanced protection against chemical, biological, and particulate threats for military and industrial workers.
- Catalyst Support:The large surface area of nanofibers provides an efficient platform for depositing catalytic nanoparticles, improving reaction kinetics and yield in chemical processes.
Tissue Engineering commands significant value due to its complexity; Energy Storage applications are expanding most quickly.
Technology:
Technology segments reflect varying levels of production maturity and scalability, impacting output volumes and consistency.
- Electrospinning:This widely adopted method uses an electric field to draw nanofibers from a polymer solution or melt, enabling precise control over fiber diameter and morphology. Continuous advancements in electrospinning equipment are increasing production yields and enhancing fiber consistency for large-scale industrial applications.
- Phase Separation:This technique involves dissolving a polymer in a solvent, inducing phase separation, and then removing the solvent to form a porous nanofiber network. It is often employed for creating highly porous scaffolds for biomedical applications, particularly in regenerative medicine research.
- Solution Blow Spinning:A simpler and more scalable method, solution blow spinning uses high-velocity gas to attenuate polymer solutions into nanofibers, offering a cost-effective alternative to electrospinning.
- Self-Assembly:This bottom-up approach relies on molecular interactions to spontaneously form ordered nanofibrous structures, often used for highly specialized materials in drug delivery and biosensing.
- Template Synthesis:Nanofibers are formed by depositing material within the pores of a template, which is then removed, allowing for precise control over fiber dimensions and composition.
Electrospinning dominates current production capacity; Solution Blow Spinning is climbing the fastest due to its versatility.
End User:
End-user categories exhibit distinct procurement patterns and demand for material certification, influencing supply chain dynamics.
- Research Laboratories:These institutions drive early-stage innovation and material characterization, requiring small volumes of diverse nanofiber types for experimental purposes. Research laboratories in academic and corporate settings consistently explore new applications and material combinations.
- Electronics Developers:This segment utilizes nanofibers for advanced components like flexible displays, high-performance sensors, and specialized semiconductor filtration media. Demand is particularly strong in technology clusters in South Korea and Taiwan, where material purity and consistency are paramount.
- Cosmetics Manufacturers:Nanofibers are incorporated into cosmetic formulations for enhanced delivery of active ingredients, improved texture, and prolonged efficacy in skincare products.
- Aerosol Producers:Companies manufacturing aerosols for medical, industrial, or consumer use employ nanofibers in filtration systems to ensure product purity and environmental compliance.
- Textile Fabricators:Integrating nanofibers into fabrics enhances properties such as water repellency, breathability, and filtration capabilities for performance apparel and technical textiles.
Research Laboratories drive early innovation; Electronics Developers are gaining share fastest with high-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent regulatory frameworks and national strategic initiatives are driving distinct regional developments in the nanofibers market. Government policies across key economies prioritize advanced materials for medical devices and high-efficiency filtration. This focus shapes material demand and manufacturing investments in specific geographic clusters.
Germany
Germany's medical technology sector generates substantial demand for specialized nanofibers in tissue engineering and advanced wound care. Compliance with EU MDR and ISO 13485 certification is critical for market access. Research and development in Munich and Stuttgart drive material innovation for biomedical applications.
Japan
Japanese industries seek high-performance nanofibers for aerospace components and next-generation energy storage solutions. METI industrial policies support advanced materials research and development, ensuring product quality through JIS standards. Manufacturers in Tokyo and Osaka focus on carbon and composite nanofibers for high-value applications.
United States
The United States market sees strong demand for nanofibers in biomedical scaffolds and advanced industrial filtration systems. US FDA guidelines govern medical device applications, while US EPA regulations drive adoption of high-efficiency filters. Innovation hubs like Boston and Silicon Valley lead in developing novel nanofiber applications for healthcare and electronics.
China
China's rapidly expanding healthcare sector and electronics manufacturing drive significant demand for nanofibers in biomedical and filtration applications. The NMPA oversees approvals for medical-grade nanofibers, with GB standards ensuring product quality across industrial uses. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta scale production for domestic and export markets.
South Korea
South Korea's robust electronics industry requires advanced nanofibers for flexible displays, high-performance sensors, and semiconductor filtration. National innovation programs support material science advancements, while the MFDS regulates medical device components. Technology firms in Seoul and Gyeonggi province continuously integrate nanofibers into next-generation electronic products.
Nanofibers Market Key Industry Players
Listed leaders compete with private specialists across the nanofiber product spectrum, creating a bifurcated market structure. This market is characterized by a blend of large, diversified chemical companies and smaller, specialized biomedical material firms, each targeting distinct application segments. Strategic archetypes include broad polymer science providers leveraging existing expertise and niche advanced material developers focusing on high-value applications. Companies primarily engage in capacity expansion and strategic partnerships to secure market share and expand their product offerings.
Within the diversified materials segment, DuPont de Nemours Inc. exemplifies a broad polymer science provider, leveraging extensive expertise across multiple end-markets. Toray Industries, Inc. anchors the advanced materials sector, specializing in high-performance carbon and composite nanofibers for aerospace and industrial filtration. Asahi Kasei Corporation represents a key player in high-performance materials, focusing on purity and consistency for electronics and healthcare applications. These firms occupy distinct positions based on their core competencies and target industries.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| DuPont de Nemours Inc. |
| Teijin Limited |
| Donaldson Company, Inc. |
| Asahi Kasei Corporation |
| Nippon Paper Industries Co., Ltd. |
| eSpin Technologies Inc. |
| Hollingsworth & Vose |
| Ahlstrom |
| Others |
Cost & Logistics Intelligence
Electrospinning equipment's high capital expenditure drives scale economies, concentrating production capacity among a few large firms. This concentration sets a high entry barrier and influences minimum price points for industrial-grade nanofibers.
Pricing Analysis
Certification level, particularly ISO 13485 for medical devices, creates the primary pricing spread in the nanofibers market. The dominant pricing model is contract-based long-term offtake for high-value applications, while commodity spot pricing applies to basic polymer nanofibers. Price differentiation also stems from material purity and customization for specialized end-uses. Pricing softness runs through bulk industrial filtration due to high competition, but biomedical applications remain price-insensitive given stringent regulatory requirements.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume polymer nanofibers, while specialized biomedical firms maintain strategic stockpiles of certified materials. Geographic supply concentration for advanced nanofibers centers on Japan, the United States, and Germany. Raw material dependencies include high-purity polymers and carbon precursors. Single-source vulnerability for specialized functionalized nanofibers represents a key structural risk. Distribution runs through direct sales to large industrial customers and specialized distributors for medical and aerospace sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanofibers market is entering a cyclical recovery, driven by renewed capital expenditure in advanced manufacturing and medical technology. This upswing creates strategic opportunities for focused investment and capability enhancement across the value chain.
For Market Incumbents:Shield core intellectual property in electrospinning processes and functionalization techniques through aggressive patent defense. Consolidate market share in established filtration and medical textile segments by investing in ISO 13485 certification capacity. This defends against emerging entrants offering lower-cost, non-certified alternatives. Deepen vertical integration into high-purity polymer production to control material consistency and cost.
For New Entrants and Emerging Players:Anchor in niche, high-growth applications like energy storage separators or advanced biosensors. Target underpenetrated electronics manufacturing clusters in South Korea and Taiwan, focusing on specialized semiconductor filtration. Develop bio-based polymer nanofibers aligned with EU Green Deal initiatives for sustainable packaging. The go-to-market angle should emphasize novel material properties and rapid prototyping capabilities rather than competing on bulk volume.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized biomedical nanofiber firms with established regulatory approvals. Focus on companies possessing proprietary functionalization techniques or strong intellectual property in electrospinning. The long-term viability for the next decade favors firms with diversified application portfolios beyond filtration. A key signal to watch is the acceleration of large-scale commercial contracts for nanofibers in battery technology or regenerative medicine.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Electrospinning | Increases production scale, meeting growing demand from advanced filtration and medical sectors. |
| Partnerships for Bio-based Polymer Development | Accelerates sustainable material innovation, aligning with EU Green Deal and new market opportunities. |
| Investment in ISO 13485 Certification | Secures market access and premium pricing in Germany's and Japan's medical device industries. |
| R&D for Energy Storage Applications | Positions firms to capitalize on the rapid expansion of electric vehicle and electronics battery markets. |
| Targeted Acquisition of Functionalization IP | Enhances product differentiation and creates high-margin offerings in specialized nanofiber applications. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings and quantitative models. Primary research involved discussions with R&D directors, procurement managers, regulatory affairs specialists, and product development leads. Secondary sources included academic journals, patent databases, and regulatory filings from the US FDA and Europe's ECHA. This approach enabled comprehensive bottom-up and top-down triangulation of market insights.
Sensitivity analysis informed the forecast framework, accounting for variable market conditions across the analysis window. The model segmented the market by product type, application, manufacturing technology, and end-user industry. CAGRs were derived by projecting demand drivers and technology adoption rates. Key forecast inputs included R&D spending in regenerative medicine and global EV battery production targets.
Material uncertainties—including unforeseen regulatory changes or breakthroughs in alternative materials—sit outside the modeled envelope. Forecasts reflect assumptions regarding current technological trajectories and market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Carbon Fiber Strands Market