
 High Temperature Fiber Market | 2026-2036
High Temperature Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Fiber Market Intelligence
Mandates within the EU Green Deal targeting industrial energy efficiency and emissions reduction are repositioning demand toward advanced high temperature fibers for thermal management. In this environment, DuPont leverages its deep expertise in aramid and specialty polymer fibers for protective apparel and composites. Morgan Advanced Materials dominates the high-performance ceramic fiber segment, serving critical applications in foundries and steel manufacturing. Concurrently, 3M Company competes by offering a diversified portfolio of inorganic fibers for insulation and fire protection across multiple end-user industries.
High temperature fibers are a class of materials engineered to retain their physical and chemical properties at continuous operating temperatures often exceeding 1000°C. These fibers, which include compositions like alumina-silicate (ceramic) or zirconia, provide exceptional thermal insulation, low thermal conductivity, and resistance to chemical attack. Ceramic fiber products constitute a large and mature segment, widely used for general industrial insulation. Demand for premium-priced alumina and zirconia fibers is driven by their superior performance in the most extreme environments, such as aerospace components and specialized foundry applications.
The market operates within a strict regulatory framework that governs material safety and application standards. The European Union's REACH regulation controls the chemical composition of fibers, while in the United States, OSHA standards dictate their use in fire protection and worker safety applications. In parallel, China’s GB standards define quality and performance for industrial materials. Stakeholders must now navigate the trade-off between higher-performance, costlier fibers and the growing pressure for material circularity and recyclability.
Market Dynamics
The central force shaping the market is a global regulatory push for industrial decarbonization. Mandates like the EU Green Deal and China's dual carbon goals are compelling energy-intensive industries to adopt advanced thermal management solutions, directly increasing reliance on high-performance fibers for efficiency and emissions reduction.
Growth Catalysts
- EU Decarbonization Mandates:The EU Green Deal's focus on industrial energy efficiency is accelerating the replacement of conventional insulation with advanced fibers in sectors like German steel manufacturing and French chemical processing.
- Aerospace Component Demand:Growth in the aerospace sector, especially for next-generation turbine blades and exhaust systems, drives requirements for fibers offering extreme temperature resistance and low weight.
- Chinese Industrial Expansion:China's continued build-out of its steel and petrochemical plant capacity creates sustained, large-scale demand for ceramic fiber furnace linings and pipe insulation.
Market Restraints
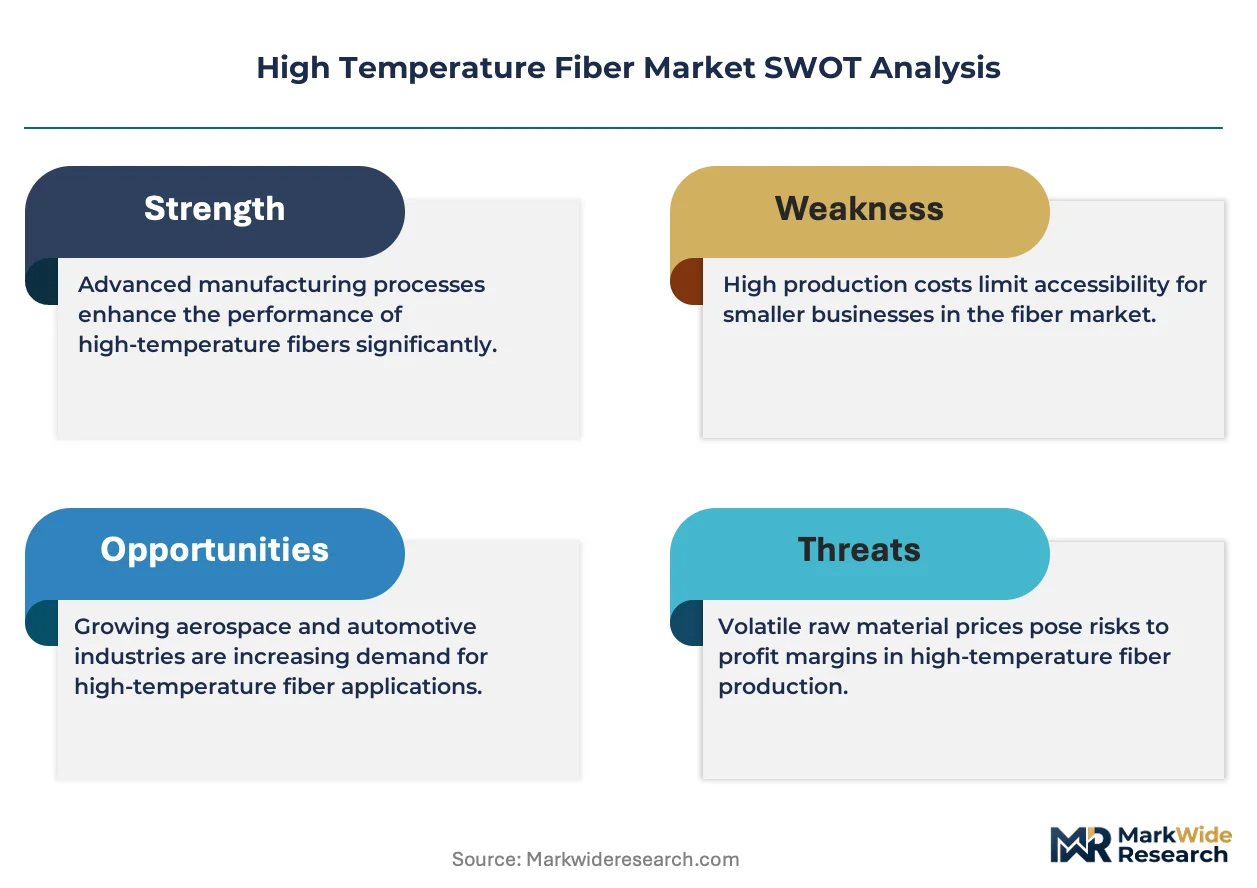
- Input Cost Volatility:The production economics for premium fibers are exposed to significant price fluctuations in key raw materials, specifically high-purity alumina and zirconia powders.
- Regulatory Scrutiny:The EU's REACH regulation places strict controls on refractory ceramic fibers due to health classifications, compelling manufacturers to invest in developing safer, biosoluble alternatives.
- Material Brittleness:The inherent brittleness of certain ceramic fibers poses installation challenges and limits their use in applications subject to mechanical shock or intense vibration.
Strategic Opportunities
- Electric Vehicle Batteries:The need for fire protection and thermal runaway prevention in electric vehicle battery packs creates a significant opportunity for specialized high-temperature fiber insulation papers.
- Hybrid Fiber Systems:Developing composite fibers that blend ceramic and polymer materials can unlock applications in flexible industrial insulation and advanced personal protective equipment.
- Indian Industrial Sector:India's expanding steel and power generation industries represent a key growth vector, with demand for insulation materials that meet local BIS quality standards.
Industry Challenges
- Material Recyclability:Developing economically viable and scalable processes for recycling end-of-life ceramic fiber products is a major operational challenge limiting circularity in the industry.
- Divergent Global Standards:Manufacturers face high compliance costs navigating differing safety and performance regulations, including OSHA worker safety rules in the US and China's GB material standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Fiber Market |
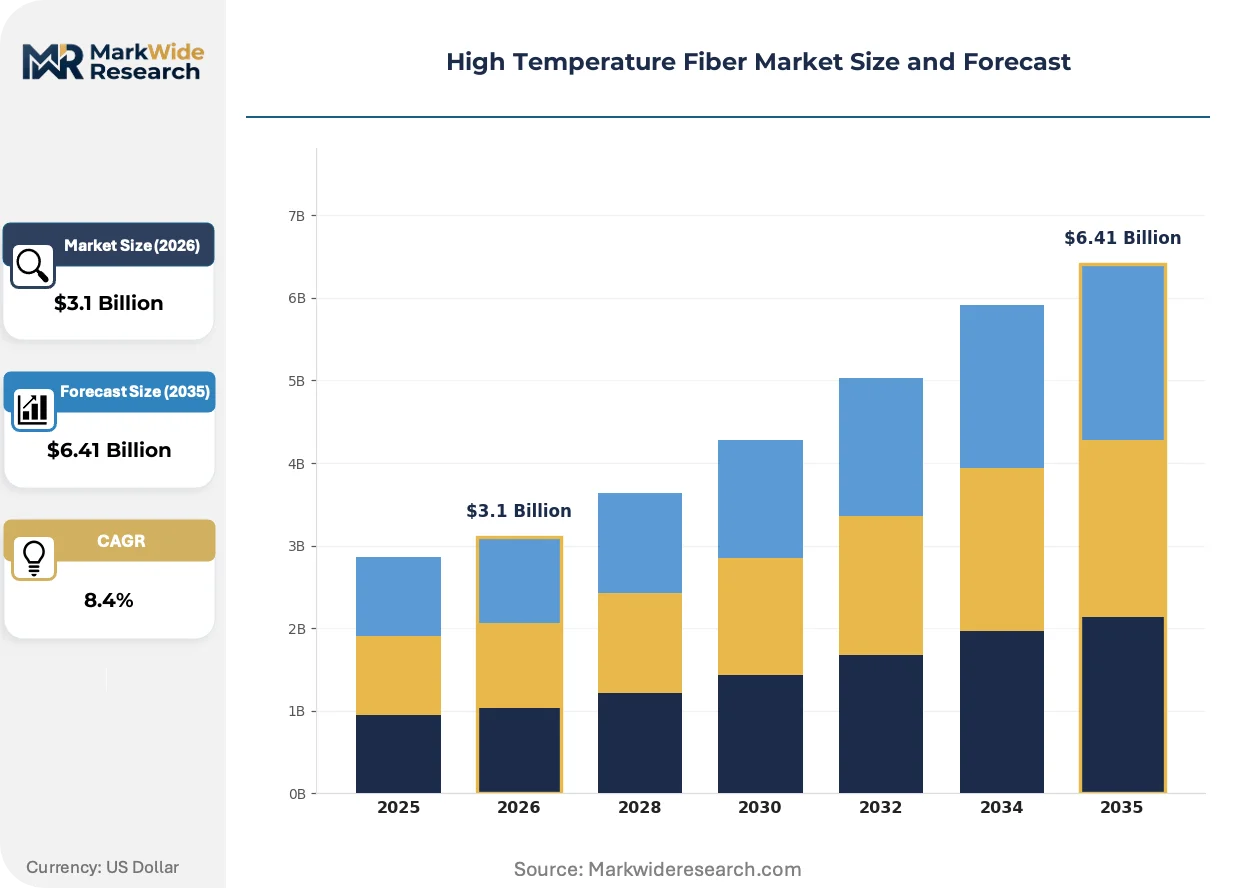
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina Fiber, Zirconia Fiber, Silica Fiber, Basalt Fiber, Ceramic Fiber Application: Thermal Insulation, Flame Retardant Textiles, Fire Protection, Technical Textiles, Composite Reinforcements End User Industry: Steel Manufacturing, Aerospace Components, Defense Equipment, Foundries, Petrochemical Plants Form: Staple, Yarn, Fabric, Roving, Felt |
| Companies Covered | Teijin Limited, 3M Company, Toray Industries Inc, Morgan Advanced Materials, Toyobo Co., Ltd., Owens Corning, Unifrax Corporation, Yantai Tayho Advanced Materials Co., Ltd., DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Fiber Market Strategic Shifts & Innovations
A fundamental shift toward material specialization defines the current market trajectory. The convergence of extreme performance requirements in aerospace with a regulatory focus on material safety and circularity is accelerating innovation in fiber composition and form.
Nanostructured fibers, particularly those based on alumina, offer superior thermal insulation at lower densities than conventional microfibers. Aerospace and semiconductor sectors are adopting these for critical thermal barrier coatings. This technology is integrating advanced insulation into smaller, lighter, and more energy-efficient system designs, pushing performance boundaries.
The European Union's Corporate Sustainability Reporting Directive (CSRD) compels large industrial end-users to disclose their environmental impact. This mandate creates a downstream pull for fibers with transparent lifecycle data, including production energy and recyclability. Fiber manufacturers supplying European industries must now provide verifiable sustainability credentials to maintain market access.
A notable demand-side shift involves end-users procuring pre-engineered, modular insulation components instead of bulk fiber. This trend favors specialized fabricators who offer custom-cut shapes and turnkey furnace lining systems over traditional distributors. The practice is most prevalent in the North American petrochemical industry, where reducing plant downtime during maintenance is a primary driver.
High Temperature Fiber Market Segmentation
Understanding the varied characteristics and end-use demands across high temperature fiber segments is crucial for strategic market positioning. Each segment presents distinct performance requirements and regulatory compliance pathways, influencing material innovation and commercial viability.
Product Type:
Regulatory frameworks like the EU's REACH legislation impose specific compliance burdens across different high-temperature fiber product types, influencing material selection and market access.
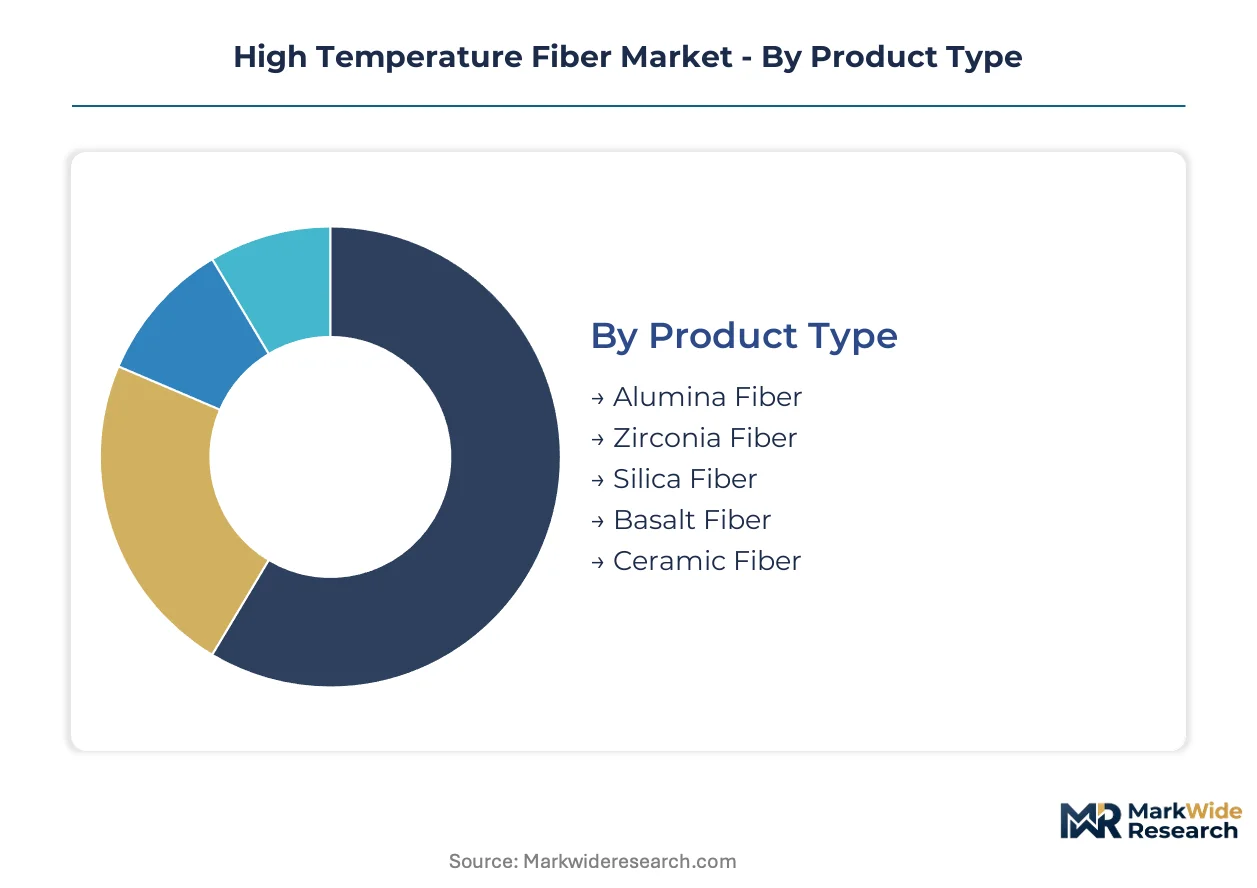
- Alumina Fiber:These advanced ceramic fibers consist primarily of aluminum oxide, offering exceptional thermal stability and chemical resistance at continuous operating temperatures exceeding 1400°C. Demand concentrates in aerospace components for turbine insulation, driven by requirements for extreme heat tolerance and reduced weight.
- Zirconia Fiber:Composed mainly of zirconium dioxide, zirconia fibers provide superior strength and thermal shock resistance, making them suitable for ultra-high temperature applications up to 2000°C. Specialized foundry applications, particularly in molten metal filtration, drive demand for these premium fibers.
- Silica Fiber:High-purity silica fibers offer excellent dielectric properties and thermal insulation, finding use in welding blankets and high-temperature textiles.
- Basalt Fiber:Produced from volcanic rock, basalt fibers provide good thermal and chemical resistance, serving as a cost-effective alternative for general industrial insulation.
- Ceramic Fiber:Alumina-silicate compositions define this large segment, widely used for general industrial insulation in furnaces and kilns.
Leading the category by volume: Ceramic Fiber. Growing fastest: Alumina Fiber.
Application:
The functional application of high temperature fibers directly shapes material engineering requirements, driving differentiation across performance characteristics.
- Thermal Insulation:This application leverages low thermal conductivity to reduce heat transfer, preserving energy and protecting equipment in industrial furnaces and boilers. The EU Green Deal's focus on industrial energy efficiency compels industries like German steel manufacturing to adopt advanced thermal insulation solutions.
- Composite Reinforcements:High temperature fibers strengthen polymer and ceramic matrices, creating lightweight, high-strength composites for demanding structural applications. Growth in aerospace components for next-generation turbine blades drives requirements for these reinforcing fibers.
- Flame Retardant Textiles:These fibers are woven into fabrics designed to resist ignition and spread of fire, crucial for protective apparel and industrial safety curtains.
- Fire Protection:Applications include fire blankets, seals, and barriers that contain flames and prevent heat transfer in buildings and industrial facilities.
- Technical Textiles:High-performance textiles incorporate these fibers for specialized uses requiring heat resistance, chemical inertness, and durability in harsh environments.
Thermal Insulation applications drive significant market volume, while Composite Reinforcements exhibit the steepest expansion trajectory.
End User Industry:
End-user industry demand profiles vary significantly, with each sector imposing distinct performance criteria and volume requirements for high-temperature fibers.
- Steel Manufacturing:This industry utilizes high temperature fibers for furnace linings, ladle insulation, and other refractory applications to withstand extreme heat and abrasive conditions. China's extensive steel manufacturing capacity creates sustained, large-scale demand for these materials.
- Aerospace Components:Fibers are critical for thermal management in aircraft engines, exhaust systems, and re-entry vehicles, requiring materials with exceptional strength-to-weight ratios and high-temperature performance. Demand for next-generation turbine blades drives innovation in this sector.
- Defense Equipment:Specialized high temperature fibers protect personnel and sensitive electronics in military vehicles and systems from extreme heat and ballistic impacts.
- Foundries:Casting operations rely on high temperature fibers for insulation in melting furnaces and as filtration media for molten metals.
- Petrochemical Plants:These facilities use high temperature fibers for insulation in reactors, pipelines, and distillation columns to maintain process temperatures and prevent energy loss.
Steel Manufacturing generates the largest volume of demand, with Aerospace Components gaining share most quickly.
Form:
The physical form of high-temperature fibers dictates their usability and integration methods within industrial processes and finished products.
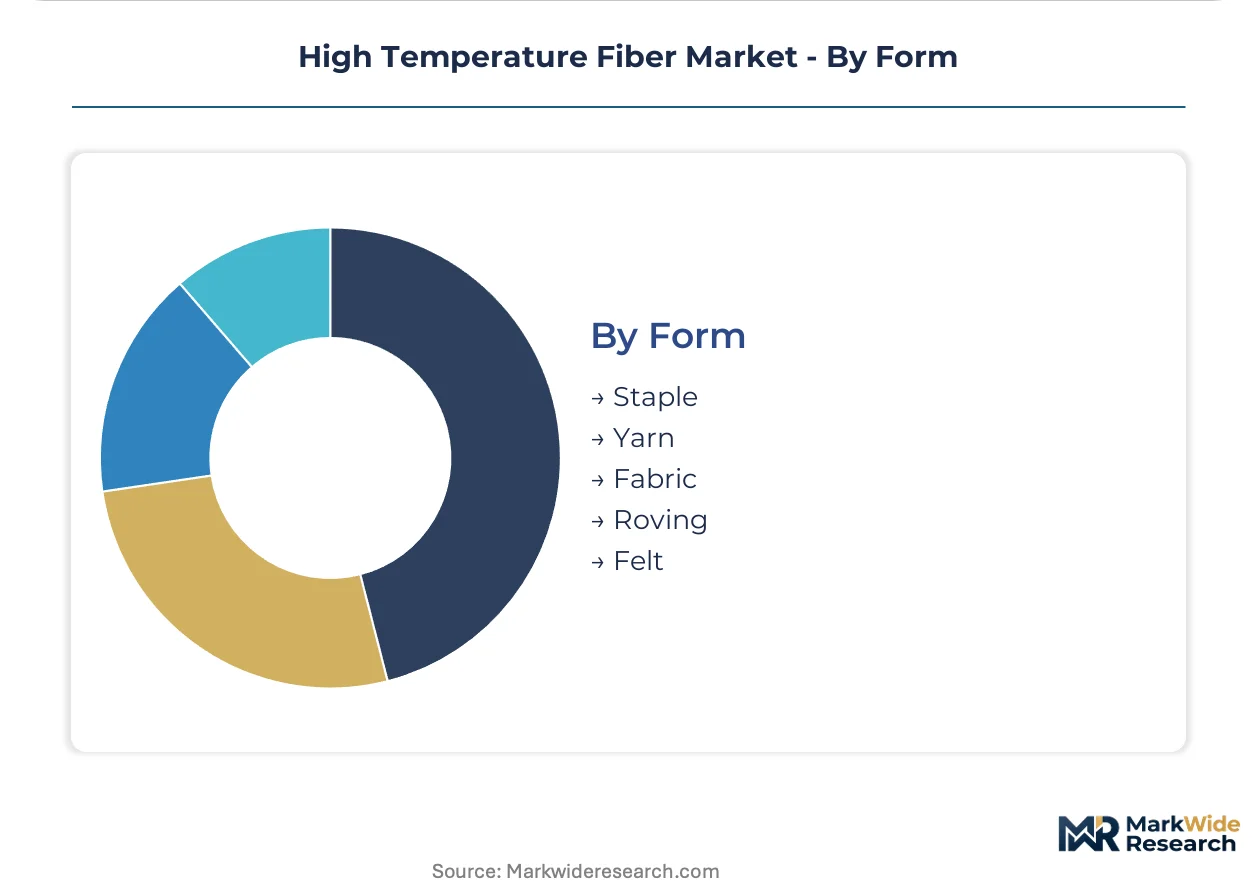
- Fabric:Woven or knitted forms of high temperature fibers offer flexibility and ease of handling, suitable for thermal barriers, protective apparel, and custom insulation wraps. The North American petrochemical industry increasingly procures pre-engineered, modular insulation components in fabric form to reduce plant downtime.
- Felt:Non-woven mats of high temperature fibers provide excellent insulation properties and conformability, often used as gaskets, seals, and battery separators. The need for fire protection and thermal runaway prevention in electric vehicle battery packs creates a significant opportunity for specialized fiber insulation felts.
- Staple:Short, discontinuous fibers are processed into bulk wool, blankets, or boards for general industrial insulation and refractory applications.
- Yarn:Continuous strands of high temperature fibers are used for braiding, weaving, and sewing, enabling the production of ropes, tapes, and specialized textiles.
- Roving:Bundles of continuous filaments provide reinforcement for composites and can be chopped or woven into various forms for specific applications.
Felt products are experiencing rapid growth, while Fabric forms cater to diverse industrial needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's extensive industrial base drives significant demand for high temperature fibers. Its petrochemical and steel manufacturing sectors require advanced thermal management solutions for energy efficiency. This concentration highlights global industrial needs for specialized insulation materials.
China
Demand for ceramic fiber furnace linings and pipe insulation is immense, supporting heavy industry. China's dual carbon goals compel energy-intensive industries to adopt advanced thermal management solutions. The Yangtze River Delta region, particularly around Shanghai and Nanjing, shows high consumption for industrial insulation.
Germany
Industrial energy efficiency mandates from the EU Green Deal reshape fiber demand. German steel manufacturing and chemical processing sectors increasingly integrate advanced fibers. The Ruhr Area, a traditional industrial heartland, prioritizes high-performance thermal insulation for its industrial facilities.
United States
The aerospace sector drives requirements for extreme temperature resistance and low weight fibers in critical components. OSHA standards dictate fiber use in fire protection and worker safety applications. Houston's petrochemical complex in Texas procures pre-engineered modular insulation components.
India
Expanding steel and power generation industries create a key growth vector for insulation materials. India's BIS quality standards influence material selection for industrial applications. The industrial corridor between Mumbai and Pune exhibits sustained demand for advanced thermal insulation solutions.
High Temperature Fiber Market Key Industry Players
Premium-margin players sit above commodity-margin players across material performance and application specificity. The market exhibits a tiered structure, ranging from specialized innovators to diversified industrial suppliers. Key archetypes include advanced material specialists and broad-portfolio manufacturers. Companies primarily pursue portfolio diversification and strategic partnerships to enhance their market reach.
Within the specialty fiber innovator tier, DuPont represents expertise in aramid and specialty polymer fibers. Morgan Advanced Materials exemplifies dominance in high-performance ceramic fiber segments. 3M Company occupies a position as a diversified supplier of inorganic fibers for insulation and fire protection. These entities anchor distinct segments of the high temperature fiber market.
| Leading Market Players |
|---|
| Teijin Limited |
| 3M Company |
| Toray Industries Inc |
| Morgan Advanced Materials |
| Toyobo Co., Ltd. |
| Owens Corning |
| Unifrax Corporation |
| Yantai Tayho Advanced Materials Co., Ltd. |
| DuPont |
| Others |
Cost & Logistics Intelligence
A clear performance and cost divergence between advanced alumina/zirconia fibers and commodity ceramic fibers shapes both pricing power and supply chain configurations in the market.
Pricing Analysis
Value-based pricing anchors premium fiber sales, reflecting superior thermal performance and longevity in extreme environments. Price differentiation stems from quality grade, specific certifications like OSHA standards, and customization for pre-engineered components. Upward pricing pressure arises from volatility in high-purity alumina and zirconia powder costs. Aerospace and defense sectors exhibit the least price sensitivity, while general industrial insulation buyers are highly price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate supply risk for industrial buyers. Geographic supply concentrates in China for ceramic fibers, with specialized raw material processing for premium fibers occurring in Europe and the United States. Raw material dependencies include high-purity alumina and zirconia powders. Commodity price volatility in these inputs presents a significant supply chain risk. Distribution runs through direct sales to large industrial end-users and specialized fabricators for modular insulation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high temperature fiber market is becoming a vertical-integration race, as companies pursue upstream control over high-purity raw material sourcing.
For Market Incumbents:
Anchor R&D efforts in developing biosoluble fiber alternatives, directly addressing EU REACH regulatory scrutiny. Consolidate market share in aerospace components through strategic acquisitions of specialized fabricators. Invest in advanced manufacturing capabilities for nanostructured fibers, countering competitive threats from emerging material innovators. Expand capacity for premium alumina fiber production to meet growing demand.
For New Entrants and Emerging Players:
Begin with specialized applications like electric vehicle battery fire protection, targeting unmet demand for thermal runaway prevention. Focus on hybrid fiber systems for flexible industrial insulation, leveraging performance gaps in existing solutions. Enter the Indian industrial sector with BIS-compliant materials, addressing regional quality standards. Develop transparent lifecycle data for products, appealing to CSRD-mandated disclosures.
For Investors and Strategic Acquirers:
Re-rating potential sits with advanced material specialists given the accelerating demand for extreme performance in aerospace components. Target firms with strong intellectual property in alumina or zirconia fiber production technologies. Monitor increasing adoption of circularity solutions as an inflection indicator for long-term viability. Focus on companies with established market access in high-growth regions like India.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Alumina Fiber | Meets rising aerospace and extreme environment demand, securing future revenue streams. |
| Biosoluble Fiber Development | Addresses stringent EU REACH regulations, ensuring market access and mitigating health risks. |
| Long-term Zirconia Supply Agreements | Stabilizes production costs for ultra-high temperature applications, reducing raw material volatility. |
| Modular Insulation Component Integration | Captures value from pre-engineered solutions, aligning with end-user procurement shifts. |
| India Market Entry Strategy | Penetrates a rapidly industrializing region, leveraging expanding steel and power generation sectors. |
Research Approach
Trade association data, regulatory filings (REACH, OSHA, GB standards), and customs records anchored secondary inputs. Primary interviews with plant managers, aerospace engineers, procurement leads, and R&D directors provided qualitative insights. This approach triangulated bottom-up market data with top-down industry trends.
Data-stream reconciliation integrated historical performance with projected growth across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and geographic region. Compound annual growth rates derived from demand-side drivers like industrial decarbonization mandates. Raw material price volatility served as a critical forecast input.
Geopolitical shifts, unforeseen technological breakthroughs, and significant regulatory amendments are the dominant revision risks. Forecasts reflect assumptions documented at the time of publication. A model refresh is warranted upon material change in industrial energy efficiency mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Global Synthetic Spider Silk Market