
 Polyimide Fiber Market | 2026-2036
Polyimide Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Fiber Market Intelligence
Aerospace procurement is restructuring demand profiles across the polyimide fiber value chain as commercial aviation and defense programs expand thermal management requirements. DuPont de Nemours, Inc. leverages its heritage in aramid chemistry to anchor premium filament supply for jet engine insulation. Evonik Industries AG specializes in high-purity polymer intermediates that sustain European aerospace certification pipelines. Kaneka Corporation dominates Asian flexible circuit substrate markets through integrated polyimide film-to-fiber conversion.
Polyimide fiber consists of aromatic imide repeating units formed through condensation of dianhydrides and diamines, yielding continuous-use temperatures exceeding 300°C with negligible thermal decomposition. These fibers serve critical functions in flame-resistant barriers, electrical insulation layers, and structural composites where organic alternatives fail. Heat-resistant fibers lead product type revenue pools due to established aerospace and metallurgy demand, while flexible fibers represent the fastest-growing category as foldable electronics and wearable thermal systems expand addressable applications. Composite fibers concentrate margin pools in prepreg formats for satellite bus structures and unmanned aerial vehicle frames.
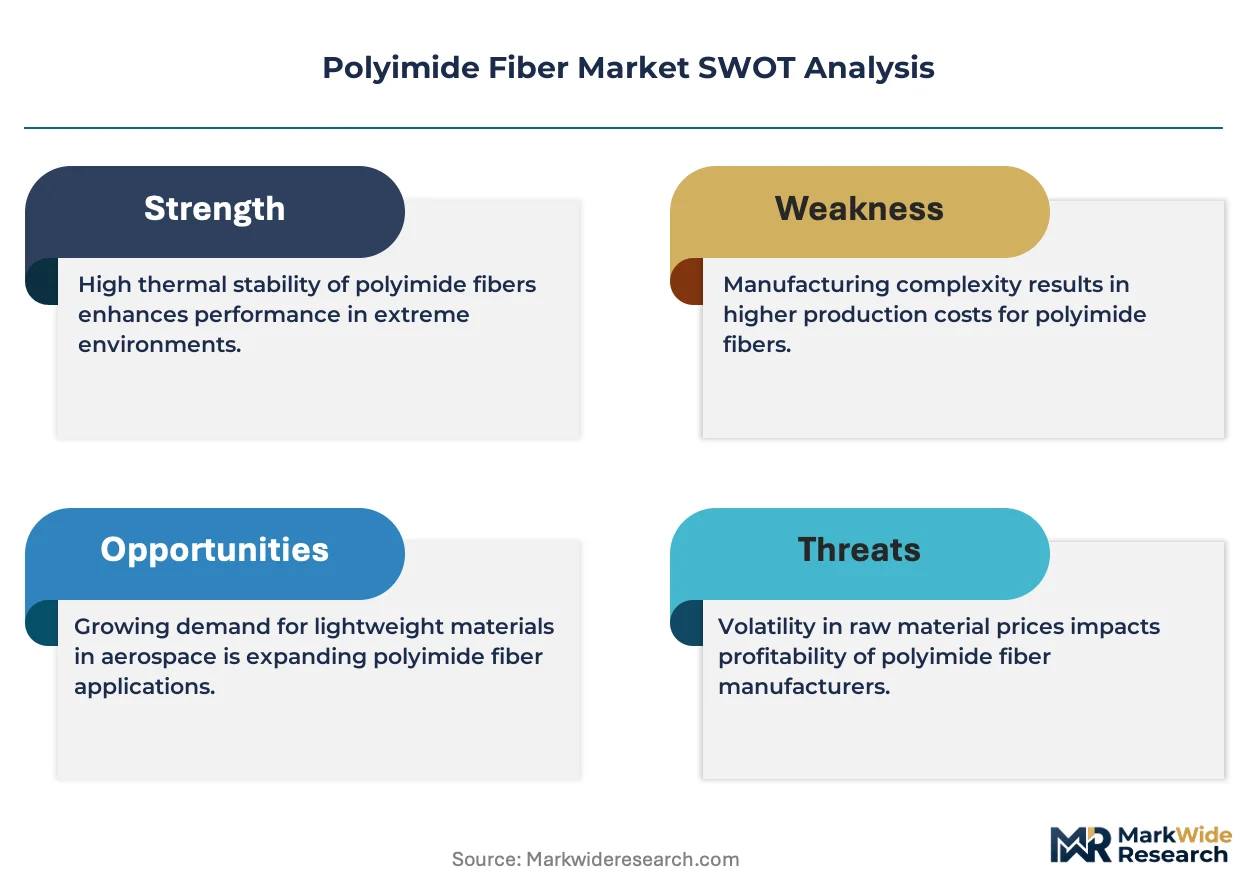
EPA emissions standards and OSHA workplace exposure limits govern US manufacturing facility compliance, while REACH and RoHS frameworks in Europe restrict hazardous substance content in electronics-grade fiber products. China's GB standards and MIIT industrial guidelines shape domestic certification pathways for export-bound material. Stakeholders must monitor evolving flame-retardancy test protocols across multiple jurisdictions and assess captive polymerization capacity as feedstock volatility reshapes cost structures.

Market Dynamics
Aerospace thermal management requirements are compressing qualification timelines for heat-resistant fiber suppliers, while electronics miniaturization in Shenzhen and Shanghai clusters pulls flexible polyimide formats into high-volume circuit substrate production.
Growth Catalysts
- Jet engine insulation retrofits:Commercial aviation fleets are replacing legacy ceramic blankets with lighter polyimide matting to meet FAA Part 25 fire-resistance mandates. MRO facilities in Georgia and Hamburg report accelerating contract awards.
- REACH Article 33 disclosure rules:European electronics OEMs are substituting halogenated flame retardants with inherently non-combustible polyimide layers to simplify supply chain compliance documentation.
- Metallurgy furnace modernization:Chinese steel producers around Tangshan are installing continuous polyimide conveyor belts to replace asbestos in 1600°C sintering operations under MIIT workplace safety directives.
Market Restraints
- Pyromellitic dianhydride feedstock volatility:Polymer-grade PMDA supply concentrates among three Chinese chemical conglomerates, exposing fiber producers to 90-day price swings that compress blending margin visibility.
- High-temperature spinning equipment scarcity:Wet-spinning lines capable of 400°C coagulation baths require 18-month lead times from specialized German and Japanese machinery builders, capping capacity expansion velocity.
- Aramid-carbon hybrid substitution:Aerospace structural applications below 250°C are migrating toward lower-cost para-aramid composites, constraining addressable volume for mid-performance polyimide grades.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor packaging and display fabrication are drawing polyimide film laminators to Gujarat and Tamil Nadu, creating captive fiber offtake.
- EV battery thermal runaway barriers:Cell-to-pack architectures are specifying milled polyimide nonwovens between lithium-ion modules, opening automotive volume absent from legacy aerospace-dominated demand curves.
- ISO 5660 cone calorimetry harmonization:Converging international flame-test protocols are reducing regional SKU fragmentation, enabling single-facility supply to multiple certification jurisdictions.
Industry Challenges
- Polymerization chemistry expertise scarcity:Fewer than 200 engineers globally possess production-scale experience with aromatic imide condensation kinetics, forcing competitors into bidding wars for technical leadership.
- Dual aerospace-electronics certification timelines:Simultaneous AS9100 and IATF 16949 audits require 14-18 months of documentation preparation, delaying revenue recognition for cross-sector suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Fiber Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aramid Fibers, Heat-Resistant Fibers, Composite Fibers, Flexible Fibers Application: Aerospace, Electronics, Automotive, Textiles End User: Manufacturers, Service Providers, Research Institutions, Government Agencies Form: Filament, Staple Fiber, Yarn, Fabric |
| Companies Covered | DuPont de Nemours, Inc., Evonik Industries AG, PPG Industries, Inc., Kaneka Corporation, PI Advanced Materials Co., Ltd., Ube Industries Ltd., Toray Industries Inc., Kolon Industries, Inc., Jiangsu Shino New Materials Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Fiber Market Strategic Shifts & Innovations
Melt-electrospinning of sub-micron polyimide filaments is collapsing the barrier between textile thermal protection and thin-film electronics, enabling multifunctional laminates that previously required separate material stacks.
Solution-blown nanofiber webs are electrifying protective apparel design by achieving 0.3-micron filtration efficiency at 40% lighter basis weights than spunbond alternatives. Firefighter equipment procurement offices in California and Bavaria are piloting these materials for next-generation turnout gear. The technology is compressing the traditional trade-off between breathability and thermal shielding that has constrained legacy nonwoven adoption.
EPA TSCA Section 6(h) restrictions on persistent organic pollutants are compelling US-based fiber finishers to eliminate perfluorinated water repellents from polyimide surface treatments. Formulators are migrating toward silicone-ceramic hybrid coatings that maintain hydrophobicity without triggering reporting thresholds. Electronics-grade fiber shipments to US contract manufacturers are experiencing 90-day qualification delays as coating chemistry transitions ripple through supply chains.
Foldable display manufacturers are consolidating vendor bases from six qualified polyimide film suppliers to three preferred partners with captive fiber spinning capability. Samsung Display and BOE Technology are requiring direct polymerization-to-film vertical integration to secure supply continuity for 2025-2026 product ramps. This concentration is visible most acutely in the Suwon and Hefei manufacturing corridors, where logistics costs and lot-to-lot consistency drive supplier selection above unit pricing.
Polyimide Fiber Market Segmentation
Polyimide fiber procurement follows distinct technical specifications across aerospace, electronics, and industrial verticals, with thermal performance thresholds and certification requirements fragmenting supplier qualification pathways. Each segmentation dimension reveals divergent margin structures and capacity investment priorities that reshape competitive positioning.
Product Type:
Thermal endurance specifications dominate buyer selection criteria, with continuous-use temperature ratings separating premium grades from commodity alternatives.
- Heat-Resistant Fibers:Engineered for sustained operation above 300°C with negligible mass loss, these fibers incorporate fully imidized aromatic backbones. Jet engine insulation retrofits at MRO facilities in Georgia and Hamburg concentrate procurement volume, driven by FAA Part 25 fire-resistance mandates that disqualify lower-temperature alternatives.
- Flexible Fibers:Optimized for repeated flex cycling without crack propagation or dielectric degradation, these grades feature controlled crystallinity and plasticized segments. Foldable electronics manufacturing in Suwon and Hefei corridors accelerates offtake as display manufacturers consolidate vendor bases toward vertically integrated suppliers.
- Composite Fibers:Prepreg-compatible formats with tailored surface chemistry for epoxy and bismaleimide matrices, serving satellite bus structures and unmanned aerial vehicle frames.
- Aramid Fibers:Hybrid aromatic polyamide-polyimide constructions offering intermediate thermal performance at reduced cost for industrial filtration and protective apparel.
Volume sits with Heat-Resistant Fibers; growth tilts toward Flexible Fibers.
Application:
End-use thermal management intensity determines fiber grade selection and supplier certification tier.
- Aerospace:Thermal protection systems for engine nacelles, thrust reversers, and auxiliary power units demand the highest purity grades with full traceability. AS9100 certification timelines of 14-18 months restrict supplier entry, concentrating procurement among heritage filament producers.
- Electronics:Flexible circuit substrates and battery thermal runaway barriers require thin-gauge fiber formats with precise dielectric constants. Cell-to-pack architectures in automotive battery systems are specifying milled polyimide nonwovens between lithium-ion modules.
- Automotive:EV battery compartment insulation and electric motor slot liners drive emerging demand for mid-performance grades with automotive IATF 16949 qualification.
- Textiles:Firefighter turnout gear and industrial protective clothing utilize solution-blown nanofiber webs achieving 0.3-micron filtration efficiency at reduced basis weights.
Revenue concentrates in Aerospace; Electronics demonstrates the steepest expansion trajectory.
End User:
Procurement scale and technical specification authority separate volume buyers from niche adopters.
- Manufacturers:Tier-1 aerospace component producers and electronics OEMs with captive polymerization capacity or long-term filament supply agreements.
- Service Providers:MRO facilities and contract manufacturers purchasing qualified fiber formats for retrofit and repair operations.
- Research Institutions:National laboratories and university consortia evaluating next-generation melt-electrospinning and solution-blowing processes.
- Government Agencies:Defense procurement offices specifying military-grade thermal protection with enhanced flame-retardancy protocols.
Procurement volume aggregates with Manufacturers; specification influence concentrates with Government Agencies.
Form:
Downstream processing compatibility and handling efficiency shape format selection across textile and composite manufacturing chains.
- Filament:Continuous monofilament and multifilament yarns for weaving and knitting operations, requiring precise denier control and surface finish consistency.
- Staple Fiber:Cut-length discontinuous fibers for nonwoven web formation and spinning blend applications in thermal insulation batts.
- Yarn:Twisted and plied constructions for braided sleeving and sewing threads in high-temperature gaskets and seals.
- Fabric:Woven, knitted, and nonwoven textile structures serving as preforms for composite lamination or finished thermal barriers.
Shipments concentrate in Filament formats; Fabric value-added processing captures expanding margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Shanghai anchor polyimide fiber demand concentration. China's MIIT directives on workplace safety and India's PLI scheme for electronics manufacturing are reshaping procurement geography. Industrial clusters in Tangshan, Suwon, and Gujarat are emerging as critical nodes for thermal protection systems and flexible circuit substrates.
United States
Jet engine insulation retrofits at MRO facilities in Georgia and commercial aviation hubs drive heat-resistant fiber procurement. FAA Part 25 fire-resistance mandates are accelerating substitution of legacy ceramic blankets with lighter polyimide matting. EPA TSCA Section 6(h) restrictions on persistent organic pollutants are forcing coating chemistry transitions at fiber finishing operations.
China
Steel producers around Tangshan are installing continuous polyimide conveyor belts to replace asbestos in 1600°C sintering operations. MIIT workplace safety directives mandate thermal protection upgrades across metallurgy operations. Shenzhen and Shanghai electronics manufacturing clusters are consolidating vendor bases for foldable display substrate supply.
Germany
Specialized machinery builders in Bavaria and Baden-Württemberg face 18-month order backlogs for wet-spinning lines capable of 400°C coagulation baths. REACH Article 33 disclosure rules are compelling electronics OEMs to substitute halogenated flame retardants with inherently non-combustible polyimide layers. Hamburg MRO facilities report accelerating contract awards for thermal protection retrofits.
South Korea
Display manufacturers in the Suwon corridor are requiring direct polymerization-to-film vertical integration from qualified suppliers. Samsung Display and BOE Technology are consolidating vendor bases to three preferred partners with captive fiber spinning capability. METI-aligned industrial guidelines support qualification timelines for aerospace-electronics dual certification.
India
PLI scheme subsidies for semiconductor packaging and display fabrication are drawing polyimide film laminators to Gujarat and Tamil Nadu. The country's national electronics regulator is establishing certification pathways for export-bound material. Captive fiber offtake is emerging from captive polymerization capacity investments in Ahmedabad and Chennai industrial corridors.
Polyimide Fiber Market Key Industry Players
Top-tier vendors anchor premium filament supply for aerospace certification pipelines, while mid-scale specialists occupy flexible electronics and industrial thermal protection segments. Heritage chemical conglomerates with aramid chemistry expertise sit alongside Asian integrated film-to-fiber converters. Strategic archetypes include captive polymerization operators, machinery-integrated spinners, and formulation-focused finishers. Capacity expansion and backward integration into dianhydride intermediates represent the dominant competitive vectors.
Within the heritage chemistry tier, DuPont de Nemours, Inc. and Evonik Industries AG exemplify premium-grade suppliers with established aerospace qualification pathways. Kaneka Corporation anchors Asian market positioning through integrated polyimide film-to-fiber conversion capabilities. These three entities represent distinct geographic and vertical integration archetypes rather than direct product competitors.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Evonik Industries AG |
| PPG Industries, Inc. |
| Kaneka Corporation |
| PI Advanced Materials Co., Ltd. |
| Ube Industries Ltd. |
| Toray Industries Inc. |
| Kolon Industries, Inc. |
| Jiangsu Shino New Materials Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Melt-electrospinning of sub-micron filaments is collapsing traditional cost structures by enabling single-facility production of multifunctional laminates that previously required separate material stacks, simultaneously concentrating supply power among machinery-integrated operators while fragmenting legacy spinning house margins.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with 18-month equipment backlogs from German and Japanese machinery builders forcing buyers to pay 15-25% markups for spot capacity versus long-term offtake agreements. Pricing stratifies across aerospace-certified, electronics-grade, and industrial-performance tiers, with AS9100 and IATF 16949 dual certification commanding substantial premiums over single-qualified alternatives. Cost compression in mid-performance grades is intensifying because para-aramid-carbon hybrids are displacing polyimide below 250°C applications. Electronics OEMs in Shenzhen and Shanghai clusters exhibit highest price sensitivity due to consolidated vendor bases, while aerospace MRO facilities in Georgia and Hamburg demonstrate lowest sensitivity given FAA Part 25 compliance mandates.
Supply Chain Analysis
Freight costs from Chinese dianhydride producers to European and North American fiber spinners have become a decisive factor in total delivered cost, with containerized chemical shipments facing extended transit times through Singapore and Rotterdam hubs. Pyromellitic dianhydride feedstock concentrates among three Chinese chemical conglomerates, while wet-spinning equipment sources from Germany and Japan, and coating chemistry formulators cluster in the US and Bavaria. Single-source vulnerability in polymer-grade PMDA exposes fiber producers to 90-day price swings that compress blending margin visibility. Distribution runs through qualified converter networks that manage AS9100 and REACH documentation chains for aerospace and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Melt-electrospinning and solution-blown nanofiber production methods are displacing legacy wet-spinning capacity, creating a technology-transition window where machinery access and polymerization chemistry expertise determine competitive survival.
For Market Incumbents: Anchor aerospace certification pipelines by locking 36-48 month offtake agreements with MRO facilities in Georgia and Hamburg before para-aramid substitution erodes addressable volume below 250°C applications. Prioritize backward integration into dianhydride intermediates to escape PMDA feedstock volatility from Chinese chemical conglomerates. Defend margin position by consolidating coating chemistry transitions ahead of EPA TSCA Section 6(h) enforcement deadlines.
For New Entrants and Emerging Players: Direct-to-film laminator partnerships in Gujarat and Tamil Nadu offer the most penetrable entry vector, bypassing 14-18 month AS9100 certification barriers while capturing PLI scheme subsidies for semiconductor packaging demand. Target EV battery thermal runaway barrier specifications from cell-to-pack architects seeking milled polyimide nonwovens between lithium-ion modules. Establish toll-spinning arrangements with underutilized wet-spinning capacity in South Korea to avoid 18-month equipment lead times.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Asian integrated film-to-fiber converters seeking European aerospace certification assets, with secondary liquidity through private equity recapitalizations of machinery-integrated specialists. Long-term viability over the five-to-ten year horizon hinges on captive polymerization capacity and dual AS9100-IATF 16949 qualification timelines. Monitor ISO 5660 cone calorimetry harmonization progress as the inflection signal for regional SKU consolidation enabling single-facility global supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Intermediates | Captive PMDA supply insulates fiber producers from Chinese feedstock volatility and 90-day price swings. |
| Dual Certification Investment (AS9100 + IATF 16949) | Simultaneous aerospace-automotive qualification opens EV battery thermal barrier revenue streams. |
| Melt-Electrospinning Capacity Buildout | Sub-micron filament production collapses cost structures for multifunctional electronics laminates. |
| Long-Term Supply Agreement with MRO Networks | FAA Part 25 retrofit mandates in Georgia and Hamburg secure 36-48 month revenue visibility. |
| Coating Chemistry Transition Partnership | Silicone-ceramic hybrid development eliminates perfluorinated water repellents ahead of EPA TSCA Section 6(h) deadlines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving plant managers at fiber spinning facilities, procurement leads at aerospace MRO networks, technical R&D directors at coating formulators, and distribution channel partners managing REACH documentation chains. Bottom-up and top-down triangulation validated volume estimates against ACC and Cefic chemical industry reports, SEC 10-K disclosures from listed materials companies, and MIIT industrial guideline publications.
Reconciliation of production capacity databases with end-use demand surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include thermal performance tier, end-use vertical, fiber format, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating jet engine retrofit cycles, foldable electronics ramp schedules, and EV battery thermal barrier adoption curves.
Inputs from machinery builders and polymerization specialists were available through the study window; gaps in real-time PMDA spot pricing and 18-month equipment order backlogs introduce uncertainty bands around capacity expansion timing. Forecasts reflect documented assumptions regarding REACH Article 33 enforcement intensity and FAA Part 25 retrofit compliance deadlines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Polyester Filament Market