
 Polyester Fibers Market | 2026-2036
Polyester Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Fibers Market Analytics
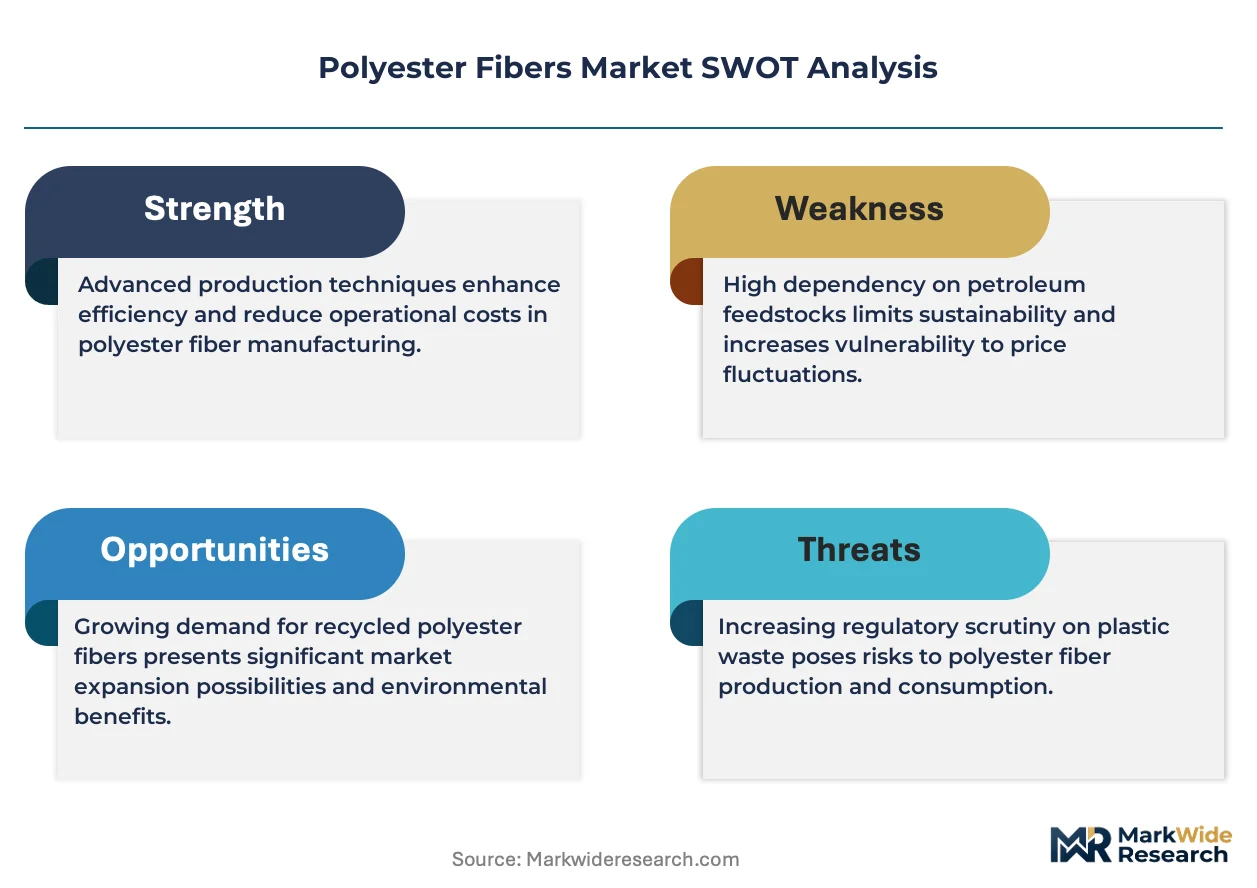
REACH compliance in Europe is pivoting capital allocation toward virgin-alternative chemistries and closed-loop recycling infrastructure. Indorama Ventures leverages its integrated PET-to-fiber platform across Thailand and Europe to sustain cost advantages under tightening chemical disclosure rules. Toray Industries anchors high-performance filament fiber supply for automotive airbag and tire cord applications where specification thresholds exceed commodity grades. Zhejiang Hengyi competes on scale in staple fiber for home textile exports, though its exposure to EU due diligence rules on forced labor risks complicates channel control.
Polyester fibers are synthetic polymers manufactured from purified terephthalic acid and ethylene glycol through melt-spinning processes, yielding filaments with tenacities ranging from 2.5 to 9.0 grams per denier depending on draw ratios and heat-setting protocols. These fibers serve primarily as cost-efficient, durable inputs for woven and nonwoven fabrics across apparel, industrial, and construction end uses. Recycled polyester fiber draws structural investment as brand sustainability mandates and regulatory recycled-content floors expand addressable volume, while specialty polyester fiber commands margin premiums in medical textiles and high-temperature filtration media where standard grades fail performance specifications. Polyester staple fiber retains volume leadership in bedding and furnishing applications where bulk and crimp recovery dictate purchasing decisions.
FDA textile contact standards, EU ECHA restrictions on antimony catalyst residues, and China's GB 18401 national textile safety code collectively shape fiber chemistry choices, finishing agent portfolios, and export market access protocols. The EU Green Deal's carbon border adjustment mechanism and evolving extended producer responsibility frameworks in California and New York will redirect investment toward chemically recycled and bio-based feedstock routes. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity in noncompliant chemistries and processes.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is redirecting capital flows toward chemically recycled feedstock routes while compressing margins on conventional virgin production. This regulatory pressure intersects with apparel brand sustainability mandates to restructure procurement relationships across the value chain.
Growth Catalysts
- EU ECHA antimony restrictions:Tightening residue limits on catalyst traces in fiber chemistry are accelerating closed-loop recycling infrastructure investments as brands seek compliant virgin alternatives.
- Automotive airbag specifications:High-tenacity filament requirements exceeding 8.0 grams per denier are creating durable demand pockets immune to commodity price cycles.
- India's textile export expansion:Integrated polyester staple fiber capacity serving both domestic mills and international buyers is concentrating volume leadership in South Asian supply chains.
Market Restraints
- PTA-MEG input cost volatility:Purified terephthalic acid and ethylene glycol prices track naphtha and paraxylene spreads, compressing spinning margins during upstream petrochemical cycles.
- China due diligence exposure:EU forced labor regulations targeting Xinjiang-origin cotton are extending scrutiny to polyester fiber channels, complicating export access for non-compliant suppliers.
- Mechanical recycling degradation:PET flake viscosity loss limits recycled fiber to lower-tenacity applications, blocking circular feedstock from performance-grade markets.
Strategic Opportunities
- Bio-based glycol routes:Ethylene glycol derived from biomass feedstocks offers compliance pathways under EU Green Deal carbon intensity thresholds for premium brand contracts.
- Medical textile specifications:Antimicrobial and biocompatible polyester grades for surgical meshes and implantable fabrics command 3-4x commodity staple premiums with lower volume volatility.
- Extended producer responsibility frameworks:California and New York state-level EPR legislation is creating mandated offtake agreements that secure long-term recycled fiber demand.
Industry Challenges
- Chemical recycling capex intensity:Depolymerization and repolymerization facilities require $200-400 million per 100,000-tonne unit, straining mid-scale producer balance sheets.
- GB 18401 certification timelines:China's national textile safety code testing protocols for formaldehyde and pH levels extend export clearance cycles by 4-6 weeks.
- Legacy melt-spinning retrofit complexity:Converting staple fiber lines to handle chemically recycled PET with varying intrinsic viscosity requires screw redesign and quench system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Fibers Market |
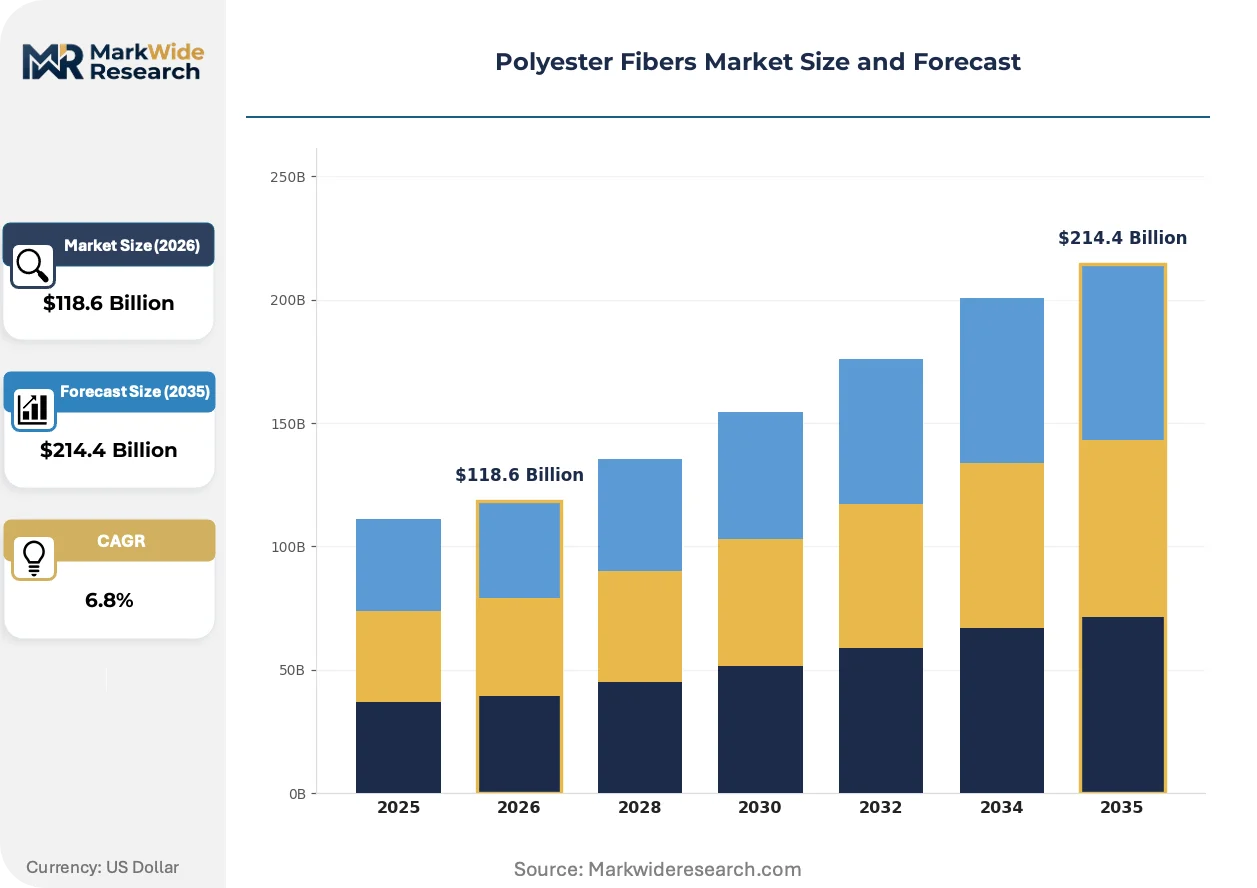
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Staple Fiber, Polyester Filament Fiber, Recycled Polyester Fiber, Specialty Polyester Fiber Application: Textiles, Automotive Upholstery, Geo-Textiles, Industrial Fabrics End User: Fashion Industry, Home Furnishings, Construction, Automotive Sector Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Reliance Industries Limited, Indorama Ventures Public Company Limited, Toray Industries Inc., Zhejiang Hengyi Group Co., Ltd, Sinopec Yizheng Chemical Fiber Limited Liability Company, Alpek S.A.B. de C.V., INVISTA, NAN YA PLASTICS CORPORATION, The Dow Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Fibers Market Evolving Landscape
Electrochemical reduction of terephthalic acid derivatives is opening bio-synthetic hybrid pathways that bypass conventional petrochemical cracking. These process innovations are compressing the carbon intensity gap between virgin and circular production.
Enzymatic PET depolymerization is electrifying the recycling technology landscape by operating at ambient temperatures with 95% monomer recovery rates. Textile-to-textile processors in the Netherlands and Japan are piloting 10,000-tonne annual units. This technology is electrifying cost structures for food-grade rPET applications previously blocked by mechanical degradation limits.
REACH authorization list expansion for microplastic release restrictions is forcing reformulation of fiber finishing agents across European supply chains. Spin finish suppliers are migrating from silicone-based lubricants to bio-derived alternatives to maintain downstream compliance. Home textile exporters to Germany and France face the steepest reformulation timelines under 2025 implementation deadlines.
Brand-led fiber provenance verification is restructuring supplier relationships away from spot-market purchasing toward multi-year traceability contracts. Outdoor apparel manufacturers now require blockchain-tracked recycled content certificates from spinning partners. This pattern is most pronounced in Nordic markets where consumer willingness-to-pay for verified circular content exceeds Southern European benchmarks by 15-20 percentage points.
Polyester Fibers Market Segmentation

Segmentation in polyester fibers reveals divergent margin profiles across commodity and specialty grades. Procurement patterns split between volume-driven staple contracts and specification-bound filament agreements.
Product Type:
Volume leadership sits with staple fiber while premium capture concentrates in specialty and recycled grades.
- Polyester Staple Fiber:Cut-length fibers ranging 1.5-15 denier serve bulk textile applications through ring and open-end spinning systems. India's Reliance Industries anchors global capacity serving bedding and apparel mills across South Asia. PTA-MEG cost volatility compresses spinning margins during upstream petrochemical cycles.
- Recycled Polyester Fiber:rPET flake-derived filaments face intrinsic viscosity degradation limiting mechanical recycling to lower-tenacity applications. EU Green Deal carbon border adjustments redirect brand procurement toward chemically recycled feedstock routes with compliant carbon intensity thresholds.
- Polyester Filament Fiber:Continuous extruded filaments deliver tenacities of 2.5-9.0 grams per denier for woven industrial fabrics.
- Specialty Polyester Fiber:Medical-grade and high-temperature filtration variants command substantial premiums in surgical mesh and industrial media.
Today's leader: Polyester Staple Fiber. Tomorrow's challenger: Recycled Polyester Fiber.
Application:
End-use diversification spreads risk across cyclical apparel and durable industrial demand.
- Textiles:Woven and knitted fabrics consume the majority staple fiber volume for apparel and home furnishing end uses. India's export expansion concentrates spinning demand in Surat and Tiruppur clusters.
- Automotive Upholstery:High-tenacity filament requirements for seat fabrics and interior trim specify abrasion resistance exceeding 50,000 Martindale cycles.
- Geo-Textiles:Staple fiber nonwovens provide soil stabilization and drainage functions in civil engineering projects.
- Industrial Fabrics:Conveyor belts and filtration media demand specialized heat-set and coating treatments.
Textiles anchor current volume. Automotive upholstery offers the steepest expansion trajectory as electric vehicle production scales.
End User:
Customer concentration varies from fragmented fashion procurement to consolidated automotive supply agreements.
- Fashion Industry:Brand sustainability mandates are restructuring supplier relationships toward multi-year traceability contracts with blockchain-verified recycled content. EU ECHA antimony restrictions accelerate closed-loop chemistry adoption.
- Home Furnishings:Bedding and upholstery manufacturers prioritize bulk and crimp recovery in staple fiber purchasing decisions.
- Construction:Geo-textile and roofing membrane applications specify UV-stabilized grades for infrastructure durability.
- Automotive Sector:Airbag and tire cord applications demand filament tenacities exceeding 8.0 grams per denier with zero defect tolerances.
Fashion industry procurement is shifting fastest. Automotive sector contracts deliver the most durable demand insulation.
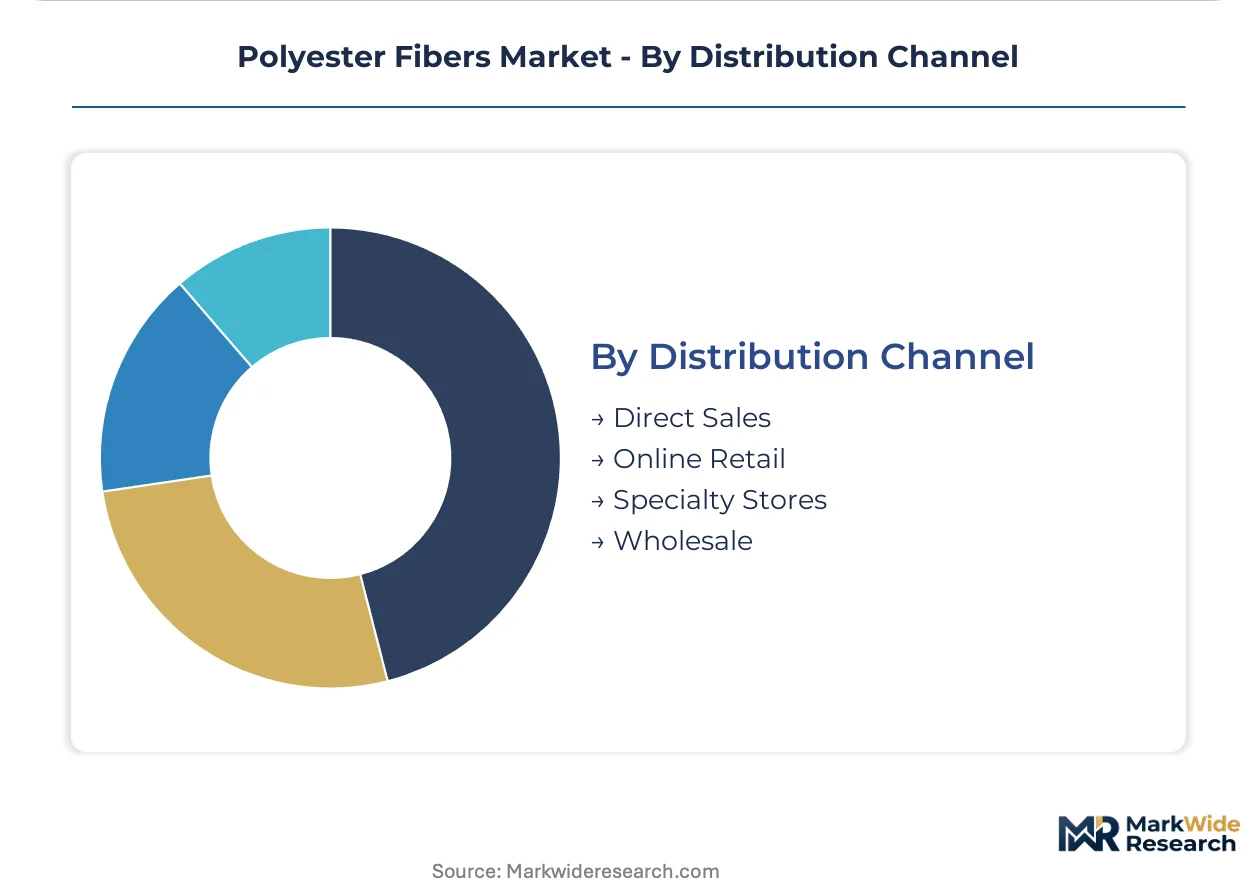
Distribution Channel:
Channel selection tracks order scale and specification complexity across customer tiers.
- Direct Sales:Mill-direct contracts dominate staple fiber volume for integrated textile producers with predictable consumption profiles.
- Wholesale:Distributor networks serve mid-scale converters lacking direct mill relationships or requiring blended fiber assortments.
- Specialty Stores:Technical fiber grades for medical and industrial applications route through specialized distributors with formulation expertise.
- Online Retail:E-commerce channels capture small-lot specialty fiber sales for research and prototyping applications.
Direct sales command current volume leadership. Online retail is gaining share fastest in specialty and sample-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled textile engineering talent concentrates in South Asian spinning clusters and East Asian chemical processing corridors, anchoring polyester fiber production capacity and export competitiveness across multiple regulatory jurisdictions.
China
Zhejiang and Jiangsu provinces host the world's largest PTA-MEG conversion capacity, feeding melt-spinning operations in Shaoxing and Suzhou industrial zones. GB 18401 national textile safety code testing extends export clearance cycles by 4-6 weeks for formaldehyde and pH certification. The Yangtze River Delta chemical fiber cluster faces escalating EU due diligence scrutiny on supply chain transparency.
India
Gujarat and Maharashtra states concentrate polyester staple fiber spinning capacity serving Surat's synthetic textile weaving belt and Tiruppur's knitwear export hub. The Production Linked Incentive scheme for man-made fibers and technical textiles redirects capital toward integrated fiber-to-fabric investments. Reliance Industries anchors massive PTA and staple fiber operations in Jamnagar and Hazira.
United States
Southeastern states concentrate carpet-grade staple fiber demand and automotive upholstery supply chains near OEM assembly plants. EPA industrial emissions standards and California's extended producer responsibility framework reshape recycling infrastructure investment toward chemically recycled feedstock routes. The Carolina textile corridor retains specialized industrial filament capacity for tire cord and airbag applications.
Germany
REACH authorization list expansion for microplastic release restrictions forces spin finish reformulation across Baden-Württemberg and North Rhine-Westphalia processing centers. KBA automotive safety specifications drive high-tenacity filament demand for seatbelt and airbag integration. The ChemCycling initiative accelerates depolymerization pilot projects in Ludwigshafen chemical parks.
Thailand
Eastern Economic Corridor petrochemical integration supports PET resin-to-fiber conversion serving ASEAN textile export markets. Board of Investment incentives for green industry projects attract bio-based glycol pilot investments. Indorama Ventures leverages integrated operations across Rayong and Map Ta Phut industrial estates to sustain cost advantages under tightening chemical disclosure rules.
Polyester Fibers Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical-to-fiber conglomerates with captive PTA-MEG supply and scale-driven commodity producers competing on volume throughput. Tiered positioning separates high-performance filament specialists from staple fiber volume leaders and emerging recycled fiber technology developers. Strategic moves center on backward integration into purified terephthalic acid production and chemical recycling joint ventures securing brand offtake agreements.
Among Asia-Pacific-based integrated producers, Reliance Industries Limited and Indorama Ventures Public Company Limited exemplify the petrochemical-backward archetype with captive feedstock control, while Toray Industries Inc. occupies the high-performance filament specialist tier serving specification-bound automotive and industrial applications. These three anchors demonstrate divergent strategic postures across commodity scale, vertical integration depth, and technical specification capture.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| Indorama Ventures Public Company Limited |
| Toray Industries Inc. |
| Zhejiang Hengyi Group Co., Ltd |
| Sinopec Yizheng Chemical Fiber Limited Liability Company |
| Alpek S.A.B. de C.V. |
| INVISTA |
| NAN YA PLASTICS CORPORATION |
| The Dow Chemical Co. |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon intensity thresholds gate qualified supply for premium-tier polyester fiber contracts, compressing margins on conventional virgin production while rewarding chemically recycled and bio-based glycol routes with brand procurement access. This sustainability mandate redirects capital toward compliant feedstock infrastructure, bifurcating the market between certified low-carbon supply and stranded conventional capacity.
Pricing Analysis
Commodity spot contracting dominates virgin staple fiber transactions, while premium-mid-economy pricing differentiation separates chemically recycled grades, bio-based specialty fibers, and standard commodity supply. Certification level under EU ECHA antimony restrictions and blockchain-verified recycled content drive price spreads between compliant and non-compliant supply. Cost compression in virgin staple fiber is intensifying because PTA-MEG input volatility tracks naphtha and paraxylene spreads. Fast-fashion procurement teams exhibit highest price sensitivity, while automotive airbag and medical textile buyers accept substantial premiums for specification-grade filament.
Supply Chain Analysis
Skilled textile engineering talent availability in Surat and Tiruppur anchors India's polyester staple fiber spinning dominance, while Zhejiang and Jiangsu provinces concentrate China's PTA-MEG conversion and melt-spinning operations. Purified terephthalic acid, ethylene glycol, and PET flake feedstock draw from integrated petrochemical complexes and mechanical recycling collection networks. Single-source vulnerability concentrates in Reliance Industries' captive PTA supply and Indorama Ventures' integrated PET-to-fiber platforms. Distribution runs through mill-direct contracts for integrated textile producers, with wholesale networks serving mid-scale converters requiring blended fiber assortments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification-grade filament and chemically recycled fiber command durable margin premiums. Demand is shifting toward high-tenacity automotive and medical applications where performance thresholds exceed commodity-grade capabilities.
For Market Incumbents: Anticipate regulatory divergence between EU ECHA restrictions and China's GB 18401 certification timelines by securing dual-jurisdiction compliance infrastructure. Backward integration into chemically recycled PET depolymerization protects margin position against virgin feedstock volatility. Capacity addition in India's Gujarat and Maharashtra textile clusters captures Production Linked Incentive scheme benefits while hedging China due diligence exposure. For New Entrants and Emerging Players: Enter via enzymatic PET depolymerization technology licensing to bypass mechanical recycling viscosity degradation limits blocking circular feedstock from performance-grade markets. Medical textile specifications for antimicrobial and biocompatible polyester grades offer the most penetrable white space with 3-4x commodity staple premiums. Go-to-market positioning should target Nordic outdoor apparel brands with blockchain-tracked recycled content certificates. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale chemical recycling technology developers because extended producer responsibility frameworks in California and New York mandate long-term offtake agreements securing recycled fiber demand. Five-to-ten-year viability hinges on acquiring platforms with pilot-scale depolymerization units and brand partnership pipelines. The signal to watch is EU carbon border adjustment mechanism implementation triggering accelerated brand procurement shifts toward compliant feedstock routes.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Depolymerization facility investments unlock food-grade rPET applications previously blocked by mechanical degradation limits. |
| Backward Integration into PTA | Captive purified terephthalic acid production insulates spinning margins from naphtha and paraxylene spread volatility. |
| Bio-Based Glycol Pilot Investment | Biomass-derived ethylene glycol routes secure EU Green Deal carbon intensity compliance for premium brand contracts. |
| Medical Grade Certification | FDA textile contact standards and biocompatibility protocols command 3-4x commodity staple premiums in surgical mesh applications. |
| Blockchain Traceability Implementation | Verified recycled content certificates restructure supplier relationships toward multi-year contracts with Nordic outdoor apparel brands. |
Research Methodology
Bottom-up textile end-use modeling reconciled against top-down polyester fiber production capacity tracking forms the analytical core of this study. Primary interviews with spinning mill procurement directors, petrochemical plant managers, apparel brand sustainability officers, and automotive Tier 1 supplier quality engineers combined with secondary validation from customs trade data, SEC 10-K filings, EU ECHA substance restriction databases, and India's DGFT export statistics. Triangulation across these sources ensures demand-side consumption patterns align with supply-side capacity utilization.
Historical trendline analysis of staple and filament fiber production volumes, trade flows, and input cost spreads established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, application end-use, customer industry, and regional production hub dimensions. CAGRs were derived from regression analysis against macro drivers including petrochemical feedstock pricing, regulatory compliance cost escalation, and brand sustainability procurement mandates. Industry-specific forecast inputs included PTA-MEG spread projections and EU carbon border adjustment mechanism implementation timelines.
The model holds under stable petrochemical feedstock pricing and gradual regulatory implementation; deviation in naphtha price volatility or accelerated EU due diligence enforcement would shift capacity utilization and margin projections. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Spandex Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Synthetic Fabric Market