
 Designer Fiber Market | 2026-2036
Designer Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Designer Fiber Market Analytics
Premium-grade lyocell and regenerated cellulose specifications is rotating demand away from commodity viscose across apparel and home furnishing channels. Lenzing AG leverages its Tencel-branded fiber platform to anchor supply relationships with European luxury textile mills. Toray Industries dominates carbon fiber derivatives for automotive and aerospace interiors through its Japanese production base. Grasim Industries competes on viscose staple fiber scale from its Indian manufacturing complexes, supplying South Asian and Middle Eastern weaving operations.
Designer fiber denotes engineered textile filaments and staple fibers manufactured to precise denier, tenacity, and moisture-management specifications for aesthetic and functional performance applications. Production employs solvent-spinning, melt-blowing, and controlled crimping processes to achieve targeted hand-feel, drape, and dye-affinity profiles for fashion and technical end-uses. Synthetic fiber formulations currently lead volume throughput due to cost scalability, while bamboo-derived cellulosics represent the fastest-expanding category as brands pursue biodegradable alternatives to petroleum-based inputs. Apparel applications command the deepest margin pools through direct designer-label partnerships, whereas industrial textiles segment growth concentrates in filtration and reinforcement geotextiles.
EPA chemical reporting obligations and REACH substance restrictions in Europe constrain formulation choices for synthetic fiber producers seeking transatlantic market access. China's GB standards and MIIT industrial policy directives shape domestic capacity expansion and export qualification protocols for regenerated cellulosic fibers. Stakeholders must monitor regulatory divergence between biodegradable certification schemes and conventional petrochemical fiber standards to anticipate which production configurations will retain cross-border eligibility.
Market Dynamics
Automotive OEMs are substituting conventional interior materials with lightweight engineered textiles at scale, creating a structural pull that reconfigures supplier relationships and capacity allocation across the value chain.
Growth Catalysts
- REACH substance restrictions:European chemical disclosure mandates are accelerating substitution of conventional synthetics with certified biodegradable alternatives, opening qualification pathways for regenerated cellulosic producers.
- Automotive lightweighting mandates:Interior textile specifications are tightening weight and flammability standards, driving engineered fiber adoption for seating, headliner, and trim applications.
- Chinese MIIT industrial policy:Domestic capacity expansion directives for high-performance fibers are channeling state-backed investment toward lyocell and carbon fiber derivative production.
Market Restraints
- Petrochemical input volatility:Crude oil and purified terephthalic acid price swings compress margin predictability for polyester and nylon staple fiber operations.
- Italian spinning concentration:Premium worsted and wool-blend fiber finishing capacity clusters in Northern Italy, creating geographic supply risk for luxury apparel brands.
- Viscose substitution ceiling:Technical performance gaps in moisture management and tensile strength limit bamboo-derived cellulosics from displacing synthetics in industrial filtration.
Strategic Opportunities
- Indian technical textile expansion:BIS certification harmonization and PLI scheme incentives are opening domestic geotextile and reinforcement fiber markets to specialized producers.
- Closed-loop solvent recycling:Convergence of membrane filtration and solvent recovery systems is enabling lyocell producers to achieve near-zero discharge at commercial scale.
- Direct-to-mill digital platforms:B2B fiber marketplaces are compressing trader margins and allowing specialty spinners to access small-lot engineered fiber directly from producers.
Industry Challenges
- Colorist and dye-affinity expertise scarcity:Formulation chemists capable of matching engineered fiber surface chemistry to waterless dyeing systems command premium compensation and limited availability.
- Biodegradable certification timeline fragmentation:Divergent OECD, ASTM, and EU soil-compostability test protocols delay product launch cycles and inflate third-party validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Designer Fiber Market |
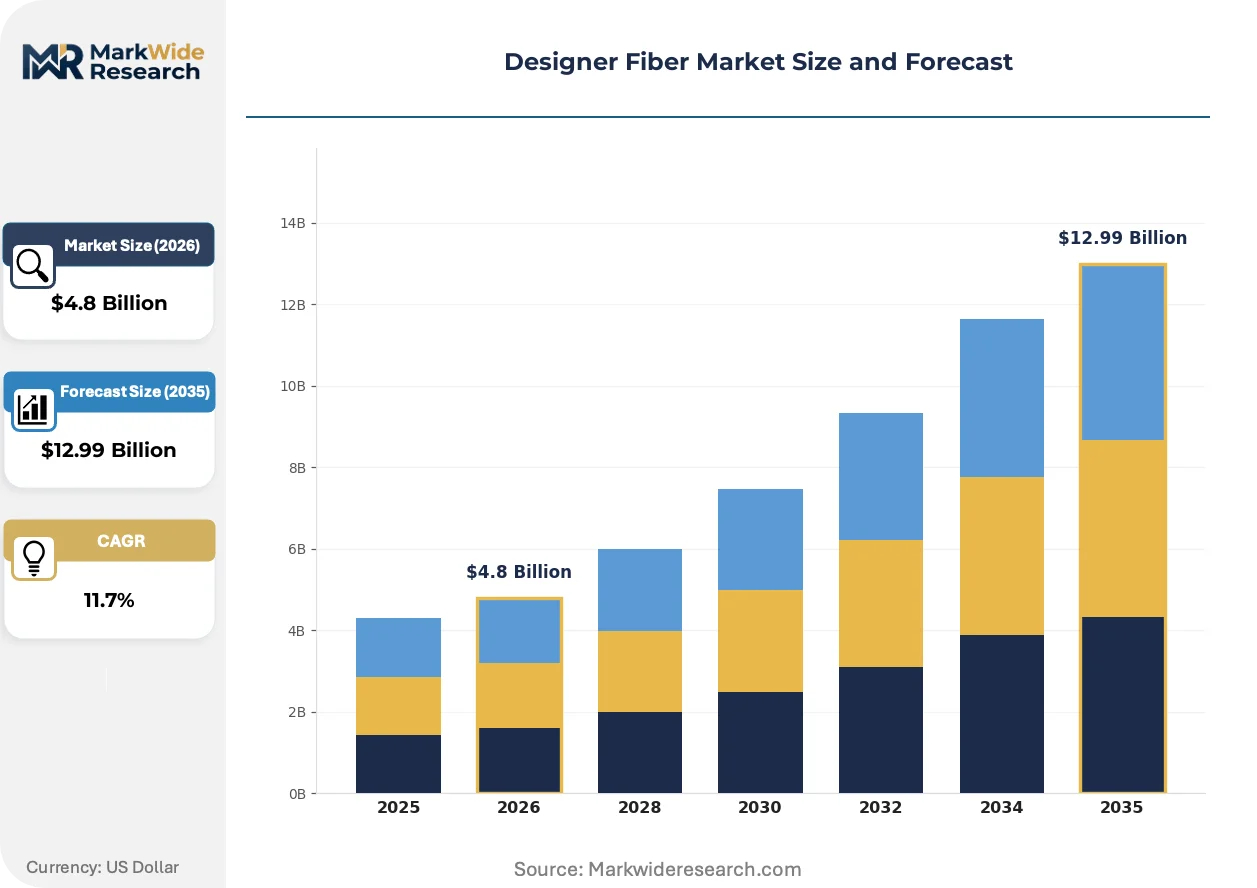
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silk, Wool, Bamboo, Synthetic Fiber End User: Textile Manufacturers, Fashion Designers, Upholstery, Specialty Fiber Producers Application: Apparel, Home Furnishings, Industrial Textiles, Automotive Interiors Technology: Weaving, Knitting, Non-Woven, Hybrid Techniques |
| Companies Covered | Lenzing AG, Toray Industries, Inc., Teijin Ltd., DuPont, Hexcel Corporation, Grasim Industries Ltd., Mitsubishi Chemical Group, SGL Carbon, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Designer Fiber Market Evolving Landscape
Three intersecting developments are compressing traditional fiber qualification cycles and elevating performance specifications across both apparel and technical end-uses.
Melt-electrospinning of sub-micron fiber webs is miniaturizing filtration media pore structures while maintaining mechanical integrity. Medical and HVAC filtration OEMs are qualifying these nanofiber laminates for HEPA-equivalent performance at reduced pressure drop. The technology is compressing incumbent melt-blown polypropylene margins in industrial air filtration.
ECHA's expanding SVHC candidate list is forcing reformulation of flame-retardant synthetic fiber additives ahead of 2025 sunset reviews. Automotive interior suppliers are accelerating halogen-free phosphorus-nitrogen compound adoption to maintain REACH compliance for seating and carpet applications. German KBA type-approval processes are now rejecting fiber submissions with legacy brominated retardant chemistries.
Brand-led fiber provenance verification is displacing traditional commodity spot purchasing for premium apparel collections. European luxury textile mills are mandating blockchain-tracked cellulose origin documentation from dissolving pulp suppliers. This behavioral shift concentrates procurement relationships with vertically integrated producers in Austria and India who control pulp-to-fiber traceability.
Designer Fiber Market Segmentation
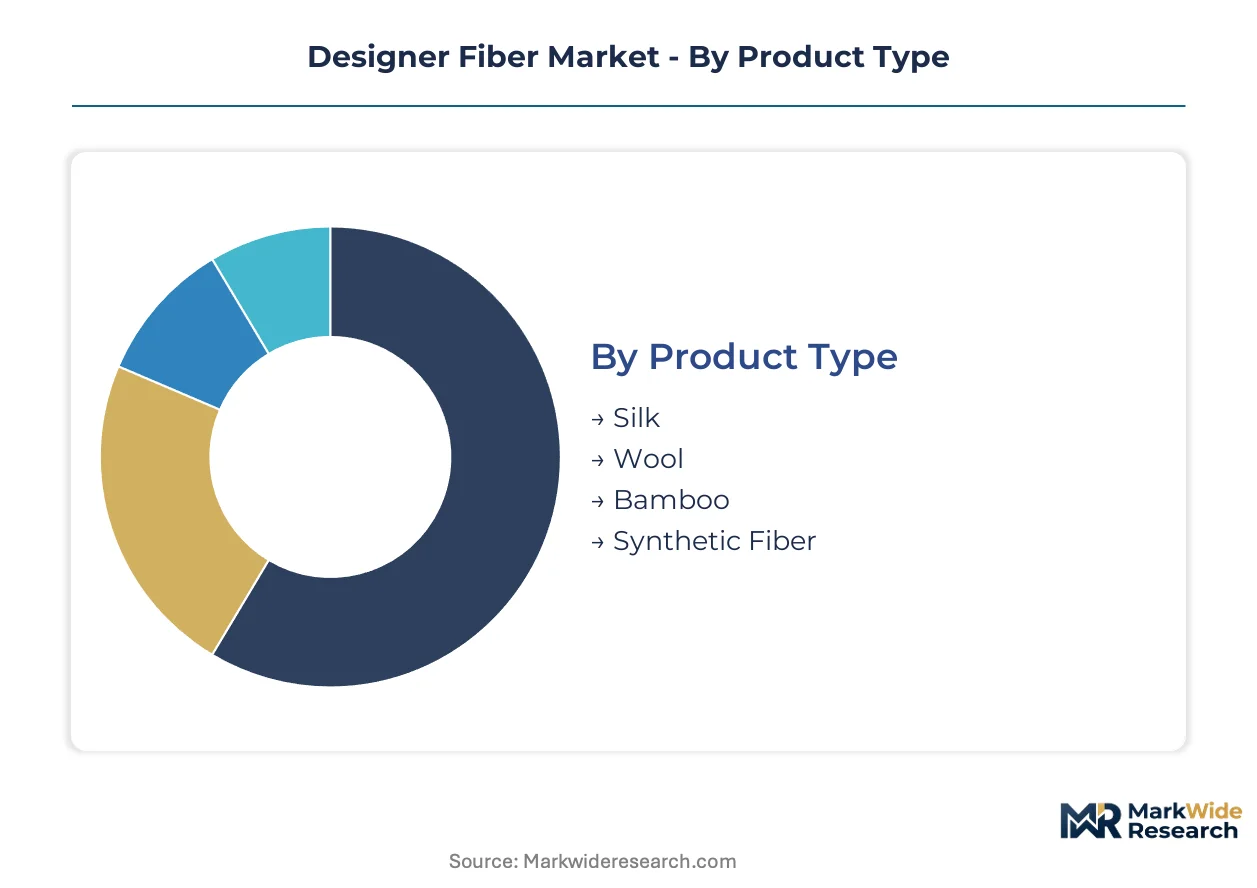
Designer fiber procurement patterns diverge sharply across end-use specifications, with margin capture varying by technical complexity and certification requirements. Understanding these segment boundaries clarifies where capacity investments and formulation R&D yield durable returns versus commodity exposure.
Product Type:
Premium protein-based and engineered cellulosic specifications command the widest spreads, while commodity synthetics compete on throughput scale.
- Silk:Mulberry and tussah silk filaments retain unmatched tensile elongation and natural luster for luxury apparel applications. Italian and Chinese weaving clusters in Como and Suzhou concentrate demand for 20/22 denier raw silk grades, though sericulture labor shortages constrain volume expansion.
- Wool:Merino superfine grades below 19.5 micron anchor premium suiting and knitwear specifications. Australian clip auctions and South African Cape wool exports supply European worsted spinners, with micron-specific procurement contracts insulating margin volatility from broader fiber commodity swings.
- Bamboo:Regenerated viscose and lyocell-processed bamboo pulp serves sustainability-positioned apparel brands seeking biodegradable alternatives. Chinese Sichuan and Zhejiang processing hubs dominate dissolving pulp supply.
- Synthetic Fiber:Polyester, nylon, and acrylic staple formulations compete on dye-affinity engineering and denier precision for mass-market apparel and technical nonwovens. Petrochemical input cost linkage compresses margin stability versus natural fiber counterparts.
The dominant share belongs to Synthetic Fiber, while Bamboo is closing the gap fastest.
End User:
Customer type determines order fragmentation, with direct designer relationships rewarding small-lot flexibility and technical textile OEMs demanding certification depth.
- Textile Manufacturers:Integrated spinning-weaving operations in India, Turkey, and Vietnam purchase fiber on specification contracts tied to finished fabric export orders. REACH and OEKO-TEX certification requirements filter supplier eligibility for European-bound shipments.
- Fashion Designers:Direct fiber selection for capsule collections and runway prototypes drives small-batch premium pricing. Milan, Paris, and New York studio procurement prioritizes hand-feel drape and exclusive color development over unit cost.
- Upholstery:Contract furniture and residential fabric mills specify abrasion-resistant synthetic blends and solution-dyed acrylics. North Carolina and Belgium manufacturing clusters concentrate demand for heavy-duty performance certifications.
- Specialty Fiber Producers:Carbon fiber precursor, aramid, and high-tenacity industrial yarn manufacturers source purified polymer feedstocks and custom additive packages. Toray Industries and Teijin anchor Japanese supply relationships for aerospace and automotive tier-1 qualification.
Textile Manufacturers absorb the highest volume, though Specialty Fiber Producers generate the steepest per-kilogram returns.
Application:
Functional performance requirements separate industrial qualification cycles from fashion-driven seasonal procurement.
- Apparel:Seasonal collections drive cotton, viscose, and polyester staple demand with color-fastness and shrinkage specifications. Fast-fashion volume retailers in Spain and Sweden compress lead times, while luxury houses in France and Italy extend development calendars for proprietary fiber finishes.
- Home Furnishings:Curtain, bedding, and carpet applications prioritize lightfastness and soil-release chemistry. Belgian and Portuguese weaving operations supply European retail chains with flame-retardant synthetic blends meeting domestic furniture standards.
- Industrial Textiles:Filtration media, reinforcement geotextiles, and conveyor belting demand precise tenacity and chemical resistance. German and US engineering firms qualify fiber submissions through extended wear testing protocols.
- Automotive Interiors:Seating, headliner, and trim specifications from BMW, Mercedes-Benz, and Toyota Motor tighten flammability and fogging standards. Lightweighting mandates accelerate substitution of leather and conventional plastics with engineered textile laminates.
Apparel retains the deepest revenue pool, yet Automotive Interiors is expanding most quickly as OEMs redesign cabin materials.
Technology:
Process selection locks in capital intensity and minimum efficient scale, with hybrid systems commanding premium positioning.
- Weaving:Shuttle and projectile looms produce structured fabrics with defined warp-weft interlacing for suiting and shirting. Northern Italy and Japan retain leadership in complex jacquard and dobby patterning for luxury applications.
- Knitting:Circular and flat-bed machines yield stretch and drape characteristics for activewear and intimate apparel. Turkish and Bangladeshi operations scale weft-knit production for European brand supply chains.
- Non-Woven:Spunbond, melt-blown, and needle-punch processes manufacture filtration media, hygiene products, and geotextiles without yarn intermediate steps. Reicofil and Oerlikon equipment lines dominate Chinese and Southeast Asian capacity additions.
- Hybrid Techniques:Combined knitting-weaving and warp-insertion systems fuse structural stability with elastic recovery for technical sportswear and medical textiles. Japanese machinery builders Shima Seiki and Stoll export programmable systems enabling small-lot customization.
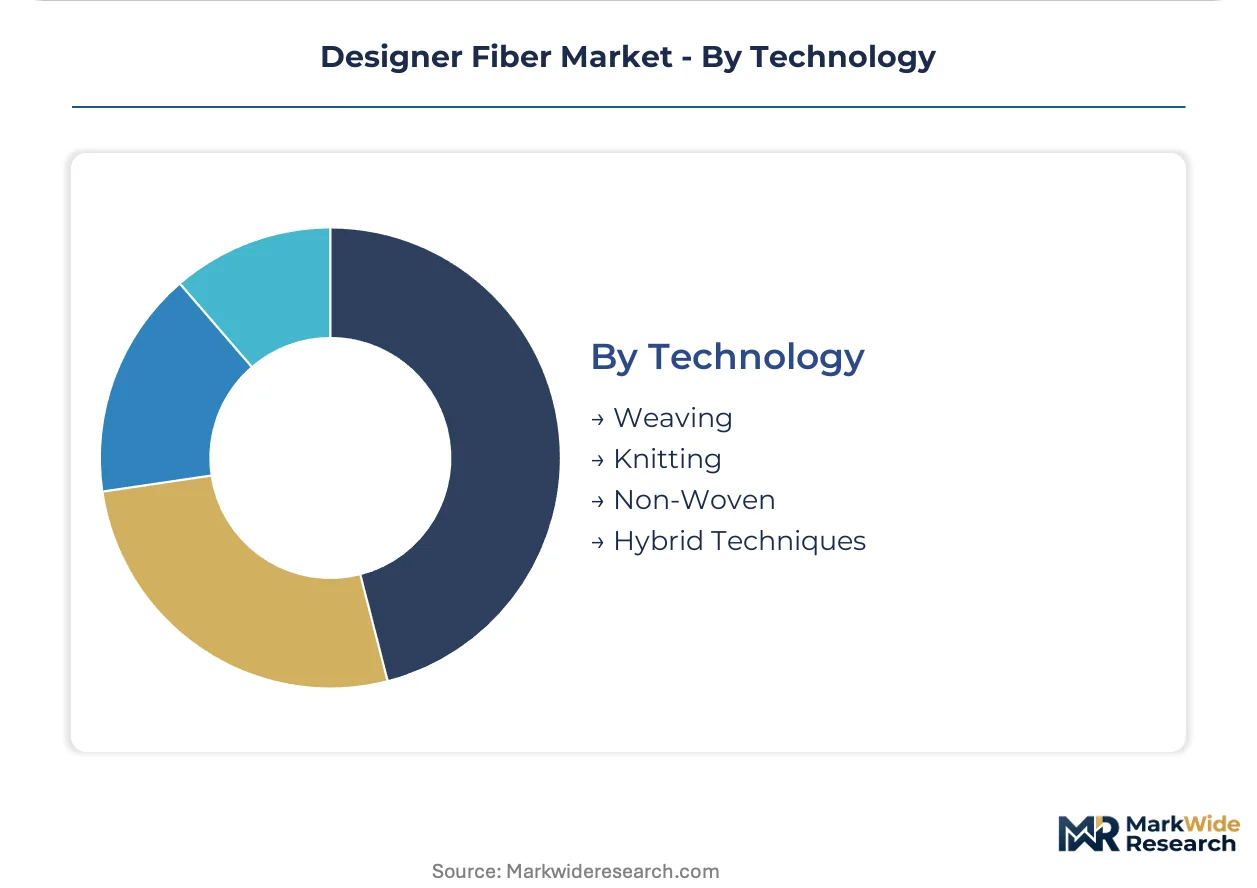
Weaving holds the installed base advantage, though Hybrid Techniques are gaining share fastest among performance apparel developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in engineered textiles reveal persistent imbalances between raw fiber exporters and finished fabric importers. China and India dominate upstream cellulosic output, while European and North American markets absorb premium-grade material for automotive and luxury apparel conversion.
China
MIIT industrial policy directives channel state investment toward lyocell and carbon fiber precursor capacity. GB standards for regenerated cellulose fiber exports tighten quality documentation for EU-bound shipments. Sichuan and Zhejiang processing hubs expand dissolving pulp integration to capture margin upstream from weaving operations.
Germany
Automotive OEM procurement from BMW and Mercedes-Benz tightens flammability specifications for seating textiles. KBA type-approval processes now reject fiber submissions containing legacy brominated retardant chemistries. Bavarian technical textile clusters around Augsburg qualify engineered laminates for cabin interior programs.
India
BIS certification harmonization and PLI scheme incentives accelerate technical textile capacity for geotextile and reinforcement applications. Grasim Industries leverages viscose staple scale from Uttar Pradesh and Karnataka manufacturing complexes. Surat and Ichalkaranji weaving clusters absorb regional fiber output for domestic and Middle Eastern export markets.
Italy
Como and Biella spinning concentrations create geographic supply risk for luxury apparel brands sourcing superfine wool and silk blends. REACH compliance documentation filters supplier eligibility for European-bound finished fabric. Northern Italian finishing mills mandate blockchain-tracked cellulose origin from Austrian and Indian pulp suppliers.
United States
EPA chemical reporting obligations under TSCA constrain formulation choices for synthetic fiber producers seeking domestic market access. North Carolina upholstery manufacturers specify solution-dyed acrylics and abrasion-resistant blends for contract furniture. Automotive tier-1 suppliers in Michigan and Ohio qualify lightweight textile laminates for Detroit OEM interior programs.
Designer Fiber Market Competitive Landscape
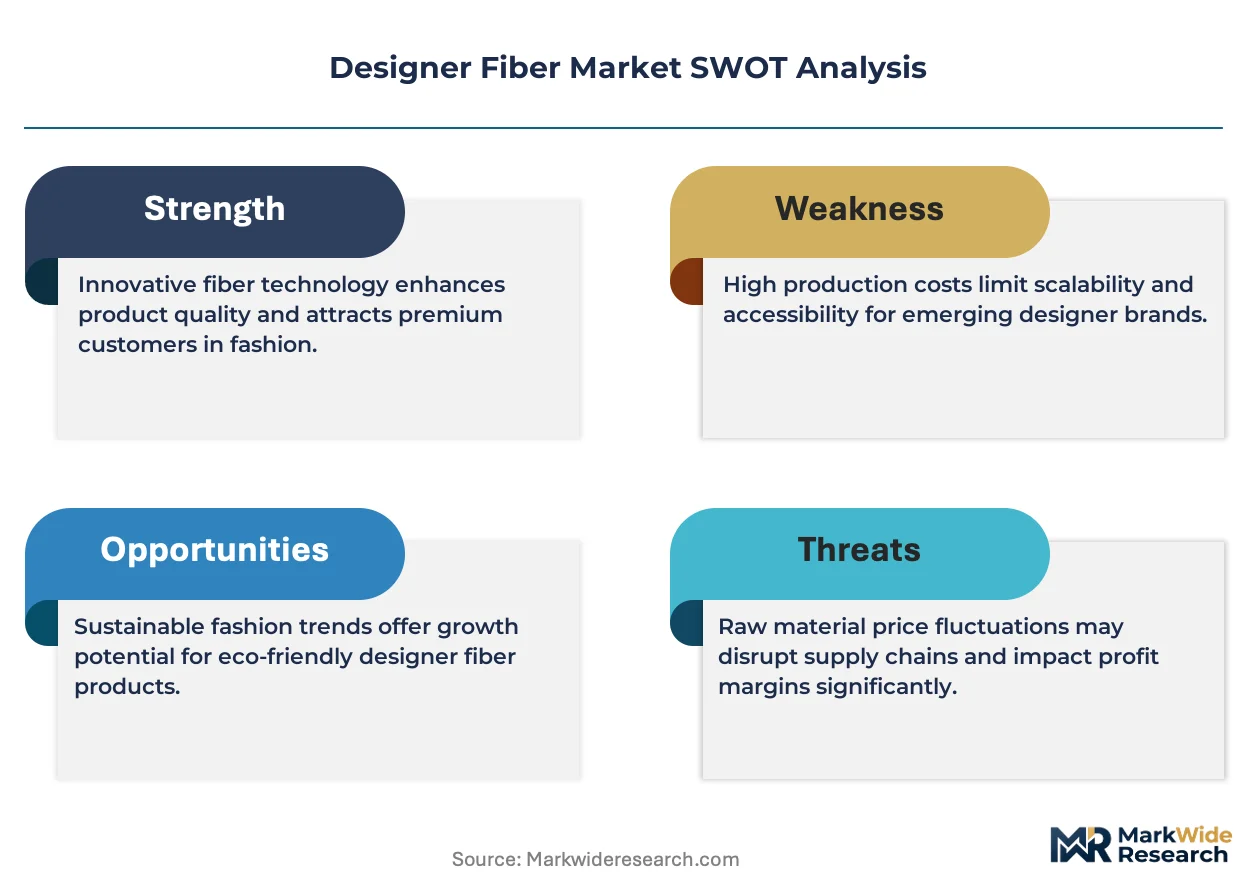
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base stratifies between integrated pulp-to-fiber operators and specialized performance material developers. Three archetypes dominate: Austrian-Indian cellulosic integrators, Japanese carbon fiber specialists, and diversified chemical conglomerates with textile divisions. Competitive moves concentrate on solvent-recycling technology licensing and direct-to-mill digital platform deployment.
Within the premium cellulosic tier, Lenzing AG and Grasim Industries occupy positions as vertically integrated reference points for traceability-focused European mills. Toray Industries anchors the high-performance synthetic segment through its Japanese production base. These three exemplify how geographic concentration of raw material access and regulatory compliance capability shape procurement relationships across automotive and luxury apparel end-uses.
| Leading Market Players |
|---|
| Lenzing AG |
| Toray Industries, Inc. |
| Teijin Ltd. |
| DuPont |
| Hexcel Corporation |
| Grasim Industries Ltd. |
| Mitsubishi Chemical Group |
| SGL Carbon |
| Solvay |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for lyocell staple fiber compress margin negotiation windows and amplify pricing power for vertically integrated Austrian and Indian producers who control dissolving pulp supply. Automotive OEM qualification timelines stretching eighteen to twenty-four months lock in contract structures that insulate premium engineered fiber tiers from spot market volatility while exposing commodity synthetics to petrochemical input swings.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across automotive and filtration end-uses, with pricing stratifying across premium certified grades, standard performance tiers, and economy commodity lots. Price differentiation rests on REACH compliance documentation and OEKO-TEX certification levels alongside volume scale commitments. Cost compression in polyester staple fiber is intensifying because purified terephthalic acid price volatility feeds directly into margin erosion. Fast-fashion volume retailers exhibit highest price sensitivity, while luxury textile mills in Como and Biella prioritize hand-feel specifications over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for dissolving pulp shipments from Sichuan and Zhejiang processing hubs. Geographic supply concentration centers on China, India, and Austria for regenerated cellulosic output, with Italian finishing mills drawing from Austrian pulp suppliers. Raw material dependencies include dissolving wood pulp, petrochemical monomers, and phosphorus-nitrogen flame retardant additives. Single-source vulnerability from sericulture labor shortages in Chinese mulberry cultivation regions threatens silk filament availability. Distribution runs through integrated spinning-weaving operations in Surat, Ichalkaranji, and Turkish manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Designer fiber markets sit in early-cycle expansion as automotive lightweighting mandates accelerate engineered textile adoption ahead of regulatory compliance deadlines. Penetration tailwinds from biodegradable certification demand position regenerated cellulosic producers for sustained procurement relationship deepening.
For Market Incumbents: Shield margin pools in premium lyocell grades by locking solvent-recycling technology licenses before competitor scale-up reaches commercial thresholds. Accelerate backward integration into dissolving pulp supply to neutralize raw material cost volatility from Chinese GB standards tightening. Defensive capacity positioning in Karnataka and Uttar Pradesh manufacturing complexes secures BIS certification pathways for technical textile expansion. For New Entrants and Emerging Players: Differentiate on closed-loop solvent recovery systems that achieve near-zero discharge profiles qualifying for European luxury mill procurement. Target Indian technical textile white space where PLI scheme incentives reduce effective capital intensity for geotextile fiber production. Pursue direct-to-mill digital platform routes that compress trader margins and establish direct specification relationships with specialty spinners. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH substance restrictions and EPA chemical reporting obligations continuously elevate compliance costs that favor scaled integrated producers over fragmented commodity competitors. Acquisition target archetype: mid-cap lyocell specialists with captive pulp supply and existing European mill qualification relationships. Monitor biodegradable certification timeline fragmentation across OECD, ASTM, and EU soil-compostability protocols as inflection signal for which production configurations retain cross-border eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Solvent Recycling Scale-Up | Lenzing AG and Grasim Industries leverage membrane filtration to achieve near-zero discharge at commercial lyocell production volumes. |
| Automotive Interior Qualification Programs | BMW and Mercedes-Benz KBA type-approval processes now mandate halogen-free phosphorus-nitrogen flame retardant chemistry in seating textiles. |
| Blockchain Provenance Verification Deployment | European luxury mills in Como mandate cellulose origin documentation from Austrian dissolving pulp suppliers for premium collection positioning. |
| Technical Textile Capacity Expansion | Indian PLI scheme incentives channel state-backed investment toward geotextile and reinforcement fiber manufacturing in Surat clusters. |
| Direct-to-Mill Digital Platform Launch | B2B fiber marketplaces compress traditional trader margins and enable specialty spinners to access small-lot engineered fiber directly. |
Research Methodology
A standing panel of fiber procurement directors at European luxury textile mills, automotive tier-1 supplier material engineers, and technical textile plant managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA SVHC candidate list updates, MIIT industrial policy directives, BIS certification harmonization documents, and SEC filings from listed chemical conglomerates. Bottom-up fiber production estimates triangulated against top-down end-use demand modeling across apparel, automotive, and industrial textile segments.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including fiber type, end-user category, application function, and processing technology. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and capacity expansion announcements. Industry-specific forecast inputs incorporated automotive OEM lightweighting mandates and biodegradable certification adoption curves.
Material uncertainties — petrochemical input volatility, REACH sunset review outcomes, and sericulture labor availability — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained regulatory enforcement intensity and automotive interior redesign cycle continuity. Practitioners should keep alternative scenarios live as Chinese MIIT capacity directives and EU Green Deal textile sustainability requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Melt Spun Fibers Market