
 Polymer Nanofiber Market | 2026-2036
Polymer Nanofiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Nanofiber Market Outlook
Subscription-based maintenance contracts for electrospinning equipment is recalibrating how capital outlays convert into recurring revenue streams. Teijin Limited leverages its vertical integration across polymer precursors and finished nanofiber mats to sustain margin control. Donaldson Company Inc. anchors its competitive position through specialized filtration product lines. Elmarco differentiates by dominating industrial-scale electrospinning platform supply.
Polymer nanofibers are synthetic or natural polymer filaments with diameters below 100 nanometers, typically produced via electrospinning from polymer solutions or melts to create high surface-area-to-volume ratio structures for barrier, absorption, or structural functions. Electrospun fibers occupy the dominant product position due to mature process control and breadth of polymer compatibility, while meltblown fibers compete on throughput for filtration media where pore size uniformity commands premium positioning. The filtration application leads current value capture given regulatory-driven replacement cycles, though tissue engineering represents the fastest-growing segment as scaffold architectures advance toward clinical translation.
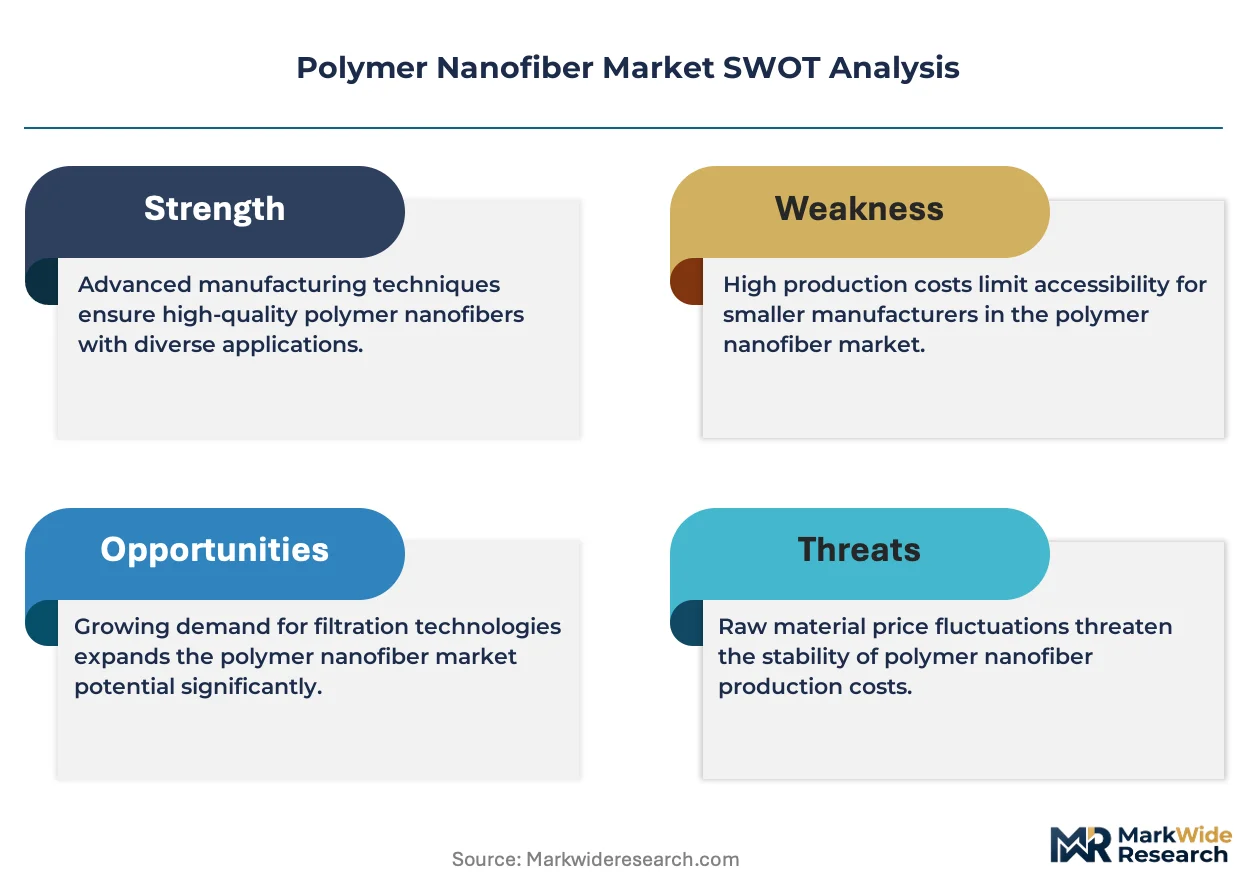
FDA biocompatibility standards for implantable devices and EPA emissions frameworks for solvent-based manufacturing constrain process chemistry choices and facility siting decisions. The EU MDR and REACH chemical registration requirements add compliance layers for European market access, particularly for biodegradable fiber claims. ISO 10993 testing protocols shape product development timelines across all jurisdictions. Stakeholders must monitor evolving regulatory convergence between medical device and advanced materials frameworks to anticipate certification pathway changes.
Market Dynamics
Electrospinning equipment manufacturers are converting capital sales into recurring revenue through subscription-based maintenance contracts, fundamentally altering how filtration and medical device producers finance nanofiber production capacity.
Growth Catalysts
- EU Medical Device Regulation:Tightened biocompatibility testing protocols for implantable nanofiber products are accelerating scaffold validation investments across German and French medical technology clusters.
- Filtration replacement cycles:EPA emissions frameworks and industrial air quality mandates in the United States are forcing shorter replacement intervals for high-efficiency nanofiber filtration media.
- Tissue engineering translation:Electrospun scaffold architectures are progressing through ISO 10993 testing protocols, opening clinical pathways for vascular grafts and wound healing applications.
Market Restraints
- Solvent-based process constraints:EPA emissions frameworks and REACH chemical registration requirements limit facility siting options and increase compliance capital for manufacturers using volatile organic solvent systems.
- Technical throughput limitations:Electrospinning production rates remain orders of magnitude below meltblown alternatives, constraining cost-competitive supply for high-volume filtration contracts.
- Biodegradable fiber certification friction:ECHA evaluation timelines for novel biodegradable polymer chemistries extend product development cycles by 18-36 months compared to established synthetic alternatives.
Strategic Opportunities
- Industrial-scale platform supply:Czech and German research institute clusters present concentrated demand for next-generation multi-nozzle electrospinning systems capable of meter-scale production widths.
- Dual carbon alignment:China's NMPA green channel for domestically produced biodegradable medical materials offers accelerated approval pathways for polylactic acid and polycaprolactone nanofiber scaffolds.
- After-sales service unbundling:Predictive maintenance contracts for electrospinning equipment are displacing traditional warranty models, creating recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Specialized operator scarcity:Electrospinning process optimization requires cross-disciplinary expertise spanning polymer rheology, high-voltage engineering, and quality systems, creating recruitment bottlenecks for scale-up facilities.
- ISO 10993 testing bottlenecks:Contract research organization capacity constraints for cytotoxicity and sensitization studies are extending medical nanofiber product development timelines by 12-18 months.
- Legacy filtration incumbent resistance:Established meltblown suppliers are leveraging existing customer relationships and lower capital requirements to delay electrospun media adoption in price-sensitive HVAC segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Nanofiber Market |
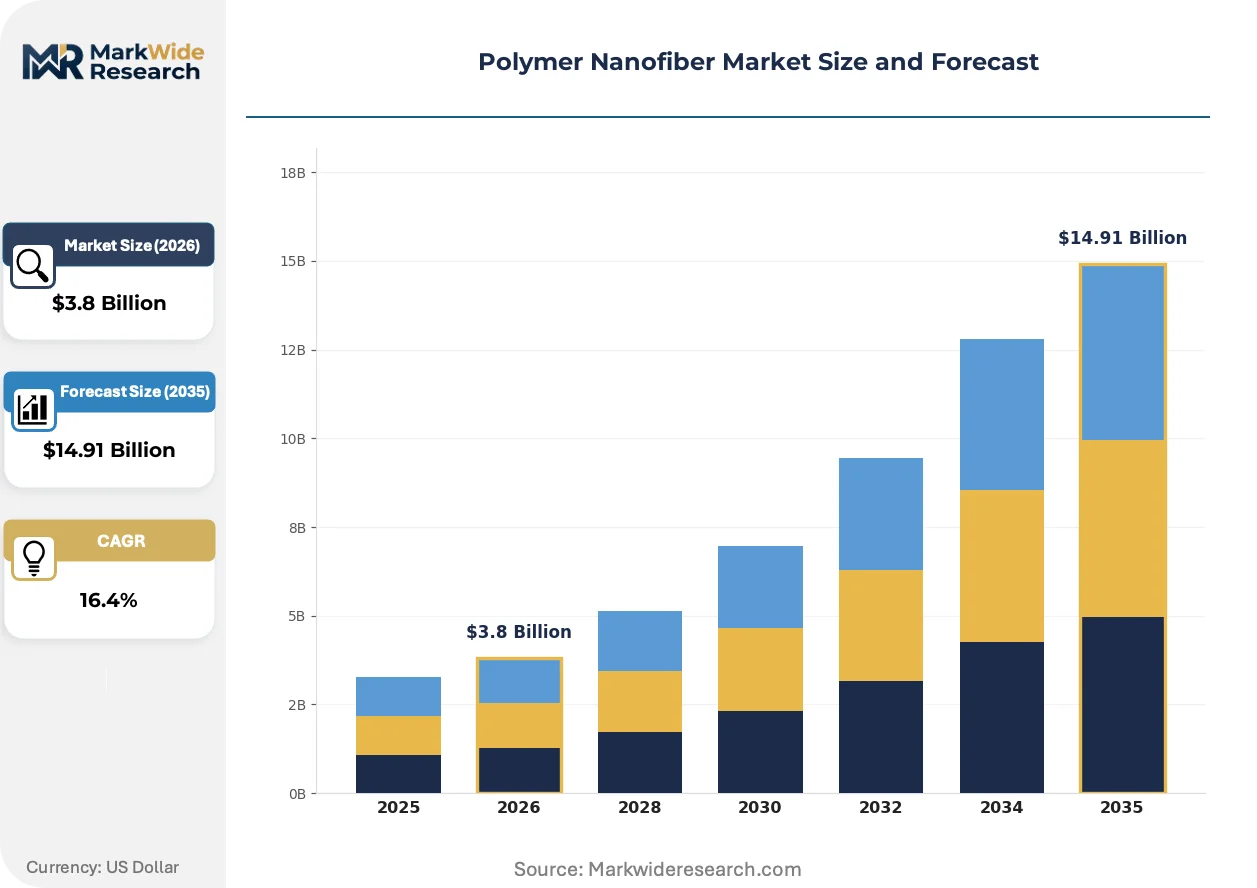
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrospun Fibers, Meltblown Fibers, Biodegradable Fibers, Composite Fibers Application: Filtration, Textiles, Tissue Engineering, Drug Delivery End User: Healthcare, Textile Manufacturers, Automotive, Aerospace Technology: Electrospinning, Melt Spinning, Solution Spinning, Others |
| Companies Covered | Teijin Limited, eSpin Technologies Inc., Toray Industries, Inc., Ahlstrom, Asahi Kasei Corporation, Donaldson Company Inc., Hollingsworth & Vose Company, Elmarco, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Nanofiber Market Strategic Shifts
Process electrification and regulatory convergence between medical device and advanced materials frameworks are compressing product development timelines while fragmenting competitive advantage across equipment, materials, and application expertise.
Multi-needle electrospinning with independent voltage control is electrifying production scalability for filtration media manufacturers. Donaldson Company and specialized German industrial filter producers are adopting these platforms to achieve pore size uniformity previously limited to laboratory-scale systems. The technology is electrifying competitive positioning in premium HVAC and industrial dust collection segments where performance certification commands price premiums over commodity meltblown alternatives.
REACH chemical registration requirements and the EU MDR's tightened biocompatibility protocols are converging to reshape European market access strategies. Manufacturers must now coordinate ECHA substance notifications with clinical validation timelines, compressing the window for first-mover advantage in biodegradable implantable scaffolds. German and French medical technology clusters are responding by co-locating polymer synthesis, electrospinning production, and sterilization facilities to reduce cross-border regulatory friction.
Hospital procurement consortiums are consolidating nanofiber scaffold sourcing through centralized tender processes, displacing direct manufacturer-to-clinic relationships that previously dominated tissue engineering supply chains. This concentration is most visible in Germany's university hospital networks, where standardized ISO 10993 certification requirements are becoming mandatory bid prerequisites. Czech and Polish distributors are adapting by building application engineering capabilities to maintain relevance in specification-influencing roles.
Polymer Nanofiber Market Segmentation
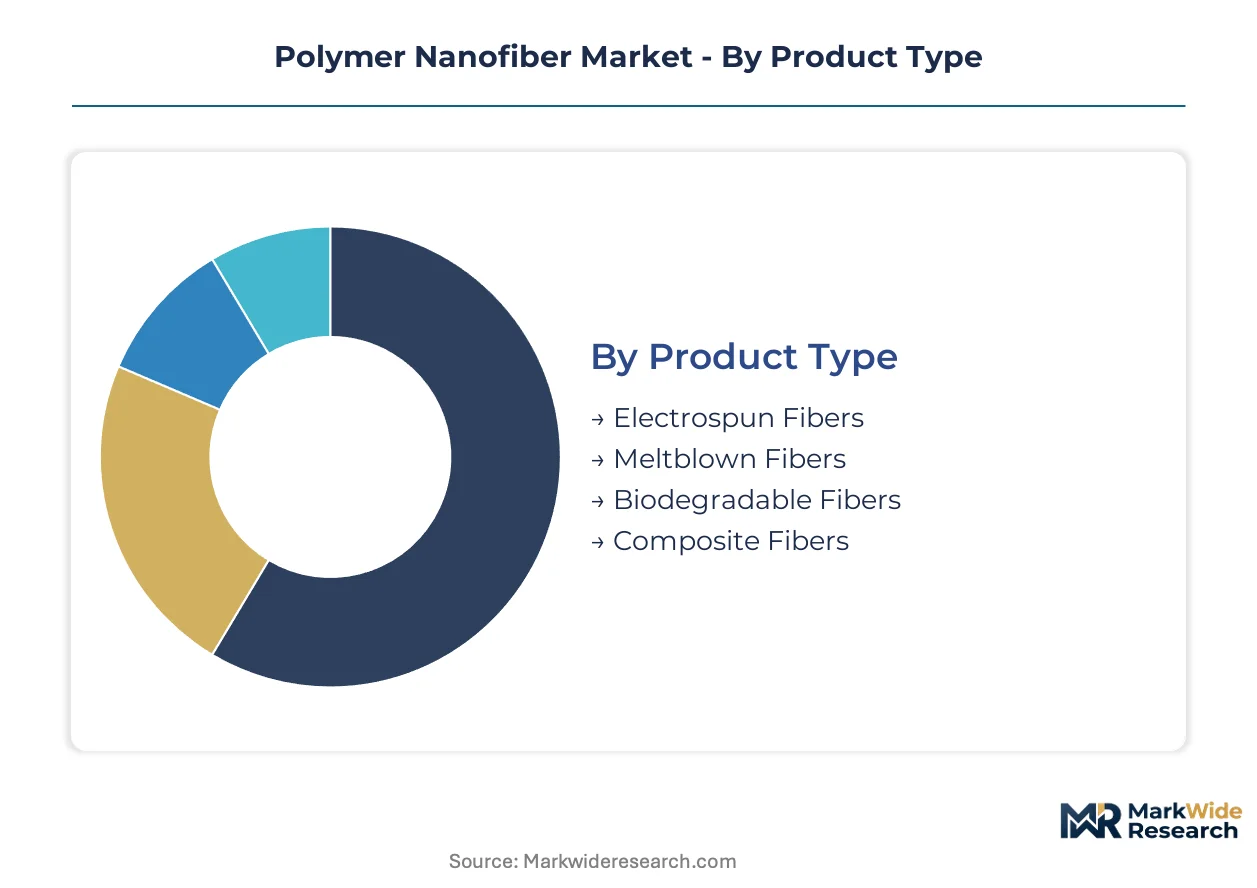
Polymer nanofiber markets fragment across production technology, application performance requirements, and regulatory compliance tiers. Each segmentation axis reveals distinct margin structures and capital intensity profiles that shape competitive entry strategies.
Product Type:
Filament architecture determines surface-area-to-volume ratios and downstream processing compatibility.
- Electrospun Fibers:These fibers achieve diameters below 100 nanometers through high-voltage-driven polymer jet elongation. Demand concentrates in German filtration manufacturers and French medical technology clusters where pore size uniformity commands certification premiums under EU MDR protocols.
- Meltblown Fibers:Thermoplastic extrusion through die orifices with high-velocity hot air attenuation produces fibers with broader diameter distributions. Automotive cabin air filter producers in Stuttgart and Munich favor meltblown media for cost-competitive high-volume contracts where throughput outweighs precision specifications.
- Biodegradable Fibers:Polylactic acid and polycaprolactone compositions degrade through hydrolytic or enzymatic pathways.
- Composite Fibers:Core-shell or side-by-side configurations combine polymer functionalities in single filament structures.
Mature deployment sits with electrospun fibers. Newer deployment is concentrated in biodegradable fibers.
Application:
End-use performance specifications segment value capture across barrier, absorption, and structural functions.
- Filtration:Nanofiber layers capture sub-micron particulates through interception and diffusion mechanisms. EPA emissions frameworks and industrial air quality mandates in the United States are forcing shorter replacement cycles for high-efficiency media.
- Tissue Engineering:Electrospun scaffolds mimic native extracellular matrix architectures for cell infiltration and proliferation. ISO 10993 testing protocols are extending product development timelines by 12-18 months as contract research organization capacity constrains cytotoxicity studies.
- Textiles:Moisture-wicking and breathable barrier applications leverage nanofiber surface area for comfort performance.
- Drug Delivery:Encapsulation and controlled release formulations exploit high surface area for API loading efficiency.
Filtration commands current revenue concentration. Tissue engineering climbs the fastest as scaffold architectures advance toward clinical translation.
End User:
Procurement sophistication and regulatory exposure differentiate customer segments.
- Healthcare:Hospital procurement consortiums in Germany's university hospital networks are consolidating nanofiber scaffold sourcing through centralized tender processes. ISO 10993 certification requirements are becoming mandatory bid prerequisites.
- Textile Manufacturers:Sportswear and protective apparel producers integrate nanofiber membranes for moisture management and chemical resistance.
- Automotive:Cabin air filtration and battery separator applications drive specification requirements from Stuttgart and Wolfsburg engineering centers.
- Aerospace:Lightweight structural composites and filtration systems for cabin air quality command performance premiums.
Healthcare procurement concentrates specification authority. Automotive volume scales fastest as electric vehicle battery separator demand expands.
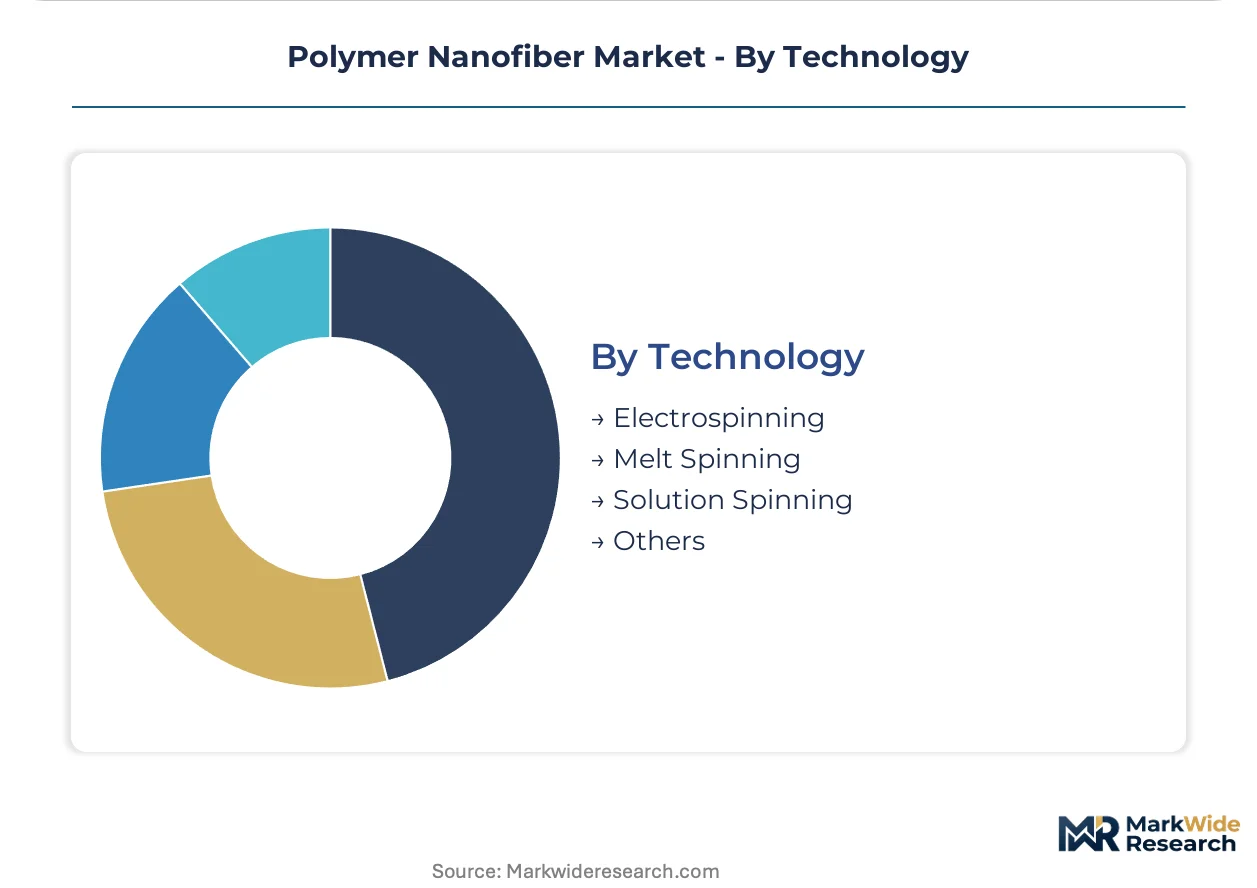
Technology:
Process chemistry and throughput economics determine facility siting and capital recovery profiles.
- Electrospinning:Solution or melt-based fiber formation under electrostatic fields achieves the finest diameter control. Czech and German research institute clusters present concentrated demand for next-generation multi-nozzle systems capable of meter-scale production widths.
- Melt Spinning:Thermoplastic extrusion and mechanical drawing produces fibers with diameters typically above 500 nanometers. EPA emissions frameworks constrain solvent-based alternatives, favoring melt processes for high-volume filtration contracts.
- Solution Spinning:Wet or dry-jet wet spinning from polymer solutions achieves intermediate diameters with specialized solvent recovery requirements.
- Others:Template synthesis, self-assembly, and phase separation methods serve niche research and prototype applications.
Electrospinning dominates medical and premium filtration applications. Melt spinning expands most quickly in cost-sensitive industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European polymer nanofiber demand through its dense concentration of automotive filtration engineering centers and specialized industrial filter manufacturers clustering around Fraunhofer research institutes.
Germany
Automotive cabin air filtration and medical scaffold applications drive specification intensity from Stuttgart and Wolfsburg engineering centers. The EU Medical Device Regulation tightens biocompatibility testing protocols for implantable nanofiber products, accelerating validation investments across German medical technology clusters. Specialized filtration manufacturers concentrate around industrial research institutes in Baden-Württemberg and Bavaria.
United States
EPA emissions frameworks and industrial air quality mandates force shorter replacement cycles for high-efficiency nanofiber filtration media. FDA biocompatibility standards for implantable devices constrain process chemistry choices for tissue engineering scaffold producers. Donaldson Company anchors filtration supply from its Minneapolis operational base.
China
Domestic electric vehicle battery separator demand expands manufacturing scale requirements for nanofiber membrane producers. The NMPA green channel for domestically produced biodegradable medical materials offers accelerated approval pathways for polylactic acid nanofiber scaffolds. Yangtze River Delta research parks concentrate electrospinning equipment development.
Japan
Premium automotive and electronics filtration applications sustain demand for ultra-fine diameter fiber production. METI industrial technology roadmaps prioritize nanofiber mat standardization for battery separator applications. Toray Industries exemplifies integrated polymer precursor and finished mat production from its Osaka-Kobe manufacturing corridor.
Czech Republic
Industrial-scale electrospinning platform demand concentrates around Liberec nanotechnology research clusters and Prague-based medical device development centers. REACH chemical registration requirements limit facility siting options for solvent-based process manufacturers. Elmarco anchors equipment supply relationships with Central European research institutes.
Polymer Nanofiber Market Competitive Environment
Capital-heavy producers compete with asset-light designers across polymer nanofiber value chains. The market structure fragments across three tiers: integrated chemical conglomerates controlling precursor supply, specialized filtration and medical device manufacturers converting mats into finished products, and equipment suppliers enabling production scale-up. Strategic archetypes include backward-integrated polymer suppliers, application-focused converters, and platform-technology licensors. Competitive moves concentrate on multi-nozzle electrospinning system development and predictive maintenance contract unbundling.
Among Japanese chemical conglomerates, Teijin Limited and Toray Industries occupy positions exemplifying backward integration from polymer precursors through finished nanofiber mat production. Donaldson Company Inc. anchors North American filtration application expertise. Czech-based Elmarco s.r.o. represents the industrial-scale equipment supply archetype, with its Liberec origins positioning it within Central European research institute networks. These three company types illustrate how competitive advantage fragments across materials control, application engineering, and production platform supply.
| Leading Market Players |
|---|
| Teijin Limited |
| eSpin Technologies Inc. |
| Toray Industries, Inc. |
| Ahlstrom |
| Asahi Kasei Corporation |
| Donaldson Company Inc. |
| Hollingsworth & Vose Company |
| Elmarco |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
German hospital procurement consortiums concentrate specification authority for tissue engineering scaffolds, anchoring value-based pricing around ISO 10993 certification tiers rather than per-unit fiber costs. This buyer concentration forces manufacturers to bundle predictive maintenance contracts with electrospinning equipment sales, converting capital transactions into recurring revenue streams that protect margin structures.
Pricing Analysis
Throughput guarantees for multi-nozzle electrospinning systems anchor value-based pricing models, with filtration media producers paying premiums for meter-scale production widths that achieve pore size uniformity. Price differentiation separates ISO 10993-certified medical grades from industrial filtration tiers, with after-sales service bundling widening spreads between premium and standard configurations. Cost compression in commodity meltblown alternatives is intensifying because automotive cabin air filter contracts prioritize volume scale over precision specifications. Textile manufacturers exhibit highest price sensitivity, while healthcare procurement consortiums absorb premiums for validated scaffold architectures.
Supply Chain Analysis
REACH chemical registration requirements and EU MDR biocompatibility protocols gate European market access, forcing manufacturers to co-locate polymer synthesis, electrospinning production, and sterilization facilities. Supply concentrates in Germany, the Czech Republic, and China, with raw material dependencies spanning polymer precursors, high-voltage power electronics, and specialized solvent recovery systems. Single-source vulnerability for industrial-scale electrospinning equipment creates bottleneck risk as Elmarco dominates platform supply relationships with Central European research institutes. Distribution runs through specialized filtration converters and hospital procurement consortiums rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer precursor supply represents the decisive competitive lever, with Teijin and Toray Industries leveraging captive material control to sustain margin structures against equipment-centric challengers.
For Market Incumbents: To counter meltblown filtration incumbents delaying electrospun adoption in price-sensitive HVAC segments, Teijin Limited should deepen upstream control over polylactic acid and polycaprolactone biodegradable polymer supply. Donaldson Company must expand application engineering capabilities in Stuttgart and Wolfsburg to defend specification-influencing roles against Czech and Polish distributors building similar competencies.
For New Entrants and Emerging Players: Launch via predictive maintenance contract unbundling to capture recurring revenue streams independent of hardware replacement cycles, targeting Czech and German research institute clusters with next-generation multi-nozzle electrospinning systems. China's NMPA green channel for domestically produced biodegradable medical materials offers the most penetrable regulatory pathway for polylactic acid nanofiber scaffolds, with Yangtze River Delta research parks providing co-location advantages for equipment development.
For Investors and Strategic Acquirers: The window for entry favors electrospinning equipment specialists with industrial-scale platform capabilities and established research institute relationships. Long-term viability hinges on consolidation of fragmented maintenance service networks into subscription-based revenue models. Monitor ECHA evaluation timeline compression for novel biodegradable polymer chemistries as the inflection signal for first-mover advantage in implantable scaffold certification.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Nozzle Electrospinning Scale-Up | Meter-scale production widths enable pore size uniformity premiums in German filtration markets. |
| Biodegradable Polymer Precursor Integration | Captive polylactic acid supply secures margin control against REACH-registered synthetic alternatives. |
| Predictive Maintenance Contract Unbundling | Recurring revenue streams displace traditional warranty models for Czech equipment installations. |
| ISO 10993 Certification Pre-Investment | Early cytotoxicity study commitment accelerates German hospital procurement consortium eligibility. |
| Research Institute Co-Location | Fraunhofer cluster proximity reduces regulatory friction for EU MDR biocompatibility validation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across electrospinning equipment engineers, polymer procurement leads at filtration OEMs, hospital purchasing committee members, and contract research organization study directors. FDA 510(k) submissions, ECHA REACH registrations, EU MDR technical documentation, and German hospital procurement databases provided validation triangulation. Bottom-up fiber production estimates and top-down application market sizing were reconciled through iterative stakeholder feedback.
Segment-level modeling tracked electrospun versus meltblown fiber architectures, filtration versus tissue engineering application performance tiers, and healthcare versus automotive end-user procurement sophistication across the projection horizon. CAGRs were derived from installation base expansion rates for industrial-scale equipment and replacement cycle compression under EPA emissions frameworks. Polymer precursor cost curves and ISO 10993 testing timeline assumptions shaped medical scaffold adoption trajectories.
REACH substance notification delays, ECHA biodegradable polymer evaluation timeline extensions, and contract research organization capacity constraints are the dominant revision risks for tissue engineering segment forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
High Performance Polyester Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
IMO Fiber Market