
 Pan-Based Carbon Fiber Cloth Market | 2026-2036
Pan-Based Carbon Fiber Cloth Market Size, Share, and Industry Trends Forecast 2026-2036
Pan-Based Carbon Fiber Cloth Market Intelligence
Japanese precursor supply is hardening as Toray Industries, Inc. leverages its integrated PAN-to-carbon-fiber pipeline to anchor global feedstock reliability. SGL Carbon sustains its European manufacturing footprint through specialized automotive and industrial grades. Hexcel Corporation competes in aerospace-qualified woven fabrics, while Mitsubishi Chemical Carbon Fiber and Composites, Inc. dominates high-performance segments with proprietary tow technology.
Pan-based carbon fiber cloth consists of polyacrylonitrile-derived carbon fibers interlaced into textile architectures, typically achieving tensile moduli exceeding 230 GPa and carbon content above 90% after oxidative stabilization and carbonization. Aerospace applications command the premium grade tier, where intermediate and high-performance specifications absorb the majority of value pools, while automotive OEMs are shifting procurement toward standard-grade woven fabrics as platform volumes scale. Non-woven fabrics represent the fastest-growing product format for compressed molding operations in electric vehicle battery enclosures.
EPA emissions benchmarks and FAA airworthiness directives jointly determine material qualification pathways for U.S.-bound manufacturers, while REACH and the EU Green Deal impose carbon footprint disclosure requirements on European suppliers. Stakeholders must monitor evolving precursor energy intensity standards and qualification timelines for recycled carbon fiber alternatives.
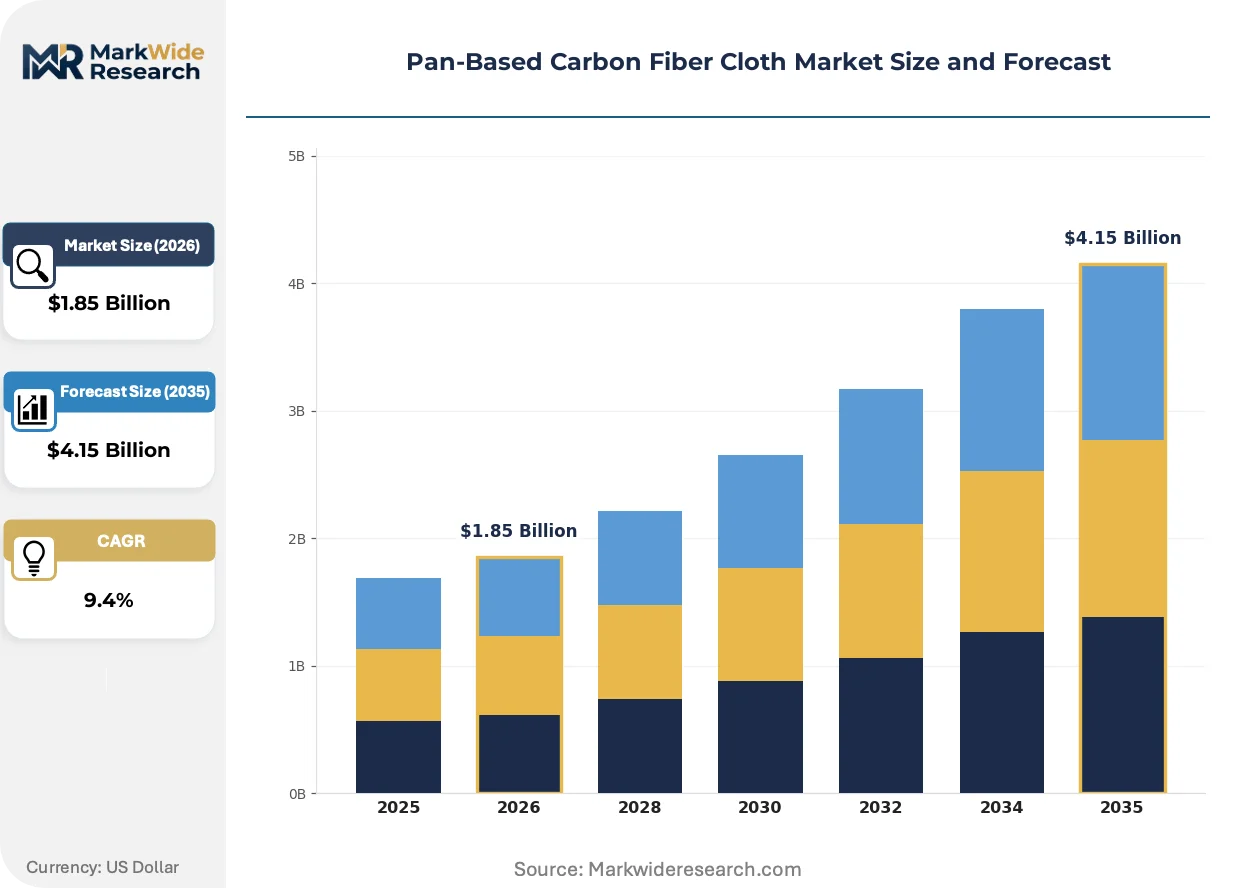
Market Dynamics
Polyacrylonitrile precursor supply concentration in Japan and Germany is hardening feedstock access for non-integrated weavers, forcing downstream fabricators to secure long-term offtake agreements or absorb margin compression from spot market volatility.
Growth Catalysts
- Aerospace OEM platform ramp-ups:Next-generation narrowbody and widebody programs are expanding qualified supplier lists for intermediate-modulus woven prepregs, pulling volume through certified supply chains.
- EU Green Deal carbon accounting:Lifecycle disclosure mandates for industrial materials are favoring PAN-based cloth with documented low-energy precursor routes in German and French procurement specifications.
- Wind blade scaling:Offshore turbine manufacturers are specifying heavier-weight carbon fiber fabrics for spar cap consolidation, concentrating demand in Denmark and Spain manufacturing clusters.
Market Restraints
- Acrylonitrile feedstock volatility:Propylene-ammonia cracking margins swing with naphtha pricing, transmitting cost pressure to carbon fiber cloth converters without pass-through mechanisms.
- Japanese precursor oligopoly:Three integrated producers control over seventy percent of global PAN supply, creating single-source vulnerability for European and North American weavers.
- Recycled fiber performance gap:Pyrolyzed reclaimed carbon fiber exhibits thirty-to-forty percent tensile strength degradation versus virgin tow, limiting substitution in primary structural applications.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle manufacturing are opening specification windows for standard-grade carbon fiber composites in battery tray and body-in-white applications.
- Thermoplastic resin convergence:Polyamide and PEEK matrix compatibility with woven PAN cloth is enabling out-of-autoclave processing for high-rate automotive stamping operations.
- Direct digital weaving:3D loom technology is collapsing preform lead times from weeks to days, creating service differentiation for mid-cap fabricators serving industrial tooling markets.
Industry Challenges
- Carbonization furnace operator scarcity:Specialized thermal process engineering expertise is concentrated among retiring cohorts in Japanese and German plant workforces, constraining brownfield expansion timelines.
- FAA-EASA dual qualification burden:Aerospace fabric suppliers must maintain parallel certification dossiers for FAA airworthiness directives and EASA design approval, duplicating testing expenditure for common specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pan-Based Carbon Fiber Cloth Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Unidirectional Fabrics, Knitted Fabrics Application: Aerospace, Automotive, Marine, Consumer Goods End User: Manufacturers, OEMs, DIY Enthusiasts, Research Institutions Grade: Standard, Intermediate, High-Performance, Specialty |
| Companies Covered | SGL Carbon, Syensqo, Toray Industries, Inc., ZOLTEK Corporation, HS Hyosung Advanced Materials, Teijin Limited, Hexcel Corporation, Formosa M Co., Ltd., Mitsubishi Chemical Carbon Fiber and Composites, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pan-Based Carbon Fiber Cloth Market Strategic Shifts & Innovations
Active consolidation across precursor-to-fabric supply tiers is compressing the vendor base while digital manufacturing tools and regulatory disclosure mandates are rewriting qualification protocols and procurement workflows.
Large-tow carbon fiber technology is consolidating the economics of industrial-grade woven fabrics. Manufacturers are expanding 48K and 50K filament count offerings that reduce layup labor for wind blade and automotive panel producers. This tow scaling is consolidating cost structures for standard-modulus applications while squeezing out smaller 3K and 6K specialty weavers serving legacy aerospace subcontracts.
REACH Article 33 disclosure expansion is tightening material passport requirements across European aerospace and automotive supply chains. Suppliers must now document Substances of Very High Concern content in carbon fiber surface treatments and sizing chemistries. German tier-one suppliers are responding by reformulating epoxy-compatible finishes to eliminate bisphenol-A derivatives before the 2026 sunset review.
Automotive OEMs are consolidating direct mill relationships for carbon fiber cloth, bypassing traditional distributor intermediaries. BMW and Mercedes-Benz procurement teams are negotiating multi-year blanket orders with Japanese and German weavers for electric vehicle platform volumes. This disintermediation is most advanced in Bavaria and Baden-Württemberg, where battery enclosure and structural battery housing programs are absorbing increasing fabric tonnage.
Pan-Based Carbon Fiber Cloth Market Segmentation
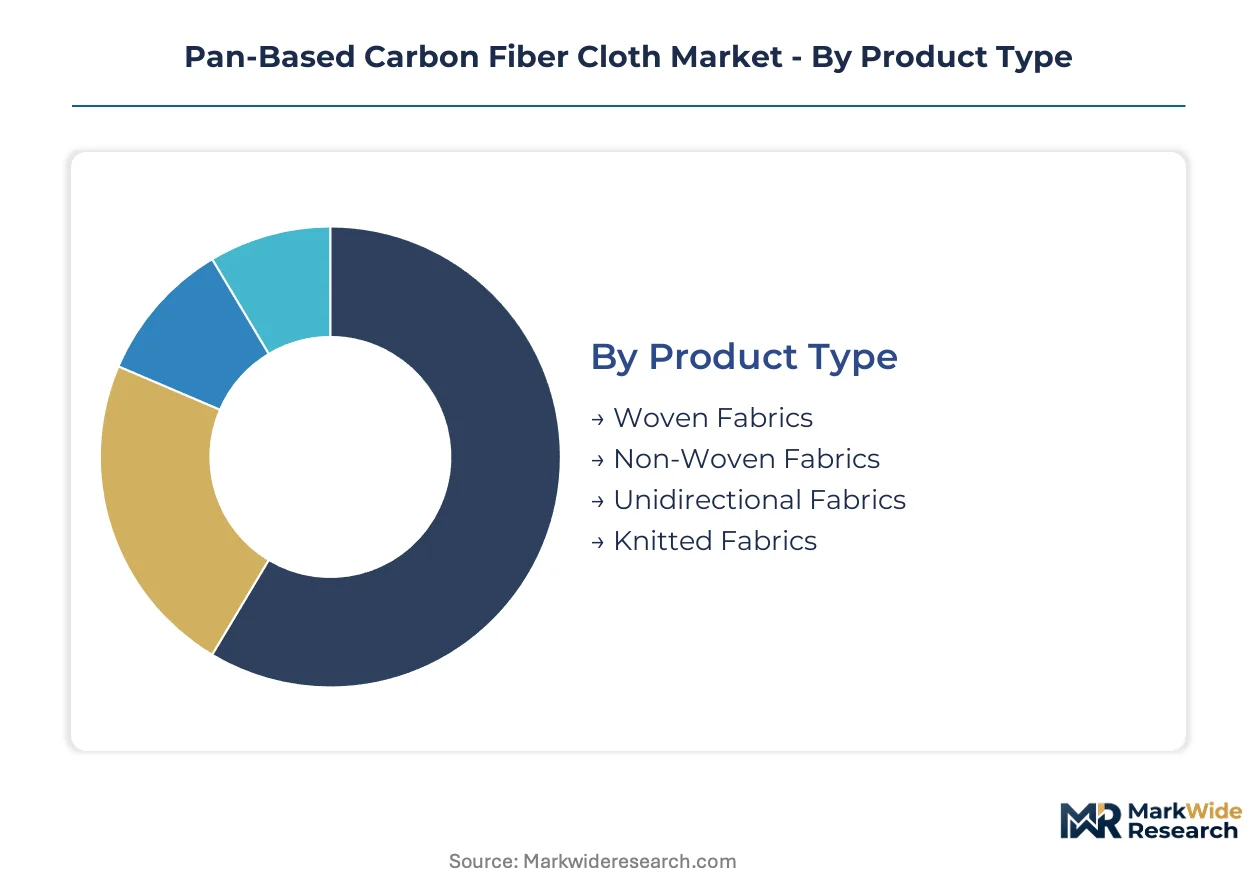
Segmentation in the Pan-Based Carbon Fiber Cloth Market reveals how supply concentration and qualification barriers fragment commercial opportunity across technical specifications and end-use channels. Each dimension carries distinct margin profiles and certification requirements that shape procurement behavior.
Product Type:
Supply concentration in Japanese precursor production hardens access to fiber formats, forcing weavers to align product portfolios with captive tow availability.
- Woven Fabrics:Interlaced fiber architectures produced on traditional looms, achieving balanced in-plane properties. Aerospace-qualified specifications from Hexcel Corporation and SGL Carbon dominate procurement in Germany and Japan, where airframe programs demand traceable fiber lineage.
- Non-Woven Fabrics:Random or oriented fiber mats consolidated through needle-punching or thermal bonding. Electric vehicle battery enclosures in Bavaria and Baden-Württemberg absorb expanding tonnage as BMW and Mercedes-Benz specify compressed molding formats for structural battery housings.
- Unidirectional Fabrics:Parallel fiber alignment maximizing specific strength in primary load directions. Wind blade spar caps in Denmark specify heavy-weight unidirectional formats.
- Knitted Fabrics:Loop-structured textiles enabling complex preform draping for industrial tooling applications.
Today's leader: Woven Fabrics. Tomorrow's challenger: Non-Woven Fabrics.
Application:
Cost tier separation across applications reflects divergent qualification burdens and volume scalability.
- Aerospace:Intermediate and high-modulus specifications absorbing premium value pools. FAA-EASA dual certification requirements concentrate qualified supplier lists around Toray Industries and Hexcel Corporation, with Boeing and Airbus platform ramp-ups pulling volume through certified supply chains.
- Automotive:Standard-grade woven fabrics scaling with electric vehicle platform volumes. German OEMs are consolidating direct mill relationships, bypassing traditional distributors for battery tray and body-in-white applications under PLI scheme incentives.
- Marine:Corrosion-resistant laminates for hull and superstructure construction, concentrated in Mediterranean and Scandinavian yacht building clusters.
- Consumer Goods:Sporting equipment and luxury goods utilizing aesthetic-grade carbon fiber with lower mechanical specification requirements.
Aerospace commands margin leadership. Automotive offers volume expansion.
End User:
Customer type determines contract structure, with volume commitments versus spot purchasing fragmenting pricing power.
- Manufacturers:Tier-one and tier-two fabricators converting cloth into composite components. Long-term offtake agreements with Japanese precursor suppliers anchor feedstock security for high-volume automotive contracts.
- OEMs:Original equipment manufacturers specifying qualified materials for in-house composite operations. Direct procurement from weavers is disintermediating traditional distribution channels.
- DIY Enthusiasts:Small-lot purchasers through retail and e-commerce channels, price-sensitive and specification-flexible.
- Research Institutions:Experimental material procurement for next-generation composite development, requiring small-batch customization.
OEM direct relationships are consolidating. Manufacturer intermediation faces compression.
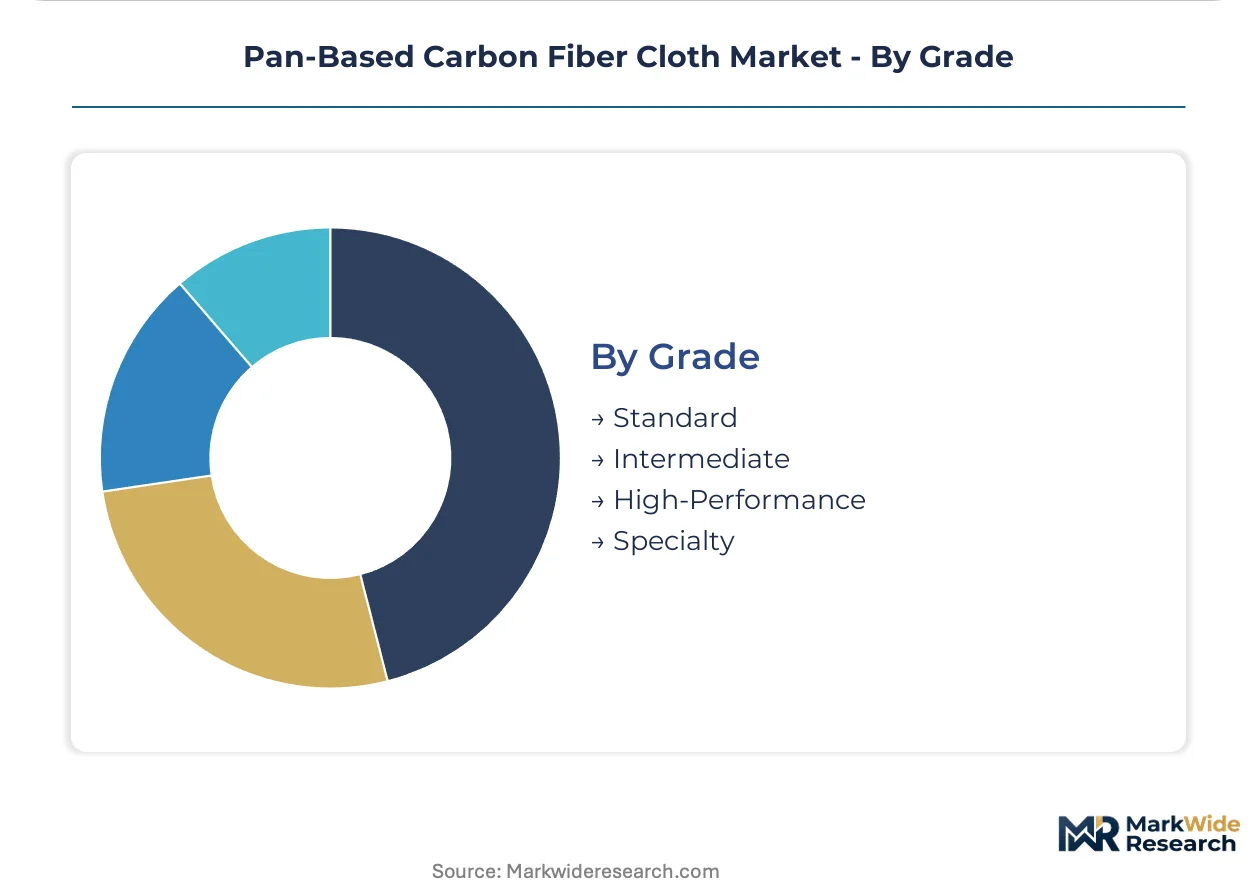
Grade:
Margin structure stratifies across performance tiers, with certification overhead creating defensible positions at the top.
- Standard:Tensile modulus typically 230 GPa, serving industrial and automotive applications where cost-per-kilogram drives specification. Wind blade and automotive panel producers favor large-tow 48K and 50K formats that reduce layup labor.
- Intermediate:Balanced stiffness and strength for primary aerospace structures. Next-generation narrowbody programs are expanding qualified supplier lists, pulling volume through certified supply chains with documented low-energy precursor routes.
- High-Performance:Ultra-high modulus specifications for satellite and defense applications. Mitsubishi Chemical Carbon Fiber dominates with proprietary tow technology.
- Specialty:Custom formulations including recycled fiber blends and thermoplastic-compatible sizings. REACH Article 33 disclosure mandates are driving reformulation of epoxy-compatible finishes to eliminate bisphenol-A derivatives.
Intermediate grade holds aerospace dominance. Standard grade scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands precursor supply chains while Germany dominates downstream fabric conversion, creating divergent competitive moats across the value chain.
United States
Boeing platform ramp-ups in Washington State and South Carolina are absorbing intermediate-modulus woven prepregs through FAA-qualified supply chains. EPA emissions benchmarks and FAA airworthiness directives jointly determine material qualification pathways for domestic fabricators. Huntsville, Alabama and Salt Lake City, Utah host emerging satellite and defense composite clusters.
Germany
Automotive lightweighting programs in Bavaria and Baden-Württemberg anchor regional consumption of standard-grade woven fabrics for electric vehicle battery enclosures. REACH compliance and EU Green Deal carbon accounting mandates favor PAN-based cloth with documented low-energy precursor routes. Wind blade manufacturing clusters in Hamburg and Bremen concentrate spar cap fabrication demand.
Japan
Toray Industries, Inc. leverages its integrated PAN-to-carbon-fiber pipeline to anchor global feedstock reliability for aerospace and industrial applications. METI industrial policy supports precursor capacity expansion and carbon fiber R&D consortia. Nagoya and Tokyo metropolitan areas host concentrated weaving and prepreg operations serving domestic OEMs.
China
Wind energy installations in Jiangsu and Guangdong provinces are scaling heavy-weight carbon fiber fabric demand for turbine blade manufacturing. MIIT industrial standards and dual carbon goals shape domestic procurement specifications for composite materials. Yangtze River Delta manufacturing hubs are consolidating carbon fiber weaving capacity.
India
PLI scheme incentives for electric vehicle manufacturing are opening specification windows for standard-grade carbon fiber composites in battery tray applications. BIS certification requirements and DGFT import policies influence feedstock access for domestic fabricators. Tamil Nadu and Maharashtra automotive clusters are piloting composite body-in-white programs.
Pan-Based Carbon Fiber Cloth Market Key Industry Players
Japanese producers anchor one tier; European specialists hold certification-heavy aerospace positions. The market structures around precursor-to-fabric integration levels, with three strategic archetypes dominating: vertically integrated multinationals controlling PAN supply, regional weavers dependent on long-term offtake agreements, and specialty converters serving qualified aerospace sub-tiers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock access and dual FAA-EASA qualification.
Within the integrated multinational tier, Toray Industries, Inc. and Mitsubishi Chemical Carbon Fiber and Composites, Inc. exemplify Japanese precursor-to-fabric control. SGL Carbon occupies a position representing European manufacturing persistence through specialized automotive and industrial grades. Hexcel Corporation anchors the aerospace-qualified woven fabric segment, sitting within the premium-tier vector where certification overhead creates defensible positioning.
| Leading Market Players |
|---|
| SGL Carbon |
| Syensqo |
| Toray Industries, Inc. |
| ZOLTEK Corporation |
| HS Hyosung Advanced Materials |
| Teijin Limited |
| Hexcel Corporation |
| Formosa M Co., Ltd. |
| Mitsubishi Chemical Carbon Fiber and Composites, Inc. |
| Others |
Cost & Logistics Intelligence
Aerospace OEM procurement teams concentrate buying power for intermediate-modulus woven prepregs, anchoring contract-based long-term offtake pricing that insulates certified suppliers from spot market volatility. This buyer archetype dominance forces non-integrated weavers into margin-absorbing positions when acrylonitrile feedstock costs swing.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade woven fabrics as Yangtze River Delta weaving clusters expand output. Three-tier pricing structure across aerospace-certified premium, automotive standard, and industrial economy levels separates margin pools by certification burden and fiber lineage documentation. Cost compression in automotive grades is intensifying because German OEMs consolidate direct mill relationships, bypassing distributor markups. Tier-one automotive fabricators show highest price sensitivity due to platform volume scaling pressures, while satellite and defense programs absorb premium tiers with minimal negotiation leverage.
Supply Chain Analysis
Freight costs for polyacrylonitrile precursor shipments from Japan to European weaving operations have become a material cost component as containerized chemical transport rates fluctuate. Supply concentrates in Japan, Germany, and China across precursor production, fabric conversion, and wind blade manufacturing respectively. The chain draws from acrylonitrile monomer, specialized carbonization furnace equipment, and epoxy-compatible sizing chemistries as critical inputs. Single-source vulnerability from Toray Industries' dominant PAN supply position creates structural risk for non-integrated North American and European weavers. Distribution runs through direct mill relationships for automotive OEMs and certified distributor networks for aerospace sub-tier fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in standard-grade segments where large-tow format adoption and thermoplastic resin compatibility enable cost-down manufacturing for electric vehicle platforms.
For Market Incumbents: Lock in precursor supply security through backward integration or multi-year offtake agreements with Japanese producers before brownfield expansion timelines extend further. Carbonization furnace operator scarcity in aging German and Japanese plant workforces threatens capacity scaling. Prioritize thermoplastic-compatible sizing R&D to capture automotive out-of-autoclave processing demand as BMW and Mercedes-Benz platform volumes accelerate. For New Entrants and Emerging Players: DIY enthusiasts and research institutions represent underserved buyer archetypes with specification flexibility and willingness to trial recycled fiber blends and specialty formulations. Compressed molding operations for battery enclosures in India offer the most penetrable application window under PLI scheme incentives. Pursue direct digital weaving technology as a service differentiation play to collapse preform lead times for industrial tooling markets. For Investors and Strategic Acquirers: Japanese automotive OEMs and chemical conglomerates are the most active acquirer in this space, seeking captive carbon fiber supply for electric vehicle platform integration. Long-term viability hinges on qualification timelines for recycled fiber alternatives and thermoplastic matrix compatibility. Watch FAA-EASA harmonization progress on dual certification burden reduction as the inflection signal for aerospace fabric supplier consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries' integrated PAN-to-fiber pipeline demonstrates feedstock security value for margin defense. |
| Large-Tow Format Capacity Expansion | 48K and 50K filament offerings reduce layup labor costs for wind blade and automotive panel producers. |
| Thermoplastic Resin Compatibility Investment | Polyamide and PEEK matrix alignment enables high-rate automotive stamping without autoclave curing. |
| Direct Digital Weaving Technology Deployment | 3D loom adoption collapses preform lead times from weeks to days for industrial tooling service differentiation. |
| REACH-Compliant Sizing Reformulation | Eliminating bisphenol-A derivatives from epoxy-compatible finishes secures German tier-one supplier positioning. |
Research Approach
Bottom-up aerospace and automotive demand modeling reconciled against top-down precursor capacity and weaving output tracking forms the analytical core of this study. Primary interviews with carbonization furnace operators, Tier 1 automotive procurement leads, aerospace composite engineers, and wind blade manufacturing directors combined with secondary validation from customs trade data, SEC filings of listed fiber producers, METI industrial statistics, and REACH Article 33 disclosure registries. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map polyacrylonitrile precursor throughput to fabric conversion rates across woven, non-woven, unidirectional, and knitted formats. Segmentation dimensions include grade tier, end-use application, and regional production cluster. CAGRs derive from fitted growth curves against platform ramp-up schedules and policy incentive timelines. Forecast inputs incorporate wind turbine installation pipelines, electric vehicle platform production plans, and FAA-EASA certification queue progressions.
Underlying measurement precision varies by segment; aerospace-qualified specifications carry tighter precision than emerging recycled fiber and thermoplastic-compatible categories due to established certification documentation. Forecasts reflect assumptions on precursor capacity expansion timelines, regulatory harmonization progress, and composite substitution rates in automotive body-in-white applications. Stakeholders should weight assumptions against their own operating context and supplier qualification status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market