
 Americas Pipe Insulation Market | 2026-2036
Americas Pipe Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Pipe Insulation Market Intelligence
The traditional dominance of standard-temperature insulation is unwinding as cryogenic-grade materials gain specification in LNG facilities across the Americas. Owens Corning leverages its vast distribution network and manufacturing scale in fiberglass products. Armacell International specializes in elastomeric foam insulation for HVAC and refrigeration systems. Saint-Gobain competes across multiple segments with its portfolio of both mineral wool and foam-based solutions.
Pipe insulation encompasses materials engineered to minimize thermal energy transfer for industrial and commercial piping systems. These products, often composed of fiberglass, mineral wool, or various foams, are crucial for maintaining process temperatures and preventing surface condensation. Industrial plants constitute a large end-user segment, prioritizing process control and energy savings. While fiberglass remains a high-volume material type, rubber and foam-based insulation show strong growth in commercial building HVAC applications.
Regulations from the US Environmental Protection Agency (EPA) and building codes in Canada mandate specific thermal performance levels for insulation. These standards directly influence material selection in construction and industrial upgrades, favoring products with higher R-values. The key decision for specifiers and installers is balancing the upfront cost of advanced insulation systems against long-term energy savings and regulatory compliance.
Market Dynamics
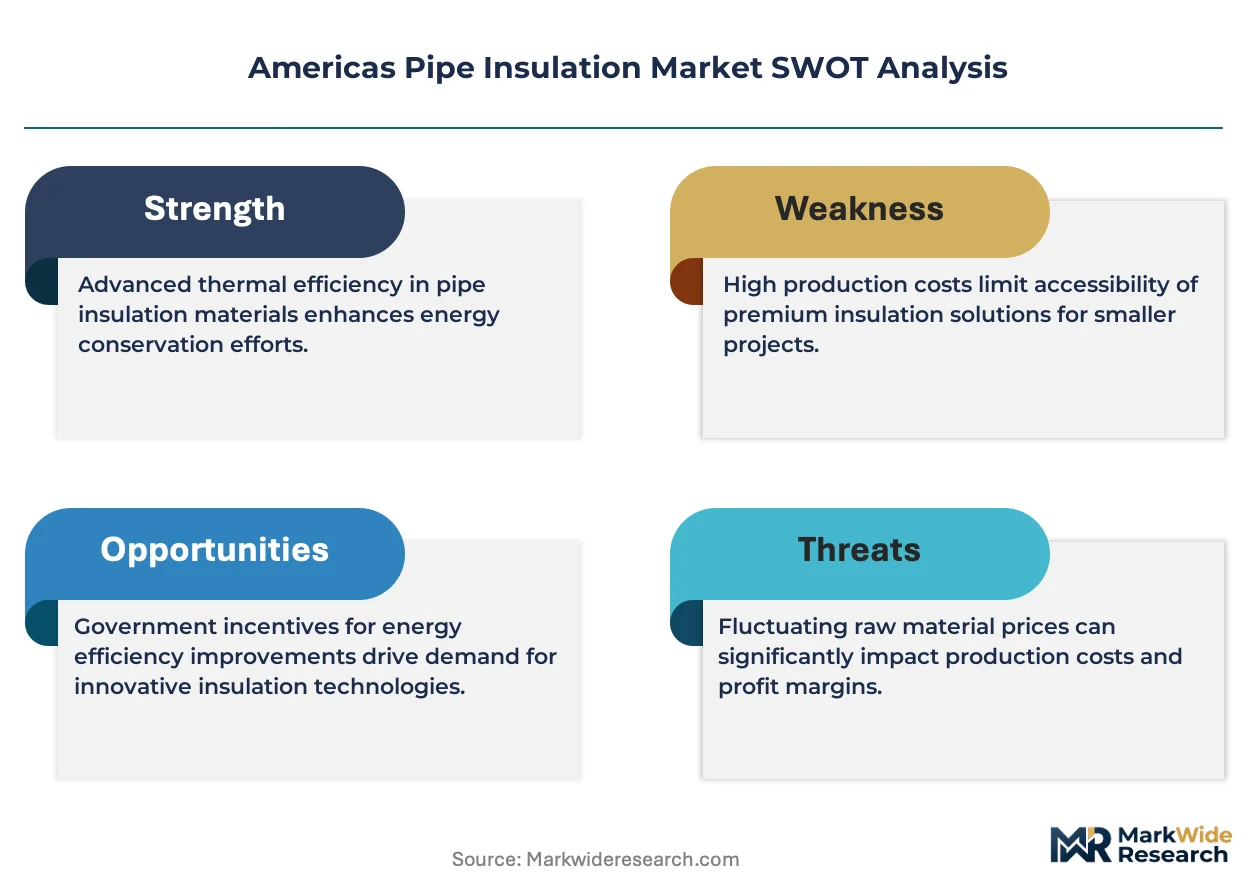
The central dynamic in the Americas pipe insulation market is the tension between rising energy efficiency mandates from regulators like the US EPA and the capital cost constraints of large-scale industrial and commercial projects. This conflict influences material selection, favoring products that balance performance with total installed cost.
Growth Catalysts
- Energy Efficiency Mandates:Stricter building codes in Canada and EPA standards in the United States compel the use of higher R-value insulation, directly driving demand for advanced materials in new construction and retrofits.
- Oil & Gas Sector Expansion:The construction of new LNG export terminals and petrochemical facilities, particularly along the US Gulf Coast, creates massive, concentrated demand for cryogenic and high-temperature process insulation.
- Brazilian Industrial Growth:A renewed cycle of industrial project development in Brazil, focused on oil, gas, and manufacturing, is establishing a significant pocket of new demand for mechanical insulation systems.
Market Restraints
- Input Cost Volatility:The pricing of foam-based insulation, such as polyisocyanurate and elastomeric foam, is directly tied to volatile petrochemical feedstock costs, creating budget uncertainty for large projects and their contractors.
- High Installation Labor Costs:Advanced insulation systems, especially for cryogenic applications, require specialized installation skills, which are in short supply and command a significant wage premium, inflating total project costs.
- Substitution by Heat Tracing:In certain industrial applications, electric heat tracing systems present a viable alternative to passive insulation for process temperature maintenance, posing a direct substitution threat.
Strategic Opportunities
- Commercial Building Retrofits:A vast stock of aging commercial buildings across North America presents a substantial opportunity for retrofitting HVAC and plumbing systems with modern, energy-efficient insulation to meet new standards.
- Mexican Manufacturing Sector:Mexico's expanding manufacturing base, particularly in the automotive and aerospace industries, represents an underpenetrated market for process pipe insulation as facilities upgrade to higher standards.
- Prefabricated Insulation Systems:The development of modular and prefabricated insulation components offers a path to reduce on-site labor time and installation errors, appealing to contractors facing skilled labor shortages.
Industry Challenges
- Installer Skill Gap:A pronounced shortage of technicians certified to install complex, multi-layered cryogenic insulation systems for LNG facilities creates project delays and quality control issues across the Americas.
- Material Certification Delays:The lengthy and expensive process of achieving code compliance and fire safety certifications for new insulation materials can significantly slow their introduction and adoption in the market.
- Legacy System Integration:Ensuring compatibility and creating effective thermal seals between new high-performance insulation and aging, often irregularly shaped, piping during brownfield projects is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Pipe Insulation Market |
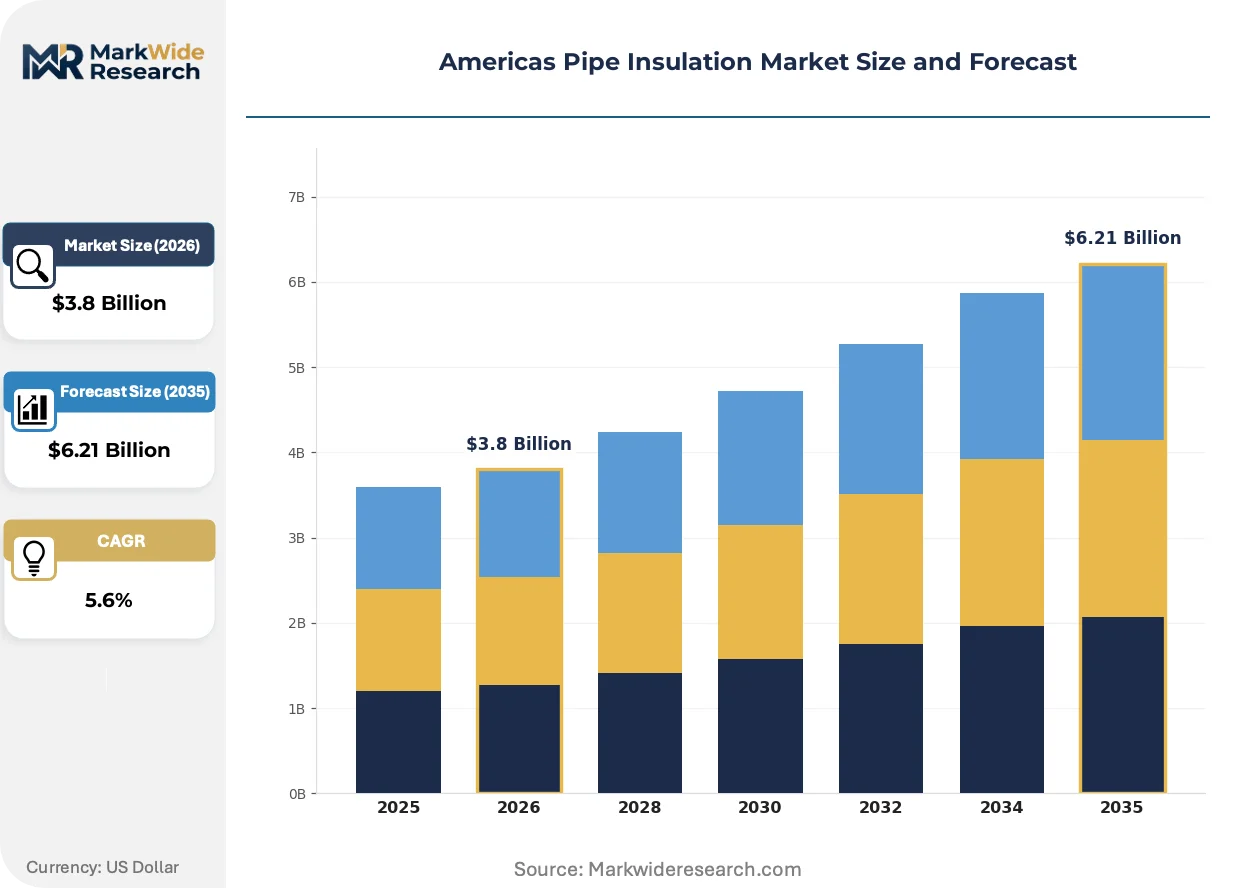
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Foam, Rubber, Mineral Wool End User: Commercial Buildings, Industrial Plants, Residential, Oil & Gas Thickness: 1 Inch, 2 Inches, 3 Inches, 4 Inches Application: Hot Water, Cold Water, Steam, HVAC |
| Companies Covered | Owens Corning, Johns Manville, Saint-Gobain, Kingspan Group, Armacell International, Rockwool International, Knauf Insulation, BASF SE, Huntsman International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Pipe Insulation Market Strategic Shifts & Innovations
A fundamental re-evaluation of total cost of ownership is reshaping material specification. The market is moving beyond initial purchase price to prioritize long-term energy performance, reduced maintenance cycles, and regulatory compliance over the asset’s entire operational lifespan.
Flexible aerogel blankets provide superior thermal insulation performance in a significantly thinner and lighter format. Industrial end-users in the oil and gas sector are increasingly specifying these materials for space-constrained or weight-sensitive applications on process piping. This advanced material is displacing traditional rigid insulation like calcium silicate and perlite in high-value, performance-critical applications.
New regulations from the US Environmental Protection Agency and updated national building codes in Canada are mandating higher minimum thermal performance levels. This regulatory push is forcing specifiers to abandon commodity-grade materials in favor of products with superior R-values per inch. The commercial HVAC and industrial refrigeration segments are most affected, accelerating the shift to elastomeric foams and advanced mineral wool products.
Life-cycle cost analysis is gaining prominence over initial material cost in procurement decisions, marking a distinct behavioral shift. The traditional model of selecting the lowest-cost bidder is being challenged by engineering-led specifications that factor in long-term energy savings and maintenance reduction. This trend is most visible in large-scale industrial projects in the US and with institutional real estate owners in Canada.
Americas Pipe Insulation Market Segmentation
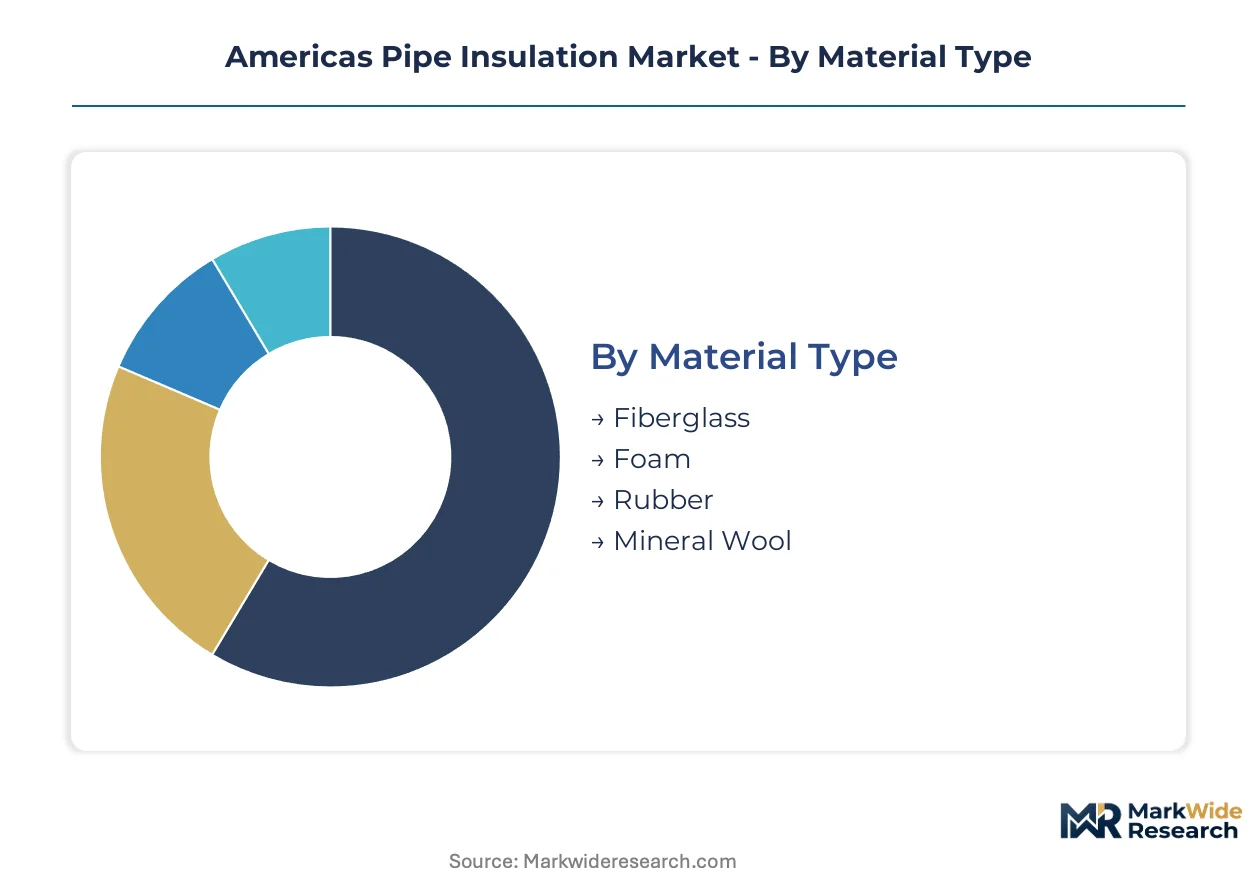
The Americas pipe insulation market exhibits segmentation across key dimensions, reflecting diverse material properties, end-user requirements, and application-specific demands. Understanding these segments helps identify pockets of concentrated demand and specialized product needs within the region.
Material Type:
Margin pools within this category are often concentrated in specialized, higher-performance materials that address specific thermal or environmental challenges.
- Fiberglass:Composed of fine glass fibers, this material offers cost-effective thermal insulation for a wide range of temperatures in industrial and commercial settings. It remains a high-volume choice for general-purpose applications across North America.
- Foam:Characterized by closed-cell structures, foam insulation provides excellent thermal resistance and condensation control, particularly for HVAC and refrigeration systems. Demand from commercial buildings in major US and Canadian cities is strong due to energy efficiency mandates.
- Rubber:Elastomeric rubber insulation offers flexibility and superior moisture resistance, making it ideal for low-temperature applications like chilled water lines and cryogenic facilities. Its use is expanding in new LNG export terminals along the US Gulf Coast.
- Mineral Wool:Manufactured from molten rock or slag, mineral wool provides high-temperature stability and fire resistance, essential for industrial process piping in petrochemical plants.
The dominant share belongs to Fiberglass, while Foam is closing the gap fastest.
End User:
Application diversity defines the end-user landscape for pipe insulation across the Americas, with each sector presenting unique performance requirements.
- Commercial Buildings:This segment utilizes insulation for HVAC, plumbing, and refrigeration systems to optimize energy performance and ensure occupant comfort. Stricter building codes in Canada drive demand for advanced materials in new construction and retrofits.
- Industrial Plants:Requires robust insulation solutions for process control, energy conservation, and safety across a broad spectrum of operating temperatures. Renewed industrial project development in Brazil creates concentrated demand for mechanical insulation systems.
- Residential:Primarily employs insulation for domestic hot water lines, heating systems, and basic plumbing to enhance energy efficiency and reduce utility expenses.
- Oil & Gas:Demands highly specialized insulation, including cryogenic grades for LNG facilities and high-temperature solutions for processing pipelines. New petrochemical facilities along the US Gulf Coast represent a significant market for these products.
Industrial Plants represent the largest consumer base, with Oil & Gas demonstrating the steepest expansion trajectory.
Thickness:
Performance requirements increasingly dictate insulation thickness, influencing material volume utilization and energy savings profiles.
- 1 Inch:Often specified for less critical applications or where space constraints are significant, such as smaller diameter domestic pipes. This thickness provides basic thermal resistance for general plumbing.
- 2 Inches:A widely adopted standard, balancing effective thermal performance with cost and installation practicality for many commercial HVAC and industrial systems. It is a common choice for process piping in manufacturing facilities.
- 3 Inches:Provides enhanced thermal resistance, crucial for meeting stricter energy efficiency mandates and maintaining precise process temperatures in industrial settings. Demand is growing in large-scale commercial retrofits in the US.
- 4 Inches:Reserved for high-performance applications, including cryogenic lines, extreme temperature industrial processes, and facilities requiring maximum energy conservation.
While 2-inch thickness holds significant volume, 3-inch and 4-inch specifications are gaining share due to stricter thermal performance standards.
Application:
Diverse customer needs drive specialized insulation applications across various thermal management requirements within the Americas.
- Hot Water:Primarily insulates lines carrying heated water in residential, commercial, and industrial settings to minimize heat loss and conserve energy. This application is fundamental across all end-user segments.
- Cold Water:Essential for preventing condensation on chilled water pipes and maintaining desired fluid temperatures in commercial HVAC and refrigeration systems. This is critical for humidity control in large buildings.
- Steam:Requires insulation capable of withstanding high temperatures to prevent significant heat loss from steam lines and ensure personnel safety in industrial plants. Petrochemical and power generation facilities are major users.
- HVAC:Encompasses insulation for heating, ventilation, and air conditioning ducts and piping, critical for energy efficiency and indoor climate control in buildings. New commercial developments in Mexico are increasing demand for these systems.
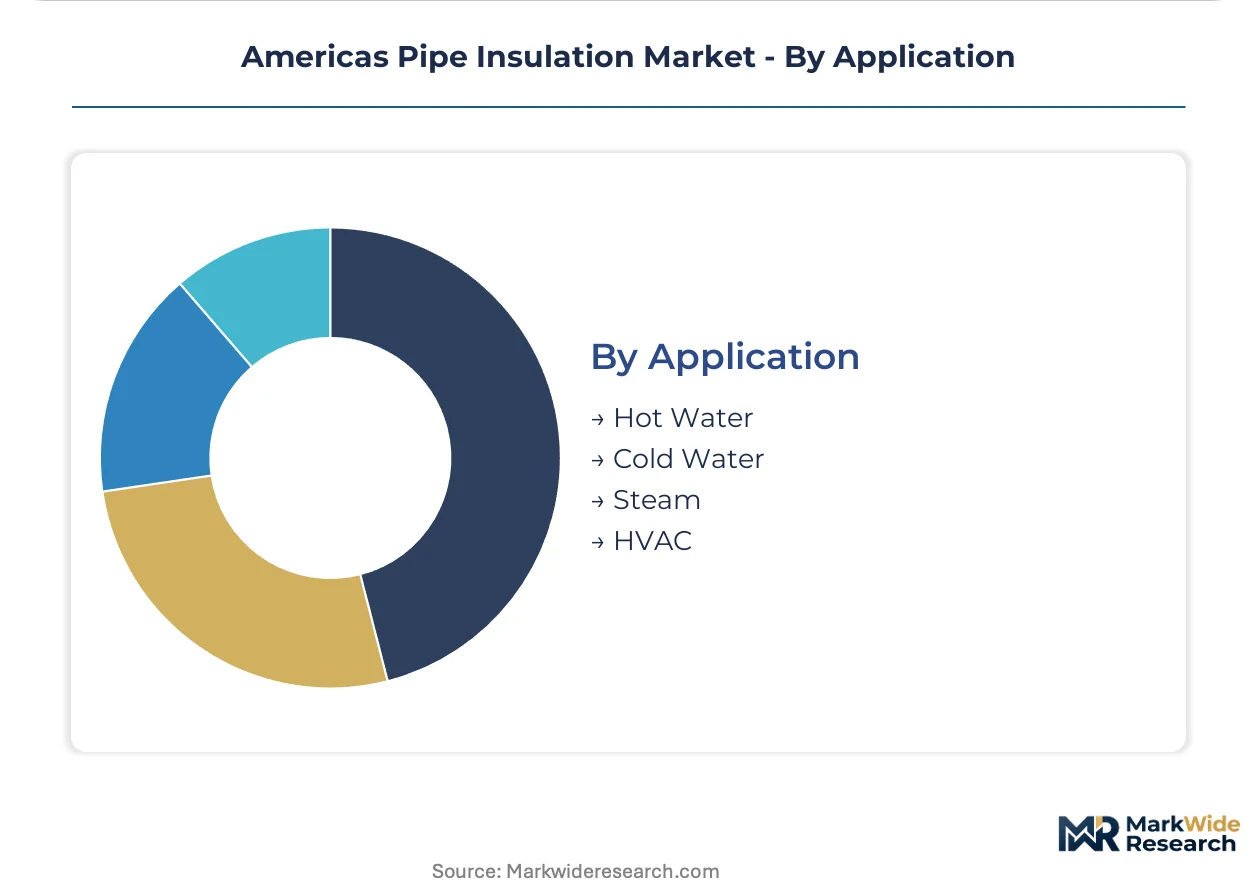
HVAC applications command a substantial portion of demand, with Steam applications requiring the most specialized material types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas pipe insulation market exhibits a dynamic interplay between domestic production and specialized material imports, particularly for high-performance applications. Stringent energy efficiency mandates across the region drive demand for advanced insulation solutions, influencing material flows. Localized industrial growth pockets further shape the regional supply and consumption patterns.
United States
Demand for pipe insulation in the United States is spurred by massive infrastructure projects and the expansion of the oil & gas sector. US EPA regulations, including updated energy efficiency standards, mandate superior thermal performance in industrial and commercial applications. The US Gulf Coast, with its burgeoning LNG export terminals and petrochemical facilities, represents a concentrated hub for cryogenic insulation demand.
Canada
Canadian pipe insulation demand is significantly influenced by stricter building codes and commercial retrofit projects aimed at energy conservation. Health Canada's guidelines and provincial building standards enforce specific thermal performance levels for new construction and renovations. Major urban centers like Toronto and Vancouver are experiencing high demand for advanced HVAC insulation in large commercial developments.
Mexico
Mexico's expanding manufacturing sector, particularly in automotive and aerospace, drives a growing need for process pipe insulation to meet international standards. The country's national energy efficiency programs encourage industrial upgrades to reduce operational costs. Industrial corridors in Nuevo León and the Bajío region are seeing increased specification of high-performance insulation systems for new factory builds.
Brazil
Renewed industrial project development in Brazil, especially within the oil, gas, and mining sectors, creates a substantial concentrated demand for mechanical insulation systems. ANVISA regulations and national energy policies are pushing for more efficient industrial processes. The São Paulo and Rio de Janeiro states, with their dense industrial parks, are focal points for large-scale pipe insulation procurement.
Americas Pipe Insulation Market Key Industry Players
Listed leaders compete with private specialists across material types and application niches within the Americas pipe insulation market. The industry structure shows a mix of large, diversified manufacturers offering a broad product portfolio, alongside smaller, specialized providers focusing on high-performance or niche solutions. Strategic archetypes include integrated material producers, application-specific foam specialists, and regional distribution networks. Capacity expansion in high-demand areas and strategic partnerships for technology licensing are dominant competitive moves as companies seek to meet regional demand and regulatory requirements.
Scale-driven material producers like Owens Corning and Saint-Gobain anchor the market through their extensive manufacturing capabilities and broad product ranges across fiberglass and mineral wool. Owens Corning, with its vast distribution network, represents a strong position in general-purpose insulation. Saint-Gobain exemplifies a diversified approach, competing across multiple segments with both mineral wool and foam-based solutions. Armacell International, a specialist in elastomeric foam insulation, occupies a strong position within HVAC and refrigeration systems, showcasing a focus on specific application areas.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Saint-Gobain |
| Kingspan Group |
| Armacell International |
| Rockwool International |
| Knauf Insulation |
| BASF SE |
| Huntsman International |
| Others |
Cost & Logistics Intelligence
Flexible aerogel blankets displacing traditional rigid insulation reshapes supply geography by concentrating high-performance material production in specialized facilities, influencing pricing economics towards value-based models.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing, which prioritizes long-term performance and regulatory compliance over initial material cost. Price differentiation stems from material R-value certification and specialized installation requirements. Pricing pressure arises from volatile petrochemical feedstock costs impacting foam-based insulation. Commercial building retrofits exhibit higher price sensitivity compared to critical oil and gas infrastructure projects.
Supply Chain Analysis
Strategic stockpiling of critical insulation materials balances project timelines against raw material volatility, particularly for large industrial contracts. Supply concentration for specialized materials centers in North America and Europe, drawing from petrochemical feedstocks and mineral resources. A structural risk involves the scarcity of skilled labor for complex cryogenic installations, creating regional chokepoints. Distribution runs through established networks and direct sales for major industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas pipe insulation market is in an early-cycle expansion phase, driven by increasing energy efficiency mandates from regulators like the US EPA. This regulatory tailwind accelerates the adoption of higher-performance insulation materials across industrial and commercial sectors.
For Market Incumbents: Shield core market share by investing in advanced material R&D, particularly for flexible aerogel blankets. Expand manufacturing capacity in strategic regions like the US Gulf Coast to meet oil and gas sector demand. This counters the threat of substitution by electric heat tracing systems. Strengthening distribution networks and securing material certifications remains a critical lever.
For New Entrants and Emerging Players: Specialized installation and project management services represent a significant service-layer gap that incumbents often underserve. Target the Mexican manufacturing sector, particularly in Nuevo León, for process pipe insulation upgrades. Focus on offering prefabricated insulation systems to mitigate high installation labor costs and improve project efficiency. This approach addresses the installer skill gap directly.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-agnostic specialists with strong regional distribution and installation capabilities. Long-term viability is robust, underpinned by sustained energy efficiency mandates and industrial expansion. Target mid-cap companies with proprietary high-performance materials or expertise in complex cryogenic insulation systems. The signal to watch is the pace of new industrial project development in Brazil and the US Gulf Coast.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | US Gulf Coast manufacturing capacity supports burgeoning LNG export terminals. |
| Technology Licensing | Partnering for aerogel blanket production addresses weight-sensitive industrial applications. |
| Green Manufacturing Transition | Adopting sustainable production methods for mineral wool aligns with environmental regulations. |
| Long-term Supply Agreement | Securing petrochemical feedstock for foam-based insulation stabilizes input costs. |
| Joint Venture | Partnering for specialized cryogenic insulation installation services addresses installer skill shortages. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers, procurement managers, HVAC specifiers, and construction project leads, then refined. This involved combining insights from these industry stakeholders with secondary validation from US EPA reports, Canadian building codes, and trade association publications. The analysis employed both bottom-up market sizing and top-down validation to ensure robust data triangulation.
Variance decomposition was applied to project market trajectories across the analysis window, segmenting by material type, end-user, thickness, application, and regional industrial activity. Compound annual growth rates were derived from historical trends and projected demand drivers. Key industry-specific forecast inputs included new LNG terminal construction schedules and commercial building retrofit rates in North America.
Underlying assumptions cover a stable regulatory environment and consistent raw material supply, with deviation risk concentrated in geopolitical events affecting energy projects. Forecasts reflect these assumptions. Revision becomes warranted when significant shifts in energy policy or industrial investment cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Active Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global High Temperature Insulation Materials Market