
 Global Pipe Insulation Market | 2026-2036
Global Pipe Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipe Insulation Market Foresight
Southeast Asia is narrowing the supply gap for high-temperature pipe insulation as Vietnam, Indonesia, and Thailand expand refining and power generation infrastructure. Owens Corning leverages its fiberglass manufacturing scale to serve petrochemical clients across the region. Johns Manville anchors its position through specialized calcium silicate products for industrial steam systems. Armacell competes with flexible elastomeric foam solutions targeting HVAC and refrigeration applications.
Pipe insulation comprises engineered materials applied to piping systems to reduce thermal energy transfer, control surface temperatures, and prevent condensation, typically specified by thermal conductivity values measured in watts per meter-kelvin and maximum service temperature thresholds exceeding 650°C for industrial mineral wool systems. Its primary purpose spans energy conservation in district heating networks, process temperature maintenance in chemical manufacturing, and personnel protection against burn hazards in power plants. Fiberglass and mineral wool categories dominate retrofit and maintenance spending due to their fire resistance and compatibility with existing infrastructure. Polyurethane foam segments capture premium positions in cryogenic and sub-ambient applications where closed-cell structures prevent moisture ingress. Cellular glass insulation occupies niche roles in corrosive environments and hydrocarbon processing where dimensional stability under thermal cycling commands higher pricing.
The EPA enforces emissions standards that indirectly tighten thermal efficiency requirements for industrial piping in US facilities, while REACH and the EU F-Gas Regulation constrain blowing agent chemistries and material compositions across European supply chains. China's MEE implements dual carbon goals that elevate energy conservation mandates for district heating and industrial steam distribution networks. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment procurement strategies and reshape supplier qualification criteria.
Market Dynamics
The EU F-Gas Regulation's phase-down of high-global-warming-potential blowing agents is forcing polyurethane foam manufacturers to reformulate product lines while chemical plants across Southeast Asia expand thermal protection requirements for rising process temperatures.
Growth Catalysts
- REACH and EU F-Gas Regulation:The phase-down mandates for HFC blowing agents accelerate demand for next-generation polyurethane formulations with lower climate impact, creating replacement cycles across European industrial infrastructure.
- Petrochemical corridor expansion:India's Gujarat coast refinery capacity additions require extensive high-temperature pipeline networks, concentrating procurement for mineral wool and calcium silicate systems.
- District heating modernization:China's MEE dual carbon goals elevate energy conservation mandates for urban steam distribution, driving retrofit specifications for cellular glass and fiberglass solutions.
Market Restraints
- Raw material volatility:Isocyanate and polyol feedstock prices fluctuate with crude oil indices, compressing margins for polyurethane foam producers serving cryogenic applications.
- Supplier concentration:Cellular glass manufacturing capacity clusters in Western Europe and select US facilities, creating lead time vulnerabilities for Asian hydrocarbon processors.
- Technical performance ceilings:Flexible elastomeric foams face maximum service temperature thresholds around 120°C, excluding them from industrial steam systems where calcium silicate dominates.
Strategic Opportunities
- Vietnam industrialization:Power generation and refining infrastructure buildouts in Vietnam create first-mover positioning for high-temperature insulation suppliers establishing local fabrication partnerships.
- Hydrogen economy infrastructure:Cryogenic hydrogen transport pipelines require vacuum-insulated pipe-in-pipe systems, opening premium segments beyond conventional materials.
- Digital specification platforms:Engineering procurement is migrating to cloud-based material selection tools that bypass traditional distributor networks, favoring suppliers with embedded thermal calculation software.
Industry Challenges
- Thermal engineering specialization:Complex heat loss calculations for multi-layer insulation systems require scarce computational fluid dynamics expertise, extending project design cycles.
- Certification fragmentation:Fire safety ratings diverge between ASTM E84, EN 13501, and GB 8624 standards, forcing manufacturers to maintain parallel testing regimens for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipe Insulation Market |
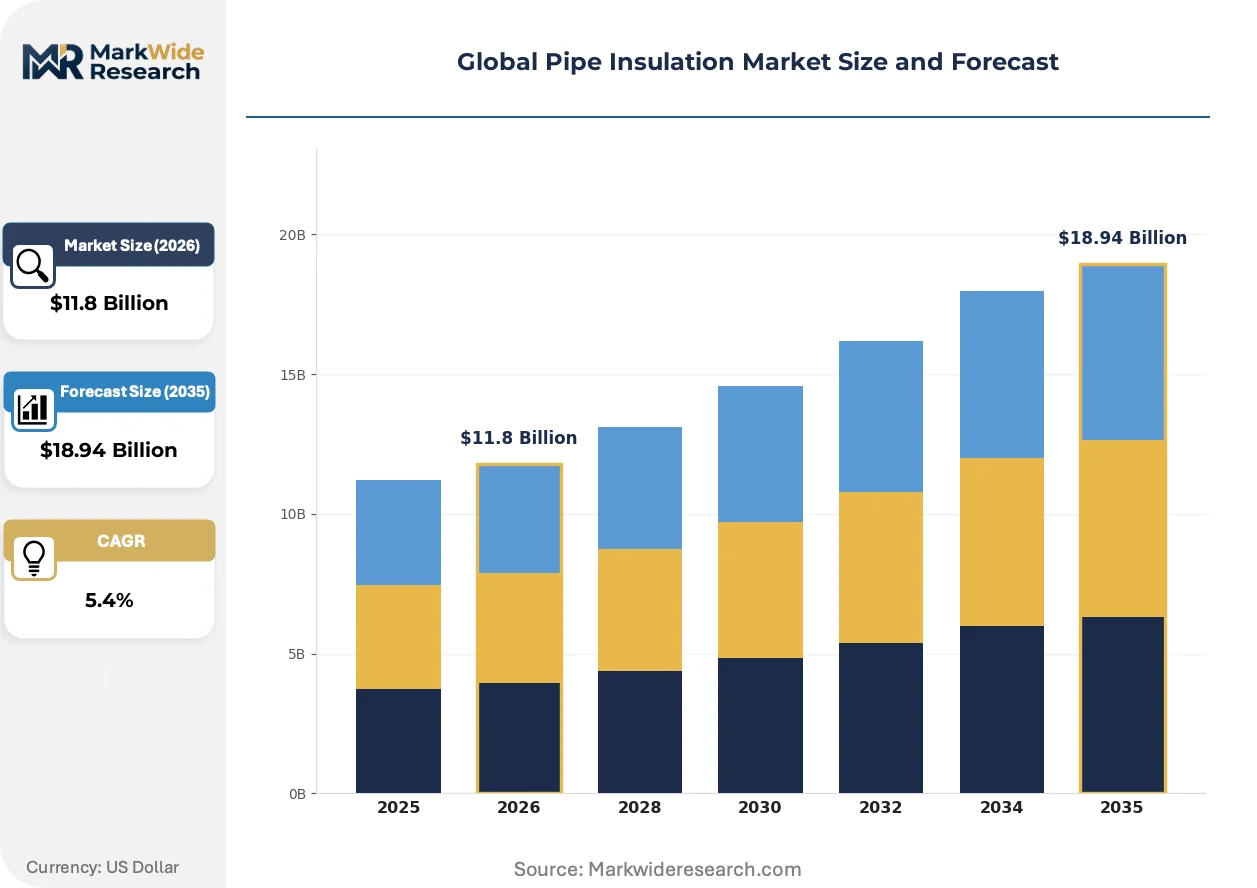
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Polyurethane Foam, Mineral Wool, Calcium Silicate, Cellular Glass End Use Industry: Oil & Gas Refineries, Chemical Plants, Power Generation, HVAC Systems, Food & Beverage Processing Application: Thermal Insulation, Acoustic Noise Control, Fire Protection, Corrosion Prevention, Energy Conservation Installation Type: New Construction, Retrofit Projects, Maintenance and Repair, Industrial Plants, Commercial Facilities |
| Companies Covered | Owens Corning, Johns Manville, Saint-Gobain, Armacell, BASF, Kingspan Group, Rockwool International, Knauf Insulation, Huntsman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipe Insulation Market Shifts & Advancements
Aerogel composite insulation is compressing installed thickness requirements while bio-based blowing agents are displacing synthetic chemistries in polyurethane production. Digital twin integration is reshaping how operators monitor thermal performance across pipeline networks.
Aerogel blankets embedded with fiberglass scrim deliver thermal conductivity values below 0.020 W/m·K at sub-ambient temperatures. LNG terminal operators in the US Gulf Coast and Qatar are specifying these systems for boil-off gas reduction. Conventional multi-layer perlite systems are rendering obsolete in cryogenic loading arms and transfer lines where space constraints dominate.
The EU F-Gas Regulation's stepped reductions in GWP thresholds tighten through 2030, prohibiting HFC-245fa and HFC-365mfc in new polyurethane foam production. European insulation producers are qualifying hydro-olefin and methyl formate alternatives with reformulated catalyst packages. Cold chain logistics facilities in Germany and the Netherlands face accelerated equipment replacement timelines as existing stock ages out of compliance.
Asset owners are unbundling insulation installation from long-term thermal performance contracts. EPC firms in the Middle East are absorbing installation risk while specialist contractors guarantee energy savings outcomes through multi-year service agreements. This model is concentrating procurement authority with project developers in Saudi Arabia's giga-project pipeline rather than distributed maintenance departments.
Global Pipe Insulation Market Segmentation
Material specifications dictate thermal performance thresholds and regulatory compliance pathways across industrial piping networks. End-use requirements fragment procurement criteria between high-temperature hydrocarbon processing and sub-ambient cryogenic systems. Application priorities determine whether energy conservation, personnel safety, or process control drives specification decisions.
Material Type:
Use-case spectrum spans fire-resistant mineral systems for refinery steam lines to flexible elastomeric foams for refrigeration circuits.
- Fiberglass:Composed of fine glass fibers bound with thermosetting resins, delivering thermal conductivity values around 0.040 W/m·K and service temperatures to 540°C. Demand concentrates in US Gulf Coast petrochemical complexes where Owens Corning and Johns Manville supply retrofit programs for aging refinery infrastructure facing EPA emissions enforcement.
- Polyurethane Foam:Closed-cell structure blown with hydro-olefin or methyl formate agents post-F-Gas reformulation, achieving thermal conductivity below 0.025 W/m·K for cryogenic service. Procurement accelerates in Germany and the Netherlands as cold chain logistics facilities replace HFC-based legacy stock ahead of regulatory deadlines.
- Mineral Wool:Spun from molten rock or slag with inorganic binder systems, rated to 650°C continuous exposure. Dominates India's Gujarat coast refinery expansions requiring high-temperature pipeline networks.
- Calcium Silicate:Hydrous calcium silicate reinforced with organic fibers, specified for industrial steam systems to 650°C where dimensional stability under thermal cycling is critical. Johns Manville anchors supply through specialized formulations.
- Cellular Glass:Foamed glass with closed-cell structure impermeable to moisture and hydrocarbons, commanding premium pricing in corrosive chemical processing environments. Manufacturing capacity clusters in Western Europe and select US facilities.
Established volume favors fiberglass; emerging adoption favors polyurethane foam with reformulated blowing agents.
End Use Industry:
Cost tier segmentation separates capital-intensive greenfield refinery projects from maintenance-budget-driven facility upgrades.
- Oil & Gas Refineries:High-temperature process lines, crude distillation units, and catalytic reformers requiring insulation to 650°C with fire-rated enclosure systems. Vietnam, Indonesia, and Thailand infrastructure buildouts concentrate procurement for mineral wool and calcium silicate.
- Chemical Plants:Corrosive process environments with thermal cycling demands, spanning sulfuric acid lines to polymerization reactors. Southeast Asian capacity expansions are narrowing supply gaps for high-temperature protection as process temperatures rise.
- Power Generation:Steam distribution networks, turbine exhaust systems, and flue gas desulfurization ducting. China's MEE dual carbon goals elevate energy conservation mandates for urban district heating retrofits.
- HVAC Systems:Chilled water distribution, refrigeration suction lines, and air handling unit connections. Armacell competes with flexible elastomeric foam solutions targeting commercial building mechanical rooms.
- Food & Beverage Processing:Clean-in-place steam lines, cryogenic freezing tunnels, and controlled-atmosphere storage. Sanitary-grade stainless steel jacketing requirements differentiate procurement from industrial specifications.
Refinery and chemical segments absorb premium material costs; HVAC and food processing segments prioritize installation speed and moisture resistance.
Application:
Volume concentration aligns with energy conservation mandates in district heating and process temperature maintenance in chemical manufacturing.
- Thermal Insulation:Reduces conductive and convective heat transfer to maintain process fluid temperatures, minimize energy consumption, and control surface temperatures for personnel protection. Specified by thermal conductivity values measured in watts per meter-kelvin across all industrial sectors.
- Acoustic Noise Control:Combines porous absorption materials with mass-loaded barriers to attenuate valve noise, pump cavitation, and gas expansion roar in compressor stations. Multi-layer systems incorporate mineral wool with perforated metal facing.
- Fire Protection:Maintains structural integrity of fire-rated enclosures, prevents flame propagation along piping runs, and protects adjacent equipment during pool fire scenarios. ASTM E84, EN 13501, and GB 8624 ratings force parallel testing regimens for export markets.
- Corrosion Prevention:Closed-cell structures prevent moisture ingress to underlying pipe surfaces, supplemented by vapor barrier jacketing in humid climates. Cellular glass dominates hydrocarbon processing where dimensional stability commands higher pricing.
- Energy Conservation:Quantified through heat loss calculations and lifecycle cost analysis, increasingly tied to performance contracting models. EPC firms in Saudi Arabia's giga-project pipeline absorb installation risk while guaranteeing savings outcomes.
Thermal and energy conservation applications dominate retrofit spending; fire protection and acoustic control gain specification share in greenfield projects with integrated safety engineering.
Installation Type:
Customer type segmentation separates owner-operated maintenance departments from EPC-led capital projects with bundled procurement authority.
- New Construction:Greenfield refinery, power plant, and chemical complex installations with integrated insulation specification during front-end engineering design. Allows optimal material selection without existing infrastructure constraints.
- Retrofit Projects:Systematic replacement of degraded or non-compliant insulation in operating facilities, often executed during scheduled turnarounds. District heating modernization in China and Europe drives fiberglass and cellular glass specifications.
- Maintenance and Repair:Reactive and preventive interventions addressing mechanical damage, moisture intrusion, or thermal performance degradation. Fiberglass and mineral wool categories capture recurring spend due to fire resistance and existing infrastructure compatibility.
- Industrial Plants:Heavy process industry facilities with specialized requirements for high temperatures, chemical exposure, and mechanical abuse. Procurement authority is concentrating with project developers rather than distributed maintenance departments.
- Commercial Facilities:Institutional buildings, data centers, and retail infrastructure with emphasis on installation speed, appearance, and occupant safety. Flexible elastomeric foams face maximum service temperature thresholds around 120°C, excluding steam system applications.
Retrofit and maintenance categories sustain recurring revenue for established materials; new construction and industrial plant segments open specification opportunities for aerogel composites and advanced formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA enforces emissions standards that indirectly tighten thermal efficiency requirements for industrial piping in US facilities. Regional procurement patterns diverge between mature retrofit markets and greenfield expansion corridors.
United States
Gulf Coast petrochemical complexes drive demand for high-temperature fiberglass systems as aging refinery infrastructure faces EPA emissions enforcement. The EPA's industrial greenhouse gas protocols elevate energy conservation specifications for process steam networks. Houston and Corpus Christi anchor procurement concentration for Owens Corning and Johns Manville retrofit programs.
Germany
Cold chain logistics facilities accelerate equipment replacement timelines as existing polyurethane stock ages out of EU F-Gas Regulation compliance. REACH and stepped GWP threshold reductions through 2030 prohibit HFC-245fa and HFC-365mfc in new foam production. The Rhine-Ruhr industrial belt concentrates reformulation activity for hydro-olefin and methyl formate alternatives.
China
The MEE implements dual carbon goals that elevate energy conservation mandates for district heating and industrial steam distribution networks. GB standards for building energy efficiency tighten specifications for urban pipeline retrofits. The Yangtze River Delta and Pearl River Delta drive cellular glass and fiberglass demand for modernization programs.
India
Refinery capacity additions along the Gujarat coast require extensive high-temperature pipeline networks, concentrating procurement for mineral wool and calcium silicate systems. The CEA mandates thermal performance standards for industrial energy efficiency. The Jamnagar and Vadodara petrochemical clusters absorb premium material costs for fire-rated enclosure systems.
Vietnam
Power generation and refining infrastructure buildouts create first-mover positioning for high-temperature insulation suppliers establishing local fabrication partnerships. National industrialization targets elevate process temperature requirements across chemical manufacturing. The Vung Tau and Hai Phong industrial zones attract regional supply chain investment for steam system protection.
Global Pipe Insulation Market Competitive Landscape
Capability concentration sits with specialized high-temperature formulation experts; scale advantage sits with integrated fiberglass and mineral wool producers. The vendor base separates into three tiers: multinational material science conglomerates with full portfolio coverage, regional fabrication specialists serving EPC contractors, and niche aerogel composite innovators targeting cryogenic premiums. Consolidation pressure runs through M&A activity among European polyurethane reformulators and capacity expansion for cellular glass in hydrocarbon processing corridors.
Among North American building materials conglomerates, Owens Corning and Johns Manville exemplify the scale-driven archetype, leveraging manufacturing breadth to serve petrochemical retrofit cycles. Saint-Gobain occupies a position within the European specialty materials tier, anchoring supply relationships through technical specification authority. Armacell represents the flexible systems specialist archetype, targeting commercial HVAC and refrigeration applications where installation speed commands procurement priority.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Saint-Gobain |
| Armacell |
| BASF |
| Kingspan Group |
| Rockwool International |
| Knauf Insulation |
| Huntsman International |
| Others |
Supply & Pricing Matrix
Western European cellular glass manufacturing clusters around Pittsburgh Corning's legacy facilities and select German industrial zones, concentrating high-performance insulation supply and sustaining premium pricing power for hydrocarbon processing applications where dimensional stability commands procurement priority. Buyers in Southeast Asian refinery expansions absorb extended lead times and freight premiums as they source from these distant supply hubs, while regional fabrication partnerships in Vietnam and Indonesia attempt to capture value through local jacketing and installation services.
Pricing Analysis
Price spreads between European and Asian supply sources widen during feedstock volatility cycles as isocyanate and polyol costs track crude oil indices. Three-tier pricing structure across premium, standard, and economy levels separates certified cellular glass systems for corrosive chemical processing from commodity fiberglass batts and unbranded mineral wool. Cost compression in polyurethane foam segments is intensifying because REACH and EU F-Gas Regulation reformulation expenses transfer to downstream buyers. HVAC contractors demonstrate highest price sensitivity due to thin installation margins, while oil and gas EPCs prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Isocyanate and polyol feedstocks for polyurethane production draw from petrochemical complexes in Germany, the Netherlands, and Belgium, tethering European insulation manufacturers to regional cracking capacity. Glass fiber supply rests on soda ash and silica sand mining operations in the United States, China, and Egypt. Single-source vulnerability concentrates in hydro-olefin blowing agent supply as European producers qualify methyl formate alternatives. Distribution runs through EPC contractor networks and specialized industrial distributors serving maintenance departments and project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipe insulation market is recovering from a cyclical trough as refinery capacity expansion cycles in India and Southeast Asia reactivate procurement pipelines. Capital project backlogs accumulated during energy price volatility are now releasing, driving specification activity for high-temperature mineral wool and calcium silicate systems.
For Market Incumbents: Build switching-cost moats through embedded thermal calculation software that locks engineering procurement into proprietary specification platforms. Incumbents should acquire regional fabrication specialists in Vietnam and Indonesia to compress lead times for Southeast Asian refinery projects. The threat of aerogel composite displacement in cryogenic applications demands accelerated R&D partnerships with LNG terminal operators to co-develop next-generation vacuum-insulated pipe-in-pipe systems. Backward integration into blowing agent chemistry secures supply security as EU F-Gas Regulation tightens. For New Entrants and Emerging Players: Vietnam's industrial zones present underpenetrated demand for high-temperature insulation suppliers establishing local fabrication partnerships. New entrants should target the hydrogen economy infrastructure segment where cryogenic transport pipeline specifications remain unsettled and first-mover technical validation commands premium positioning. A go-to-market angle through digital specification platforms bypasses entrenched distributor relationships and reaches engineering procurement directly. For Investors and Strategic Acquirers: Long-term, this sits as a cyclical industrial materials play because refinery and chemical plant investment cycles drive decade-long replacement waves for thermal protection systems. Acquisition targets should display specialized high-temperature formulation expertise rather than commodity fiberglass scale. The signal to watch is F-Gas Regulation compliance timeline acceleration in European cold chain logistics, which would force accelerated replacement cycles and concentrate procurement authority with reformulation-capable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Chemistry | Secures supply of hydro-olefin and methyl formate alternatives as EU F-Gas Regulation tightens GWP thresholds. |
| Local Fabrication Partnerships in Vietnam | Compresses lead times for Vung Tau and Hai Phong refinery projects against Western European supply clusters. |
| Digital Specification Platform Development | Embeds thermal calculation software that locks engineering procurement into proprietary platforms bypassing distributors. |
| Aerogel Composite R&D Partnerships | Co-develops next-generation vacuum-insulated pipe-in-pipe systems with Qatar and US Gulf Coast LNG terminal operators. |
| Regional Acquisition of Fabrication Specialists | Captures installation value and specification influence in India's Gujarat coast petrochemical corridor expansions. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant engineers, EPC procurement leads, insulation specification consultants, and maintenance directors at hydrocarbon processing facilities; and secondary validation through customs and trade data, chemical industry association reports, SEC filings from listed building materials conglomerates, and regulatory filings with EPA and ECHA. Bottom-up triangulation across material-type demand estimates and top-down cross-checks against end-use industry capital expenditure patterns anchored volume projections.
Forecast inputs considered material specifications, end-use industry requirements, application priorities, and installation type procurement patterns across the projection horizon. Segmentation dimensions modeled include thermal performance thresholds, regulatory compliance pathways, and regional infrastructure investment cycles. CAGRs were derived from historical replacement rates in district heating networks and greenfield refinery construction timelines, incorporating isocyanate feedstock cost trajectories and F-Gas Regulation phase-down schedules as industry-specific variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese fiberglass producers or accelerated aerogel composite adoption by LNG operators would shift outcomes. Cross-checking against EPC contractor order backlogs and national refinery commissioning schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Polyisocyanurate Insulation Market