
 Americas Steel Pipes Market | 2026-2036
Americas Steel Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Steel Pipes Market Analysis
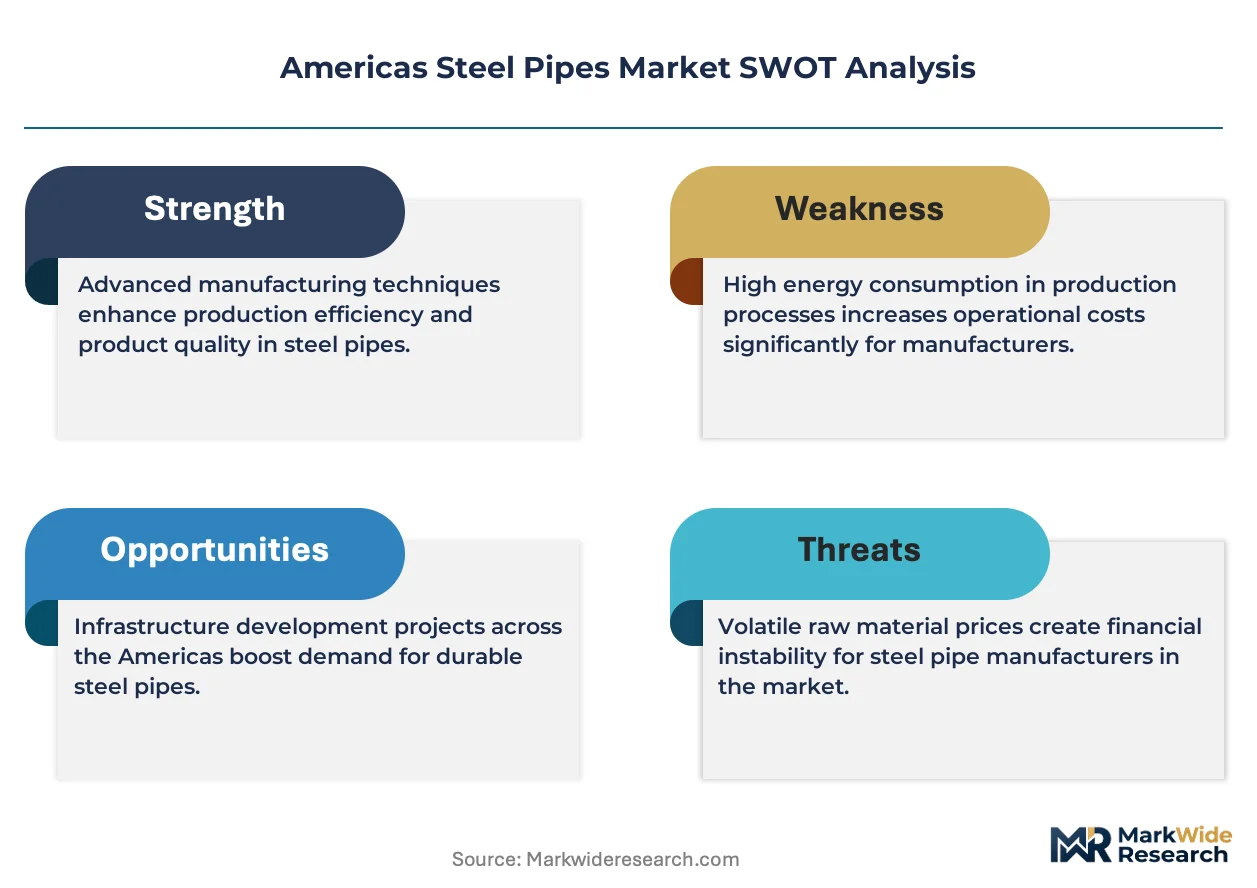
Market Dynamics
The distributor-wholesaler channel is narrowing as energy providers and large contractors pursue direct mill relationships for long-term offtake. Nucor Corporation leverages its electric arc furnace network to sustain cost-advantaged coil supply for pipe production. Tenaris anchors South American demand through its integrated seamless pipe operations in Argentina and Mexico. JSW Steel USA competes aggressively on plate and coil conversion for spiral and longitudinal welded products.
Product Landscape
Americas steel pipes are hollow cylindrical sections manufactured from carbon or alloy steel grades, typically produced through hot rolling, welding, or extrusion processes with wall thicknesses ranging from schedule 40 to heavy-wall X80 grades for high-pressure service. These products convey fluids, gases, and structural loads across oilfield gathering networks, municipal water systems, and commercial building frames. Welded pipes dominate volume throughput due to lower unit economics on standard diameters, while seamless pipes command premium positioning in sour gas and deepwater applications where defect tolerance thresholds are minimal. Coated pipes represent the fastest-expanding product class as fusion-bonded epoxy and three-layer polyethylene systems extend field life in corrosive soil and subsea environments.
Regulatory Environment
API 5L and ASTM A53 standards govern dimensional and metallurgical specifications across US and Canadian jurisdictions, while Mexico's national standards body enforces NOM compliance for pressure-rated products. The US Buy America Act and Canadian Content Requirements restrict federally funded infrastructure to domestically melted and finished steel, reshaping cross-border sourcing patterns for water and energy transmission projects. Stakeholders must monitor evolving domestic content thresholds and harmonization gaps between USMCA partners to avoid qualification failures on public procurements.
Market Dynamics
The distributor-wholesaler channel is narrowing as energy providers and large contractors pursue direct mill relationships for long-term offtake agreements, compressing traditional intermediaries and reshaping pricing power toward integrated producers.
Growth Catalysts
- Energy Transmission Buildout:North American midstream operators are expanding gathering and trunk line networks to accommodate Permian and Vaca Muerta production growth, pulling large-diameter line pipe demand.
- Buy America Compliance:US federally funded water infrastructure mandates domestic melt and finish requirements, locking in qualified domestic mill capacity for municipal transmission projects.
- Corrosion-Resistant Coatings:Fusion-bonded epoxy and three-layer polyethylene systems are extending asset life in sour service and subsea environments, expanding replaceable inventory cycles.
Market Restraints
- Scrap-Coil Cost Volatility:Electric arc furnace operators face margin compression when shredded scrap prices spike above $400 per ton, squeezing welded pipe conversion economics.
- Seamless Supply Concentration:Argentina and Mexico host the hemisphere's only integrated seamless billet-to-pipe capacity, creating geographic single-source risk for high-pressure applications.
- Composite Substitution:Reinforced thermoplastic pipes are capturing gathering line share in low-pressure CO2 and water service, displacing steel in corrosion-critical loops.
Strategic Opportunities
- Brazil Pre-Salt Development:Santos Basin deepwater projects require X70 and X80 grade heavy-wall seamless strings, opening premium product penetration for qualified mills.
- Carbon Capture Infrastructure:CO2 pipeline networks for enhanced oil recovery and sequestration hubs demand high-integrity welded systems with sour service certification.
- Direct Mill Procurement:Contractor-of-record models are replacing distributor stocking programs, enabling long-term volume commitments and co-developed specification tiers.
Industry Challenges
- Welder Certification Bottlenecks:API 1104-qualified manual and automated welding inspectors face acute shortages, delaying field joint qualification on transmission spreads.
- Buy America Documentation Burden:Melt and pour certificate tracing through multi-step coil supply chains consumes procurement bandwidth and extends qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Steel Pipes Market |
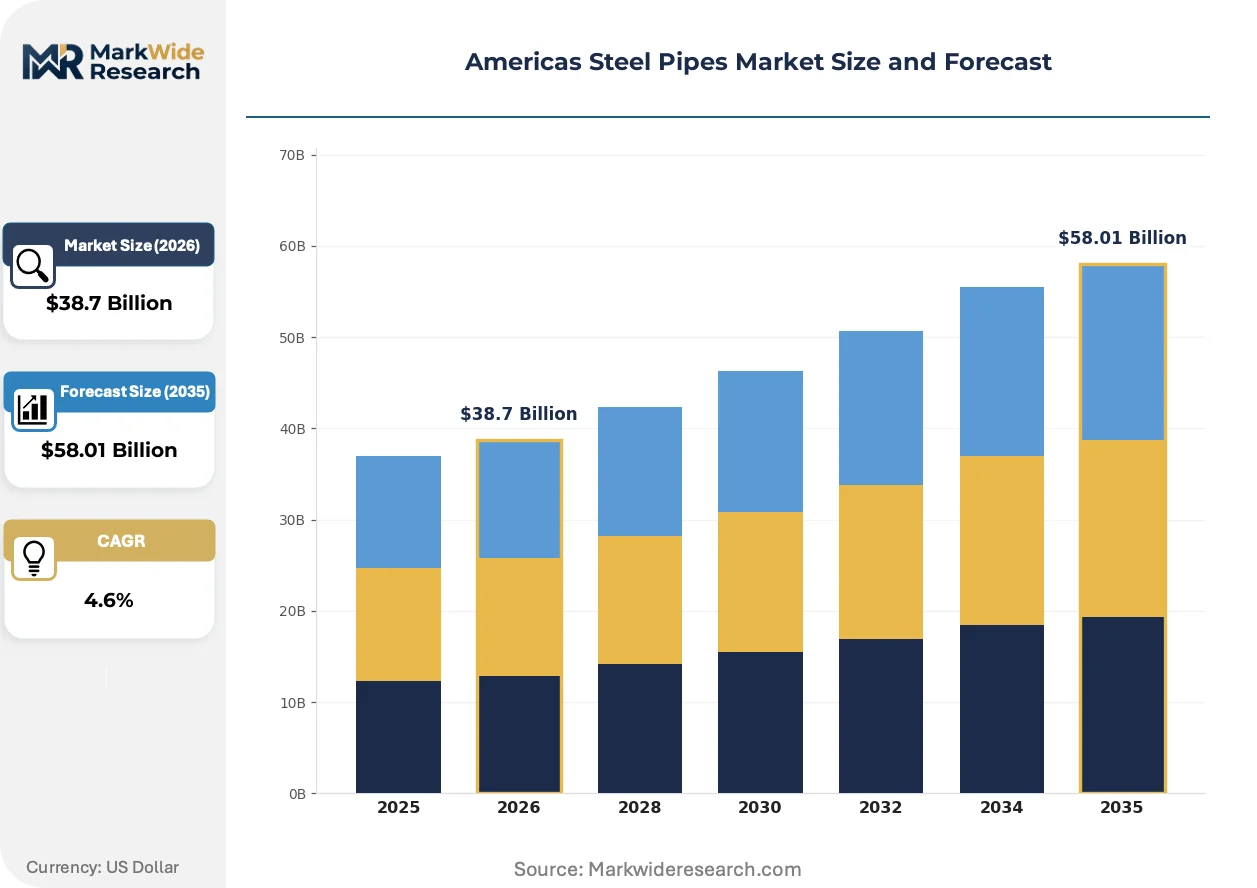
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Oil & Gas, Water Supply, Automotive Product Type: Seamless Pipes, Welded Pipes, Spiral Pipes, Coated Pipes End User: Manufacturers, Contractors, Municipalities, Energy Providers Technology: Hot Rolling, Cold Rolling, Extrusion, Welding |
| Companies Covered | Nucor Corporation, United States Steel Corporation, ArcelorMittal USA, Tenaris, American SpiralWeld Pipe, Welspun Tubular, JSW Steel USA, Valmont Tubing, Tubos de Acero de Mexico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Steel Pipes Market Emerging Trajectories
Steel pipe manufacturing is converging with digital traceability and advanced metallurgy, compressing specification development cycles while extending asset performance guarantees into previously uneconomical service environments.
High-frequency electric resistance welding is hybridizing with inline ultrasonic testing and automated seam annealing, producing weld zones with toughness properties approaching parent plate. Midstream operators in the Permian and Bakken are specifying these enhanced HFW products for gathering lines previously reserved for seamless. The technology is compressing the premium gap between welded and seamless pressure ratings.
The US Buy America Act and Canadian Content Requirements are tightening domestic content verification through certified mill test reports and melt-source affidavits. Cross-border suppliers without integrated US or Canadian melt capacity face disqualification from federal water and energy infrastructure procurements. Mexican producers with USMCA-qualified coil supply are repositioning to capture displaced Asian import share.
Specification-driven procurement is consolidating buyer power around engineering-procurement-construction firms and major midstream operators, marginalizing distributor inventory carrying roles. Direct mill contracts with five-year offtake terms are replacing spot purchasing and stock-and-defer arrangements. The shift is most visible in Texas and Alberta, where operator consolidation has concentrated annual pipe demand among fewer procurement desks.
Americas Steel Pipes Market Segmentation
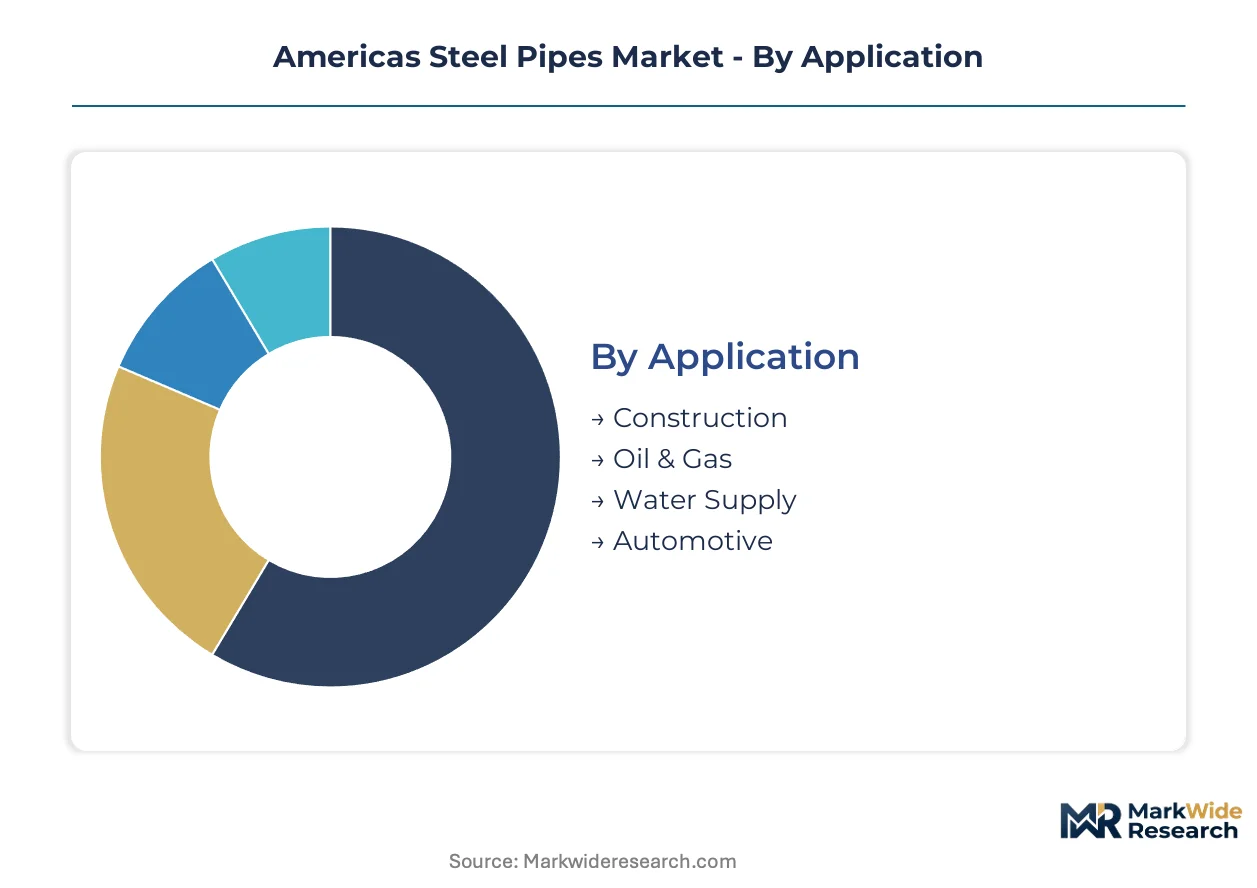
Steel pipe specifications vary sharply across pressure ratings, corrosion exposure, and installation environments. Procurement patterns diverge between spot-buy distributors and long-term direct mill contracts. Understanding segment boundaries clarifies where margin concentrates and where volume commoditizes.
Application:
Use-case spectrum spans structural loading, hydrocarbon containment, fluid transmission, and precision engineering tolerances.
- Construction:Hollow structural sections and standard schedule pipe carry dead loads across commercial building frames and infrastructure pilings. Demand clusters in Texas urban corridors and Brazilian commercial development zones where high-rise permitting accelerates.
- Oil & Gas:Line pipe and OCTG strings withstand internal pressure cycling and sour gas exposure. Permian Basin gathering systems and Vaca Muerta trunk lines pull X70 and X80 grade specifications from qualified domestic mills.
- Water Supply:Cement-lined and epoxy-coated ductile iron alternatives compete for municipal transmission mains. US Buy America compliance locks federally funded projects to domestic melt and finish capacity.
- Automotive:Precision-drawn mechanical tubing serves chassis components and exhaust architectures. Mexican automotive assembly clusters consume tight-tolerance cold-finished products.
Established volume favors Oil & Gas; emerging adoption favors Water Supply.
Product Type:
Cost tier stratification separates premium defect-free seamless from commodity welded throughput.
- Seamless Pipes:Solid billet extrusion eliminates longitudinal weld seams for sour service and deepwater reliability. Santos Basin pre-salt development and Bakken high-pressure injection wells specify heavy-wall X80 strings from Argentine and Mexican integrated mills.
- Welded Pipes:Coil-fed longitudinal or spiral forming delivers lower unit economics on standard diameters. Electric resistance welding dominates line pipe for Permian gathering networks where pressure ratings permit.
- Spiral Pipes:Helical seam construction from heavy plate enables large-diameter transmission at reduced wall thickness. Brazilian and Mexican water infrastructure projects specify spiral-welded for trunk line diameter requirements.
- Coated Pipes:Fusion-bonded epoxy and three-layer polyethylene systems extend field life in corrosive soil and subsea environments. Coated products are gaining share fastest in offshore Brazil and US Gulf Coast replacement cycles.
Price differentiation separates seamless premium positioning from welded commodity throughput.
End User:
Customer type determines procurement sophistication and contract duration.
- Manufacturers:Downstream fabricators and equipment builders source mechanical tubing and pressure-rated components for value-added assembly. Automotive and appliance OEMs in Mexico specify tight dimensional tolerances.
- Contractors:Engineering-procurement-construction firms consolidate direct mill negotiations for project-specific lots. Texas and Alberta pipeline spreads increasingly bypass distributor inventory.
- Municipalities:Public water authorities face Buy America documentation burdens and extended qualification timelines. US federal funding compliance restricts sourcing to certified domestic melt capacity.
- Energy Providers:Integrated midstream operators and utility holding companies execute five-year offtake agreements. Long-term volume commitments reshape pricing power toward integrated producers.
Procurement concentration favors Energy Providers; regulatory complexity burdens Municipalities.
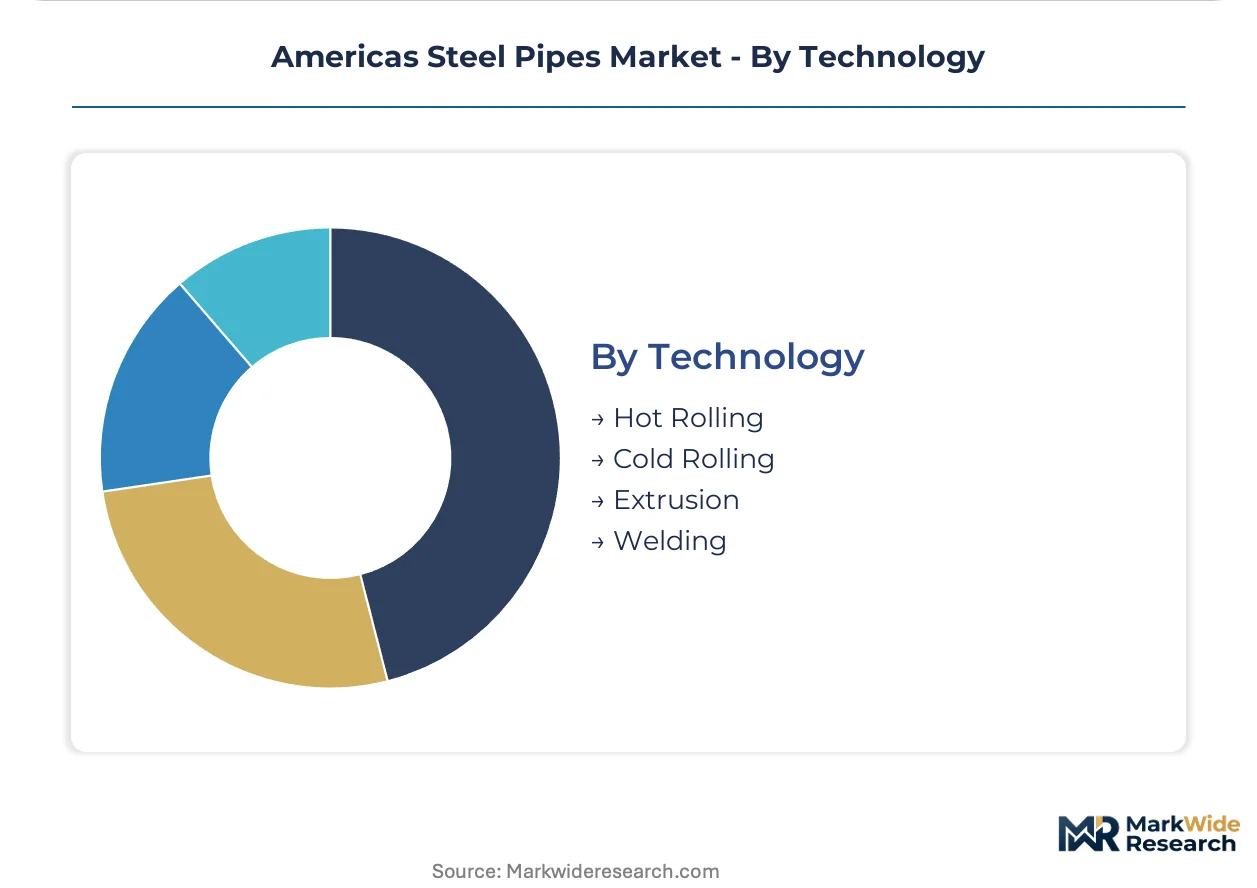
Technology:
Process maturity and capital intensity separate hot-formed bulk production from precision finishing.
- Hot Rolling:Continuous casting and roughing mill reduction produces parent plate and coil for welded pipe feedstock. Nucor's electric arc furnace network supplies cost-advantaged hot-rolled coil across the southern US.
- Cold Rolling:Precision dimensional control and surface finish improvement serve automotive and mechanical tubing specifications. Mexican cold-finishing capacity supports maquiladora automotive component supply.
- Extrusion:Solid billet piercing and mandrel elongation create defect-free seamless hollows. Argentina and Mexico host the hemisphere's only integrated seamless billet-to-pipe capacity.
- Welding:High-frequency electric resistance and submerged arc processes dominate longitudinal and spiral seam joining. Inline ultrasonic testing and automated seam annealing compress the toughness gap with seamless parent material.
Capital deployment favors Welding; technical barrier concentration sits with Extrusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure incentives and domestic content mandates are redrawing procurement geographies across the hemisphere. Energy transmission buildouts and water utility modernization anchor demand concentration in specific industrial corridors.
United States
Permian Basin midstream expansion and Gulf Coast LNG export terminals pull large-diameter line pipe specifications toward Texas and Louisiana manufacturing clusters. FERC pipeline certification requirements and EPA environmental reviews extend project timelines, compressing spot purchasing windows. Houston-Galveston anchors distributor consolidation as direct mill procurement displaces traditional stocking programs.
Brazil
Pre-salt Santos Basin development commands X70 and X80 grade seamless strings for deepwater production risers. ANVISA and national petroleum regulator standards govern subsea equipment qualification, favoring integrated mills with sour service certification. Rio de Janeiro and São Paulo industrial zones concentrate fabrication and coating capacity for offshore project integration.
Mexico
Vaca Muerta shale trunk lines and USMCA-qualified coil supply position northern border states as welded pipe export platforms. NOM pressure-rated product standards and CFE electrical infrastructure procurement rules shape qualification protocols. Monterrey and Altamira host integrated seamless and spiral-welded capacity serving both domestic energy and cross-border water transmission.
Canada
Alberta oil sands steam distribution networks and British Columbia LNG feedstock lines sustain demand for heavy-wall transmission products. Canadian Content Requirements and provincial procurement policies restrict federally funded infrastructure to domestic melt capacity. Calgary-Edmonton corridor concentrates engineering-procurement-construction firm headquarters, consolidating direct mill negotiation leverage.
Argentina
Vaca Muerta unconventional development and domestic gas pipeline rehabilitation sustain seamless pipe consumption despite currency volatility. National hydrocarbons regulator specifications and import substitution policies protect local mill positioning. Buenos Aires province integrated billet-to-pipe operations anchor the hemisphere's southernmost seamless supply source.
Americas Steel Pipes Market Vendor Landscape
On the supply side, the industry is consolidating around integrated producers with captive melt capacity and coating integration, compressing distributor intermediaries and reshaping pricing power toward qualified domestic mills. Three archetypes dominate: electric arc furnace-based coil converters, integrated seamless billet-to-pipe operators, and spiral-welded plate processors. Capacity expansion and direct mill procurement partnerships represent the dominant competitive vectors, displacing traditional stock-and-defer arrangements.
Among North American integrated producers, Nucor Corporation and United States Steel Corporation exemplify scale-driven coil supply archetypes, while Tenaris occupies a position representing seamless integration across hemispheric sourcing. These three anchors demonstrate how melt-source control and specification-tier qualification determine competitive positioning in federally funded procurement environments.
| Leading Market Players |
|---|
| Nucor Corporation |
| United States Steel Corporation |
| ArcelorMittal USA |
| Tenaris |
| American SpiralWeld Pipe |
| Welspun Tubular |
| JSW Steel USA |
| Valmont Tubing |
| Tubos de Acero de Mexico |
| Others |
Supply Flow & Price Mechanics
Monterrey's integrated seamless and spiral-welded capacity anchors pricing power for API-certified products across the Americas, with NOM-compliant mills commanding premiums on cross-border water transmission contracts.
Pricing Analysis
Certification level creates the primary spread between commodity welded and premium seamless tiers. Three-tier pricing structure across premium, standard, and economy levels reflects API 5L grade differentiation, with X80 heavy-wall seamless commanding substantial premiums over HFW line pipe. Pricing pressure stems from scrap-coil volatility above $400 per ton, squeezing electric arc furnace converters. Municipalities exhibit highest price sensitivity due to federal funding constraints, while integrated midstream operators accept premium positioning for long-term offtake security.
Supply Chain Analysis
Contract manufacturing concentrates around Nucor's electric arc furnace network, Tenaris's Argentine and Mexican seamless operations, and JSW Steel USA's plate conversion facilities. Raw material flows draw from US shredded scrap, Brazilian slab imports, and Canadian hot-rolled coil. Single-source vulnerability concentrates in seamless billet supply, with only two hemispheric integrated mills serving sour service demand. Distribution runs through direct mill procurement channels, compressing traditional distributor-wholesaler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating and inspection services represent the fastest-expanding recurring-revenue layer, outpacing base pipe hardware as asset life extension becomes a procurement priority.
For Market Incumbents: Insulate margin position by deepening backward integration into fusion-bonded epoxy application capacity and sour service certification assets. Acquire distressed spiral-welded plate processors in Texas and Alberta to consolidate direct mill negotiation leverage against EPC procurement concentration. Threat substitution from reinforced thermoplastic pipes in low-pressure CO2 service demands preemptive coating technology investment.
For New Entrants and Emerging Players: Carbon capture pipeline infrastructure in the US Gulf Coast and Alberta represents the most penetrable entry point, with qualification requirements still crystallizing and incumbent certification backlogs extending delivery timelines. Target coating subcontractor partnerships with established mills lacking in-house epoxy or three-layer polyethylene capacity. Go-to-market positioning should emphasize rapid API 1104 welder certification and digital traceability systems.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because domestic content mandates lock qualified melt capacity into federally funded procurement pools regardless of commodity cycle volatility. Target acquisition archetype: mid-scale spiral-welded processors with USMCA-qualified coil supply and existing CFE or state water authority relationships. Signal to monitor: ANP and CFE qualification timeline acceleration indicating demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adding X80 seamless heavy-wall capacity captures Santos Basin pre-salt premium demand. |
| Backward Integration | Captive electric arc furnace coil supply defends margin against scrap price volatility spikes. |
| Long-term Supply Agreement | Five-year offtake contracts with Permian midstream operators lock volume through cycle turns. |
| Joint Venture | Coating facility partnerships with Brazilian fabricators access ANVISA subsea qualification pathways. |
| Geographic Expansion | Monterrey-Austin corridor positioning captures displaced Asian import share under Buy America. |
Methodological Framework
Initial hypotheses were tested against primary input from pipeline procurement directors, EPC contract managers, mill sales executives, and API certification auditors and refined through secondary validation against FERC pipeline filings, USITC trade data, ANP project registries, and SEC 10-K disclosures from integrated producers. Bottom-up volume estimates from application-specific demand drivers were triangulated with top-down market sizing from trade flow analysis.
Demand-supply balance modeling across the analysis window incorporated pipe grade tier, end-use application, pressure rating specification, and regional regulatory cluster segmentation dimensions. CAGRs were derived from regression analysis of historical capacity utilization and project announcement pipelines, with specific inputs including Permian Basin rig counts and Vaca Muerta trunk line authorization timelines.
Macroeconomic conditions sit as an overlay; deviation in scrap pricing bands, federal infrastructure appropriation levels, or Brazilian real exchange rates would shift the trajectory. Quarterly review of API 1104 welder certification backlogs and CFE procurement calendar releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Qatar PVC Pipe Market