
 Flame-Retardant Foams and Insulation Market | 2026-2036
Flame-Retardant Foams and Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Flame-Retardant Foams and Insulation Market Analysis
The EU Green Deal is rebalancing demand toward low-emission, halogen-free insulation systems across European construction and transport sectors. BASF SE leverages its integrated polyurethanes portfolio to supply next-generation flame-retardant formulations. Owens Corning anchors North American demand through its mineral wool and foam glass specialization for commercial building envelopes. Saint-Gobain competes on multi-material breadth, spanning glass wool, stone wool, and innovative phenolic foam systems for high-performance facades.
Flame-retardant foams and insulation comprise engineered cellular materials formulated with phosphorus, nitrogen, or mineral-based additives to inhibit ignition, suppress smoke, and maintain thermal performance under fire exposure; manufacturers achieve these properties through controlled polymerization, expansion processes, and additive integration to meet strict reaction-to-fire classifications. Phenolic foam occupies the premium tier for aerospace and rail applications where low smoke toxicity commands specification priority. Polyurethane spray foam dominates retrofit construction volumes due to ease of application and high R-value per inch. Melamine foam extends into electronics and transportation soundproofing where open-cell structure and inherent flame resistance create defensible margin pools.
REACH restrictions on halogenated flame retardants and the EU F-Gas Regulation are reshaping material qualification pathways, forcing reformulation investments and supplier recertification cycles. The EPA and OSHA maintain parallel pressure in the United States through VOC emission limits and workplace exposure standards that filter permissible chemistries. FDA oversight of foam components in medical and food-contact applications adds a third compliance layer for multi-sector suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
REACH restrictions on halogenated flame retardants are forcing wholesale reformulation across polyurethane and polystyrene foam portfolios, compressing qualification timelines and elevating R&D burn rates for compounders serving construction and transport sectors.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for high-GWP blowing agents are accelerating adoption of hydrofluoroolefin and hydrocarbon alternatives in rigid foam systems across Germany, France, and the Netherlands.
- Retrofit construction:Deep energy renovation mandates in residential and commercial building stock are pulling spray polyurethane foam volumes for envelope sealing and continuous insulation layers.
- Phenolic foam chemistry:Low-smoke toxicity specifications in rail and aerospace interiors are concentrating specification authority around phenolic systems for wall and ceiling panel applications.
Market Restraints
- Phosphorus additive costs:Supply concentration for red phosphorus and phosphate esters in China creates input price volatility that squeezes margin on halogen-free formulations.
- Technical limitation:Intumescent coatings required for open-cell polyurethane in high-rise applications add labor cost and thickness penalties that specifiers in cost-sensitive markets resist.
- Regulatory friction:Divergent flammability testing protocols between ASTM E84 in the United States and EN 13501 in Europe force dual certification investments for multi-region suppliers.
Strategic Opportunities
- India infrastructure:Smart Cities Mission and PMAY-Urban housing targets are creating first-mover advantage for mineral wool and rigid PIR foam suppliers establishing local compounding capacity.
- Electric vehicle battery enclosures:Thermal runaway containment specifications are opening dedicated demand for aerogel and ceramic fiber-foam composites in pack insulation systems.
- Mass timber construction:Cross-laminated timber building codes in Canada and the Nordic countries are mandating cavity-fill fireblocking foams that integrate with wood structural systems.
Industry Challenges
- Fire testing engineer scarcity:Qualified personnel capable of conducting large-scale reaction-to-fire testing under EN 13823 and NFPA 285 protocols command premium compensation that extends certification timelines.
- Capex intensity:Continuous panel lamination lines for PIR and phenolic foam production require eight-figure investments that limit market entry for mid-scale compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame-Retardant Foams and Insulation Market |
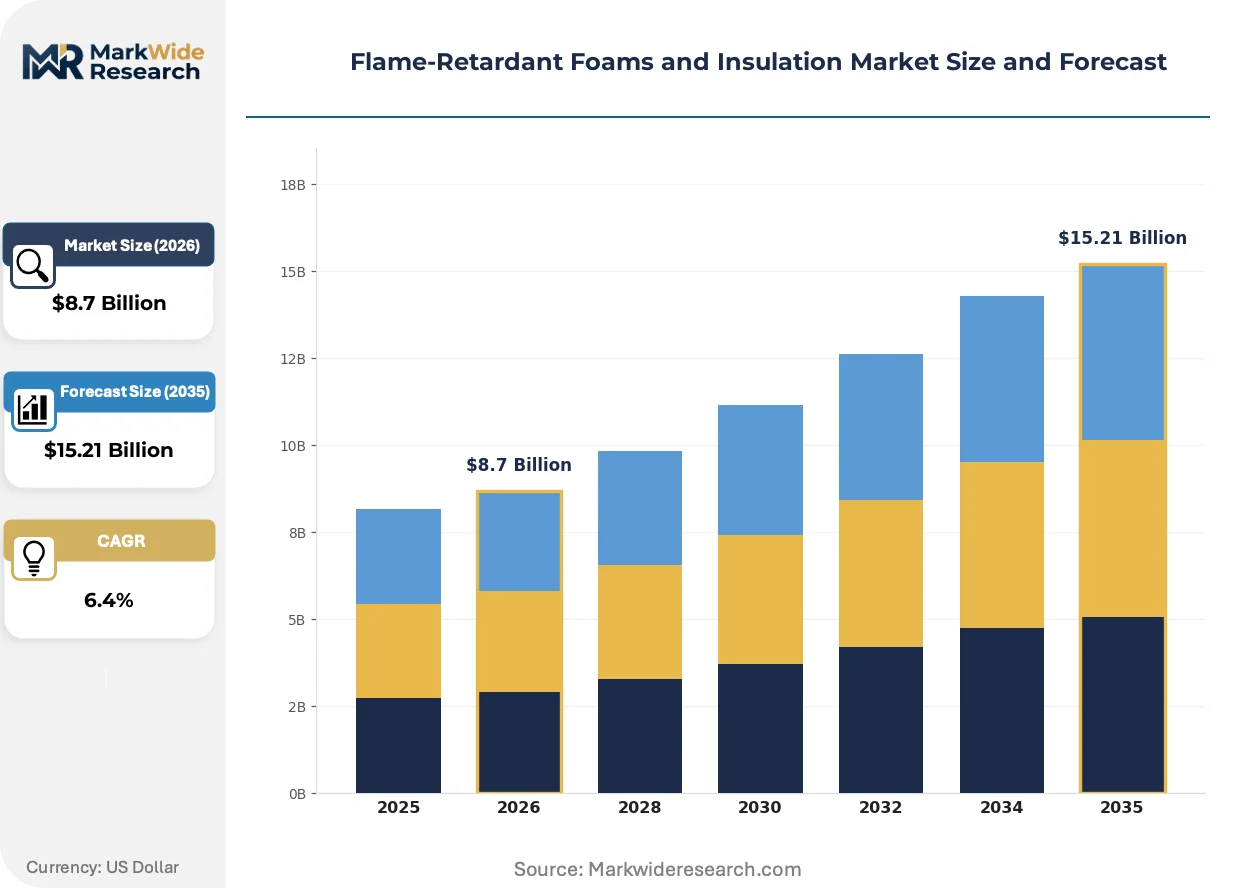
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polystyrene, Polyurethane, Phenolic, Melamine End Use Industry: Construction, Aerospace, Automotive, Electronics Form: Spray Foam, Rigid Foam, Flexible Foam, Board Application: Insulation, Soundproofing, Packaging, Fire Protection |
| Companies Covered | Owens Corning, Armacell International S.A., BASF SE, Kingspan Insulation, Rogers Corporation, Evonik Industries, Saint-Gobain, Johns Manville, Zotefoams plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame-Retardant Foams and Insulation Market Emerging Trajectories
Formulation chemistry and manufacturing process control are converging to deliver fire performance without the toxicity trade-offs that characterized legacy halogenated systems, compressing the gap between regulatory minimums and specifier preferences.
Bio-based polyols derived from soybean and castor oil feedstocks are expanding into spray foam and rigid board applications where they reduce petrochemical dependency while maintaining Class A surface burning characteristics. Regional insulation contractors in the United States Midwest are piloting these systems for agricultural and light commercial builds. The expansion into cost-competitive specification is pressuring conventional petroleum-based suppliers to demonstrate equivalent long-term thermal stability.
REACH authorization requirements for decabromodiphenyl ether and hexabromocyclododecane are eliminating legacy options from European supply chains, forcing compounders to validate phosphorus-nitrogen synergists and metal hydroxide loadings. Downstream fabricators of upholstered furniture and automotive seating are requalifying entire foam portfolios. Germany's automotive OEMs are most exposed, with interior trim suppliers facing 18-month recertification windows.
Specification authority is migrating from general contractors to fire engineering consultants who conduct performance-based design assessments using computational fluid dynamics modeling. This procurement pattern elevates suppliers with documented reaction-to-fire data packages and third-party certification depth. The shift is most visible in United Kingdom commercial high-rise and healthcare verticals where Building Safety Regulator oversight intensified post-Grenfell.
Flame-Retardant Foams and Insulation Market Segmentation
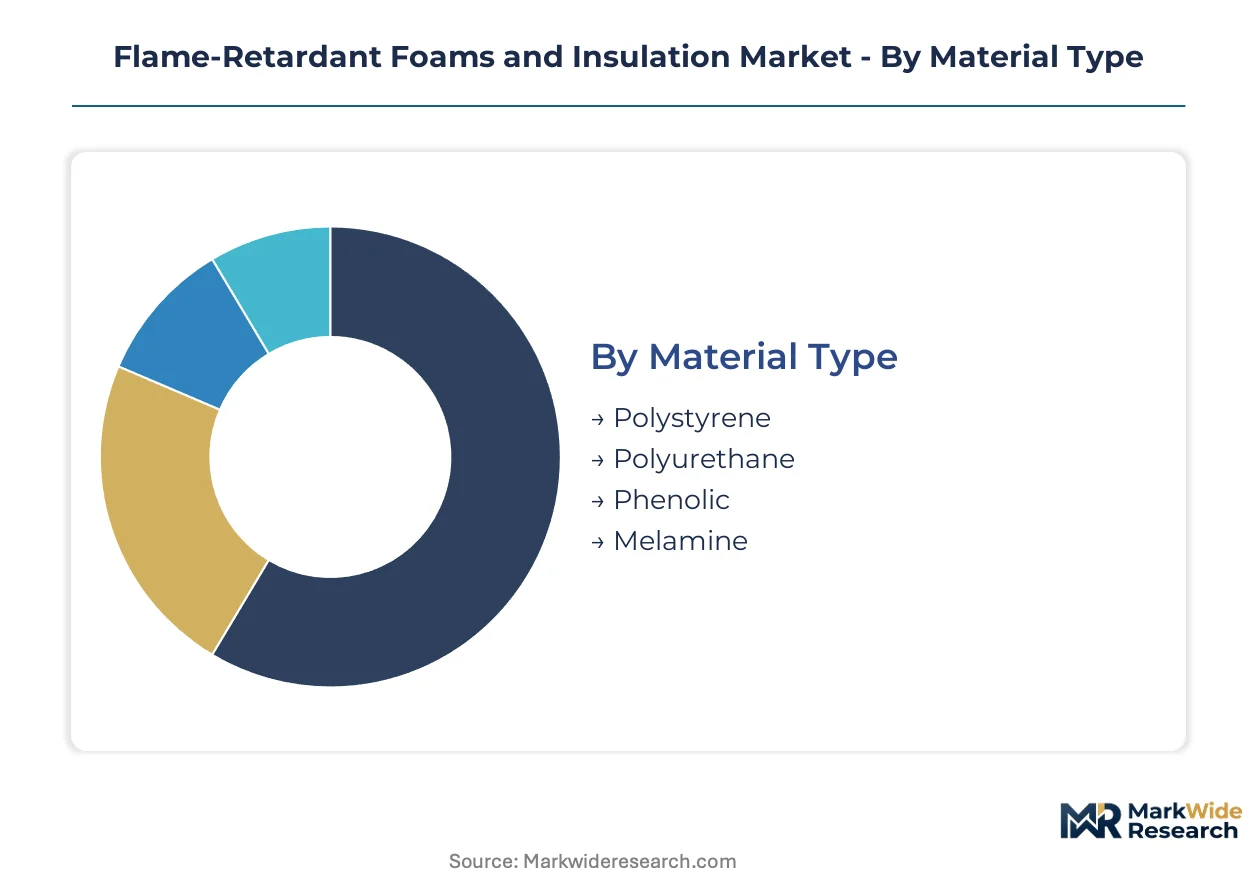
Segmentation in flame-retardant foams and insulation reveals how technical specifications diverge across fire performance tiers, blowing agent chemistry, and installation methods. Procurement patterns vary sharply between specification-driven aerospace contracts and price-sensitive construction retrofit volumes.
Material Type:
Supply concentration for phosphorus and nitrogen-based additives favors compounders with backward integration into flame retardant chemistry, particularly those serving REACH-regulated European markets.
- Polystyrene:Expanded and extruded variants dominate cost-sensitive commercial construction in Germany and the United States where continuous insulation board specifications prioritize thermal resistance per dollar. BASF SE and Dow anchor production capacity in the Rhine-Ruhr and Gulf Coast clusters, though F-Gas Regulation phase-downs are forcing reformulation of blowing agent packages.
- Polyurethane:Spray-applied and rigid board systems command premium specification in deep energy retrofits across France and the Netherlands, with hydrofluoroolefin transitions elevating raw material costs for mid-scale applicators. The segment's reliance on red phosphorus and phosphate ester supply from Chinese producers creates margin volatility that independent compounders struggle to hedge.
- Phenolic:Low-smoke toxicity characteristics meet rail and aerospace interior standards under EN 45545 and FAA regulations, with closed-cell structure delivering superior fire resistance in constrained cavity applications.
- Melamine:Open-cell acoustic absorption properties serve electronics and transportation soundproofing where inherent nitrogen-based flame resistance eliminates additive costs.
Today's leader: Polyurethane. Tomorrow's challenger: Phenolic.
End Use Industry:
Application-driven procurement separates specification authority between fire engineering consultants in high-rise construction and OEM material engineers in transport sectors.
- Construction:Building envelope and continuous insulation applications in Germany, China, and the United States absorb the majority of rigid foam volumes, with EU Green Deal renovation mandates accelerating specification upgrades toward halogen-free systems. Deep retrofit programs in the Netherlands and France are pulling spray polyurethane foam demand for air sealing and thermal bridge elimination.
- Aerospace:Phenolic foam and ceramic fiber composites dominate cabin interior applications where FAR 25.853 fireworthiness standards mandate low heat release and smoke density, with Boeing and Airbus Tier-1 suppliers consolidating qualification around three approved compounders.
- Automotive:Seat cushioning and interior trim applications face REACH-driven recertification timelines for decabromodiphenyl ether alternatives, with German OEMs most exposed to supply disruption.
- Electronics:Melamine foam and intumescent polyurethane systems serve server rack and battery enclosure applications where thermal management converges with ignition resistance.
Construction commands current volume. Electric vehicle thermal runaway containment is expanding most quickly.
Form:
Installation method determines labor cost allocation and contractor specialization, with spray foam requiring certified applicator networks that rigid board systems bypass.
- Spray Foam:Polyurethane and polyisocyanurate formulations dominate residential and light commercial retrofit in the United States Midwest, where agricultural building contractors pilot bio-based polyol systems for cost-competitive specification.
- Rigid Foam:PIR and phenolic boards serve rainscreen and cavity wall assemblies in the United Kingdom and Nordic countries, with continuous lamination line investments limiting supplier entry.
- Flexible Foam:Upholstered furniture and automotive seating applications face the steepest REACH recertification burdens, with phosphorus-nitrogen synergists displacing legacy halogenated loadings.
- Board:Mineral wool and foam glass specialization anchors Owens Corning's position in North American commercial envelopes, with multi-layer facings enabling weather resistance integration.
Spray foam leads retrofit volumes. Rigid foam is gaining share fastest in new commercial specification.
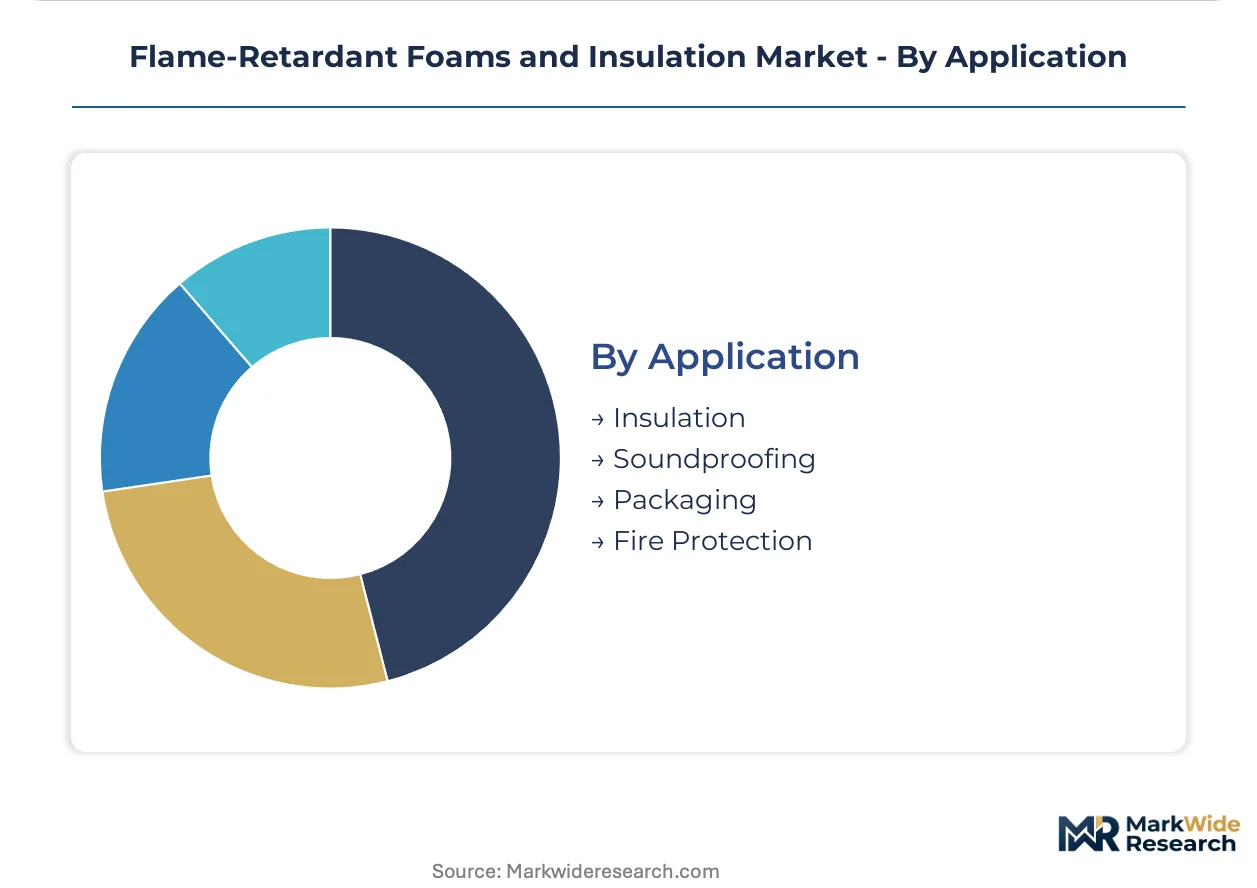
Application:
Functional performance requirements separate commodity thermal insulation from engineered fire protection systems with certified reaction-to-fire data packages.
- Insulation:Thermal performance under fire exposure drives specification across all material types, with R-value retention and intumescent char formation determining code compliance in Germany and California.
- Soundproofing:Open-cell melamine and acoustic polyurethane foams serve rail and automotive NVH applications where flame resistance is secondary to absorption coefficients.
- Packaging:Electronics and medical device cushioning requirements balance shock absorption with FDA oversight of foam components in food-contact and healthcare applications.
- Fire Protection:Intumescent coatings and cavity-fill fireblocking foams for mass timber construction in Canada and the Nordic countries command premium specification authority from fire engineering consultants.
Insulation dominates revenue. Fire protection for electric vehicle battery enclosures shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flame-retardant foams and insulation trace their industrial lineage to German chemical engineering clusters of the 1960s, where phenolic and polyurethane formulations first achieved commercial scale for aerospace and construction applications.
Germany
Deep energy renovation mandates under the EU Green Deal are pulling spray polyurethane foam volumes for envelope sealing across residential and commercial building stock. ECHA REACH restrictions on halogenated flame retardants force compounders serving construction and transport sectors into accelerated reformulation cycles. The Rhine-Ruhr industrial corridor anchors production capacity for expanded polystyrene and rigid PIR board systems.
United States
Retrofit construction in the Midwest and Southeast is concentrating demand for spray-applied polyurethane systems among agricultural and light commercial contractors. EPA VOC emission limits and OSHA workplace exposure standards filter permissible chemistries for domestic compounders. The Gulf Coast petrochemical cluster supplies blowing agent precursors and polyol feedstocks for regional foam manufacturers.
China
Large-scale infrastructure programs and commercial development in coastal provinces are driving specification upgrades for mineral wool and rigid foam insulation. The country's national chemical regulator enforces GB standards for fire performance testing that diverge from European EN protocols. Manufacturing concentration in the Yangtze River Delta supplies phosphorus-based flame retardant additives to domestic and export markets.
India
Smart Cities Mission and PMAY-Urban housing targets are creating first-mover advantage for mineral wool and rigid PIR foam suppliers establishing local compounding capacity. BIS certification requirements for construction materials are tightening reaction-to-fire standards in metropolitan building codes. Industrial corridors in Gujarat and Maharashtra are attracting joint ventures for continuous panel lamination lines.
France
Deep retrofit programs in the Île-de-France and Auvergne-Rhône-Alpes regions are accelerating adoption of hydrofluoroolefin-blown rigid foam systems. EU F-Gas Regulation phase-down schedules for high-GWP blowing agents are elevating raw material costs for mid-scale applicators. Lyon-based engineering consultancies are consolidating specification authority for commercial high-rise fire performance design.
Flame-Retardant Foams and Insulation Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and application technology. Continuous panel lamination lines for PIR and phenolic foam production require eight-figure investments that limit market entry, while specialty compounders leverage toll manufacturing relationships to serve niche specification tiers. Three archetypes dominate: integrated chemical majors with captive additive supply, regional insulation fabricators with certified applicator networks, and materials science specialists focused on aerospace and transport certification. Competitive moves concentrate on backward integration into flame retardant chemistry and strategic partnerships with fire engineering consultants for performance-based design authority.
Among integrated chemical majors, BASF SE and Evonik Industries exemplify the backward-integrated archetype with captive supply of phosphorus-nitrogen synergists and polyol systems. Owens Corning occupies a position representing the regional-fabricator model with specialized mineral wool and foam glass production for North American commercial envelopes. Saint-Gobain sits within the multi-material breadth tier, spanning glass wool, stone wool, and phenolic foam systems for high-performance facade specification across European markets.
| Leading Market Players |
|---|
| Owens Corning |
| Armacell International S.A. |
| BASF SE |
| Kingspan Insulation |
| Rogers Corporation |
| Evonik Industries |
| Saint-Gobain |
| Johns Manville |
| Zotefoams plc |
| Others |
Supply Flow & Price Mechanics
Red phosphorus and phosphate ester feedstock volatility originating in Chinese manufacturing clusters cascades through halogen-free formulation costs, compressing margins for European compounders while elevating premium-tier pricing authority for backward-integrated suppliers with captive additive production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified phenolic systems for rail interiors from commodity polystyrene boards in cost-sensitive construction. Price differentiation hinges on EN 13501 fire classification tier and volume scale, with bulk retrofit contracts commanding discounts unavailable to project-based specifiers. Cost compression in mid-tier polyurethane spray foam intensifies because Chinese phosphorus additive supply concentration feeds input volatility. Agricultural contractors in the United States Midwest exhibit highest price sensitivity, while aerospace Tier-1 suppliers accept premium positioning for FAR 25.853-certified low-smoke toxicity systems.
Supply Chain Analysis
Fire testing engineer scarcity in Germany and the United Kingdom constrains certification throughput for compounders seeking EN 13823 and NFPA 285 compliance, extending qualification timelines and elevating labor cost allocations. Manufacturing gravity centers on Germany's Rhine-Ruhr corridor, the United States Gulf Coast, and China's Yangtze River Delta, with each hub feeding distinct regional specification regimes. Raw material flows draw from concentrated phosphorus mining operations in China, petrochemical polyol production in Texas and Louisiana, and mineral wool fiber processing in Belgium and France. Single-source vulnerability in red phosphorus supply creates exposure to export restriction shocks. Distribution runs through certified applicator networks for spray foam and direct-to-contractor channels for rigid board systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in flame-retardant foams and insulation rests on reformulation cost-down curves for bio-based polyol systems and specification migration toward premium phenolic tiers in electric vehicle battery enclosures.
For Market Incumbents: Lock in specification authority by deepening backward integration into phosphorus-nitrogen flame retardant chemistry and securing multi-year supply agreements with German automotive OEMs facing REACH recertification deadlines. Capacity addition in Gujarat and Maharashtra industrial corridors captures first-mover positioning in India's Smart Cities infrastructure buildout. Certification investment in EN 45545 rail standards defends against mineral wool substitution in European mass timber construction. For New Entrants and Emerging Players: Regional insulation contractors serving United States agricultural retrofit represent an underserved buyer archetype with willingness to trial bio-based spray foam systems at price parity with petroleum-based alternatives. Electric vehicle battery enclosure thermal runaway containment offers the most penetrable application, with aerogel-foam composite demand outpacing qualified supplier capacity. Go-to-market execution through fire engineering consultancy partnerships secures performance-based design specification authority in United Kingdom commercial high-rise verticals. For Investors and Strategic Acquirers: Consolidation pressure builds where continuous panel lamination line capex requirements exceed mid-scale compounder balance sheet capacity, creating acquisition opportunities for mineral wool and rigid PIR specialists with proven EN 13501 certification depth. Long-term viability favors suppliers with demonstrated reformulation agility across F-Gas Regulation hydrofluoroolefin transitions and REACH halogenated flame retardant phase-outs. Watch phosphorus additive price volatility as inflection indicator for margin compression timing in halogen-free formulation tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame Retardant Chemistry | Captive phosphorus-nitrogen synergist production insulates BASF and Evonik from Chinese supply volatility. |
| Long-term Supply Agreement with Automotive OEMs | Multi-year contracts with German interior trim suppliers secure volume through REACH recertification cycles. |
| Capacity Expansion in India Industrial Corridors | Joint venture lamination lines in Gujarat address Smart Cities Mission demand with localized BIS certification. |
| Green Manufacturing Transition to Bio-based Polyols | Soybean and castor oil feedstock systems reduce petrochemical dependency while maintaining Class A surface burning ratings. |
| Joint Venture with Fire Engineering Consultancies | Partnerships with Lyon-based and United Kingdom performance-based design firms secure specification authority in commercial high-rise. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and France, with primary inputs from each market gathered through structured interviews with plant managers at foam manufacturing facilities, procurement leads at construction and automotive OEMs, distribution channel partners serving regional contractor networks, and technical R&D directors overseeing reformulation programs. Secondary validation draws from ECHA REACH substance dossiers, EPA VOC emission guidance documents, SEC 10-K filings from listed insulation manufacturers, and BIS construction material certification records. Bottom-up volume estimates triangulate against top-down market sizing derived from trade flow analysis and end-use consumption patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation modeling by material type, end-use industry, installation form, and application function. CAGRs derive from fitted growth curves calibrated to regulatory milestone timing and infrastructure program deployment schedules. Industry-specific forecast inputs include EU F-Gas Regulation phase-down compliance cost trajectories and electric vehicle battery enclosure thermal runaway specification adoption curves.
Underlying measurement precision varies by segment; construction retrofit volumes carry tighter precision than emerging electric vehicle battery enclosure applications where specification standards remain fluid. Forecasts reflect assumptions around REACH authorization timelines, F-Gas Regulation enforcement consistency, and infrastructure program funding continuity. Material deviation in phosphorus additive export restrictions or mass timber building code adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market