
 Dielectric Materials Market | 2026-2036
Dielectric Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Dielectric Materials Market Analysis
Modular substrate packaging is recalibrating how buyers specify dielectric materials for multilayer circuit boards. Rogers Corporation leverages its ceramic-polymer composite expertise to dominate high-frequency laminate supply for 5G base stations. Shin-Etsu Chemical Co., Ltd. anchors Asian silicon-based dielectric production through captive polysilicon refining and wafer-grade material control. Dow Inc. competes in fluoropolymer dielectric films for microelectronics, extending its position through backward integration into specialty monomer production.
Dielectric materials are electrically insulating substances that polarize under an applied electric field, with critical parameters including dielectric constant, loss tangent, and breakdown voltage measured in kilovolts per millimeter. These materials function primarily to store electrical energy, isolate conductive elements, and enable controlled signal propagation across capacitors, printed circuit boards, and power transmission systems. Ceramic formulations occupy the premium tier in high-temperature and high-voltage applications where thermal stability above 500°C is mandatory, while polymer films lead in flexible electronics and miniaturized consumer devices where processability and low cost dominate selection criteria. Composite dielectrics represent the fastest-growing category as hybrid architectures combining ceramic fillers with polymer matrices address the performance gap between single-material solutions.
The US FCC maintains emission standards that dictate dielectric performance thresholds for telecommunications hardware, while REACH and RoHS in Europe restrict hazardous substances in electronic components, directly influencing material substitution patterns among suppliers. China's SAMR enforces GB standards on dielectric strength and thermal cycling reliability for domestically manufactured capacitors and insulators, creating compliance barriers for non-certified imports. Stakeholders must monitor how evolving PFAS restrictions in multiple jurisdictions reshape fluoropolymer dielectric supply chains and accelerate investment in bio-based and silicone alternatives.
Market Dynamics
Modular substrate packaging architectures are forcing dielectric material suppliers to reconfigure product portfolios around layer-specific performance specifications rather than commodity-grade bulk supply.
Growth Catalysts
- 5G Base Station Deployment:Massive MIMO antenna arrays require ultra-low loss dielectric laminates. China's MIIT spectrum allocations and tower construction mandates accelerate substrate qualification cycles.
- REACH PFAS Restrictions:The European Chemicals Agency is phasing out fluorinated dielectric precursors. This regulatory pressure accelerates silicone and bio-based polymer R&D investment across capacitor manufacturers.
- Semiconductor Packaging Clustering:Advanced packaging facilities concentrate around Seoul and Pyeongtaek in South Korea. Proximity demand pulls high-purity ceramic substrate supply into dedicated regional distribution channels.
Market Restraints
- Polysilicon Supply Concentration:Wafer-grade silicon feedstock for dielectric production concentrates among Asian refiners. Price volatility in this input directly compresses margin structures for silicon-based dielectric producers.
- GB Standard Compliance Barriers:China's SAMR enforces thermal cycling reliability certification for imported capacitor films. Non-certified suppliers face extended qualification timelines and exclusion from state-backed infrastructure projects.
- Ceramic Filler Substitution Pressure:Barium titanate and other high-k ceramic fillers face cost and weight disadvantages against engineered polymer alternatives in consumer electronics.
Strategic Opportunities
- India Electronics Manufacturing:The country's PLI scheme for semiconductor and component production creates first-mover positioning for dielectric suppliers establishing local compounding or toll-processing operations.
- AI Accelerator Thermal Management:High-power chiplet architectures demand dielectric materials with thermal conductivity above 10 W/mK. This emerging application segment rewards ceramic-polymer composite specialists.
- Dual Carbon Policy Alignment:China's carbon intensity targets favor domestic suppliers with verified low-emission production processes. Foreign competitors can capture share through joint ventures with certified local partners.
Industry Challenges
- Multilayer Co-Processing Expertise Gap:Advanced packaging requires dielectric engineers who understand both thin-film deposition and polymer lamination. Talent scarcity in this hybrid skill set extends product development timelines.
- Cross-Border Certification Lag:Dielectric materials qualified under US FCC emission standards require separate GB standard testing for China market entry. Parallel track testing doubles pre-revenue investment.
- Legacy Equipment Retrofit Complexity:Established laminate producers face capital-intensive upgrades to handle ceramic-filled resin systems on existing coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dielectric Materials Market |
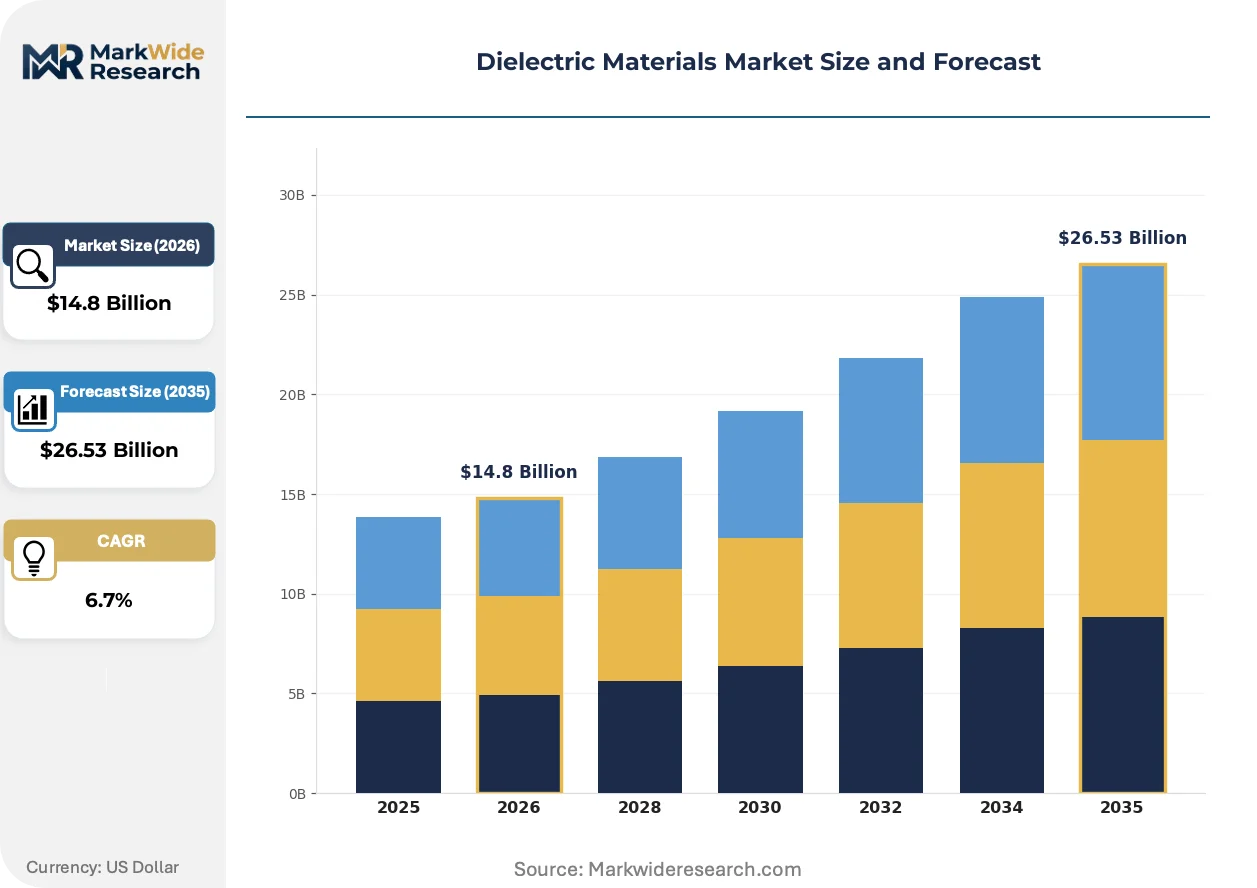
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Polymer, Composite, Glass Application: Electronics, Telecommunications, Power Systems, Automotive Form: Films, Sheets, Rods, Coatings End User: Manufacturers, R&D Institutions, Electronics Firms, Energy Sector |
| Companies Covered | Rogers Corporation, Honeywell International Inc., 3M Company, Solvay S.A., Shin-Etsu Chemical Co., Ltd., Dow Inc., Linde PLC, BASF SE, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dielectric Materials Market Emerging Trajectories
Dielectric material innovation is pivoting from incremental property improvement toward architectural redesign of composite microstructures that reconcile conflicting performance requirements.
Ceramic-polymer composite dielectrics are consolidating position as the dominant solution class for high-frequency, high-temperature applications. 5G infrastructure OEMs and automotive radar suppliers have accelerated adoption beyond initial qualification phases. This technology is consolidating supplier tiers by rewarding compounders with captive ceramic filler synthesis and precision dispersion capabilities.
The European F-Gas Regulation is tightening supply constraints on fluoropolymer dielectric precursors used in high-voltage capacitors and wire insulation. Manufacturers are reformulating around silicone and hydrocarbon-based alternatives with comparable thermal stability. Microelectronics packaging operations in Germany and France face the steepest substitution curves due to proximity enforcement and customer sustainability mandates.
Buyer specification practices are fragmenting as modular substrate architectures enable layer-by-layer material selection. Tier-one PCB fabricators now source dielectrics through direct technical partnerships rather than distributor intermediaries. This pattern concentrates procurement leverage among South Korean and Taiwanese packaging houses with sufficient volume to justify dedicated supply agreements.
Dielectric Materials Market Segmentation
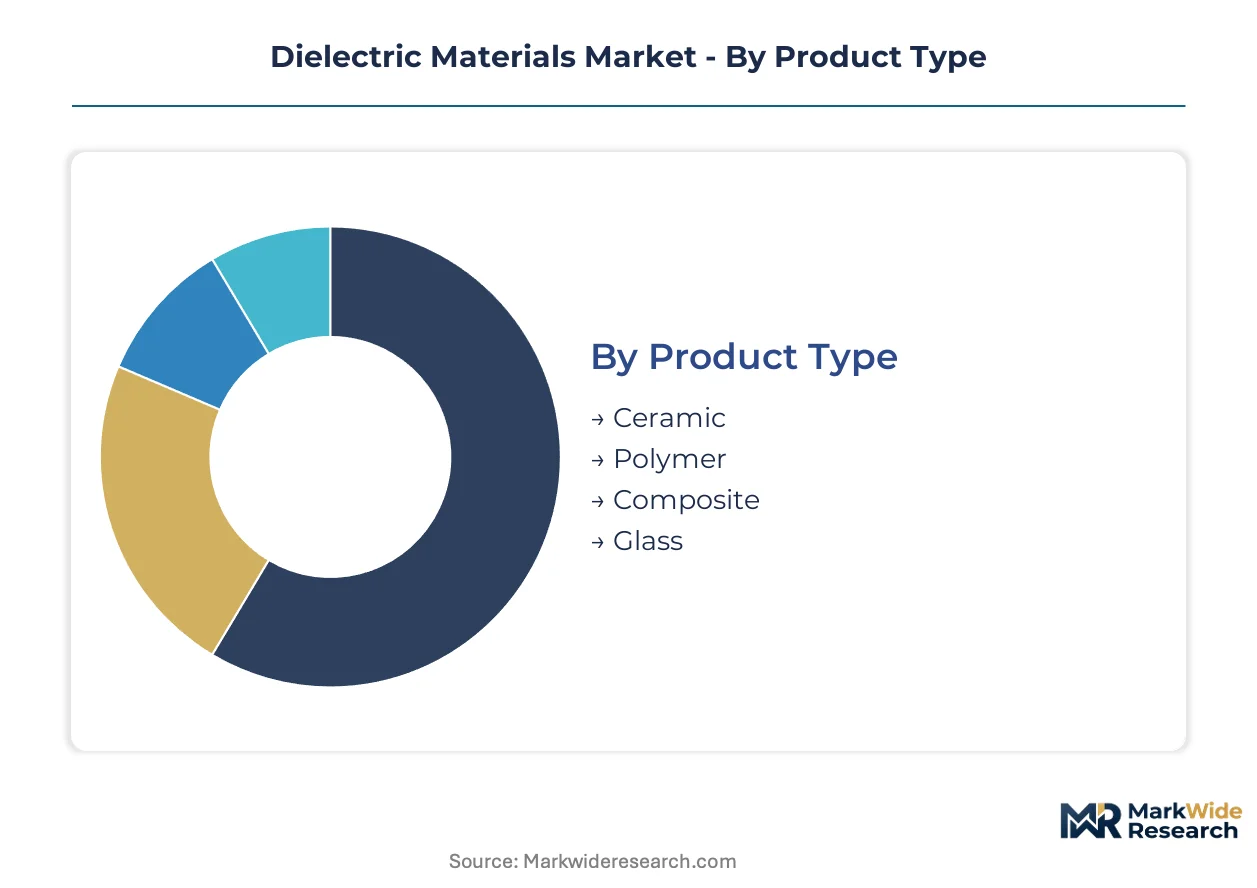
Dielectric material suppliers must align product architectures with distinct performance thresholds across substrate types, application environments, and processing formats. Segmentation reveals where technical specifications diverge sharply and where hybrid solutions bridge capability gaps.
Product Type:
Supply concentration in ceramic precursor synthesis and polymer resin production shapes competitive positioning across material categories.
- Ceramic:Oxide and nitride formulations deliver thermal stability above 500°C with dielectric constants ranging from 9 to 100+. Demand clusters in South Korea's semiconductor packaging corridor around Seoul and Pyeongtaek, driven by high-frequency substrate requirements for AI accelerators.
- Polymer:Polyimide, PTFE, and liquid crystal polymer films dominate flexible electronics and miniaturized consumer devices. China's MIIT spectrum allocations for 5G infrastructure pull ultra-low loss laminate demand toward domestic compounders with GB standard certification.
- Composite:Hybrid architectures combine ceramic fillers with polymer matrices to reconcile thermal conductivity and processability.
- Glass:Borosilicate and alkali-free variants serve specialized high-voltage insulator and display substrate applications.
Ceramic absorbs the bulk of installed capacity; composite is expanding most quickly.
Application:
End-use diversification creates divergent specification regimes that fragment supplier-customer relationships.
- Electronics:Capacitors, PCBs, and semiconductor packages require precisely tuned dielectric constants and loss tangents. REACH PFAS restrictions in Europe are accelerating silicone-based reformulation among microelectronics manufacturers in Germany and France.
- Telecommunications:5G massive MIMO antenna arrays and base station infrastructure demand ultra-low loss substrates. China's tower construction mandates compress qualification cycles for imported laminates.
- Power Systems:High-voltage transmission and grid infrastructure prioritize breakdown voltage above 300 kV/mm.
- Automotive:EV power electronics and radar modules specify materials with combined thermal cycling reliability and high-frequency performance.
Electronics commands the largest revenue share; telecommunications shows the steepest expansion trajectory.
Form:
Processing format determines capital equipment requirements and margin structures across the value chain.
- Films:Thin-film dielectrics below 25 micrometers enable multilayer PCB miniaturization and flexible circuit architectures. South Korean packaging houses in Pyeongtaek specify rolled annealed copper-compatible films for advanced substrate lamination.
- Sheets:Rigid laminate formats support high-layer-count boards and thermal management substrates. China's state-backed infrastructure projects require GB standard-certified sheet supply from domestic or joint-venture producers.
- Rods:Cylindrical geometries serve high-voltage insulator and connector applications.
- Coatings:Conformal and potting formulations protect sensitive electronics from moisture and thermal stress.
Sheets absorb the bulk of installed capacity; films are gaining share fastest.
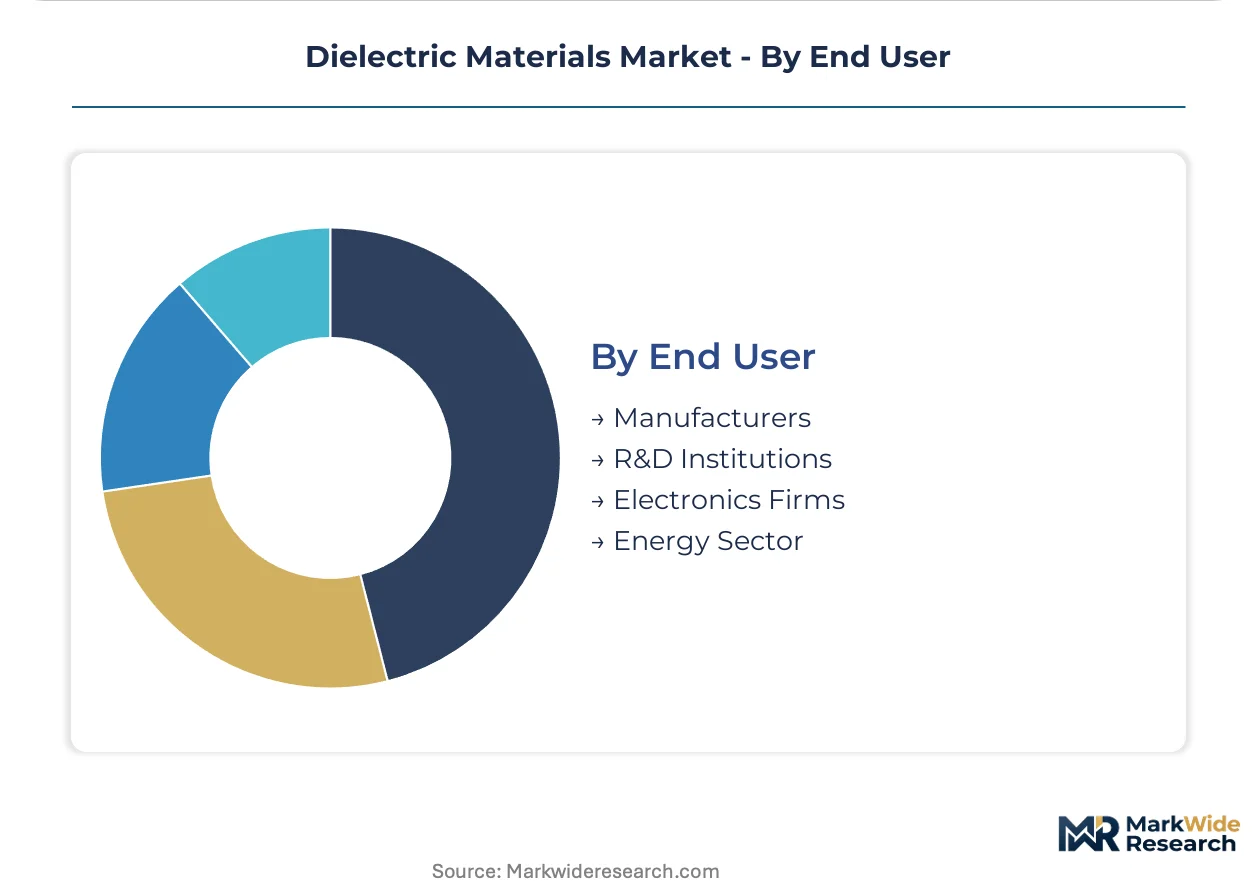
End User:
Customer type dictates technical service intensity and procurement contract structures.
- Manufacturers:Tier-one PCB fabricators and substrate producers source dielectrics through direct technical partnerships rather than distributor channels. Procurement leverage concentrates among South Korean and Taiwanese packaging houses with dedicated volume agreements.
- R&D Institutions:National laboratories and university research centers pilot next-generation composite formulations and deposition techniques.
- Electronics Firms:OEMs in consumer devices and telecommunications specify dielectric performance thresholds for outsourced manufacturing.
- Energy Sector:Utilities and grid operators procure high-voltage insulators with decades-long reliability warranties.
Manufacturers absorb the bulk of installed capacity; R&D institutions are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific nations manufacture the bulk of dielectric substrates while North American and European markets consume advanced formulations for high-frequency applications. Production capacity clusters around East Asian chemical processing corridors. Regulatory divergence across major economies is fragmenting qualification requirements for cross-border suppliers.
China
MIIT spectrum allocations for 5G infrastructure pull ultra-low loss laminate demand toward domestic compounders. SAMR enforces GB standards on thermal cycling reliability that extend qualification timelines for imported capacitor films. The Yangtze River Delta anchors high-purity ceramic substrate production for semiconductor packaging.
United States
FCC emission standards dictate dielectric performance thresholds for telecommunications hardware manufacturers. The EPA monitors PFAS usage in fluoropolymer dielectric precursors under evolving chemical safety frameworks. Texas and Arizona host expanding advanced packaging facilities that source ceramic-polymer composites through dedicated technical partnerships.
South Korea
Seoul and Pyeongtaek concentrate semiconductor packaging demand that pulls high-purity ceramic substrate supply into regional distribution channels. MFDS-aligned material purity protocols govern dielectric film imports for medical electronics applications. The government-backed K-Semiconductor Belt initiative accelerates substrate qualification cycles for domestic suppliers.
Germany
ECHA REACH restrictions on fluorinated dielectric precursors accelerate silicone-based reformulation among microelectronics manufacturers. The F-Gas Regulation tightens supply constraints on high-voltage capacitor materials. Bavaria and Baden-Württemberg host automotive radar module producers specifying ceramic-polymer composites for thermal cycling reliability.
Japan
METI industrial policy supports domestic dielectric material production for advanced packaging applications. JIS standards on electronic material purity create compliance benchmarks for imported films. The Kanto region around Tokyo maintains concentrated demand from tier-one PCB fabricators sourcing through direct technical partnerships.
Dielectric Materials Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across ceramic, polymer, and composite dielectric categories. The vendor base organizes around three strategic archetypes: chemical conglomerates with backward integration into specialty monomers, ceramic compounders with captive filler synthesis, and laminate specialists with precision dispersion capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for modular substrate packaging growth.
Among diversified chemical conglomerates, Dow Inc. and BASF SE exemplify scale-driven players with upstream control over resin and monomer supply. Shin-Etsu Chemical Co., Ltd. anchors the specialist tier through its position in silicon-based dielectric production. Rogers Corporation occupies a distinctive niche representing ceramic-polymer composite expertise for high-frequency applications.
| Leading Market Players |
|---|
| Rogers Corporation |
| Honeywell International Inc. |
| 3M Company |
| Solvay S.A. |
| Shin-Etsu Chemical Co., Ltd. |
| Dow Inc. |
| Linde PLC |
| BASF SE |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive polysilicon refining in Asia anchors both supply security and pricing power for silicon-based dielectric producers, while ceramic-polymer composite specialists leverage in-house filler synthesis to defend margin structures against commodity resin volatility. This integration pattern separates premium-tier suppliers from toll-compounders exposed to raw material pass-through.
Pricing Analysis
Margin tightening in standard-grade polymer films reflects polysilicon feedstock volatility and REACH-driven reformulation costs. Contract-based long-term offtake dominates ceramic substrate procurement, with price differentiation resting on GB standard certification and volume scale. Tier-one PCB fabricators show lowest price sensitivity due to dedicated technical partnerships, while emerging Indian compounders face acute cost-down pressure.
Supply Chain Analysis
Single-source vulnerability sits with wafer-grade polysilicon refiners concentrated in China, Japan, and South Korea. Barium titanate ceramic fillers and fluoropolymer precursors draw from geographically concentrated precursor plants. Tariff exposure on imported capacitor films into China creates qualification bottlenecks. Distribution runs through direct technical partnerships rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dielectric material competition is becoming a vertical-integration race, with upstream control over ceramic filler synthesis and specialty monomer production determining who captures modular substrate packaging growth.
For Market Incumbents: Anticipate silicone-based substitute displacement by accelerating captive ceramic filler capacity in South Korea's packaging corridor. Defend position through backward integration into high-purity oxide precursor production and pre-emptive GB standard certification for China's state-backed infrastructure pipeline.
For New Entrants and Emerging Players: Mid-tier Indian electronics manufacturers represent the most penetrable buyer archetype, underserved by technical service intensity from established suppliers. Target toll-compounding partnerships with PLI scheme beneficiaries and lead with rapid qualification support for multilayer co-processing.
For Investors and Strategic Acquirers: Exit pathways concentrate in ceramic-polymer composite specialists with precision dispersion capabilities and captive filler synthesis. Long-term viability hinges on positioning for AI accelerator thermal management demand. Watch PFAS regulatory acceleration in Europe as inflection signal for fluoropolymer-dependent assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Filler Synthesis | Captive barium titanate production insulates Rogers Corporation and Shin-Etsu from precursor volatility. |
| GB Standard Certification Investment | SAMR thermal cycling compliance unlocks China's state-backed 5G infrastructure procurement. |
| Silicone-Based Reformulation Program | ECHA REACH restrictions on fluorinated precursors reward early movers in hydrocarbon alternatives. |
| Joint Venture with Indian PLI Beneficiaries | Local compounding operations capture Electronics Manufacturing incentive flows and bypass import duties. |
| AI Accelerator Thermal Management Partnership | Ceramic-polymer composites above 10 W/mK thermal conductivity address high-power chiplet architectures. |
Methodological Framework
SEC 10-K filings, customs trade data, and ECHA regulatory submissions formed the secondary backbone, cross-referenced with primary interviews involving dielectric material R&D directors, PCB fabricator procurement leads, and semiconductor packaging engineers. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates across ceramic, polymer, and composite categories.
Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation by material type, application environment, processing format, and end-user category. CAGRs were derived from supply-side capacity buildouts and demand-pull indicators including MIIT spectrum allocations and K-Semiconductor Belt investments.
Revisions become necessary when PFAS regulatory timelines accelerate, polysilicon supply disruptions materialize, or GB standard certification requirements shift. Forecasts reflect documented assumptions about modular substrate adoption rates and dual carbon policy enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Insulation Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Flexible Insulation Market