
 Industrial Pipe Insulation Market | 2026-2036
Industrial Pipe Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Pipe Insulation Market Outlook
ASTM C547 and EN 14303 specification upgrades are bifurcating the competitive landscape into premium-certified and commodity-grade supply tiers. Saint-Gobain leverages its dual-certification footprint across North American and European test houses to command specification-driven contracts. Owens Corning anchors its position through backward integration into borosilicate glass fiber production, capturing margin pools that commodity importers cannot access.
Industrial pipe insulation comprises thermally resistant materials engineered to reduce heat transfer in process piping, typically achieving thermal conductivity values below 0.040 W/m·K depending on material density and binder chemistry. Its primary commercial purpose centers on limiting energy dissipation in steam distribution networks and maintaining process fluid temperatures within operational tolerances. Mineral wool dominates mature replacement cycles in power generation, where operators prioritize fire resistance ratings over thermal efficiency gains. Foam products capture expanding share in oil and gas applications, particularly in subsea tiebacks where hydrostatic pressure resistance and low water absorption specifications command price premiums over fiberglass alternatives.
OSHA's updated permissible exposure limits for respirable crystalline silica are reshaping installation protocols and driving specification shifts toward pre-formed, low-dust mineral wool products in US manufacturing facilities. The EU F-Gas Regulation and REACH restrictions on formaldehyde-based binders are simultaneously tightening material compliance requirements across European supply chains. Stakeholders must monitor how dual regulatory pressures on blowing agents and binder chemistry converge to redefine cost structures and supplier qualification criteria.
Market Dynamics
Dual regulatory pressures on blowing agents and binder chemistry are compressing supplier margins while bifurcating procurement into certified-premium and commodity-grade tiers.
Growth Catalysts
- EU F-Gas Regulation:Mandates on lower-GWP blowing agents are forcing foam manufacturers to reformulate products, opening specification windows for compliant suppliers in chemical processing applications.
- Refinery upgrade cycles:Germany's industrial corridor is accelerating replacement demand as energy-intensive operators retrofit steam distribution networks to cut thermal losses.
- OSHA silica limits:Tighter permissible exposure thresholds for respirable crystalline silica are driving specification shifts toward pre-formed, low-dust mineral wool in US manufacturing facilities.
Market Restraints
- Input cost volatility:Borosilicate glass fiber feedstock prices fluctuate with energy costs, squeezing margins for non-integrated producers who lack captive supply.
- REACH formaldehyde restrictions:Binder chemistry compliance timelines are extending qualification cycles for European suppliers, delaying contract awards.
- Subsea specification barriers:Hydrostatic pressure resistance requirements in oil and gas tiebacks limit foam product penetration to certified grades with premium pricing.
Strategic Opportunities
- India's chemical cluster expansion:Petrochemical capacity additions along the Gujarat coast are creating greenfield specification opportunities for fire-resistant mineral wool systems.
- Carbon border adjustment mechanisms:EU CBAM implementation is rewarding low-embodied-carbon insulation materials with preferential procurement scoring in cross-border tenders.
- Predictive maintenance integration:IoT sensor convergence with thermal monitoring is enabling condition-based insulation replacement contracts in power generation fleets.
Industry Challenges
- Dual-certification complexity:ASTM C547 and EN 14303 parallel compliance requires redundant testing protocols, stretching R&D budgets for mid-tier suppliers.
- Installation labor scarcity:Specialized applicator training for low-dust mineral wool systems is lagging demand growth in US Gulf Coast industrial corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Pipe Insulation Market |
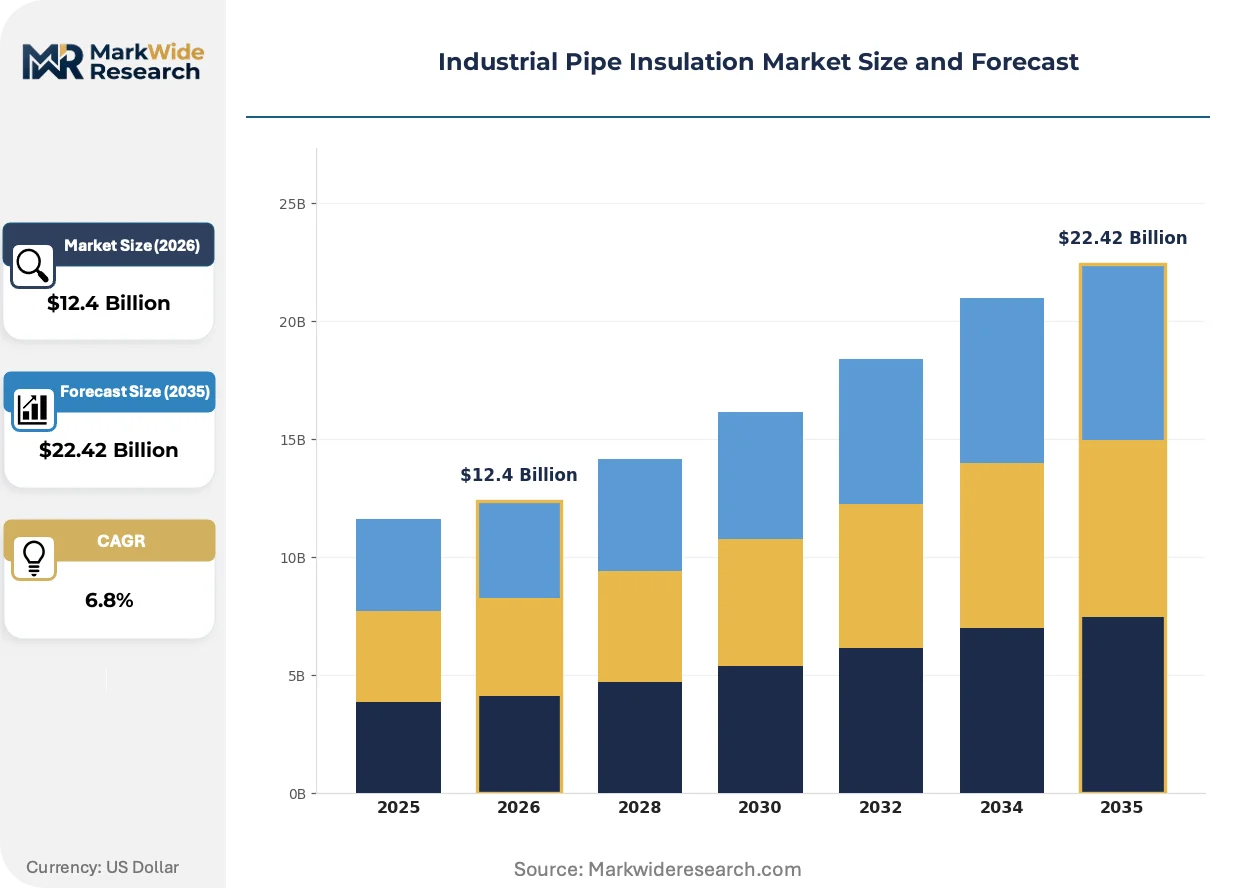
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam, Mineral Wool, Polyethylene Installation Type: Pre-Insulated, Field-Applied, Removable, Rigid End User: Manufacturing, Oil & Gas, Power Generation, Chemical Processing Thickness: 1 inch, 2 inch, 3 inch, 4 inch |
| Companies Covered | Saint-Gobain, Owens Corning, Johns Manville, Rockwool International, BASF SE, Kingspan Group, Armacell, Knauf Insulation, Huntsman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Pipe Insulation Market Strategic Shifts
Aerogel composite formulations and bio-based binder chemistries are disrupting established material hierarchies while digital specification tools compress buyer decision cycles.
Multilayer aerogel blankets achieving thermal conductivity below 0.020 W/m·K are decomposing the traditional mineral wool-foam duopoly in high-temperature steam applications. LNG liquefaction terminals in Qatar and Australia are specifying these systems for cryogenic pipe runs where space constraints outweigh first-cost premiums. The technology is decomposing incumbent margin structures by collapsing the performance gap between premium and standard insulation tiers.
REACH restrictions on formaldehyde-based binders are forcing European manufacturers toward phenolic and bio-alternatives with extended cure cycles. Owens Corning and Saint-Gobain have requalified product lines through ECHA-notified bodies, locking in specification advantages for two to three certification cycles. Mineral wool segments in power generation and marine applications face the steepest compliance ramps.
Engineering-procurement-construction firms are unbundling insulation specification from general contracting, creating direct relationships with material suppliers. This disintermediation concentrates buying power with EPC technical offices in Houston, Rotterdam, and Singapore. After-sales thermal performance guarantees are replacing commodity purchase orders in refinery and chemical plant contracts.
Industrial Pipe Insulation Market Segmentation
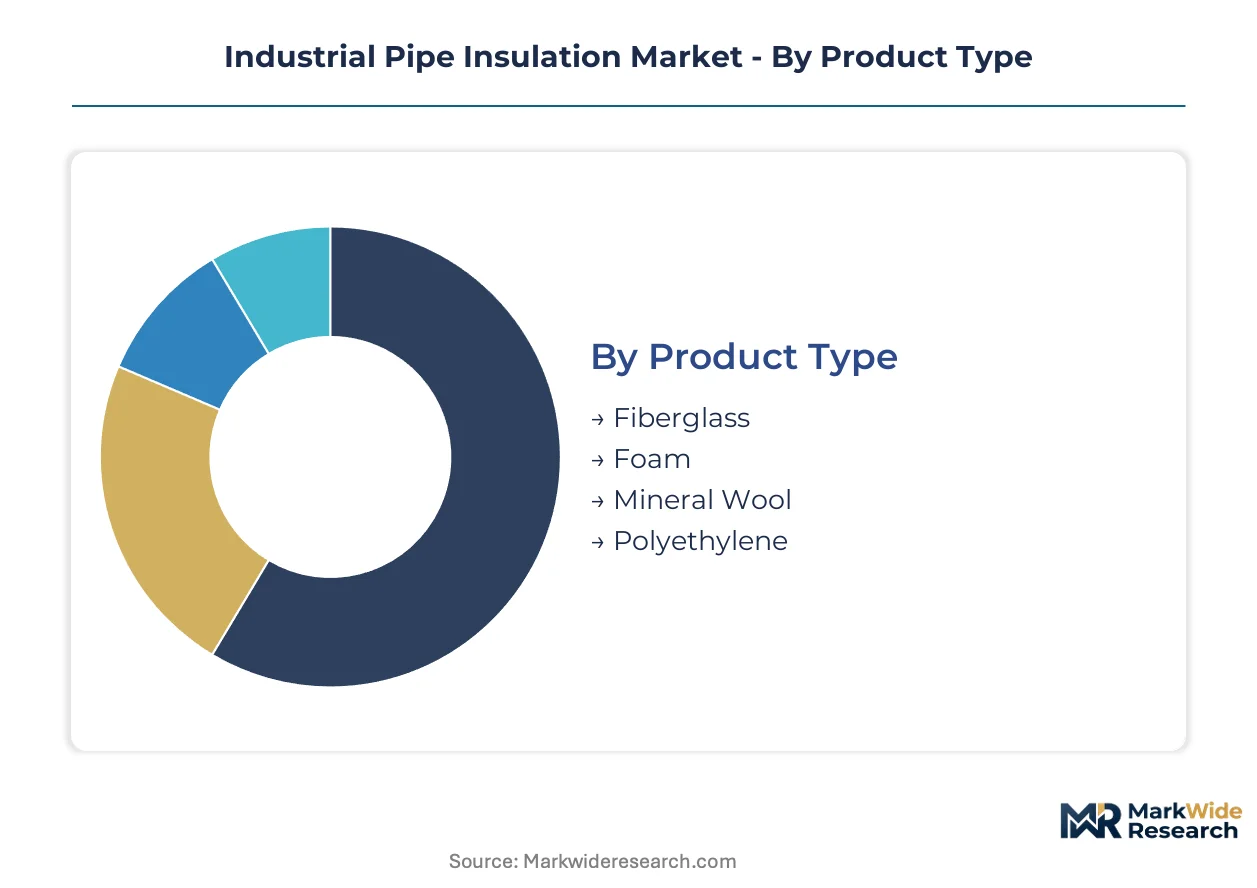
Material chemistry and installation method determine thermal performance thresholds, fire resistance ratings, and labor cost structures across industrial pipe insulation procurement. Specification engineers weight these trade-offs differently across steam distribution, cryogenic service, and high-temperature process applications.
Product Type:
Margin pools concentrate in formulations achieving dual ASTM C547 and EN 14303 certification, where specification-driven premiums offset reformulation costs for compliant blowing agents and binder systems.
- Fiberglass:Borosilicate glass fiber matrices with thermal conductivity ranging 0.030-0.040 W/m·K dominate replacement cycles in US power generation fleets where OSHA silica exposure limits favor pre-formed, low-dust configurations. Owens Corning's backward integration into captive borosilicate feedstock locks in margin pools unavailable to commodity importers facing energy-linked input volatility.
- Foam:Rigid polyurethane and polyisocyanurate systems achieve sub-0.025 W/m·K conductivity values through hydrocarbon or HFO blowing agents, capturing specification premiums in subsea oil and gas tiebacks where hydrostatic pressure resistance and low water absorption command price multiples over fiberglass alternatives. EU F-Gas Regulation mandates on lower-GWP formulations are compressing supplier margins while opening procurement windows for compliant grades in German chemical processing clusters.
- Mineral Wool:Stone or slag wool binders deliver fire resistance ratings exceeding 1000°C, anchoring demand in power generation boiler circuits and marine engine rooms where regulatory compliance overrides thermal efficiency optimization.
- Polyethylene:Closed-cell foam structures serve low-temperature HVAC and plumbing applications with limited penetration into industrial process specifications due to temperature ceiling constraints.
The dominant share belongs to fiberglass, while foam is closing the gap fastest on the strength of subsea specification premiums and chemical plant energy-loss reduction mandates.
Installation Type:
Procurement patterns diverge between capital projects favoring factory-controlled quality and turnaround schedules demanding field flexibility.
- Pre-Insulated:Factory-applied systems with integral vapor barriers and protective jackets eliminate field cutting and sealing variables, concentrating demand in LNG liquefaction terminals and cryogenic pipe runs where installation defect risks carry catastrophic thermal loss consequences. Qatar and Australian projects specify these systems for space-constrained layouts where first-cost premiums amortize through reduced labor hours and guaranteed performance envelopes.
- Field-Applied:On-site layering of insulation segments and weatherproofing enables geometric adaptation to complex piping geometries, retaining share in refinery revamp projects where existing infrastructure constraints preclude modular replacement.
- Removable:Quilted blankets with fastening systems support valve and flange maintenance access, penetrating maintenance-contractor procurement in US Gulf Coast petrochemical corridors where turnaround frequency drives reusable asset preferences.
- Rigid:Pre-formed sections with integral closures accelerate installation velocity in large-diameter steam distribution networks, matching German refinery upgrade timelines for thermal loss reduction compliance.
Pre-insulated systems command the steepest price premiums, though removable configurations are climbing fastest on predictive maintenance integration and condition-based replacement contracting.
End User:
Customer technical requirements range from fire-resistance prioritization in power generation to hydrostatic pressure specifications in offshore hydrocarbon production.
- Oil & Gas:Subsea tieback specifications for hydrostatic pressure resistance and thermal performance across -160°C to 200°C service envelopes drive foam product penetration with certified-grade pricing multiples. Offshore projects in the North Sea and Gulf of Mexico anchor demand for multilayer systems combining aerogel interlayers with rigid foam structural cores.
- Chemical Processing:Energy-intensive operators in Germany's industrial corridor are accelerating steam distribution network retrofits to cut thermal losses, opening specification windows for compliant foam and mineral wool systems under EU F-Gas and REACH binder restrictions.
- Power Generation:Fire resistance ratings dominate boiler and turbine insulation procurement, anchoring mineral wool share despite thermal conductivity disadvantages versus foam alternatives. US coal and combined-cycle fleets prioritize pre-formed low-dust products under tightened OSHA silica exposure thresholds.
- Manufacturing:Process fluid temperature maintenance across food, pharmaceutical, and general industrial applications drives standardized fiberglass and polyethylene specifications with limited premium-grade penetration.
Oil and gas retains the largest value concentration, yet chemical processing is gaining share fastest on capacity expansion in India's Gujarat corridor and European refinery upgrade cycles.
Thickness:
Dimensional selection directly correlates with process temperature differential, ambient conditions, and condensation control requirements in specification engineering.
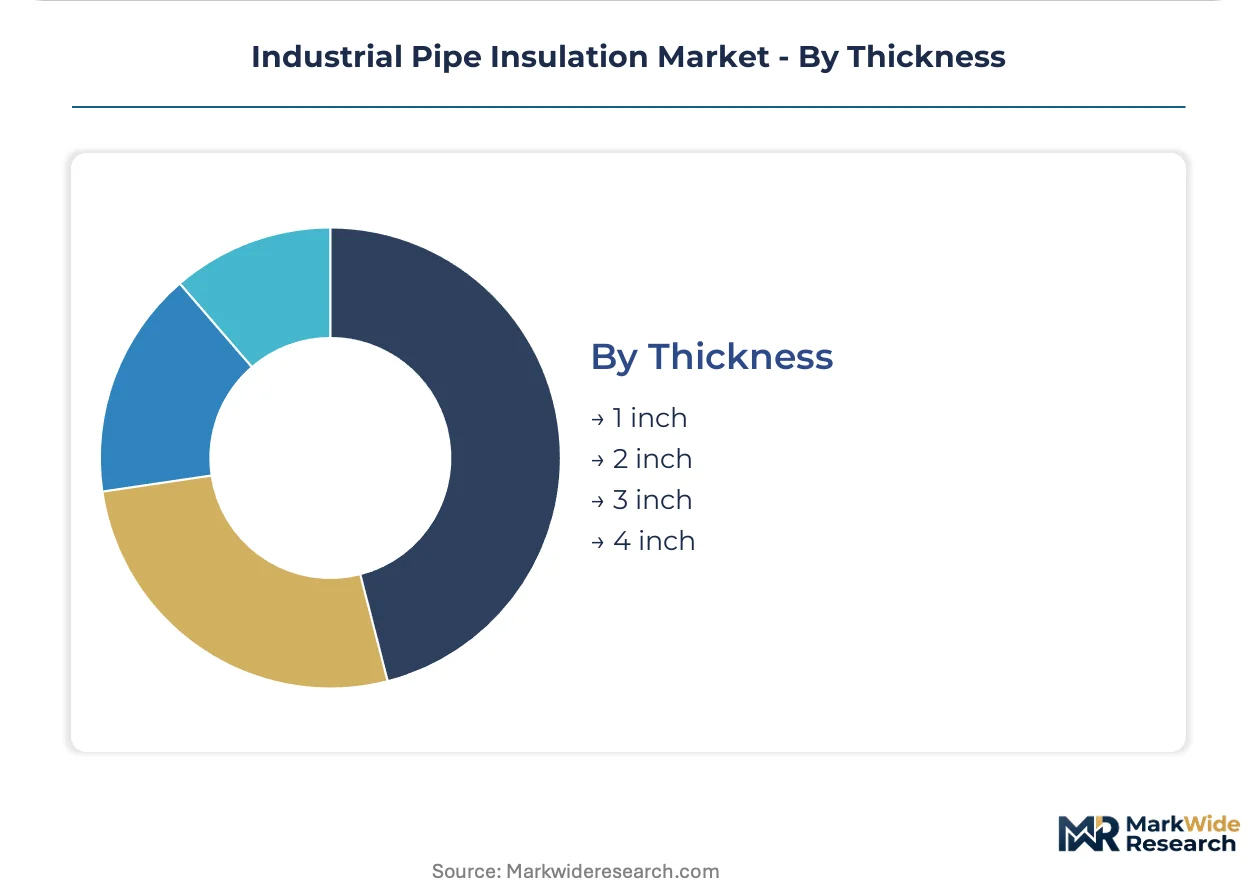
- 2 inch:Standard specification for moderate-temperature steam service in chemical processing and manufacturing applications, balancing material cost against thermal loss reduction targets in German refinery retrofit programs.
- 3 inch:Cryogenic and high-temperature process default for LNG terminals and power generation superheated steam lines where condensation prevention or personnel protection mandates override incremental material expense.
- 1 inch:Constrained to low-temperature differential applications and jacketing overlays where space limitations or existing infrastructure clearances restrict build-up.
- 4 inch:Extreme service specification for Arctic pipeline routes and ultra-high-temperature process units with limited volume penetration outside specialized hydrocarbon production environments.
Two-inch specifications hold the broadest application base, while three-inch configurations are expanding most quickly on cryogenic LNG infrastructure deployment and elevated process temperature requirements in chemical plant expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among integrated glass fiber and mineral wool producers in Germany, the United States, and China, with specification-grade capacity clustering near major chemical processing and power generation demand centers. Regional procurement patterns diverge sharply between mature replacement markets with tightened silica exposure protocols and greenfield expansions prioritizing fire resistance ratings.
United States
OSHA's respirable crystalline silica limits are accelerating specification shifts toward pre-formed, low-dust mineral wool configurations across Gulf Coast petrochemical corridors. The Department of Energy's industrial efficiency incentives support steam distribution network retrofits in Texas and Louisiana refining clusters. Houston anchors North American procurement volume through EPC technical offices that disintermediate general contracting relationships.
Germany
EU F-Gas Regulation mandates on lower-GWP blowing agents are compressing foam supplier margins while opening procurement windows for compliant grades. REACH restrictions on formaldehyde-based binders extend qualification cycles for mineral wool systems in power generation applications. The Rhine-Ruhr and Bavarian chemical clusters are accelerating replacement demand through refinery upgrade programs targeting thermal loss reduction.
China
GB standards for industrial energy conservation are tightening thermal performance requirements across steel and petrochemical sectors. The Ministry of Ecology and Environment's dual carbon goals are reshaping specification priorities toward lower-embodied-carbon insulation materials. Yangtze River Delta chemical processing expansions in Jiangsu and Zhejiang provinces are driving greenfield demand for fire-resistant systems.
India
Bureau of Indian Standards certification requirements are formalizing quality tiers in an historically fragmented supply base. The Production Linked Incentive scheme for chemicals and petrochemicals is accelerating capacity additions along the Gujarat coast. Dahej and Mundra industrial corridors are creating specification opportunities for mineral wool systems in refinery and LNG infrastructure projects.
Saudi Arabia
Saudi Standards, Metrology and Quality Organization technical regulations are aligning industrial insulation specifications with Gulf Cooperation Council harmonization initiatives. Vision 2030 downstream diversification programs are expanding chemical processing capacity at Jubail and Yanbu industrial cities. Aramco's domestic procurement preferences are concentrating demand with regional fabricators holding SABIC supply chain qualifications.
Industrial Pipe Insulation Market Competitive Environment
Concentration sits with integrated glass fiber and stone wool producers possessing captive raw material supply and dual-certification footprints across ASTM and EN test houses. The competitive map separates into three archetypes: backward-integrated multinationals controlling borosilicate feedstock, regional specialists with SABIC or EPC direct relationships, and formulation-focused foam producers navigating blowing agent transitions. Dominant competitive moves include capacity expansion in low-embodied-carbon product lines and strategic partnerships with engineering-procurement-construction firms for specification unbundling.
Among European-integrated material science groups, Saint-Gobain and Rockwool International exemplify the dual-certification archetype, while Owens Corning represents North American backward integration into captive glass fiber production. BASF SE and Huntsman International occupy positions within the foam formulation tier, navigating EU F-Gas Regulation compliance windows. These anchors illustrate how specification-grade premiums accrue to players with redundant testing protocols and in-house binder chemistry capabilities.
| Leading Market Players |
|---|
| Saint-Gobain |
| Owens Corning |
| Johns Manville |
| Rockwool International |
| BASF SE |
| Kingspan Group |
| Armacell |
| Knauf Insulation |
| Huntsman International |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day qualification cycles for dual-certified insulation products concentrate procurement leverage with specification engineers at major EPC firms, compressing margins for non-integrated suppliers while rewarding captive borosilicate feedstock holders with pricing power in premium-grade tiers. This lead-time band reflects how REACH and OSHA compliance testing protocols have reshaped supplier economics, bifurcating the market into certified-premium and commodity-grade pricing corridors.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across foam product categories, forcing manufacturers to absorb reformulation costs for lower-GWP blowing agents while maintaining specification premiums for compliant grades. Three-tier pricing structure across premium-certified, mid-grade, and commodity levels separates ASTM C547/EN 14303 dual-certified products from single-standard alternatives, with price differentiation anchored in certification investment and captive raw material access. Cost compression in mid-tier foam segments is intensifying because hydrocarbon blowing agent transitions extend production cycles, while US Gulf Coast petrochemical operators prove least price-sensitive due to thermal loss reduction mandates and OSHA silica compliance liability.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending inbound logistics costs for borosilicate glass fiber feedstock, amplifying margin advantages for producers with captive smelting operations in Ohio and West Virginia. Supply concentrates among integrated producers in Germany, the United States, and China, with specification-grade capacity clustering near Rhine-Ruhr chemical corridors and Texas refining hubs. Raw material dependencies center on soda ash, boron compounds, and formaldehyde-free binder chemistries, with single-source vulnerability concentrated in European phenolic resin supply. Distribution runs through EPC technical offices in Houston, Rotterdam, and Singapore that disintermediate traditional general contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from aerogel composite systems achieving sub-0.020 W/m·K thermal conductivity, requiring defensive positioning around certification moats and captive supply economics.
For Market Incumbents: Secure dual-certification redundancy across ASTM and EN test houses to lock in specification-driven contract premiums before REACH binder restrictions fully phase in. Deepen upstream control over borosilicate feedstock to defend margin pools against commodity importers facing energy-linked input volatility. Prioritize low-embodied-carbon product line investments to capture EU CBAM procurement scoring advantages. For New Entrants and Emerging Players: ECHA-notified body fast-tracks for phenolic and bio-based binder systems open qualification windows in European power generation and marine applications where incumbent requalification cycles lag demand. Target India's Gujarat chemical corridor expansion for greenfield mineral wool specifications, where Bureau of Indian Standards certification formalization is displacing fragmented local supply. Pursue direct EPC technical office relationships in Singapore to bypass entrenched general contracting channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified material science conglomerates with underperforming insulation divisions lacking dual-certification infrastructure or captive borosilicate supply. Long-term viability hinges on regulatory compliance durability across F-Gas and REACH evolution, with consolidation rewards accruing to platforms integrating binder chemistry capabilities with specification-grade testing assets. Watch for OSHA silica enforcement acceleration in US manufacturing corridors as inflection signal for low-dust mineral wool demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Feedstock | Captive supply locks in margin pools unavailable to commodity importers facing energy cost volatility. |
| Dual-Certification Capacity Expansion | ASTM C547 and EN 14303 redundancy commands specification premiums in cross-border chemical processing tenders. |
| Low-GWP Blowing Agent Reformulation | EU F-Gas compliance opens procurement windows in German refinery upgrade cycles while compressing non-compliant supplier margins. |
| IoT-Enabled Predictive Maintenance Partnerships | Sensor integration with thermal monitoring creates condition-based replacement contracts in power generation fleets. |
| Low-Embodied-Carbon Product Line Investment | EU CBAM implementation rewards preferential procurement scoring for compliant materials in cross-border infrastructure. |
Study Parameters
A standing panel of EPC specification engineers, petrochemical plant maintenance directors, mineral wool production managers, and industrial procurement leads provided ongoing calibration against actual contract award patterns and qualification cycle durations. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings of publicly traded insulation producers, American Chemistry Council sector reports, and European Chemical Industry Council capacity databases. Bottom-up volume estimates from end-use application sizing were triangulated against top-down macroeconomic indicators and energy efficiency policy trajectories.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling material chemistry segments, installation method preferences, end-use industry requirements, and regional regulatory clusters. CAGRs were derived from segmented growth rate analysis applied to baseline penetration estimates, incorporating refinery upgrade cycle timing, chemical capacity expansion pipelines, and power generation fleet replacement schedules as industry-specific demand drivers.
Underlying assumptions cover continued OSHA silica enforcement trajectory, EU F-Gas Regulation phase-down timelines, and REACH binder restriction implementation, with deviation risk concentrated in blowing agent technology transitions and carbon border adjustment mechanism scope expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Acoustic Materials Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market