
 Global Low Smoke Halogen-Free Cable Materials Market | 2026-2036
Global Low Smoke Halogen-Free Cable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Smoke Halogen-Free Cable Materials Market Foresight
The performance gap between premium cross-linked polyolefin formulations and commodity ethylene vinyl acetate blends is decoupling as fire safety specifications tighten across high-occupancy buildings. DuPont leverages its fluoropolymer heritage to sustain technical credibility in aerospace wiring channels. BASF SE anchors European supply through integrated polyamide and TPU compounding assets in Ludwigshafen. Jiangsu Dewei Advanced Materials competes on cost-adjusted performance for Asian power transmission tenders.
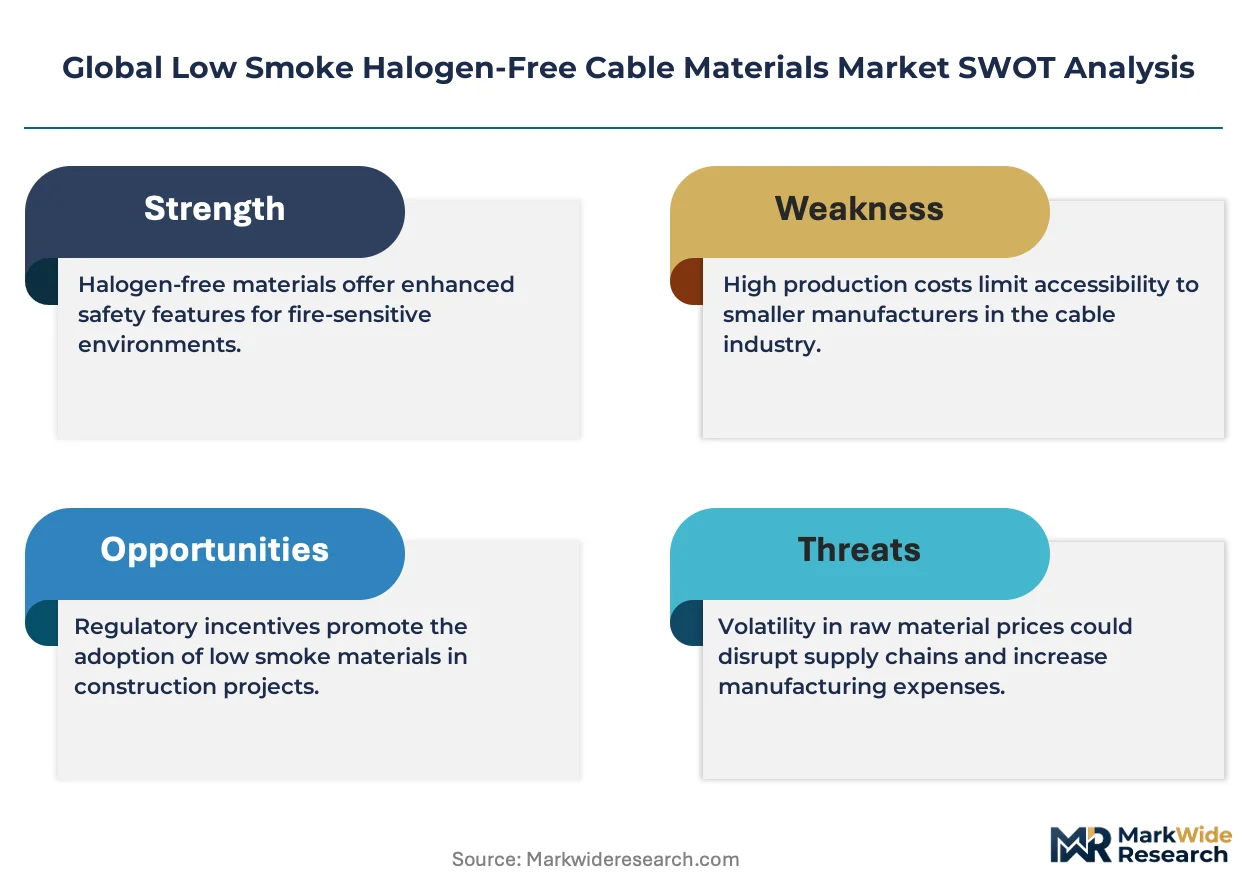
Low smoke halogen-free cable materials are thermoplastic or cross-linked compounds formulated without chlorine, bromine, or fluorine, achieving flame retardancy through metal hydroxide fillers such as aluminum or magnesium hydroxide at loadings typically exceeding 50 percent by weight; they generate minimal opaque smoke and no corrosive halogen acids during combustion, protecting both human evacuation paths and sensitive electronic equipment in confined installations. Cross-linked polyolefin dominates margin pools in marine systems and aerospace wiring where IEC 60332-3 and EN 50575 certifications command price premiums. Thermoplastic elastomers represent the fastest-expanding material category as robotic cable and continuous-flex industrial automation applications multiply.
The EU Green Deal and REACH framework restrict halogenated flame retardants in public infrastructure, while NFPA 262 governs plenum-rated installations across United States commercial buildings. China's GB standards and dual carbon goals pressure domestic cable producers toward metal hydroxide-based formulations. Stakeholders must monitor how certification fragmentation between UL 1581, IEC 60332, and emerging national fire codes reshapes product development priorities and regional market access requirements.
Market Dynamics
The transition from legacy PVC insulation to metal hydroxide-based formulations is compressing established supply chains as data center operators and infrastructure developers simultaneously demand higher fire safety ratings and lower embodied carbon in cable procurement specifications.
Growth Catalysts
- EU Green Deal implementation:REACH restrictions on halogenated flame retardants in public infrastructure are mandating material substitution across European transportation and building projects, eliminating incumbent PVC and fluoropolymer alternatives from tender eligibility.
- Data center power density escalation:Hyperscale facility operators in Northern Virginia, Frankfurt, and Singapore are specifying IEC 60332-3 certified cabling for busway and power distribution architectures to satisfy insurer risk assessments and local fire marshal requirements.
- Cross-linked polyolefin compounding advances:Improved dispersion of aluminum hydroxide at loadings exceeding 60 percent by weight is enabling thinner wall constructions without sacrificing mechanical properties, opening marine and aerospace wiring channels previously reserved for fluoropolymer competitors.
Market Restraints
- Metal hydroxide feedstock concentration:High-purity aluminum hydroxide supply concentrates among Chinese and Brazilian bauxite processors, exposing compounders to export quota volatility and ocean freight rate spikes that compress margin stability.
- Processing energy intensity:Cross-linking via electron beam or silane grafting requires capital-intensive equipment with extended qualification timelines, creating a barrier to entry for mid-volume compounders seeking marine certification.
- Commodity EVA substitution pressure:Ethylene vinyl acetate blends at lower filler loadings satisfy minimum smoke requirements in price-sensitive building wire applications, fragmenting volume into lower-margin product tiers.
Strategic Opportunities
- Indian smart city infrastructure:Bureau of Indian Standards adoption of halogen-free mandates in metro rail and airport construction is creating procurement volume for compounders establishing local compounding partnerships ahead of domestic capacity buildout.
- Continuous-flex robotics cabling:Thermoplastic elastomer formulations with dynamic flex life exceeding 10 million cycles are capturing specification share in automotive manufacturing lines and warehouse automation deployments across Germany and Japan.
- NFPA 262 plenum certification expansion:US commercial real estate developers pursuing LEED and WELL certifications are specifying smoke density limits below 0.50 optical density, favoring premium polyolefin compounds over legacy PVC plenum alternatives in high-rise construction.
Industry Challenges
- IEC-UL certification harmonization delays:Divergent test protocols between IEC 60332-3 vertical flame spread and UL 1581 vertical tray burn methods force compounders to maintain dual formulation portfolios, extending product development cycles by 8-14 months.
- Compounder technical talent scarcity:Formulation chemistry expertise combining polymer rheology, filler surface modification, and cable processing physics concentrates among retiring specialists in Ludwigshafen, Tokyo, and Connecticut, constraining R&D velocity at emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Smoke Halogen-Free Cable Materials Market |
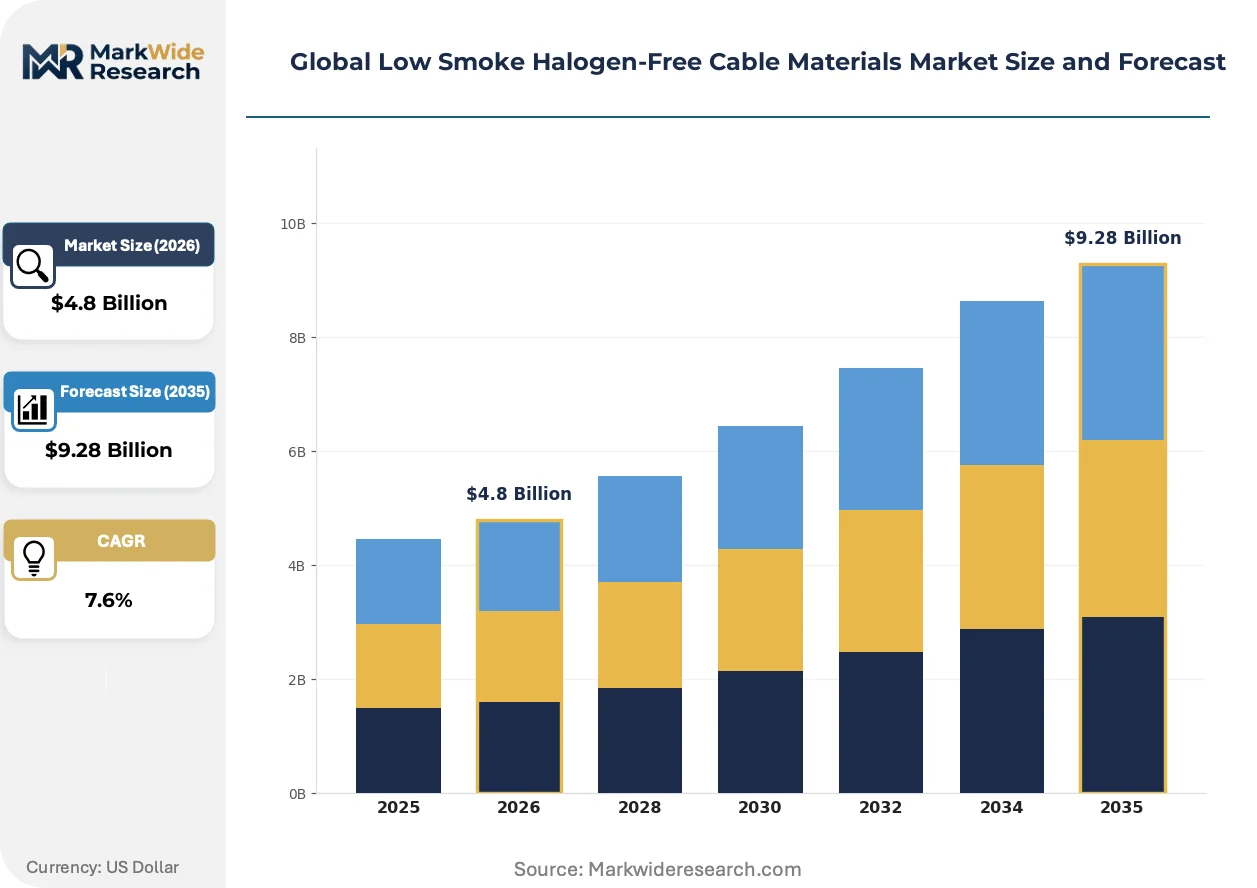
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Ethylene Vinyl Acetate, Polyvinyl Chloride, Cross-linked Polyolefin, Thermoplastic Elastomers Application: Power Transmission, Telecommunication, Industrial Automation, Marine Systems, Aerospace Wiring End User Industry: Energy Generation, Telecommunication Providers, Manufacturing Plants, Shipping Operators, Aviation Corporations Certification Standard: UL 1581, IEC 60332, BS 7629, EN 50575, NFPA 262 |
| Companies Covered | Bayer AG, Hitachi-Cable Ltd., DuPont, Jiangsu Dewei Advanced Materials Co., Ltd., Fujikura Ltd., The Dow Chemicals, Alpha Gary, Shanghai Kaibo, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Smoke Halogen-Free Cable Materials Market Shifts & Advancements
Material scientists and cable engineers are converging on multi-functional filler systems that simultaneously deliver flame retardancy, mechanical durability, and processing efficiency, collapsing the traditional trade-offs that segmented the market into application-specific compound tiers.
Silane-grafted polyolefin compounds with in-situ moisture cross-linking are absorbing specification share in medium-voltage power distribution applications previously dominated by peroxide-cured ethylene propylene rubber. European grid operators in Germany and the Netherlands are qualifying these materials for 20-30 kV submarine and underground installations where thermal aging resistance and low smoke emission are co-requisites. The technology is absorbing margin from EPDM suppliers by eliminating the need for separate curing infrastructure while matching their long-term electrical stability performance.
REACH authorization procedures for legacy brominated flame retardants are accelerating compounder reformulation cycles as ECHA adds decabromodiphenyl ether and hexabromocyclododecane to the sunset list. German automotive cable producers are converting harness specifications to metal hydroxide systems ahead of 2025 type-approval deadlines, pressuring Eastern European compounders to upgrade compounding lines or exit supply chains. The regulatory pressure is compressing the viable product lifecycle of halogenated alternatives and redirecting R&D budgets toward surface-modified magnesium hydroxide grades with improved polymer compatibility.
Specification consolidation among engineering-procurement-construction firms is concentrating buying power for large infrastructure projects, displacing fragmented distributor networks in favor of direct compounder relationships with tier-one cable manufacturers. Skanska, Bechtel, and Samsung C&T are pre-qualifying halogen-free material suppliers for multi-year framework agreements covering data center, transit, and healthcare verticals. The purchasing pattern shift is most visible in Nordic markets where public procurement rules favor consolidated supplier panels with documented carbon footprints and circular material content declarations.
Global Low Smoke Halogen-Free Cable Materials Market Segmentation
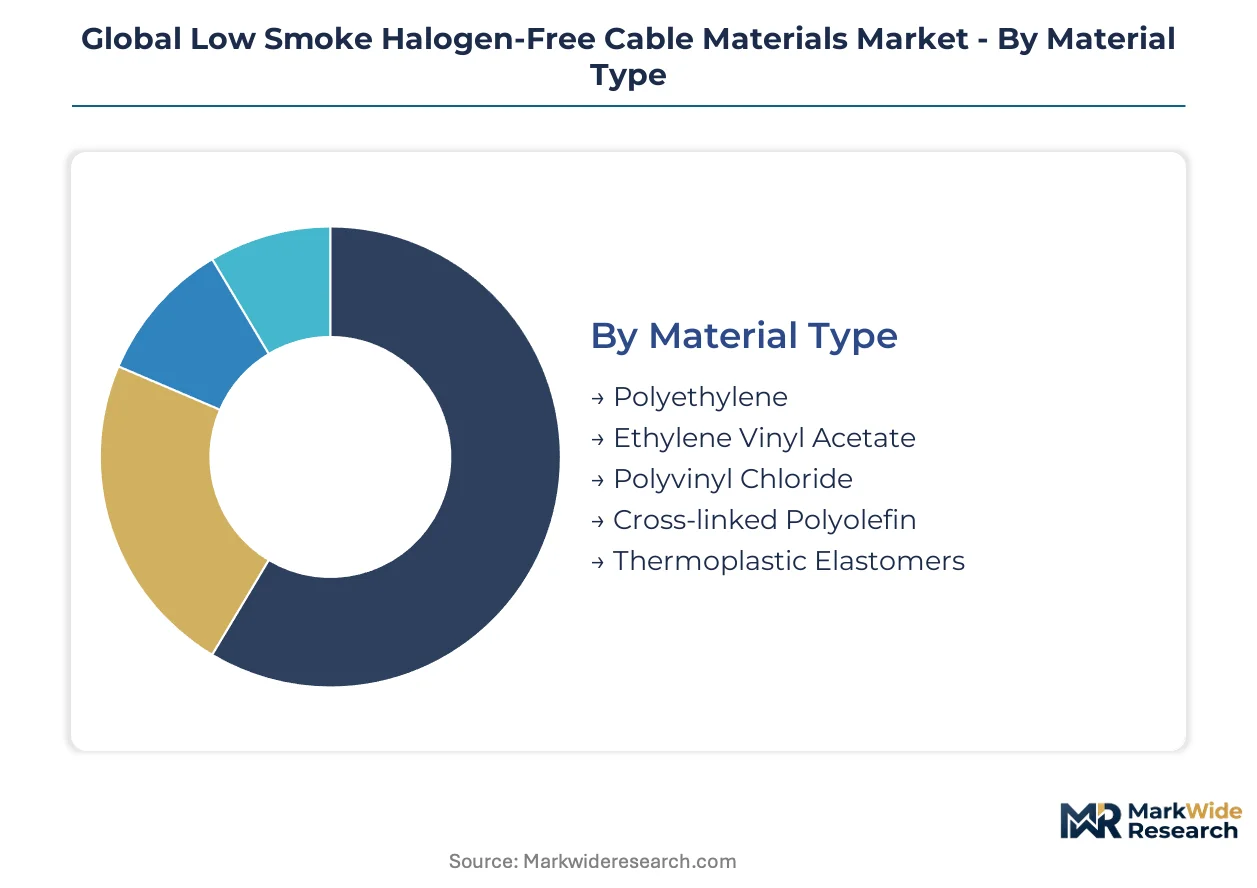
Material selection in low smoke halogen-free cable compounds follows divergent technical logics across voltage classes, flex requirements, and regulatory jurisdictions. Compounders configure formulation portfolios around certification tier and end-use thermal stress rather than pursuing universal solutions.
Material Type:
Cross-linking chemistry and base polymer architecture determine smoke suppression efficiency, mechanical durability, and processing economics across installation environments.
- Cross-linked Polyolefin:Silane-grafted or electron-beam-cured formulations achieve thermal stability exceeding 150°C while maintaining low smoke density under IEC 60332-3 protocols. Marine systems and aerospace wiring in Germany and Japan specify these compounds for bundled cable installations where flame spread containment is mandatory.
- Thermoplastic Elastomers:TPU and TPE compounds deliver dynamic flex life surpassing 10 million cycles without cracking, enabling continuous-motion robotic cabling in automotive assembly lines across Stuttgart and Toyota City. The absence of cross-linking infrastructure reduces capital barriers for compounders serving industrial automation.
- Polyethylene:Linear low-density grades serve as base resins for metal hydroxide compounding at 50-60% filler loadings in building wire applications.
- Ethylene Vinyl Acetate:EVA copolymers at 18-28% vinyl acetate content improve filler dispersion and surface finish in cost-sensitive power distribution cables.
- Polyvinyl Chloride:Phthalate-plasticized PVC persists in transition markets where halogen-free mandates remain unenforced, though smoke generation disqualifies it from new infrastructure tenders in EU member states.
Cross-linked Polyolefin leads on scale; Thermoplastic Elastomers lead on momentum.
Application:
Installation environment dictates the priority ranking among flame retardancy, mechanical toughness, and signal integrity performance vectors.
- Power Transmission:Medium-voltage compounds for 20-30 kV submarine and underground circuits require silane-grafted polyolefin with enhanced thermal aging resistance. Grid operators in the Netherlands and Germany are qualifying these materials for North Sea interconnector projects where low smoke emission accompanies electrical reliability mandates.
- Industrial Automation:Continuous-flex cabling for robotic arms and automated guided vehicles demands thermoplastic elastomer formulations with oil resistance and torsional fatigue performance. Automotive manufacturing clusters in Bavaria and Aichi Prefecture are driving specification volume for high-cycle flex applications.
- Telecommunication:Data center busway and structured cabling prioritize IEC 60332-3 certification for bundled installations in hyperscale facilities across Northern Virginia and Singapore.
- Marine Systems:Offshore platform and vessel wiring requires IMO-compliant low smoke compounds with hydrocarbon resistance for engine room temperatures.
- Aerospace Wiring:FAA and EASA certification timelines restrict qualified compound sources for aircraft harness applications to established fluoropolymer and polyolefin suppliers.
Power Transmission commands the largest procurement volumes; Industrial Automation exhibits the steepest specification growth trajectory.
End User Industry:
Procurement sophistication varies sharply between regulated utilities and fragmented manufacturing operations, fragmenting pricing power across the value chain.
- Energy Generation:Offshore wind developers and nuclear operators specify certified compounds through engineering-procurement-construction consortiums with multi-year framework agreements. Orsted and EDF procurement teams audit compounder carbon footprints and circular content declarations as tender pre-conditions.
- Telecommunication Providers:Hyperscale data center operators in Frankfurt and Singapore enforce IEC 60332-3 and NFPA 262 compliance through direct supplier relationships, bypassing distributor networks.
- Manufacturing Plants:Automotive OEMs and tier suppliers convert harness specifications to metal hydroxide systems ahead of REACH authorization deadlines for legacy brominated flame retardants.
- Shipping Operators:Cruise line and container ship newbuilds in South Korean yards adopt IMO 2020-aligned low smoke cabling for passenger safety zones.
- Aviation Corporations:Boeing and Airbus supply chains maintain dual-qualified compound sources to mitigate certification risk in long-lead wiring harness contracts.
Energy Generation concentrates purchasing power; Telecommunication Providers are advancing specification requirements fastest.
Certification Standard:
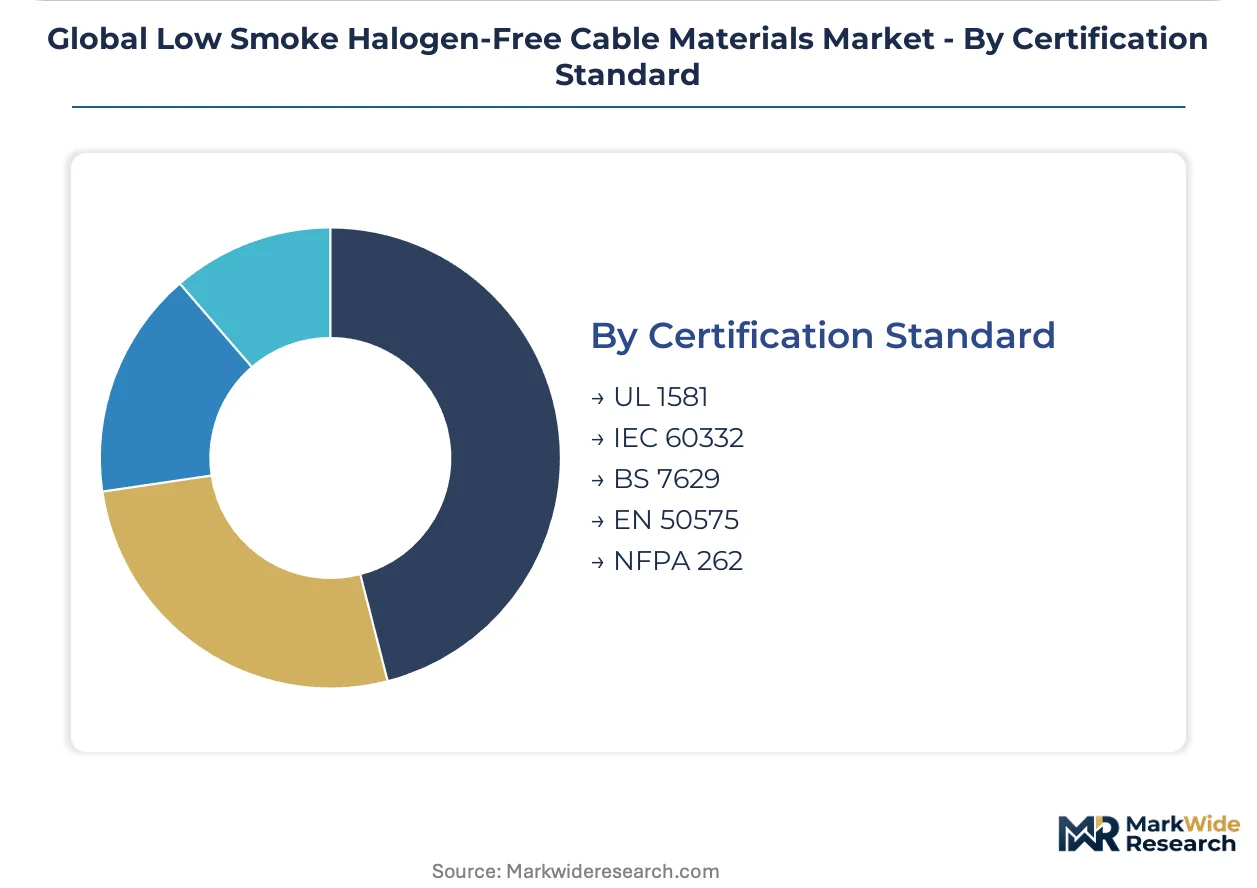
Test protocol fragmentation between IEC and UL systems forces compounders to maintain parallel formulation portfolios, extending qualification timelines and R&D overhead.
- IEC 60332:The vertical flame spread and vertical tray burn protocols govern bundled cable installations across European, Middle Eastern, and Asian infrastructure projects. German rail operators and Chinese metro authorities specify Category A ratings for tunnel and station cabling where evacuation path visibility is critical.
- NFPA 262:The plenum-rated smoke density limit of 0.50 optical density governs US commercial building installations. LEED and WELL certification pursuit in New York and Chicago high-rise construction is elevating specification share for premium polyolefin compounds over legacy PVC alternatives.
- UL 1581:The vertical tray flame test remains mandatory for US industrial and utility cable approvals, creating divergence from IEC test methods.
- EN 50575:The European Construction Products Regulation fire performance classes CPR B2ca and Cca are mandatory for fixed installation cables in EU member states.
- BS 7629:British Standard specifications for fire-resistant cables with enhanced circuit integrity persist in UK and Commonwealth procurement frameworks post-Brexit.
IEC 60332 covers the broadest geographic footprint; NFPA 262 is gaining specification traction fastest in premium commercial construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with polymer rheology expertise cluster in Ludwigshafen, Tokyo, and Connecticut, anchoring regional innovation capacity. Procurement volumes concentrate where data center construction, offshore wind deployment, and metro rail expansion intersect with tightening fire safety codes.
China
Hyperscale data center operators in Beijing and Shanghai are replacing PVC-insulated busway cabling with metal hydroxide-based alternatives. The country's GB standards and dual carbon goals pressure domestic cable producers toward halogen-free formulations. Jiangsu province hosts compounding capacity serving power transmission tenders across the Yangtze River Delta.
Germany
Grid operators in the Netherlands and Germany are qualifying silane-grafted polyolefin for 20-30 kV North Sea interconnector projects. REACH restrictions on halogenated flame retardants eliminate PVC alternatives from public infrastructure tenders. BASF SE's integrated polyamide and TPU compounding assets in Ludwigshafen anchor European supply security.
United States
Hyperscale facility operators in Northern Virginia specify IEC 60332-3 certified cabling to satisfy insurer risk assessments and local fire marshal requirements. NFPA 262 governs plenum-rated installations across commercial buildings pursuing LEED and WELL certifications. DuPont leverages its fluoropolymer heritage to sustain technical credibility in aerospace wiring channels.
Japan
Automotive manufacturing clusters in Aichi Prefecture drive specification volume for thermoplastic elastomer formulations with dynamic flex life exceeding 10 million cycles. METI-backed industrial automation initiatives accelerate continuous-flex robotic cabling adoption. Fujikura Ltd. and Hitachi-Cable occupy positions serving harness conversion timelines ahead of 2025 type-approval deadlines.
India
Bureau of Indian Standards adoption of halogen-free mandates in metro rail and airport construction creates procurement volume for compounders establishing local partnerships. Smart city infrastructure investments in Delhi-Mumbai Industrial Corridor projects demand certified low smoke materials. Domestic capacity buildout lags, opening channels for technology licensing arrangements with East Asian suppliers.
Global Low Smoke Halogen-Free Cable Materials Market Competitive Landscape
Capital-heavy producers with integrated polyolefin compounding and silane grafting infrastructure compete with asset-light designers outsourcing cross-linking to toll processors. The vendor base fragments across three tiers: integrated chemical conglomerates with captive polymer supply, specialized cable compounders focused on certification-heavy marine and aerospace verticals, and regional processors serving price-sensitive building wire applications. Dominant competitive moves include capacity expansion in silane-grafting lines for medium-voltage power cables and strategic partnerships between compounders and tier-one cable manufacturers to secure multi-year framework agreements with engineering-procurement-construction firms.
Within the integrated chemical conglomerate tier, BASF SE and The Dow Chemical exemplify European and North American anchors with backward control over base resin supply. Among Asia-Pacific-based compounders, Jiangsu Dewei Advanced Materials Co., Ltd. occupies a position representing cost-adjusted performance competition for regional power transmission tenders. DuPont sits within the specialty materials archetype, drawing on fluoropolymer heritage to sustain specification share in certification-restricted aerospace and defense channels.
| Leading Market Players |
|---|
| Bayer AG |
| Hitachi-Cable Ltd. |
| DuPont |
| Jiangsu Dewei Advanced Materials Co., Ltd. |
| Fujikura Ltd. |
| The Dow Chemicals |
| Alpha Gary |
| Shanghai Kaibo |
| BASF SE |
| Others |
Supply & Pricing Matrix
Formulation chemists with polymer rheology and filler surface modification expertise cluster in Ludwigshafen, Tokyo, and Connecticut, creating labor-cost differentials that widen pricing-tier spreads between European premium compounds and Asian cost-adjusted alternatives. REACH compliance costs and certification overhead in Germany sustain premium positioning, while Chinese compounders leverage lower technical wage structures to capture volume in price-sensitive building wire segments.
Pricing Analysis
The bundled certification-and-technical-service model dominates premium tiers, while unbundled commodity compounds compete on base resin cost. Three-tier pricing structure across IEC 60332-3 certified premium, EN 50575 mid-tier, and uncertified economy levels reflects certification investment recovery timelines. Cost compression in EVA-based building wire compounds is intensifying because Brazilian and Chinese aluminum hydroxide processors are expanding merchant-grade supply. Data center operators and EPC consortiums exhibit the lowest price sensitivity, while regional electrical distributors in transition markets remain highly elastic.
Supply Chain Analysis
Single-source vulnerability sits with high-purity aluminum hydroxide supply concentrated among Chinese bauxite processors and Brazilian refining operations. Metal hydroxide feedstock, silane grafting agents, and specialized TPU base resins draw from geographically concentrated upstream nodes. Export quota volatility from Chinese environmental regulators creates structural supply risk. Distribution runs through direct compounder relationships with tier-one cable manufacturers, displacing fragmented distributor networks in large infrastructure verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through silane-grafting technology substitution that collapses EPDM curing infrastructure costs while capturing premium power transmission qualifications.
For Market Incumbents: Lock in multi-year framework agreements with Skanska, Bechtel, and Samsung C&T before EPC consolidation completes, while deepening captive supply of surface-modified magnesium hydroxide grades to offset Chinese feedstock volatility. BASF SE and Dow Chemical should accelerate silane-grafting capacity in Ludwigshafen and Freeport to defend against Japanese TPE specialists entering European offshore wind channels. For New Entrants and Emerging Players: Launch via technology licensing partnerships with East Asian compounders to serve Indian metro rail and airport construction ahead of domestic capacity buildout. Target continuous-flex robotics cabling for automotive manufacturing clusters in Bavaria and Aichi Prefecture, where dynamic flex life specifications exceed incumbent EVA capabilities and certification barriers favor specialized formulation expertise over capital scale. For Investors and Strategic Acquirers: Chemical conglomerates with backward resin integration are the most active acquirer in this space, seeking specialty cable compounders with IEC-UL dual certification portfolios. Over the medium-term horizon, acquisition targets include mid-volume compounders with silane-grafting infrastructure and marine certification track records. Monitor ECHA sunset list acceleration for brominated flame retardants as the inflection signal for metal hydroxide formulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Silane-Grafting Capacity Expansion | Eliminates peroxide curing infrastructure while matching EPDM thermal aging for 20-30 kV submarine cables. |
| Backward Integration into Metal Hydroxide | Captures margin from Chinese bauxite processors and insulates against export quota volatility. |
| Dual Certification Portfolio Investment | Resolves IEC-UL protocol divergence that extends product development cycles by 8-14 months. |
| Long-term Supply Agreement with EPC Firms | Secures volume commitments from Skanska and Bechtel ahead of consolidated supplier panel pre-qualification. |
| Surface-Modified Magnesium Hydroxide R&D | Improves polymer compatibility to meet German automotive harness conversion timelines ahead of REACH deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cable compounder R&D directors, EPC procurement leads, tier-one cable manufacturer plant managers, and formulation chemistry specialists with secondary validation. Customs data from Chinese bauxite processors, ECHA regulatory filings, IEC certification registries, and SEC disclosures from integrated chemical conglomerates anchored supply-side modeling. Bottom-up volume estimates from compounding capacity utilization and top-down demand projections from infrastructure investment databases were triangulated for consistency.
Segment-weighting applied material type, application voltage class, and certification tier as primary dimensions across the projection horizon. Cross-linked polyolefin, thermoplastic elastomer, and commodity EVA grade tiers were modeled separately with end-use coefficients for data center, marine, aerospace, and industrial automation channels. CAGRs derived from regression against historical substitution rates from PVC to halogen-free formulations, adjusted for regulatory mandate acceleration in EU member states and Chinese dual carbon policy implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum hydroxide export restriction scenarios or accelerated REACH authorization timelines. Forecasts reflect assumptions about EPC firm consolidation pace and certification harmonization progress without guaranteeing specific regulatory calendar outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Insulation Market
Insulation Materials
Hot Insulation Materials Market