
 Active Insulation Market | 2026-2036
Active Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Active Insulation Market Intelligence
Software-defined climate control integration is rebalancing the value proposition from a simple material to an intelligent system component. W.L. Gore & Associates, Inc. leverages its membrane expertise to create breathable yet insulated fabrics. Polartec, LLC specializes in fleece and synthetic fiber technologies that respond to body heat and external conditions. Toray Industries, Inc. extends its chemical engineering capabilities into advanced synthetic insulation fibers for diverse applications.
Active insulation refers to materials engineered to dynamically adjust their thermal resistance in response to environmental stimuli. These materials, often using microencapsulated phase change materials, maintain thermal comfort across fluctuating conditions. The technology of Phase Change Materials sees significant application within the performance apparel segment. In construction, aerogel panels are gaining traction for superior thermal management.
Material composition and market access are shaped by regulations like the EU's REACH framework, which governs chemical substances in textiles. In parallel, US EPA standards influence material choices for building applications, while China's GB standards mandate energy efficiency in new construction. Stakeholders must navigate the complex interplay between pioneering new material functionalities and adhering to an expanding set of international safety and environmental mandates.
Market Dynamics
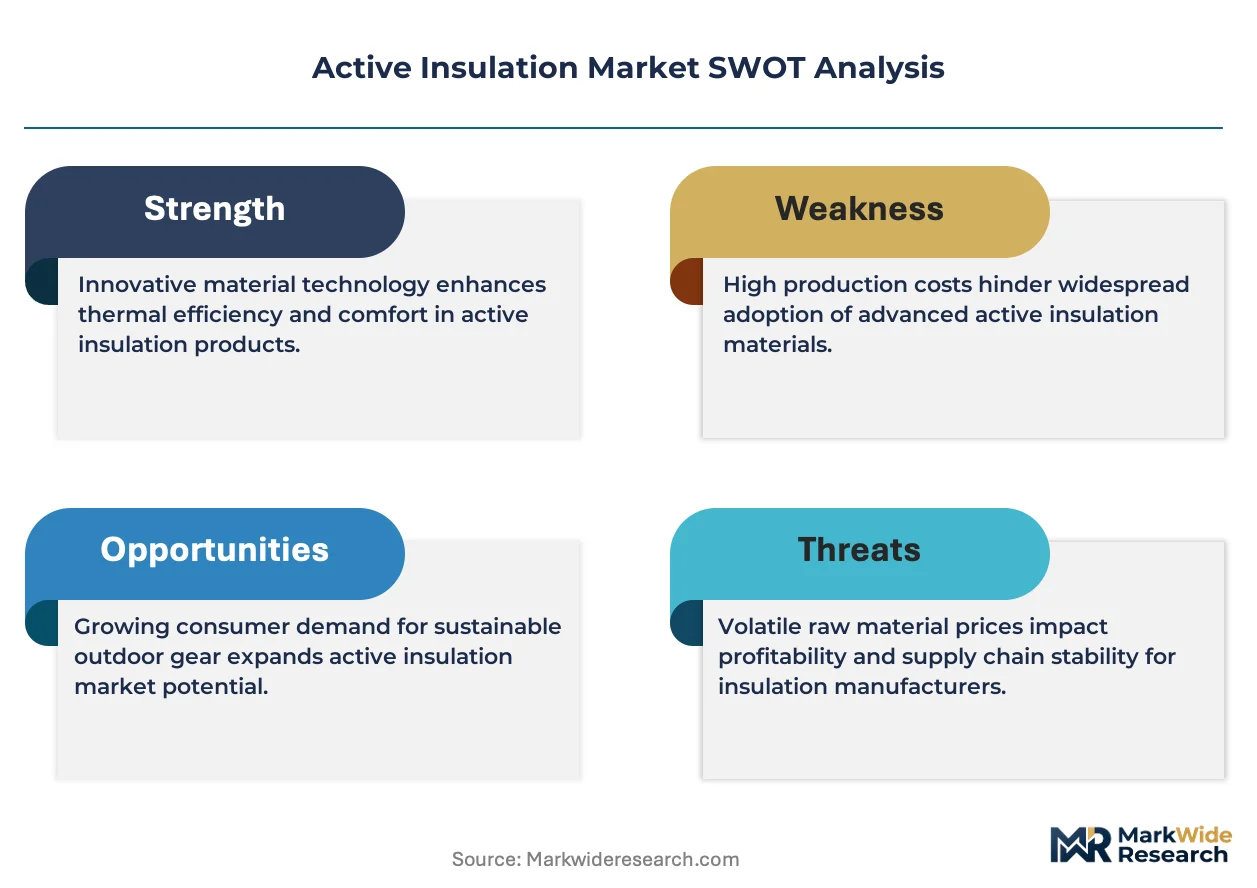
The convergence of material science and software-defined control is the central force shaping the active insulation market. The evolution from passive thermal barriers to intelligent, environmentally responsive systems, driven by technologies like Phase Change Materials, is creating new value propositions in apparel and construction.
Growth Catalysts
- Advanced Materials:The continuous improvement of microencapsulated Phase Change Materials (PCMs) enhances thermal regulation capabilities, driving adoption in high-performance sportswear and technical workwear.
- Energy Efficiency Mandates:Regulations such as China's GB standards for new construction and the EU Green Deal's building renovation goals create sustained demand for high-performance insulation like aerogel panels.
- Industrial Demand:Germany's advanced manufacturing sector requires specialized technical textiles for automotive interiors and protective industrial apparel, pulling demand for durable, responsive insulation.
Market Restraints
- Cost Structure:The high production cost of materials like aerogels and advanced PCMs confines their application primarily to premium, performance-oriented market segments, limiting broader adoption.
- Regulatory Compliance:The EU's REACH framework imposes strict controls on chemical substances, complicating the development and import of new insulation formulations and textile finishes.
- Durability Limitations:Certain active insulation technologies exhibit performance degradation after repeated washing or extended wear, presenting a significant challenge for their use in everyday apparel.
Strategic Opportunities
- Medical Applications:Untapped opportunities exist in the medical sector for thermal management blankets, patient transport systems, and therapeutic wraps that require stable temperature control.
- Smart Textile Integration:The convergence of active insulation with wearable sensors and IoT connectivity enables the creation of intelligent garments that actively manage thermal comfort based on biometric data.
- Cold Chain Logistics:There is significant potential for using advanced insulation panels and wraps to improve thermal efficiency in temperature-sensitive pharmaceutical and food logistics in North America.
Industry Challenges
- Performance Standardization:A lack of universally accepted testing standards for measuring the dynamic thermal response of active insulation creates ambiguity for end-users and complicates product comparisons.
- Manufacturing Integration:Integrating novel materials like PCMs into existing, high-volume textile production lines requires significant capital investment and process re-engineering, slowing adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Insulation Market |
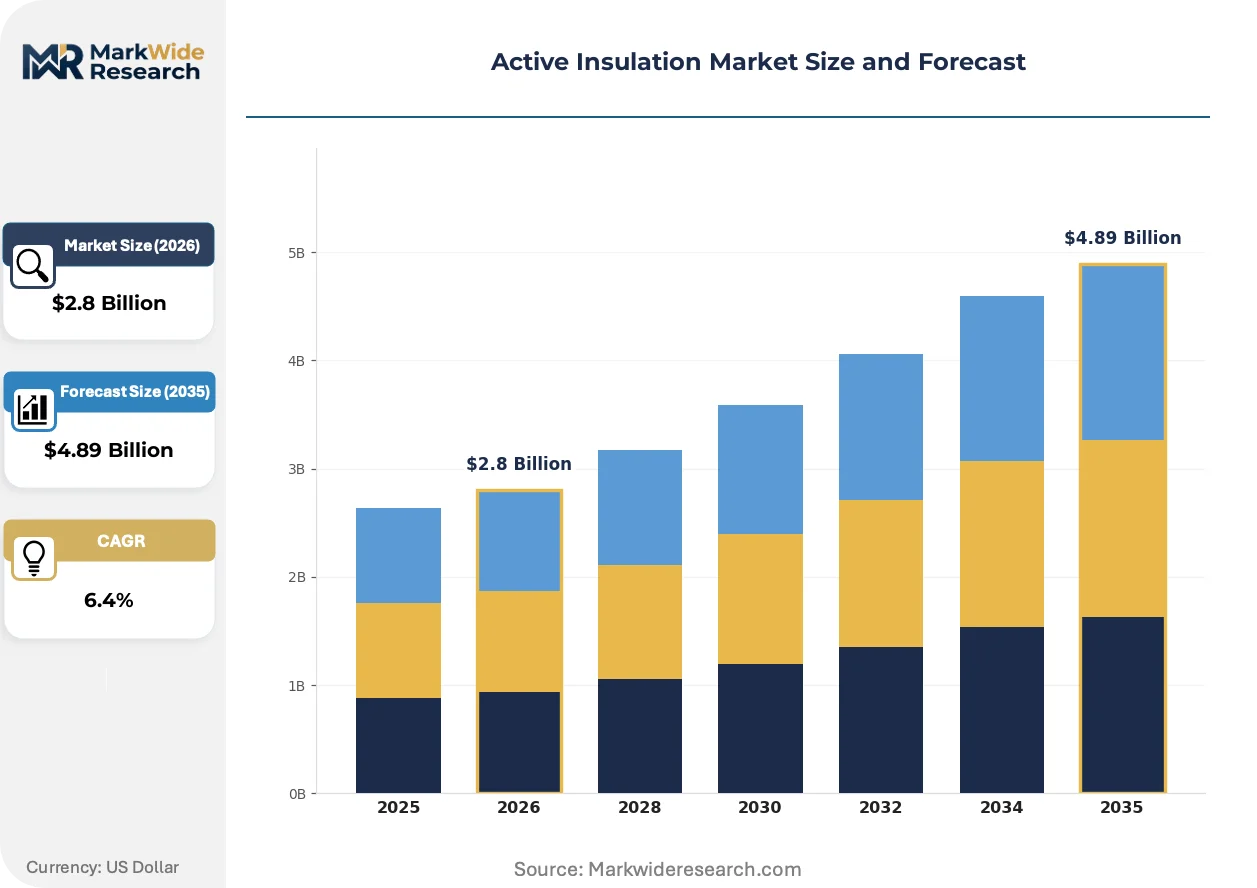
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
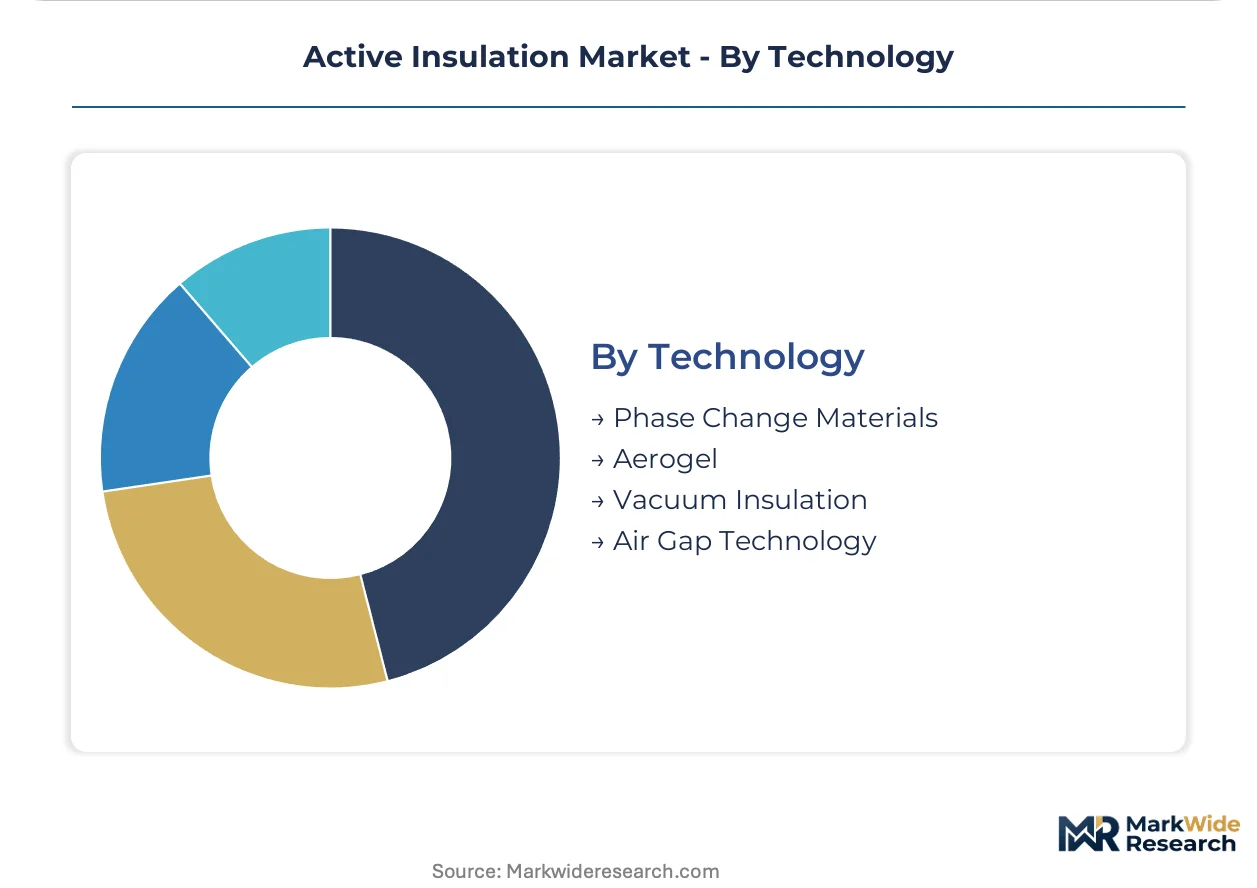
| Segmentation | Product Type: Fibers, Films, Coatings, Panels End User: Construction, Apparel, Automotive, Aerospace Application: Thermal Management, Soundproofing, Energy Saving, Climate Control Technology: Phase Change Materials, Aerogel, Vacuum Insulation, Air Gap Technology |
| Companies Covered | Owens Corning, PrimaLoft, Inc., Armacell International S.A, Saint-Gobain Group, Rockwool International A/S, 3M Company, W.L. Gore & Associates, Inc., Polartec, LLC, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Insulation Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of material science with digital intelligence. This shift is creating textiles and building materials that are no longer passive components but active participants in managing thermal environments, driven by sustainability pressures and new consumer expectations for performance.
Biomimetic fibers that alter their structure in response to temperature are a key technological development. The military and professional sports sectors are rapidly adopting these materials for next-generation uniforms and performance apparel. This innovation is rewriting the definition of a textile from a static barrier to a dynamic, self-regulating system.
The EU's circular economy policies, including the Corporate Sustainability Reporting Directive (CSRD), are influencing material selection. These regulations compel manufacturers to provide detailed lifecycle data on their products, including insulation components. This affects the entire textile supply chain, accelerating the shift toward bio-based polymers and recycled synthetic fibers to meet transparency and sustainability mandates.
Consumer demand is shifting toward versatile, all-season products that reduce the need for multiple specialized garments. This behavioral change disrupts the conventional seasonal sales model within the outdoor and urban apparel industries. The trend is most pronounced in major metropolitan areas across Europe and North America, where consumers prioritize functionality and minimalist consumption.
Active Insulation Market Segmentation
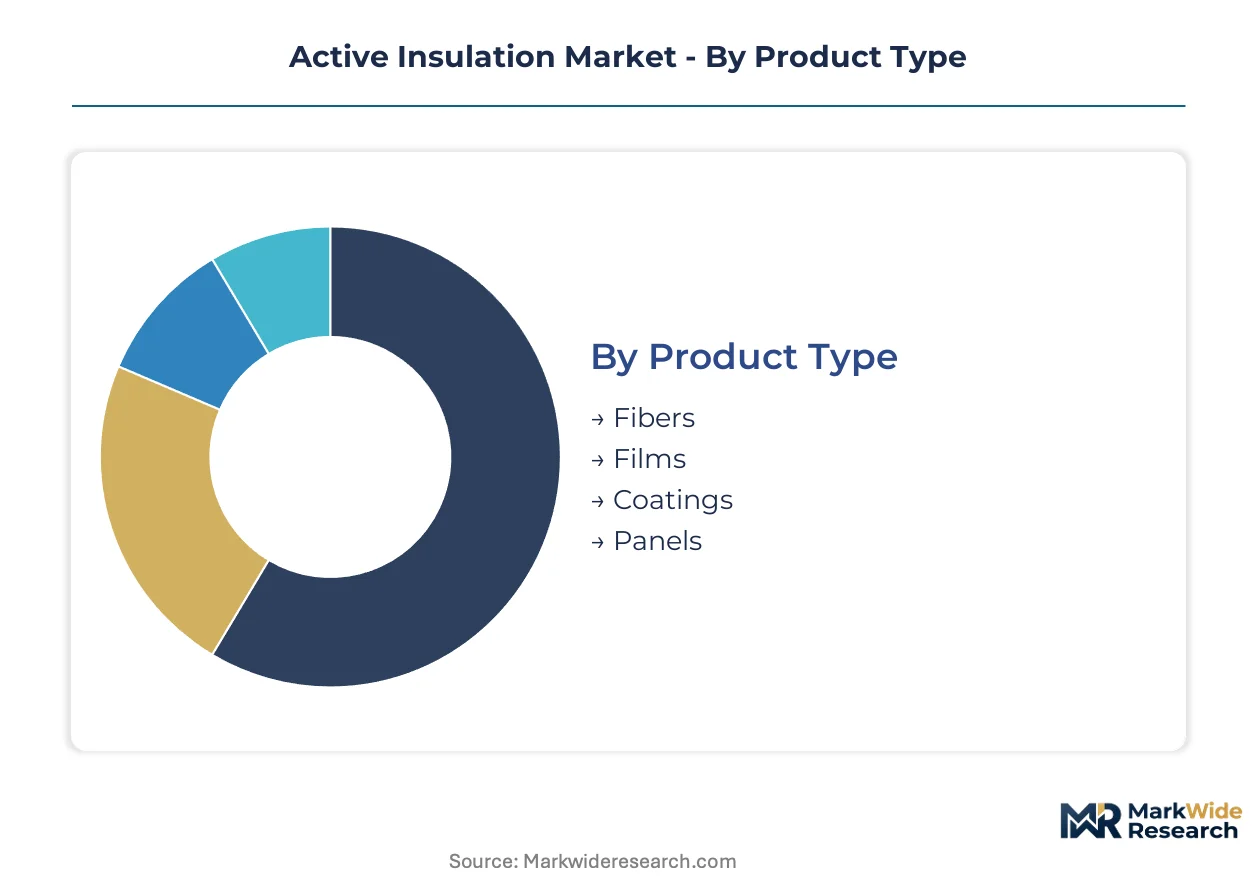
The active insulation market categorizes materials and technologies by their form, application, and underlying scientific principles. This segmentation is crucial for understanding specific performance requirements across diverse end-use sectors. Manufacturers tailor products to meet distinct demands for thermal regulation, durability, and integration into existing systems.
Product Type:
The product type segmentation reveals a spectrum from highly customized material formulations to standardized components within the active insulation market.
- Fibers:These are engineered textile components, often synthetic, designed to entrap air and incorporate active elements like microencapsulated PCMs for dynamic thermal response. Demand concentrates in performance apparel and technical workwear, driven by consumer expectations for lightweight, adaptable clothing in Europe and North America.
- Panels:Rigid or semi-rigid structures incorporating advanced insulation materials such as aerogels or vacuum insulation panels, offering superior thermal resistance in a compact form. Construction applications, particularly in Germany and China, drive demand for these panels due to stringent energy efficiency mandates.
- Films:Thin, flexible layers integrated into textiles or architectural glazing, providing thermal regulation through reflective or phase-change properties.
- Coatings:Applied as liquid or spray-on solutions to surfaces, these impart thermal management capabilities to fabrics, building envelopes, or industrial equipment.
Leading the category by volume: Fibers. Growing fastest: Panels.
End User:
End-user categories delineate distinct application environments, each with specific performance requirements for active insulation solutions.
- Construction:This sector utilizes active insulation in building envelopes, roofs, and interior walls to enhance energy efficiency and occupant comfort. Regulations like the EU Green Deal's building renovation goals and China's GB standards stimulate demand for high-performance materials.
- Apparel:Active insulation is integrated into sportswear, outdoor gear, and protective clothing to provide dynamic thermal comfort across varying activity levels and environmental conditions. Performance apparel manufacturers in the US and Germany are key demand centers.
- Automotive:Employed in vehicle interiors and battery thermal management systems to optimize cabin climate and extend electric vehicle range.
- Aerospace:Utilizes lightweight, high-performance insulation for aircraft cabins and critical component protection, where weight and thermal stability are paramount.
Construction and Apparel sectors collectively drive significant demand for active insulation materials.
Application:
The application segment distinguishes active insulation by its primary functional outcome, ranging from precise temperature maintenance to broader environmental control.
- Thermal Management:This application focuses on precisely maintaining a target temperature range within a system or environment, often critical for sensitive electronics, medical devices, or cold chain logistics. North American cold chain logistics operations increasingly adopt advanced insulation for temperature-sensitive pharmaceuticals.
- Climate Control:Encompasses broader regulation of environmental conditions, including temperature, humidity, and airflow, to ensure human comfort or optimal operational performance. Smart textile integration in Europe is leveraging active insulation for personalized climate control in garments.
- Soundproofing:Active insulation materials can also incorporate acoustic dampening properties, reducing noise transmission in building interiors or automotive cabins.
- Energy Saving:Direct application of active insulation to reduce energy consumption by minimizing heat loss or gain in buildings, industrial processes, or transport.
Thermal Management and Climate Control applications frequently overlap, offering integrated solutions.
Technology:
Technology segmentation highlights the foundational material science approaches enabling dynamic thermal regulation across the active insulation market.
- Phase Change Materials:These substances absorb and release latent heat during phase transitions (e.g., solid to liquid), providing dynamic thermal buffering to maintain comfort. Microencapsulated PCMs are widely adopted in high-performance sportswear and technical textiles across global markets.
- Aerogel:A synthetic porous ultralight material derived from a gel, where the liquid component is replaced with gas, known for its extremely low thermal conductivity. Aerogel panels find increasing use in construction and industrial insulation due to their superior performance in Germany and Japan.
- Vacuum Insulation:Panels or systems that achieve very high thermal resistance by creating a vacuum within their structure, significantly reducing heat transfer by conduction and convection.
- Air Gap Technology:Utilizes confined air layers within materials to create insulating barriers, leveraging the low thermal conductivity of still air for thermal regulation.
Phase Change Materials and Aerogel technologies are currently the focus of significant R&D investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial heartland, particularly the Rhine-Ruhr region, drives significant demand for advanced active insulation solutions. Its advanced manufacturing sector requires specialized technical textiles for automotive interiors and protective industrial apparel. This supports the market for high-performance materials.
Germany
Germany's advanced manufacturing sector requires specialized technical textiles for automotive interiors and protective industrial apparel. The EU's REACH framework influences material composition for these high-performance applications. The Rhine-Ruhr industrial cluster sees robust demand for durable, responsive insulation materials.
China
China's rapid urbanization and ambitious energy efficiency mandates stimulate demand for high-performance insulation. China's GB standards for new construction create sustained need for advanced materials like aerogel panels. The Yangtze River Delta region integrates active insulation into building envelopes and industrial equipment.
United States
United States consumers demand advanced active insulation for high-performance sportswear and outdoor gear. US EPA standards influence material choices for building applications, driving innovation in thermal management. North American cold chain logistics operations increasingly adopt advanced insulation for temperature-sensitive pharmaceuticals.
Japan
Japanese construction projects and industrial applications utilize active insulation for superior thermal management. METI initiatives encourage energy-efficient building practices, boosting demand for advanced materials. The Tokyo metropolitan area integrates vacuum insulation panels into compact building designs.
France
French construction and apparel sectors drive demand for active insulation, aligning with sustainability goals. The EU Green Deal's building renovation goals create sustained demand for high-performance insulation solutions. Paris, a fashion capital, integrates smart textile technology and active insulation into premium performance apparel.
Active Insulation Market Key Industry Players
Capital-heavy producers compete with asset-light designers, shaping the active insulation market structure. This market shows a tiered structure, with established material science firms alongside innovative textile specialists and specialized solution providers. Strategic archetypes include integrated manufacturers controlling the entire supply chain and niche innovators focusing on specific material formulations for performance apparel. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach and address diverse end-user demands.
Specialists in performance textile innovation include W.L. Gore & Associates, Inc., known for its membrane expertise in breathable fabrics. Polartec, LLC exemplifies a focus on fleece and synthetic fiber technologies that respond to body heat and external conditions. Toray Industries, Inc., a Japanese chemical engineering firm, represents a broader approach, extending its capabilities into advanced synthetic insulation fibers for diverse applications. These firms anchor the premium segment, driving material advancements and influencing product development across apparel and technical textiles. Their strategies often involve continuous R&D and collaboration with leading brands to maintain their competitive positioning in specialized markets.
| Leading Market Players |
|---|
| Owens Corning |
| PrimaLoft, Inc. |
| Armacell International S.A |
| Saint-Gobain Group |
| Rockwool International A/S |
| 3M Company |
| W.L. Gore & Associates, Inc. |
| Polartec, LLC |
| Toray Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Specialized chemical engineering expertise in Germany and Japan drives higher pricing tiers for advanced active insulation materials, while labor-cost differentials in Asian textile manufacturing influence the cost structure of volume-produced performance apparel components.
Pricing Analysis
Value-based pricing anchors premium active insulation formulations, reflecting their superior thermal regulation and durability. Price differentiation stems from material performance grade and specific regulatory certifications, such as EU REACH compliance for textile finishes. Pricing stability remains strong in high-performance niches due to continuous research and development investments. Construction sector buyers exhibit higher price sensitivity compared to specialized medical or aerospace applications.
Supply Chain Analysis
Workforce availability in advanced material science centers like Germany and Japan supports the production of high-performance aerogels and specialized PCMs. Supply concentration for base synthetic fibers primarily resides in China and Southeast Asia. Raw material dependencies include specialized polymers and microencapsulated phase change materials. Commodity price volatility for these chemical precursors presents a structural supply chain risk. Distribution largely runs through B2B channels, connecting material producers directly with textile manufacturers and construction project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The active insulation market functions as a cost-of-compliance story, where stringent regulations like the EU REACH framework create a barrier-to-entry moat for non-compliant players.
For Market Incumbents: Anchor continuous R&D into next-generation phase change materials and biomimetic fibers to counter commoditization in basic insulation segments. Invest in advanced manufacturing capacity in strategic regions to mitigate supply chain risks for critical components. Deepen vertical integration into specialized polymer production to control input costs and ensure material quality. Focus on achieving higher performance certifications to differentiate against emerging substitute technologies.
For New Entrants and Emerging Players: Smart textile integration offers a technology-first wedge into personalized climate control garments. Target underpenetrated medical applications, such as therapeutic wraps and patient transport systems, where stable temperature control is paramount. Develop localized cold chain logistics solutions in North America, leveraging advanced insulation panels for temperature-sensitive pharmaceuticals. Go-to-market strategies should emphasize performance validation and regulatory compliance for rapid adoption.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized material science firms given sustained demand from energy efficiency mandates and evolving consumer expectations. Acquisition targets should include developers of novel microencapsulated PCMs and manufacturers of high-performance aerogel panels. The signal to watch is the establishment of universally accepted dynamic thermal testing standards, which will provide clearer product comparisons and accelerate market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Next-Gen PCM Formulation | Introduces superior thermal buffering capabilities, enhancing comfort and energy efficiency in performance apparel. |
| Strategic Partnership: Automotive OEM | Integrates advanced insulation into electric vehicle battery thermal management, extending range and safety. |
| Capacity Expansion: Aerogel Panel Manufacturing | Increases availability of high-performance building insulation, supporting energy efficiency mandates in construction. |
| Green Manufacturing Transition | Addresses EU's circular economy policies and CSRD, attracting sustainability-focused consumers and investors. |
| Technology Licensing: Biomimetic Fibers | Accelerates adoption of self-regulating textiles across military and professional sports sectors for dynamic comfort. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews with material scientists, textile engineers, building code officials, and performance apparel brand managers. This approach leveraged both bottom-up and top-down triangulation to ensure comprehensive data coverage and validation across the active insulation market.
Data-stream reconciliation informed the analytical framework, modeling segmentation dimensions including product type, end-user, application, technology, and regional regulatory environments. Compound Annual Growth Rates (CAGRs) were derived through a rigorous analysis of historical market trends and projected technological advancements over the projection horizon. Key industry-specific forecast inputs included energy efficiency mandates and the pace of Phase Change Material development cycles.
Several conditions sit outside the modeled scope, including unforeseen material science breakthroughs and global geopolitical trade restrictions. Forecasts reflect assumptions regarding stable macroeconomic conditions and consistent regulatory enforcement throughout the modeling period. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Beryllium Oxide Market