
 Epoxy Thinner Market | 2026-2036
Epoxy Thinner Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Thinner Market Insights
ISO 12944 corrosion-protection certification is unwinding competitive access for suppliers without accredited coating-system portfolios. Akzo Nobel N.V. leverages its marine-certification depth to anchor premium positioning in shipyard channels. PPG Industries, Inc. sustains R&D intensity across automotive refinish formulations. BASF SE dominates bulk chemical supply chains for solvent-based thinners in European industrial coatings.
Epoxy thinner denotes a reactive diluent or solvent blend that reduces viscosity in epoxy resin systems, typically containing xylene, MIBK, or glycol ether esters to achieve application viscosities between 50 and 200 centipoise for spray or brush deployment. Its primary commercial purpose centers on enabling proper film formation in protective coatings, adhesives, and composite manufacturing where unthinned epoxy resins exhibit excessive viscosity for field application. Solvent-based formulations still occupy the largest volume share in marine and heavy-industrial settings where fast evaporation and humidity tolerance outweigh VOC concerns. Water-based alternatives are gaining structural traction in construction end uses where LEED-compliant building codes restrict solvent emissions on job sites. Bio-based variants remain niche but carry margin premiums in European markets where Ecolabel procurement specifications reward renewable content.
EPA NESHAP standards constrain hazardous air pollutant emissions from coating operations, pushing facilities toward lower-HAP thinner formulations or add-on control equipment. REACH registration requirements in Europe force continuous substance evaluation, with ECHA scrutiny on glycol ethers directly impacting formulation choices for exporters. China's MEE enforces GB standards on VOC content in architectural coatings, creating compliance thresholds for imported thinner products. Stakeholders must monitor how divergent regional solvent restrictions reshape product portfolios and determine whether localized blending capacity or reformulated universal grades offer superior route-to-market economics.
Market Dynamics
REACH compliance in Europe is tightening permissible solvent thresholds, forcing continuous reformulation of epoxy thinner portfolios and accelerating R&D cycles across coating manufacturers.
Growth Catalysts
- Marine shipyard expansion:South Korean shipyards are expanding epoxy thinner procurement for protective coatings on new vessel construction and maintenance programs.
- Infrastructure build-out:China's bridge and industrial facility construction drives coating consumption, concentrating demand for high-performance epoxy systems.
- ISO 12944 certification requirements:Corrosion-protection certification is unwinding competitive access for suppliers without accredited coating-system portfolios.
Market Restraints
- Xylene price volatility:Aromatic solvent feedstock costs fluctuate with crude oil indices, compressing formulation margins for commodity-grade thinners.
- Supply concentration in European bulk chemicals:BASF SE dominates solvent-based thinner supply chains, creating dependency risk for regional formulators.
- VOC substitution pressure:Water-based alternatives are gaining structural traction in construction end uses where LEED-compliant building codes restrict solvent emissions.
Strategic Opportunities
- Bio-based formulation white space:European Ecolabel procurement specifications reward renewable content, carrying margin premiums for qualified products.
- Water-based technology convergence:Hybrid waterborne-epoxy systems are opening construction applications previously closed to solvent-based products.
- Automotive refinish channel innovation:PPG Industries sustains R&D intensity across automotive refinish formulations, signaling channel-specific growth potential.
Industry Challenges
- Reformulation timeline compression:ECHA scrutiny on glycol ethers forces rapid substance evaluation, straining product development cycles for exporters.
- Certification portfolio gaps:ISO 12944 corrosion-protection standards require accredited coating-system portfolios that smaller suppliers lack resources to assemble.
- Regional regulatory divergence:EPA NESHAP standards, REACH requirements, and China's GB standards create fragmented compliance obligations for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Thinner Market |
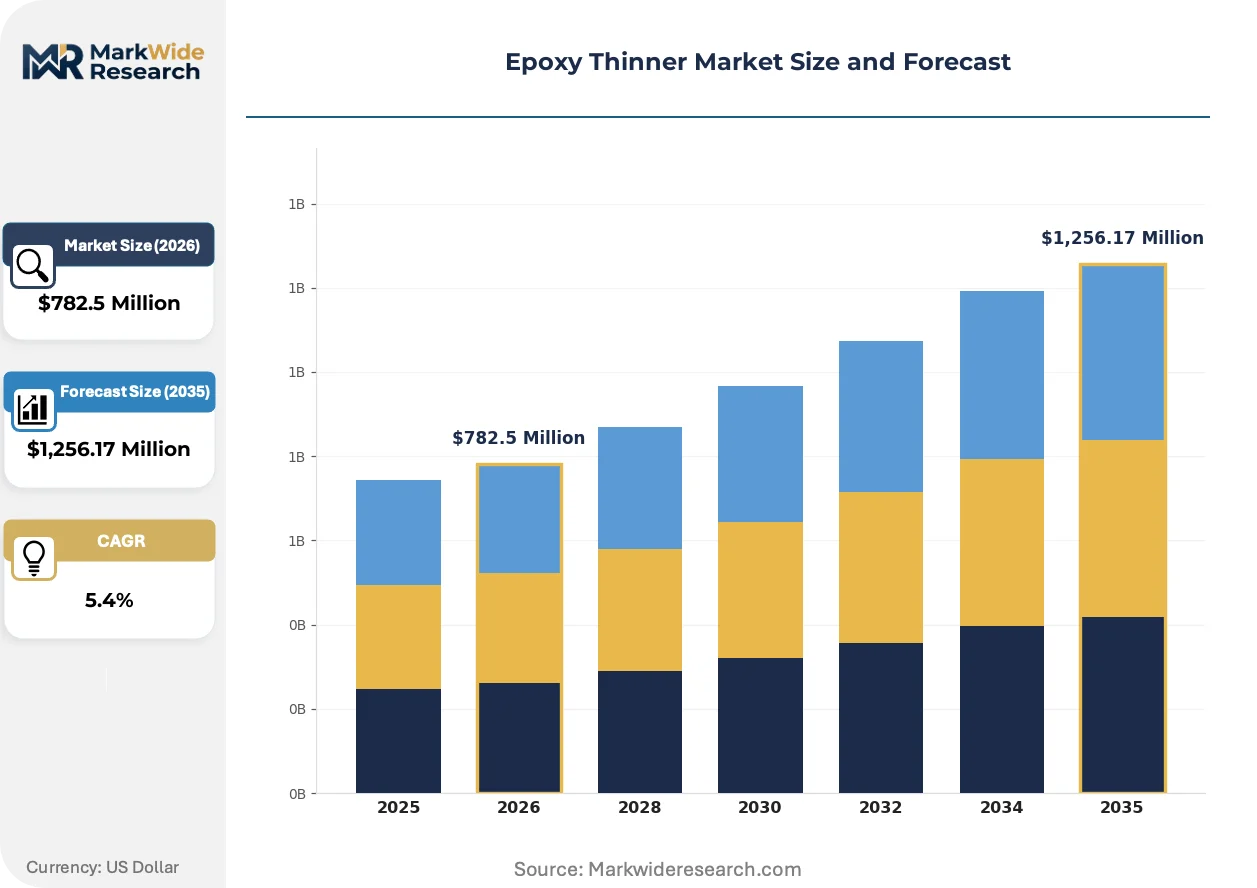
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,256.17 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solvent-Based, Water-Based, Bio-Based, Others Application: Coating, Adhesive, Flooring, Composite End User: Construction, Automotive, Aerospace, Marine Packaging Type: Drum, Can, Bottle, Bulk |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, BASF SE, Axalta Coating Systems Ltd., Hempel A/S, Jotun Group, RPM International Inc., Nippon Paint Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Thinner Market Trends and Innovations
Formulation chemistry and regulatory compliance are actively reshaping competitive positioning in epoxy thinners, with solvent substitution and certification requirements driving portfolio restructuring across marine, industrial, and construction end uses.
Waterborne epoxy thinner technology is displacing solvent-based formulations in construction applications where humidity tolerance is less critical than VOC compliance. LEED-compliant building codes in North American and European markets are accelerating adoption among general contractors and facility managers. This displacement is compressing addressable volume for traditional xylene and MIBK blends in architectural coatings.
REACH registration requirements in Europe force continuous substance evaluation, with ECHA scrutiny on glycol ethers directly impacting formulation choices for exporters. Industrial coating facilities must maintain reformulation flexibility or absorb add-on control equipment costs. Marine and heavy-industrial segments in Germany, Netherlands, and Belgium face the most acute compliance pressure due to concentrated manufacturing bases.
Marine-certification depth is reshaping procurement patterns in shipyard channels. Akzo Nobel N.V. leverages its accredited portfolio to anchor premium positioning, while buyers consolidate supplier relationships to reduce qualification overhead. This concentration is most visible in South Korean and Chinese shipbuilding clusters where ISO 12944 compliance is mandatory for protective coating specifications.
Epoxy Thinner Market Segmentation
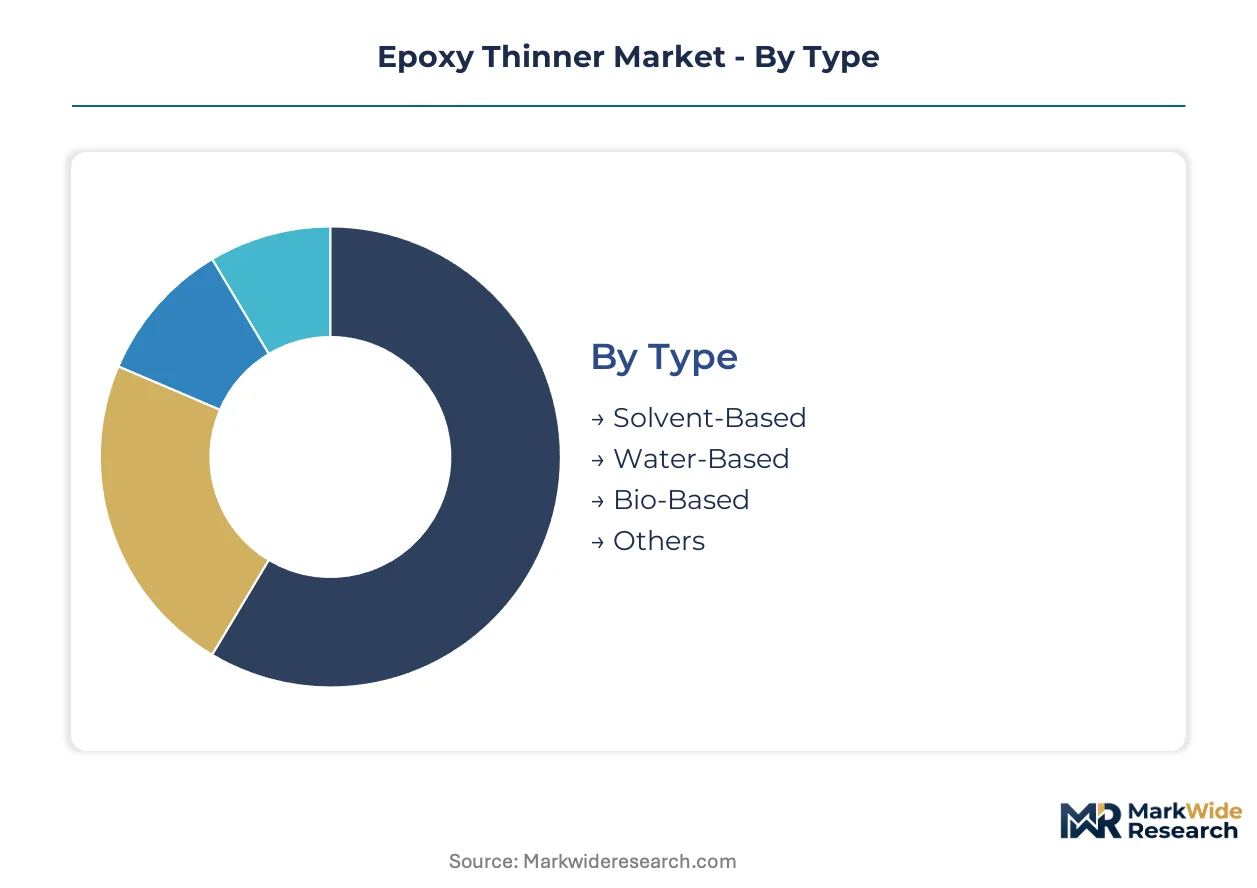
Epoxy thinner segmentation reveals how formulation chemistry, application requirements, and logistics economics create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure that reshape supplier priorities across marine, industrial, and construction channels.
Type:
Domestic production concentrates solvent-based formulations in South Korea and China where shipyard demand anchors volume. Export-led segments face REACH-driven reformulation cycles in European markets.
- Solvent-Based:Xylene and MIBK blends dominate marine and heavy-industrial applications where fast evaporation rates and humidity tolerance outweigh VOC constraints. South Korean shipyards anchor procurement volume for protective coatings on new vessel construction.
- Water-Based:Hybrid waterborne-epoxy systems displace solvent alternatives in North American and European construction where LEED-compliant building codes restrict on-site emissions. General contractors drive specification shifts in commercial flooring and architectural coatings.
- Bio-Based:Renewable-content formulations carry margin premiums in EU markets where Ecolabel procurement specifications reward sustainable chemistry.
- Others:Reactive diluents and specialty glycol ether esters serve niche composite manufacturing and high-performance adhesive applications.
Solvent-based formulations command the established base. The steepest expansion runs through water-based technology as construction codes tighten.
Application:
Cost tiering separates commodity protective coatings from premium adhesive and composite systems where specification control drives pricing power.
- Coating:Protective coatings for bridges, industrial facilities, and marine structures generate the largest absolute volume. China's infrastructure build-out concentrates demand for high-performance epoxy systems with ISO 12944 corrosion-protection certification.
- Adhesive:Structural bonding applications in automotive and aerospace require precise viscosity control for automated dispensing equipment. Formulation margins exceed coating grades due to performance-critical specifications.
- Flooring:Self-leveling epoxy systems for commercial and industrial facilities favor water-based thinners where indoor air quality regulations apply.
- Composite:Wind turbine blade manufacturing and aerospace components utilize low-volatility reactive diluents for vacuum infusion processes.
Coating applications absorb the highest volume throughput. Composite applications gain share fastest as renewable energy manufacturing scales.
End User:
Customer type determines whether procurement flows through specification-driven engineering channels or price-sensitive contractor networks.
- Construction:General contractors and facility managers prioritize VOC compliance over performance margins in architectural applications. LEED certification requirements reshape thinner specification across North American commercial projects.
- Automotive:Refinish shops and OEM coating lines demand consistent viscosity control for spray application equipment. PPG Industries sustains R&D intensity across this channel.
- Aerospace:MRO facilities and OEM manufacturers require qualified materials with full traceability and certification documentation.
- Marine:Shipyards in South Korea and China consolidate supplier relationships to reduce qualification overhead for ISO 12944-compliant protective systems.
Construction end users generate the broadest geographic dispersion. Marine channels concentrate procurement most tightly around certified suppliers.
Packaging Type:
Volume scale and supply chain configuration determine whether bulk delivery or unitized packaging captures route-to-market economics.
- Drum:Standard 200-liter steel drums serve industrial coating facilities and mid-tier formulators with predictable consumption patterns. European industrial coatings rely heavily on drum logistics from BASF SE bulk chemical supply chains.
- Can:Smaller metal cans target automotive refinish shops and specialty adhesive manufacturers requiring frequent product rotation.
- Bottle:Retail-sized containers reach DIY consumers and small-scale maintenance contractors through distribution networks.
- Bulk:Tanker and tote deliveries serve large shipyard operations and integrated coating manufacturers with captive blending capacity. South Korean marine clusters favor bulk procurement for cost efficiency at scale.
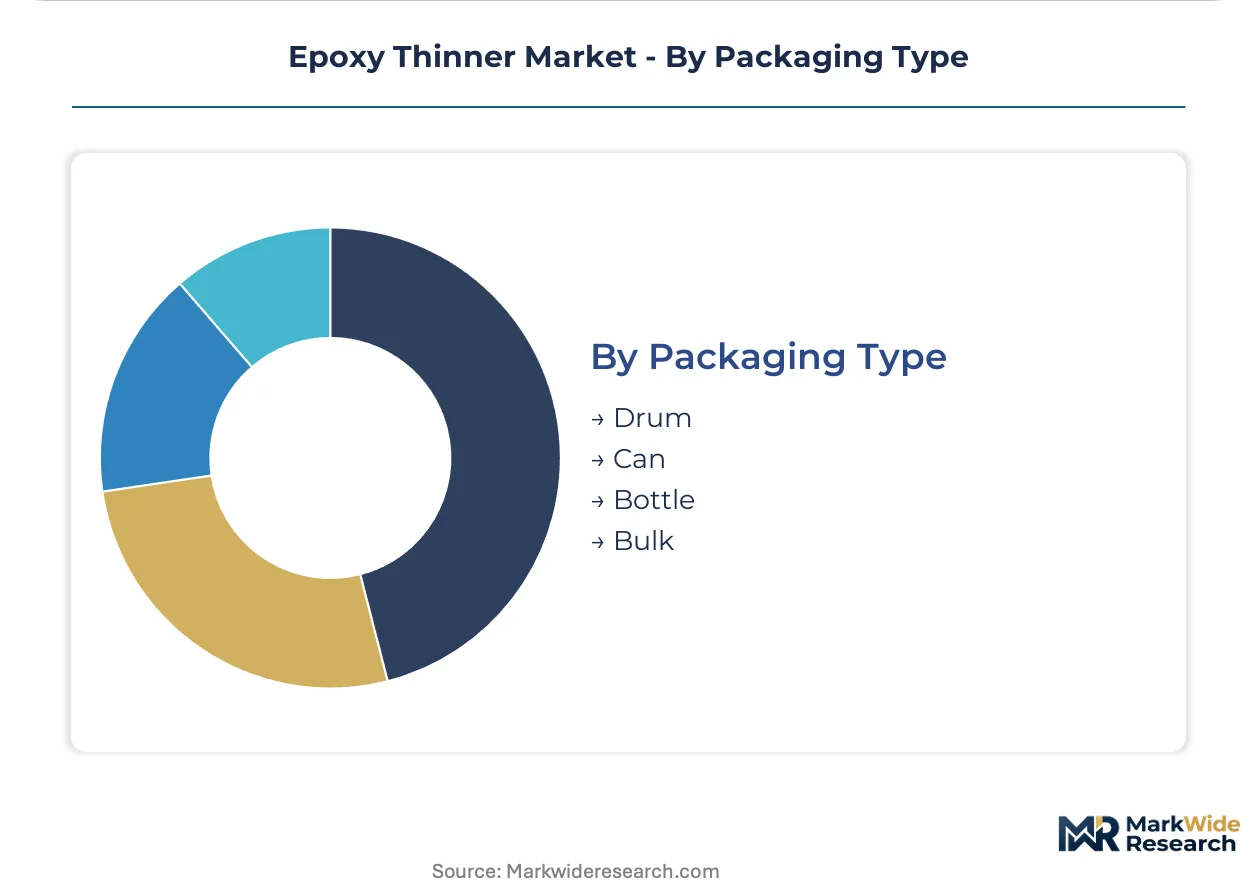
Drum packaging retains the largest installed base. Bulk delivery posts the steepest volume climb as shipyard consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Busan-Ulsan maritime corridor underwrites South Korea's commanding position in marine-grade epoxy thinner consumption. Shipyard clusters along this coastline anchor procurement volume for ISO 12944-certified protective systems.
South Korea
DSME and HHI shipyards drive concentrated demand for xylene-based thinners in new vessel construction. MEE-aligned environmental protocols influence formulation specifications for export-bound coatings. The Busan-Ulsan corridor hosts integrated supply chains where bulk thinner deliveries feed directly into shipyard paint shops.
China
Bridge construction across the Yangtze River Delta and industrial facility expansion in Shandong Province generate coating demand. GB standards on VOC content enforce compliance thresholds for architectural applications. The Pearl River Delta manufacturing belt concentrates water-based thinner production for LEED-aspiring construction projects.
Germany
Industrial coatings for automotive and machinery applications sustain solvent-based thinner demand despite substitution pressure. REACH registration requirements force continuous substance evaluation for glycol ether formulations. The Ruhr industrial basin and Bavarian chemical corridors house reformulation laboratories serving pan-European coating manufacturers.
United States
Commercial flooring and automotive refinish channels absorb waterborne epoxy thinner volumes. EPA NESHAP standards constrain hazardous air pollutant emissions from coating operations. Gulf Coast petrochemical infrastructure supplies aromatic feedstocks to regional formulators serving marine and industrial end users.
Netherlands
Rotterdam port logistics and North Sea offshore maintenance programs sustain marine coating demand. ECHA scrutiny on solvent classifications accelerates portfolio restructuring for exporters. The Rotterdam-Antwerp chemical cluster concentrates blending capacity for REACH-compliant thinner formulations.
Epoxy Thinner Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage. The vendor base separates into three tiers: integrated chemical conglomerates with captive solvent supply, coating specialists with marine-certification portfolios, and regional formulators serving contractor networks. Strategic moves concentrate on portfolio diversification into water-based technologies and geographic expansion through distribution partnerships in Asian shipyard clusters.
Among European-based chemical conglomerates, BASF SE anchors bulk supply chain positioning for solvent-based thinners. Akzo Nobel N.V. and PPG Industries, Inc. represent contrasting archetypes: the former exemplifies marine-certification depth for shipyard channels, while the latter occupies a position in automotive refinish innovation. These three entities collectively illustrate how certification assets, R&D intensity, and supply chain control differentiate competitive positioning across end-use verticals.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems Ltd. |
| Hempel A/S |
| Jotun Group |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between South Korean shipyards and solvent suppliers lock in feedstock access while anchoring price visibility for xylene and MIBK blends across volatile crude oil cycles. These arrangements insulate marine coating channels from spot market swings while compressing margin flexibility for formulators serving spot-buying construction contractors.
Pricing Analysis
Volume-discount tiering separates bulk procurement by South Korean and Chinese shipyards from drum-lot purchases by mid-tier industrial formulators. Pricing stratifies across ISO 12944-certified premium grades, standard industrial formulations, and economy-grade architectural thinners. Cost compression in commodity solvent blends is intensifying because xylene feedstock costs fluctuate with crude oil indices. Construction contractors exhibit the highest price sensitivity, while marine shipyards prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory cycles for aromatic solvents extend lead times when Rotterdam-Antwerp chemical clusters face REACH-driven reformulation backlogs. Manufacturing concentrates in Germany, South Korea, and China, with BASF SE anchoring European bulk supply. Feedstock chains draw from Gulf Coast petrochemical infrastructure and Middle Eastern crude derivatives. Single-source vulnerability runs through concentrated glycol ether suppliers facing ECHA scrutiny. Distribution feeds from integrated chemical complexes to shipyard clusters and regional blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as waterborne epoxy technology penetrates construction applications previously closed to solvent systems, with LEED-compliant building codes accelerating specification shifts across North American commercial projects.
For Market Incumbents: Compound certification depth in marine channels to defend against water-based substitution pressure in construction end uses. Pursue backward integration into captive solvent production in South Korea to secure feedstock access against xylene price volatility. Anchor premium positioning through ISO 12944 portfolio expansion rather than commodity volume competition. For New Entrants and Emerging Players: ISO 12944 certification fast-track offers the most penetrable entry path into South Korean shipyard supply chains where incumbent qualification overhead creates procurement consolidation. Target water-based formulation white space in European construction where Ecolabel procurement specifications reward renewable content. Lead with LEED-compliant product positioning to bypass entrenched solvent-based distribution relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulators with marine-certification assets and water-based technology pipelines rather than commodity solvent traders. Long-term viability favors suppliers with dual competence across solvent-based marine systems and waterborne construction formulations. Watch ECHA substance evaluation timelines as inflection indicators for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Feedstock Supply | BASF SE's captive supply chains demonstrate how upstream control insulates margins from crude oil volatility. |
| Water-Based Formulation Platform Expansion | PPG Industries sustains R&D intensity across automotive refinish channels where VOC compliance reshapes procurement. |
| ISO 12944 Certification Portfolio Buildout | Akzo Nobel N.V. leverages marine-certification depth to anchor premium positioning in South Korean shipyard channels. |
| Long-Term Supply Agreement with Shipyard Clusters | DSME and HHI procurement consolidation favors suppliers with bulk delivery capacity and accredited coating systems. |
| Bio-Based Chemistry R&D Investment | European Ecolabel procurement specifications reward renewable content, carrying margin premiums for qualified products. |
Research Methodology
A standing panel of coating formulators, shipyard procurement managers, chemical distribution channel partners, and REACH compliance consultants provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews captured demand patterns from marine, construction, and automotive end users while customs data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases furnished secondary benchmarks. Bottom-up volume builds across formulation types triangulated against top-down chemical consumption estimates.
Consistency checks validated model outputs against external trade flow data and regional production capacity disclosures. Segmentation modeling spanned formulation chemistry, application requirements, end-user procurement patterns, and packaging logistics across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure spending trajectories, shipyard order backlogs, and regulatory phase-in schedules. Feedstock cost indices and certification adoption curves served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory phase-in assumptions and continued shipyard demand concentration; material deviation in REACH enforcement intensity or crude oil volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Aromatic Solvents Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Organic Solvents Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Isopropylamine Market
Solvents
Acetone Derivatives Market
Solvents
Global Solvent Dyes Market
Solvents
Aprotic Solvents Market
Solvents
Europe Acetonitrile Market
Solvents
Chlorobenzene Market
Solvents
Asia-Pacific Ethane Market
Solvents
Mixed Xylene Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Global Solvent Evaporation Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Benzyl Alcohol Market