
 USA and Canada Copper Market | 2026-2036
USA and Canada Copper Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Copper Market Analytics
Aftermarket service revenue from smelter maintenance and refining optimization is narrowing as primary producers bring technical capabilities in-house. Freeport-McMoRan Inc. leverages its integrated North American asset base to control concentrate-to-cathode margins. Hudbay Minerals anchors its position through underground mining specialization in Manitoba and Arizona. Southern Copper Corporation competes on large-scale open-pit economics that sustain cost leadership across the Americas.
USA and Canada copper encompasses refined metal and semi-fabricated products with minimum purity of 99.90% cathode, produced through pyrometallurgical smelting, solvent extraction-electrowinning, or electrolytic refining for electrical conductivity exceeding 100% IACS. Copper wire dominates product type value capture due to grid infrastructure and electric vehicle charging deployment. Rod and tube forms attract premium pricing from plumbing and HVAC specification lock-ins. Recycling technology is gaining share as scrap-fed cathode production displaces energy-intensive primary smelting in regional supply balances.
EPA effluent guidelines and Canadian Environmental Protection Act standards shape extraction permitting timelines and water management capital requirements. OSHA mine safety enforcement and provincial tailings regulations in British Columbia, Ontario, and Arizona dictate operational compliance costs for underground and open-pit developers. Stakeholders must monitor how carbon border adjustments and clean electricity procurement standards redefine smelter power sourcing decisions across both jurisdictions.
Market Dynamics
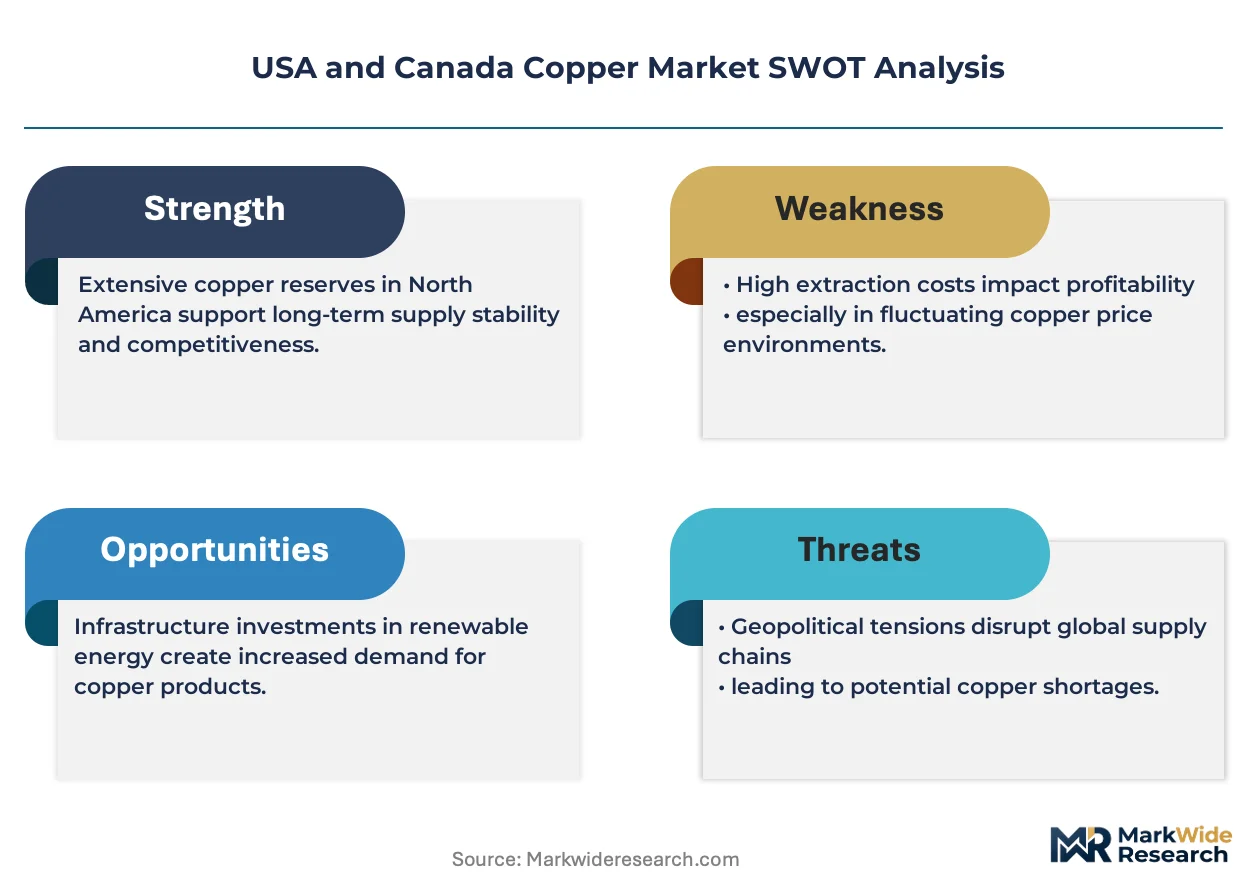
Electrical grid modernization across the USA and Canada is compressing copper procurement timelines while EPA effluent standards and Canadian tailings regulations are extending mine permitting cycles, creating structural tension between demand acceleration and supply elasticity.
Growth Catalysts
- Grid hardening mandates:FERC transmission reliability orders and provincial clean electricity standards in Ontario and British Columbia are accelerating utility-scale copper wire procurement for substation upgrades and intertie expansion.
- EV charging infrastructure:The IRA's alternative fuel vehicle refueling property credit and Canada's Zero Emission Vehicle Infrastructure Program are driving copper conductor demand for DC fast-charging station deployment across interstate corridors and Trans-Canada Highway nodes.
- Scrap-fed cathode technology:Secondary smelting advances in Arizona and Quebec are displacing energy-intensive primary production, tightening regional supply balances and reducing import dependency for refined metal.
Market Restraints
- Sulfuric acid input volatility:Solvent extraction-electrowinning operations in Arizona and Nevada face margin compression from acid spot price swings tied to phosphate fertilizer and industrial chemical demand cycles.
- Permitting timeline extension:EPA's updated mining effluent guidelines and British Columbia's tailings storage facility regulations are stretching project development horizons for greenfield porphyry deposits in the Highland Valley and Yukon.
- Aluminum conductor substitution:Transmission planners in cost-constrained Midwest ISO zones are specifying ACSS and ACAR overhead lines for non-critical grid segments, displacing copper in select voltage classes.
Strategic Opportunities
- Manitoba underground expansion:The Flin Flon-Snow Lake belt offers untapped volcanogenic massive sulfide potential with existing rail and hydropower infrastructure reducing development capital intensity.
- Building electrification codes:California's Title 24 and Vancouver's zero-emissions building plan are mandating heat pump and EV-ready wiring that elevates copper intensity per residential unit above legacy construction standards.
- Direct cathode-to-rod integration:Proximity smelting and continuous casting investments in the Arizona copper corridor are compressing logistics costs and capturing premium pricing from Southwestern wire and cable fabricators.
Industry Challenges
- Underground mining automation talent:Remote mucking and automated haulage deployment in Manitoba and Arizona operations require mechatronics and data science competencies that outpace regional vocational pipeline output.
- Tailings dam engineering certification:British Columbia's Dam Safety Regulation and Global Industry Standard on Tailings Management compliance are extending qualified engineer sign-off timelines for facility expansions and raising professional liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Copper Market |
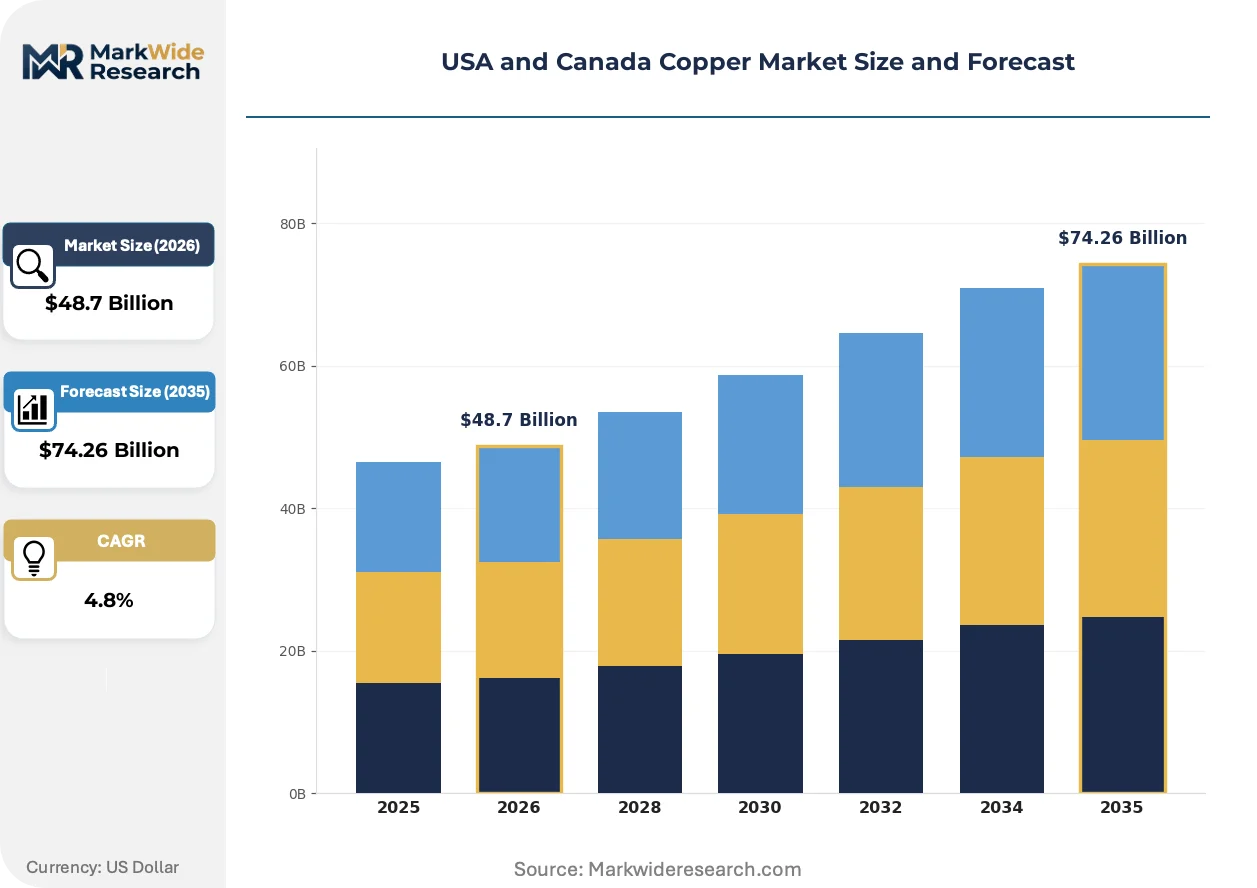
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Wire, Copper Pipe, Copper Sheet, Copper Alloy End User: Electrical, Plumbing, Construction, Electronics Form: Rod, Tube, Foil, Plate Technology: Smelting, Refining, Electrolysis, Recycling |
| Companies Covered | Freeport-McMoRan Inc., Hudbay Minerals, Southern Copper Corporation, Taseko Mines, Excelsior Mining, Faraday Copper, Western Copper and Gold, Glencore, KGHM Polska Miedz SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Copper Market Evolving Landscape
Process metallurgy and power systems engineering are converging to reshape how copper moves from ore to conductor, with regulatory pressure and procurement rationalization acting as twin accelerants of technical change.
Continuous casting and rolling technology is migrating from batch ingot-based production to direct feed from solvent extraction-electrowinning tankhouses. Southwestern wire mills and rod producers are retrofitting SCR and Properzi lines to accept cathode bundles without intermediate melting, cutting energy consumption and lead times. This shift is compressing the traditional merchant cathode spot market as captive integration deepens.
EPA's updated Effluent Limitations Guidelines and Standards for the Copper and Lead-Zinc Mining Point Source Category are forcing Arizona and Nevada heap leach operations to install zero liquid discharge systems and constructed wetlands. Water management capital now rivals extraction equipment in project economics, with operators in the Sonoran Desert prioritizing closed-loop circuit designs to secure National Pollutant Discharge Elimination System permits.
Utility procurement is consolidating around long-term cathode offtake agreements with embedded price collars. Investor-owned utilities in ERCOT and CAISO zones are bypassing merchant metal markets entirely, contracting directly with Arizona smelters for 5-7 year rod supply schedules indexed to COMEX with volume floors. This behavior is most visible in Texas and California, where transmission buildout timelines require supply certainty that spot markets cannot provide.
USA and Canada Copper Market Segmentation
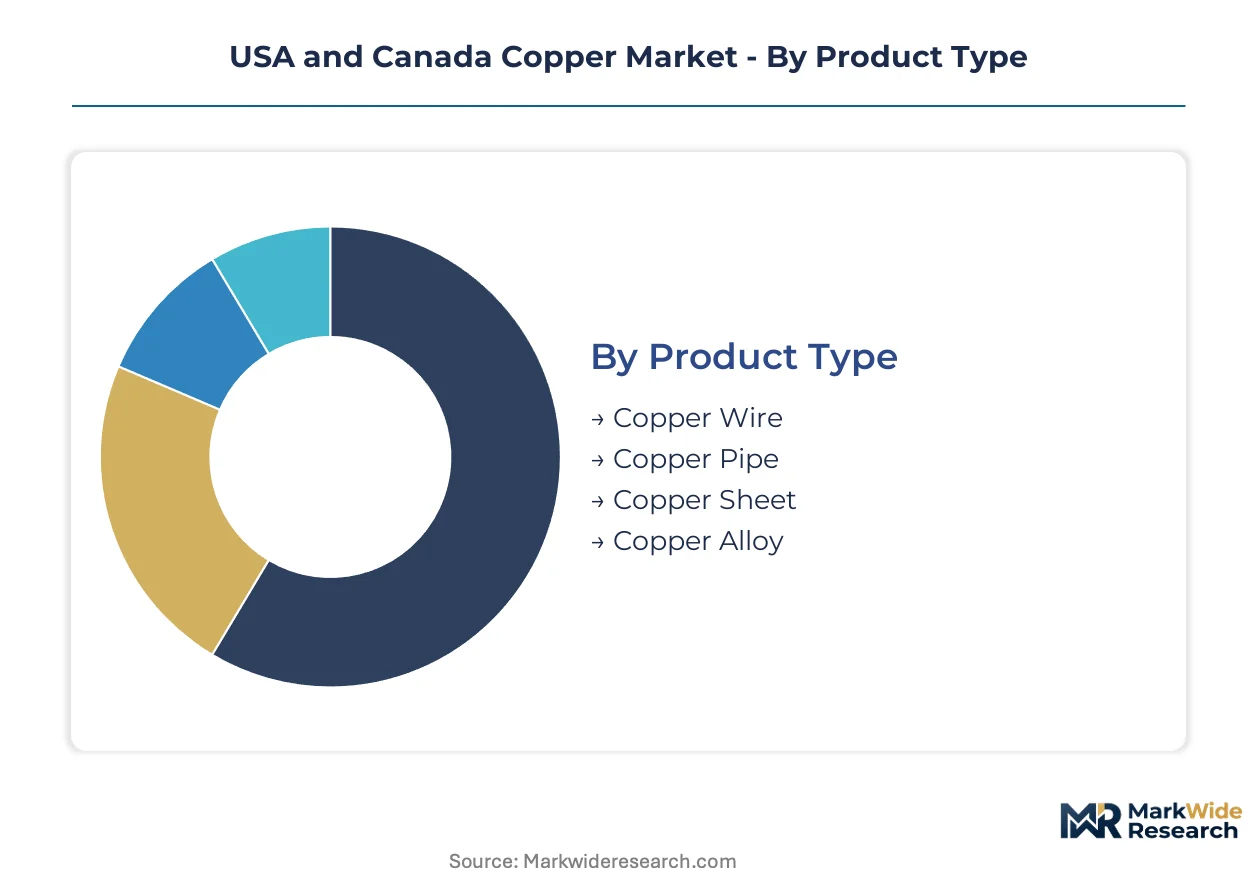
Segmentation reveals how copper value migrates through distinct technical specifications and procurement channels. Product form, end-use application, and processing technology each create separate margin pools with divergent competitive dynamics.
Product Type:
After-sales service intensity varies sharply across product categories, with wire and alloy products demanding ongoing technical support for specification compliance while pipe and sheet operate on commodity procurement cycles.
- Copper Wire:Electrical-grade conductor manufactured to ASTM B3 and B8 standards with annealed or hard-drawn temper for conductivity exceeding 100% IACS. Demand concentrates in Arizona and Texas utility corridors where ERCOT and CAISO transmission buildouts require continuous cathode-to-rod supply integration. FERC reliability mandates compress procurement timelines and elevate just-in-service inventory requirements.
- Copper Alloy:Brass and bronze formulations with controlled zinc, tin, or nickel additions for machinability and corrosion resistance. Demand concentrates in Ontario automotive stampings and British Columbia marine hardware where specification lock-ins create multi-year contract structures. Canadian Environmental Protection Act substance restrictions shape alloying element selection.
- Copper Pipe:Seamless tube meeting ASTM B88 for potable water and HVAC refrigerant lines. Residential construction in California and Vancouver drives type L and K specification uptake under Title 24 electrification codes.
- Copper Sheet:Cold-rolled plate and coil for architectural cladding and industrial equipment fabrication. Commercial building retrofits in Toronto and Chicago specify C11000 grade for patina performance and LEED compliance.
By volume, Copper Wire leads. By expansion trajectory, Copper Alloy is climbing fastest.
End User:
Cost tier stratification separates premium-specification electrical and electronics buyers from price-sensitive construction and plumbing procurement.
- Electrical:Utility-scale transmission developers and EV charging infrastructure deployers specifying ASTM B3 bare conductor and NEMA WC5 insulated cable. IRA alternative fuel vehicle refueling credits accelerate DC fast-charging station deployment across Interstate corridors and Trans-Canada Highway nodes.
- Electronics:Semiconductor packaging and printed circuit board fabricators demanding oxygen-free high-conductivity copper with sub-5 ppm impurity thresholds. Arizona and California cleanroom facilities drive ultra-pure cathode procurement.
- Construction:General contractors and mechanical subcontractors procuring standard-grade pipe and sheet for commercial and residential building envelopes. Vancouver zero-emissions building mandates elevate copper intensity per housing unit.
- Plumbing:Wholesale distributors and mechanical contractors sourcing type L, M, and DWV tube for potable water and drainage systems. California plumbing code updates restrict lead content in soldered joints.
Electrical commands the largest revenue pool. Electronics exhibits the steepest margin expansion.
Form:
Volume concentration in rod and tube reflects continuous casting investment patterns, while foil and plate serve fragmented specialty applications.
- Rod:Continuous cast and rolled feedstock for wire drawing mills. Southwestern fabricators in Arizona and Nevada capture logistics savings from proximity smelting integration.
- Tube:Extruded and drawn seamless pipe for plumbing, HVAC, and industrial heat exchange. Ontario and British Columbia distributors maintain specification-differentiated inventory positions.
- Foil:Cold-rolled thin strip for lithium-ion battery current collectors and flexible electronics. Limited domestic capacity creates import dependency for sub-50 micron gauges.
- Plate:Hot-rolled thick sections for electrical busbar and industrial equipment. Transformer manufacturers in Quebec and Wisconsin specify edge-conditioned plate for core winding applications.
Rod dominates tonnage. Foil is gaining share fastest in value terms.
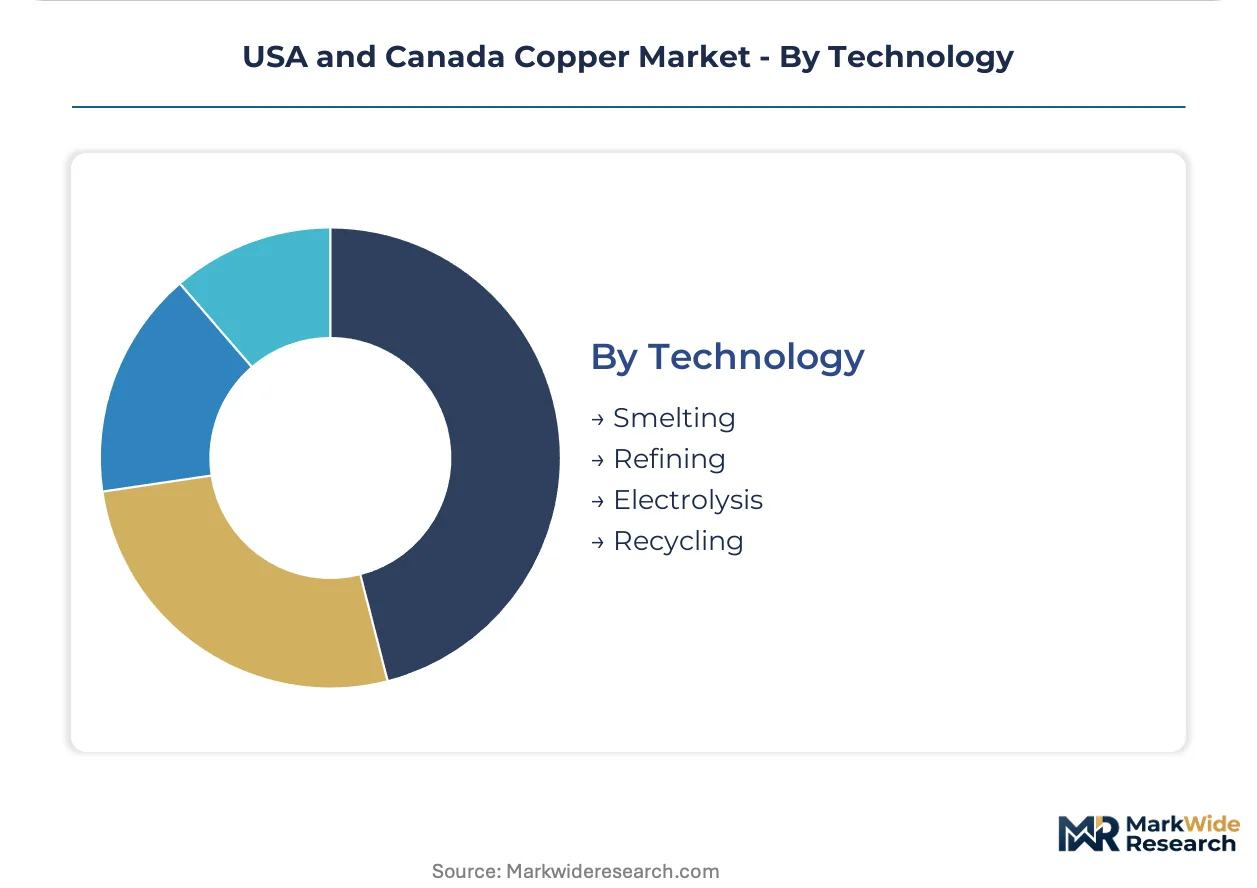
Technology:
Margin structure separates energy-intensive primary processing from scrap-fed secondary routes with divergent carbon intensity profiles.
- Smelting:Pyrometallurgical concentrate processing in flash and bath furnaces. Arizona operations face EPA effluent guideline compliance costs for sulfur capture and acid plant integration.
- Recycling:Scrap-fed cathode production via secondary smelting and fire refining. Quebec and Arizona facilities displace primary metal with lower-emission feedstock.
- Refining:Fire and electrolytic purification to 99.99% cathode grade. British Columbia and Ontario refineries serve regional rod mill demand.
- Electrolysis:Solvent extraction-electrowinning for oxide ore processing. Nevada and Arizona heap leach operations confront sulfuric acid input cost volatility.
Smelting retains volume leadership. Recycling is expanding most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper extraction and refining capacity clusters in the southwestern United States and western Canadian provinces, with infrastructure buildout and regulatory frameworks creating divergent investment conditions across sub-regional markets.
Arizona
Utility-scale transmission projects from ERCOT and CAISO interconnects drive cathode procurement acceleration. EPA effluent guidelines under the Clean Water Act mandate zero liquid discharge systems for heap leach operations. The Morenci-Safford corridor hosts integrated smelter-rod mill complexes serving Southwestern wire fabricators.
British Columbia
Highland Valley porphyry deposits supply concentrate to Pacific Rim smelters amid Asian demand pull. Provincial Dam Safety Regulation and Global Industry Standard on Tailings Management compliance extend facility expansion timelines. Vancouver serves as the corporate headquarters cluster for junior exploration firms targeting Yukon and Northwest Territories extensions.
Ontario
Automotive electrification programs from Detroit Three OEMs elevate alloy demand for stamping and busbar applications. Canadian Environmental Protection Act substance restrictions shape alloying element selection for brass and bronze formulations. Sudbury Basin legacy infrastructure supports nickel-copper co-production with hydropower-fed refining capacity.
Manitoba
Flin Flon-Snow Lake volcanogenic massive sulfide belts offer untapped underground potential with existing rail and Manitoba Hydro infrastructure. Provincial mine closure and reclamation regulations govern development sequencing for new shaft operations. Snow Lake anchors Hudbay Minerals' copper-zinc production with automated haulage deployment.
Quebec
Scrap-fed secondary smelting advances displace primary metal in regional supply balances. Hydro-Québec clean electricity procurement standards favor low-carbon cathode production for Northeastern US export. Rouyn-Noranda refining complex processes concentrate from Abitibi-Témiscamingue mining camps.
USA and Canada Copper Market Competitive Landscape
Integrated majors and pure-play developers split the market into distinct capability tiers. Concentration remains moderate with asset-specific advantages determining regional share rather than scale economies alone. Two archetypes dominate: vertically integrated producers controlling concentrate-to-cathode margins, and development-stage specialists advancing greenfield porphyry deposits through permitting cycles. Competitive moves center on captive power arrangements and direct offtake contracting with utilities bypassing merchant metal markets.
Within the integrated producer tier, Freeport-McMoRan Inc. and Southern Copper Corporation exemplify scale-driven positioning across North American smelting and refining assets. Among development specialists, Hudbay Minerals occupies a position anchored in Manitoba underground expertise with Arizona expansion exposure. Taseko Mines and Excelsior Mining represent the junior developer archetype advancing southwestern porphyry and in-situ recovery projects through extended permitting timelines.
| Leading Market Players |
|---|
| Freeport-McMoRan Inc. |
| Hudbay Minerals |
| Southern Copper Corporation |
| Taseko Mines |
| Excelsior Mining |
| Faraday Copper |
| Western Copper and Gold |
| Glencore |
| KGHM Polska Miedz SA |
| Others |
Value Network & Pricing Analysis
The Arizona copper corridor concentrates solvent extraction-electrowinning capacity that feeds directly into Southwestern rod mills, compressing logistics costs and amplifying pricing power for integrated producers against merchant cathode spot markets. EPA effluent guideline compliance costs and sulfuric acid input volatility create divergent margin structures between captive utility offtake agreements and speculative trading positions.
Pricing Analysis
IRA clean electricity procurement standards and FERC transmission reliability orders dictate the pricing tier structure across contract-based long-term offtake agreements. Premium-mid-economy pricing differentiation separates utility-scale direct cathode contracts with volume floors from speculative merchant spot transactions and scrap-fed secondary supply. Cost compression in standard-grade rod supply is intensifying because aluminum ACSS conductor substitution in Midwest ISO transmission planning displaces copper in non-critical voltage classes. Wholesale distributors and mechanical contractors in plumbing procurement exhibit highest price sensitivity, while semiconductor packaging fabricators demanding oxygen-free high-conductivity copper show lowest elasticity due to specification lock-ins.
Supply Chain Analysis
Export-control scrutiny on mining automation technology and heap leach process equipment limits flows of remote mucking systems and automated haulage components into Arizona and Nevada operations. Geographic supply concentration centers on the USA, Canada, and Chile for concentrate feedstock, with British Columbia's Highland Valley district and Arizona's Morenci-Safford corridor anchoring North American refining capacity. Raw material dependencies rest on sulfuric acid for leaching operations, metallurgical coal for smelting reduction, and diesel fuel for haulage fleets. Single-source vulnerability concentrates in qualified tailings dam engineering certification under British Columbia's Dam Safety Regulation. Distribution runs through direct cathode-to-rod integration at Southwestern wire mills bypassing traditional merchant metal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum conductor substitution in cost-constrained transmission planning threatens copper intensity per grid dollar invested, forcing incumbents to defend specification standards through electrification code mandates and premium conductivity positioning.
For Market Incumbents: Entrench captive power arrangements with Hydro-Québec and Arizona Public Service to lock in low-carbon smelting economics against carbon border adjustment exposure. Deepen backward integration into Manitoba underground mining automation to offset mechatronics talent scarcity threatening Flin Flon-Snow Lake expansion timelines. Defend specification lock-ins in Ontario automotive stamping and British Columbia marine hardware against brass alloy competitors. For New Entrants and Emerging Players: Establish a beachhead in Quebec scrap-fed secondary smelting where clean electricity procurement standards favor low-carbon cathode production for Northeastern US export. Target Yukon and Northwest Territories greenfield porphyry exploration through Vancouver corporate headquarters clustering to access junior financing networks. Penetrate via direct offtake contracting with ERCOT and CAISO transmission developers requiring supply certainty that spot markets cannot provide. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors development-stage specialists advancing automated underground operations through extended permitting timelines rather than mature open-pit assets facing grade decline. Long-term viability across the analysis window hinges on water management capital efficiency under EPA zero liquid discharge mandates and tailings storage facility compliance costs. Acquisition target archetype: Manitoba underground specialists with existing rail and hydropower infrastructure reducing development capital intensity. Signal to watch: British Columbia Dam Safety Regulation enforcement actions accelerating qualified engineer liability exposure and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Cathode-to-Rod Integration | Proximity smelting investments in Arizona compress logistics costs and capture premium pricing from Southwestern wire fabricators. |
| Scrap-Fed Secondary Smelting Expansion | Quebec and Arizona facilities displace energy-intensive primary production under clean electricity procurement standards. |
| Automated Underground Mining Deployment | Remote mucking and haulage systems in Manitoba operations require mechatronics competencies outpacing regional vocational output. |
| Zero Liquid Discharge Compliance | EPA effluent guidelines force Arizona heap leach operations to install constructed wetlands rivaling extraction equipment in capital allocation. |
| Long-Term Utility Offtake Contracting | ERCOT and CAISO developers bypass merchant metal markets for 5-7 year rod supply schedules indexed to COMEX with volume floors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EIA electricity generation data, EPA effluent guideline dockets, and FERC transmission interconnection queues. Primary interviews engaged mine operations managers at Arizona and Nevada heap leach facilities, utility procurement officers at ERCOT and CAISO zone developers, rod mill technical directors in the Southwestern wire fabrication corridor, and tailings engineering consultants under British Columbia's Dam Safety Regulation. Bottom-up cathode production estimates triangulated against top-down grid infrastructure copper intensity models derived from IRA alternative fuel vehicle refueling credit deployment data.
Forecast inputs incorporate product form segmentation across wire, alloy, pipe, and sheet categories; end-use application splits between electrical, electronics, construction, and plumbing; and technology pathways spanning smelting, recycling, refining, and electrolysis. Modeled dimensions include cathode purity grades, continuous casting integration levels, and regional regulatory framework clusters. CAGRs were derived from elasticity-adjusted demand curves responding to grid hardening mandates and EV charging infrastructure deployment trajectories. Industry-specific inputs capture sulfuric acid price volatility effects on solvent extraction-electrowinning margins and scrap availability forecasts for secondary smelting displacement rates.
Sensitivities concentrate around EPA mining effluent guideline enforcement intensity, British Columbia tailings storage facility approval timelines, and aluminum conductor substitution thresholds in Midwest ISO transmission planning. Forecasts reflect documented assumptions regarding electrification code adoption rates and clean electricity procurement standard stringency. Material shifts in carbon border adjustment implementation schedules or FERC reliability mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Selenium Market
Metals & Minerals
Californium Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Nickel Nano Powder Market