
 One-Component Foam Market | 2026-2036
One-Component Foam Market Size, Share, and Industry Trends Forecast 2026-2036
One-Component Foam Market Outlook
ISO 9001 quality management certification is collapsing as a baseline gate for polyurethane foam suppliers seeking specification-grade contracts. Henkel AG & Co KGaA leverages its adhesive chemistry heritage to sustain formulation leadership in hybrid blowing agent systems. Sika AG anchors European distribution through direct contractor relationships and specification-driven channel control. Dow Inc. competes on monomer backward integration, securing captive supply of polymeric MDI feedstocks.
One-component foam denotes a pre-formulated, moisture-curing polyurethane system packaged in pressurized containers that expands upon application to fill cavities, seal joints, and insulate thermal bridges without requiring on-site metering or mixing equipment. The chemistry relies on isocyanate-terminated prepolymers reacting with atmospheric humidity to produce carbon dioxide as the blowing mechanism, yielding closed-cell structures with thermal conductivity values near 0.025 W/m·K. Aerosol formats dominate residential maintenance volumes due to convenience and shelf stability, while cartridge systems capture commercial and industrial margin pools through precision dispensing and reduced waste. Polyurethane technology maintains the largest installed base, though hybrid formulations incorporating physical blowing agents are displacing legacy chemical systems in jurisdictions with stringent environmental standards.
REACH registration requirements govern substance authorization across Europe, forcing reformulation cycles that elevate R&D costs for non-compliant suppliers. The EPA Significant New Alternatives Policy program restricts hydrofluorocarbon blowing agents in the United States, redirecting investment toward hydrofluoroolefin and hydrocarbon alternatives. BIS certification under Indian standards IS 17056 mandates fire performance testing for imported foam products, creating compliance barriers for unqualified exporters. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized production or standardized global formulations offer superior risk-adjusted returns.
Market Dynamics
REACH registration timelines and the EU Green Deal are compressing reformulation cycles for polyurethane foam suppliers, forcing simultaneous R&D investment in hydrofluoroolefin alternatives while maintaining legacy product lines for less regulated export markets.
Growth Catalysts
- German passive house mandates:Air-sealing requirements under EnerPHit renovation standards are specifying one-component foam for thermal bridge elimination in retrofit envelopes.
- EPA SNAP restrictions:Hydrofluorocarbon phase-down rules are redirecting capital toward compliant blowing agent platforms ahead of enforcement deadlines.
- Cartridge precision dispensing:Commercial contractors are specifying cartridge systems over aerosols for reduced waste and controlled expansion in high-performance building joints.
Market Restraints
- Polymeric MDI supply concentration:European production clusters in Germany and the Netherlands create feedstock vulnerability for non-integrated formulators.
- BIS IS 17056 fire testing:Indian import certification mandates 90-day laboratory validation timelines that delay market entry for new suppliers.
- Mineral wool substitution:Non-combustible insulation materials are capturing specification share in high-rise residential facades where foam fire ratings face scrutiny.
Strategic Opportunities
- Indian building code enforcement gaps:State-level adoption of Energy Conservation Building Code creates first-mover positioning for certified foam distributors in Maharashtra and Gujarat.
- Hydrocarbon-hybrid convergence:Pentane-integrated formulations combining chemical and physical blowing mechanisms are opening patent white space outside legacy HFC licensing networks.
- Direct contractor specification:Bypassing traditional distribution through specification-engineered relationships with envelope contractors captures margin pools in commercial new construction.
Industry Challenges
- Formulation chemist scarcity:Expertise in moisture-cured prepolymer kinetics and blowing agent compatibility is concentrating among retiring technical staff at established suppliers.
- Dual-registration compliance:Maintaining parallel REACH-registered and non-REACH product portfolios strains quality management systems and batch traceability infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One-Component Foam Market |
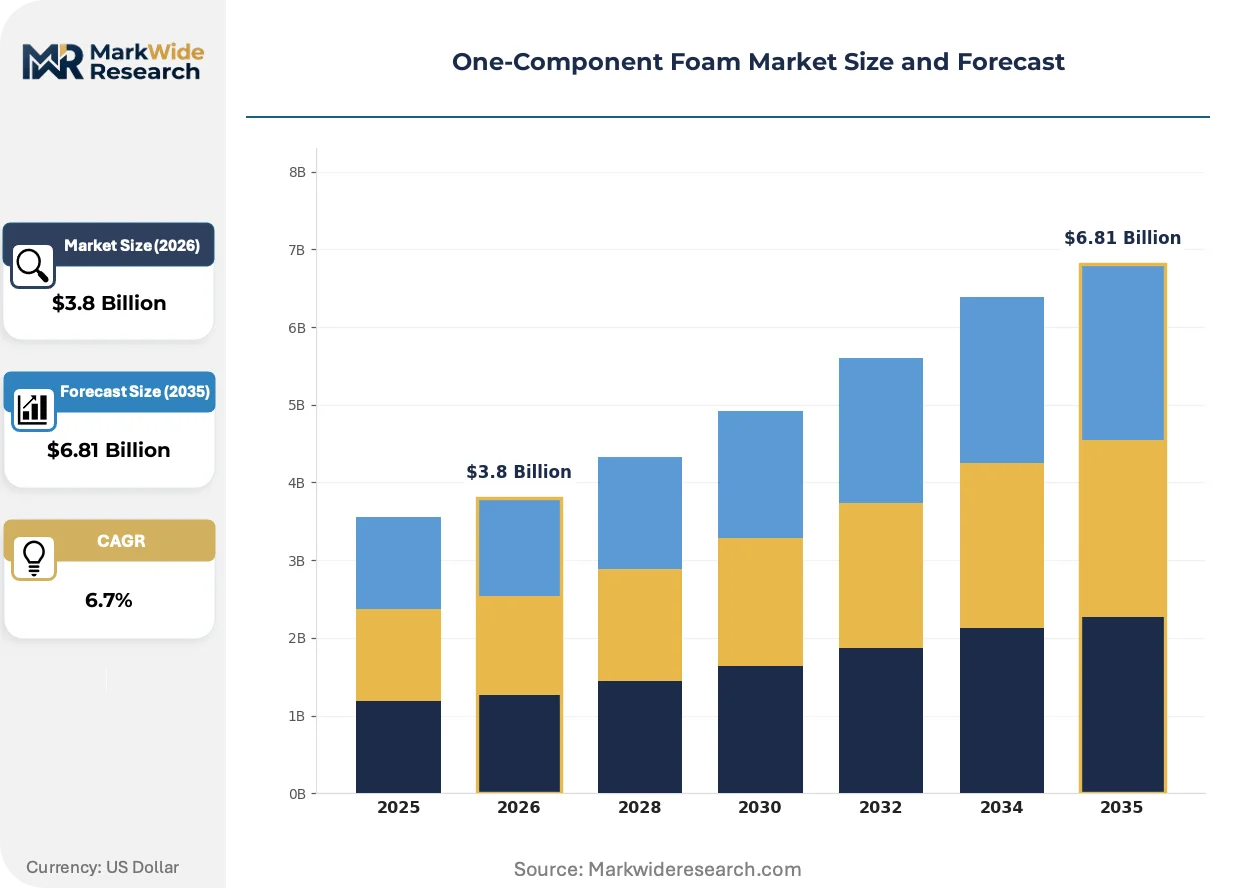
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Cartridge, Squeeze Bottle, Trigger Spray End User: Residential, Commercial, Industrial, Construction Application: Insulation, Sealing, Gapping, Filling Technology: Chemical Blowing Agent, Physical Blowing Agent, Hybrid, Polyurethane |
| Companies Covered | Henkel AG & Co KGaA, Sika AG, BASF SE, Dow Inc., Huntsman Corporation, Soudal Group, Selena Group, Tremco CPG Inc, Polypag AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One-Component Foam Market Strategic Shifts
Formulation chemistry is fragmenting along regulatory fault lines, with physical blowing agent hybrids, bio-based polyols, and precision application hardware emerging as concurrent development vectors rather than sequential replacements.
Pre-mix cartridge systems with integrated static mixers are miniaturizing application equipment for residential maintenance crews who previously relied on professional-grade dispensing rigs. Window and door installers in North American retrofit markets are adopting these portable units for same-day service calls. The technology is compressing the skill barrier between DIY aerosol users and certified commercial applicators.
ECHA substance evaluation under REACH is accelerating data requirements for isocyanate respiratory sensitization, forcing suppliers to submit extended toxicity dossiers for existing prepolymer registrations. Downstream formulators face reformulation deadlines if candidate list inclusions trigger authorization requirements. Construction product manufacturers in Germany and France are front-loading substitution assessments to maintain CE marking continuity.
Specification engineers are consolidating vendor relationships around single-source accountability for thermal envelope performance warranties, displacing fragmented procurement across separate sealant, insulation, and adhesive suppliers. Commercial facade contractors in Benelux markets are demanding unified responsibility for air tightness guarantees. This concentration is elevating suppliers with in-house testing laboratories and certified installer training programs.
One-Component Foam Market Segmentation
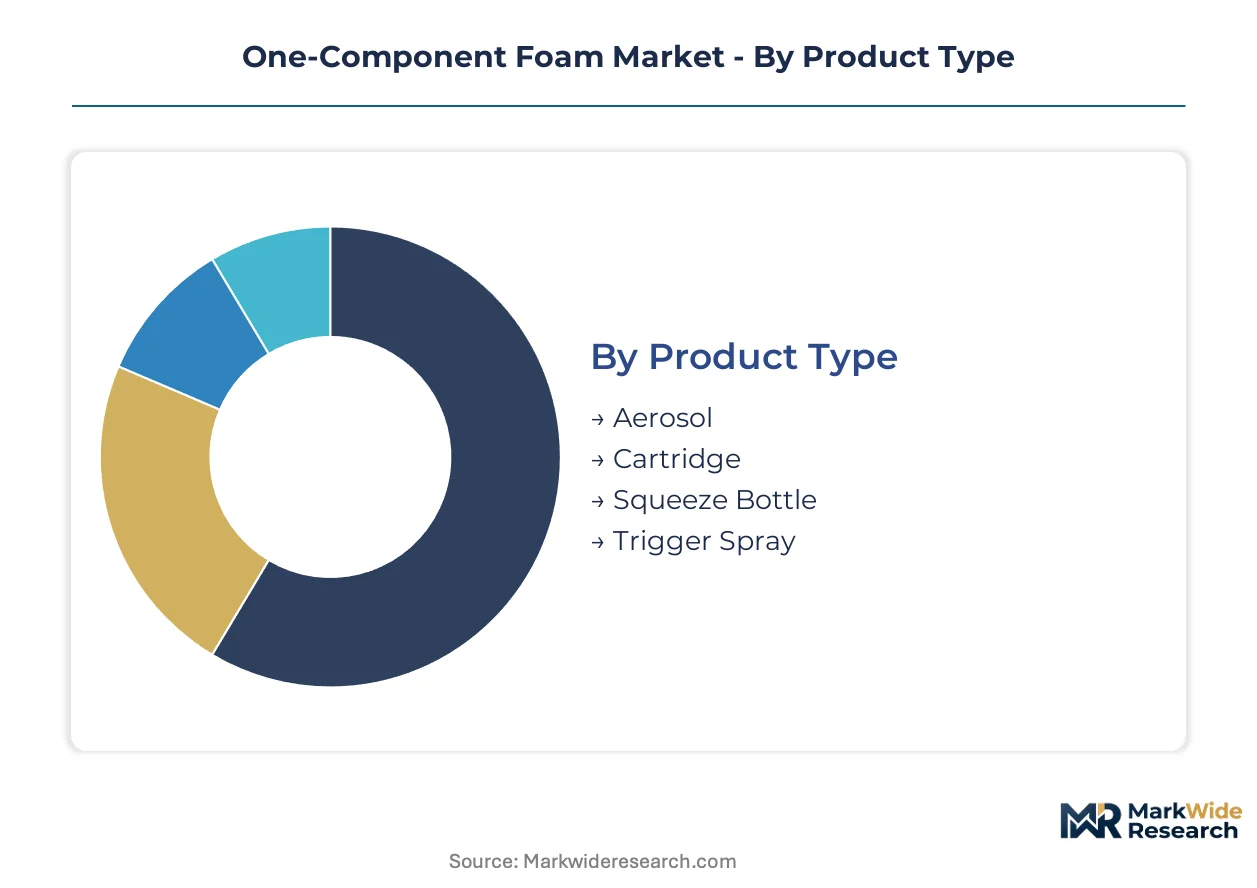
Segmentation in one-component foam reveals how formulation chemistry, packaging format, and end-use specifications fragment procurement patterns. Contractors specify across multiple dimensions simultaneously, creating overlapping margin pools that favor suppliers with portfolio breadth.
Product Type:
Cartridge systems command premium pricing in commercial specification channels where waste reduction and precision dispensing justify higher unit economics. Aerosol formats dominate residential maintenance volumes through retail accessibility and shelf-stable convenience.
- Cartridge:Pre-formulated cartridges with integrated static mixers enable controlled expansion ratios for thermal bridge elimination in EnerPHit-compliant renovations. German envelope contractors specify these systems for air-tightness guarantees in passive house retrofits.
- Aerosol:Pressurized metal containers with propellant-driven delivery suit DIY gap-filling and seasonal maintenance cycles. North American hardware retail channels move these units in high volumes for window and door installation crews.
- Squeeze Bottle:Hand-pressure dispensing targets small-scale touch-up applications and craft-scale manufacturing.
- Trigger Spray:Pump-action mechanisms serve low-expansion precision work in electrical box sealing and fixture mounting.
Aerosol holds installed capacity. Cartridge is rotating up the share rankings.
End User:
Construction sector procurement concentrates specification authority with envelope contractors who bundle insulation, sealing, and air-barrier warranties. Residential demand fragments across homeowner DIY and professional installer channels with divergent price sensitivity.
- Construction:General and specialty contractors purchasing through specification-driven distribution for commercial facade and thermal envelope projects. Benelux markets consolidate vendor relationships around single-source accountability for performance warranties.
- Residential:Homeowners and small-scale renovators sourcing through retail hardware and e-commerce platforms. Seasonal demand patterns align with weather-dependent maintenance cycles in temperate climates.
- Commercial:Facility managers and maintenance departments procuring for building envelope repair and HVAC sealing.
- Industrial:Manufacturing operations using foam for equipment insulation, vibration damping, and void filling in production fixtures.
Construction anchors volume concentration. Residential is expanding most quickly through retail channel penetration.
Application:
Insulation applications extract maximum value per kilogram through thermal performance specifications, while sealing commands loyalty through recurring maintenance demand and contractor training relationships.
- Insulation:Cavity filling and thermal bridge elimination requiring closed-cell structures with conductivity near 0.025 W/m·K. Passive house standards in Germany mandate these specifications for EnerPHit renovation compliance.
- Sealing:Joint and perimeter air-barrier applications where durability and adhesion determine callback rates. Commercial contractors in North America specify these for blower-door test compliance.
- Gapping:Non-structural void filling around penetrations and rough openings.
- Filling:Bulk volume displacement in packaging, flotation, and sound-dampening applications.
Sealing holds installed capacity. Insulation is rotating up the share rankings.
Technology:
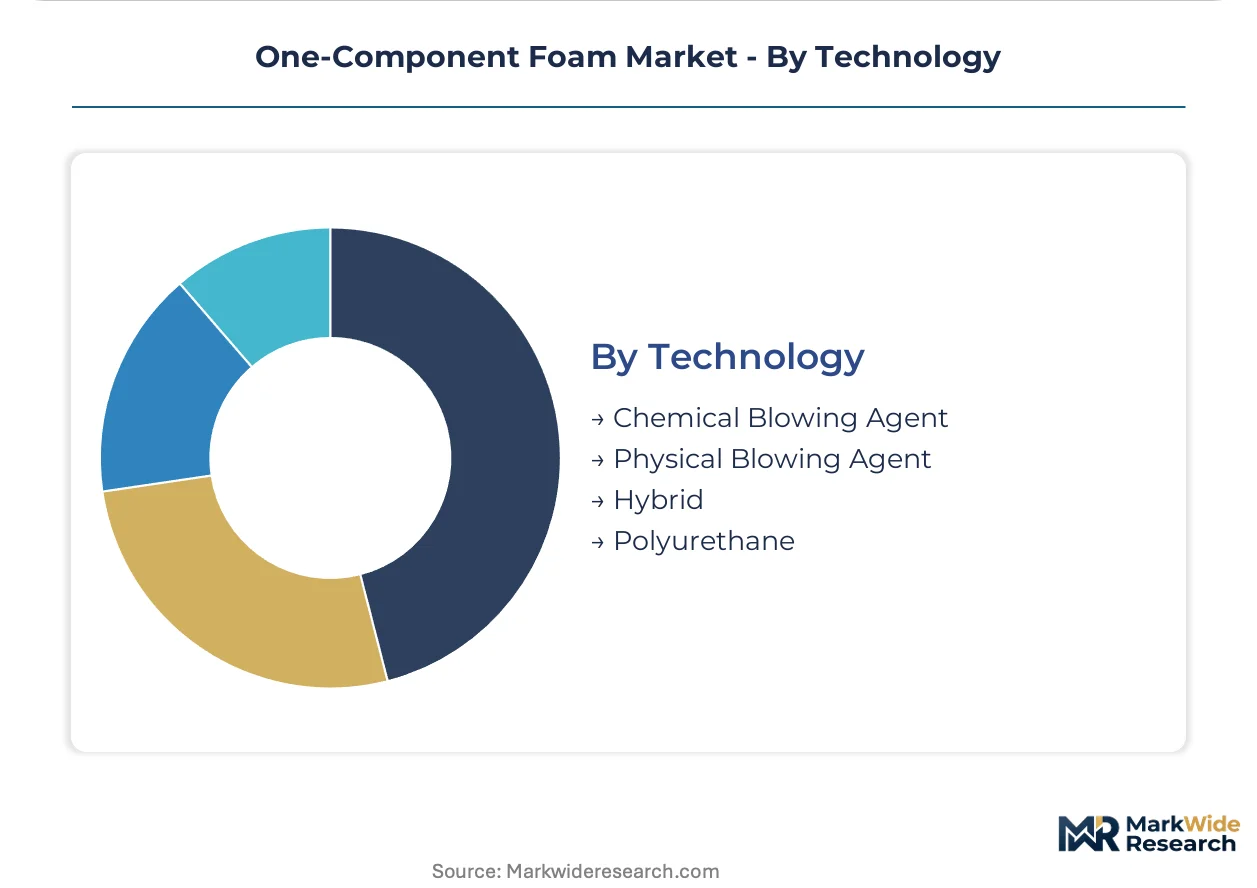
Physical and hybrid blowing agent platforms concentrate R&D investment as REACH and EPA SNAP restrictions compress reformulation timelines. Polyurethane maintains scale advantages through feedstock integration and process familiarity.
- Hybrid:Pentane-integrated formulations combining chemical and physical blowing mechanisms to navigate patent licensing networks and environmental compliance. These systems open white space outside legacy HFC supply chains.
- Polyurethane:Moisture-cured isocyanate prepolymer chemistry with the largest installed production base. Dow Inc. and integrated suppliers leverage captive polymeric MDI supply to defend position.
- Chemical Blowing Agent:Traditional water-isocyanate reaction systems facing regulatory pressure in European and North American jurisdictions.
- Physical Blowing Agent:Hydrocarbon and hydrofluoroolefin alternatives redirecting capital ahead of enforcement deadlines.
Polyurethane holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Envelope contractors and passive house specifiers concentrate procurement authority in Germany, while residential maintenance demand fragments across North American hardware retail channels. Chemical feedstock integration and regulatory compliance timelines are reshaping supplier geography.
Germany
EnerPHit renovation standards mandate thermal bridge elimination through precision air-sealing systems. REACH substance evaluation under ECHA accelerates isocyanate data requirements for prepolymer registrations. The Rhine-Main industrial corridor hosts integrated polymeric MDI production clusters serving formulators.
United States
Window and door retrofit crews drive aerosol volumes through seasonal maintenance cycles. EPA SNAP restrictions redirect capital toward hydrofluoroolefin blowing agent platforms ahead of enforcement deadlines. The Gulf Coast petrochemical corridor supplies captive isocyanate feedstocks to integrated manufacturers.
India
State-level Energy Conservation Building Code adoption in Maharashtra and Gujarat creates specification opportunities for certified distributors. BIS IS 17056 mandates 90-day fire performance testing timelines that delay import market entry. The Delhi-Mumbai Industrial Corridor concentrates construction material distribution infrastructure.
Netherlands
Benelux facade contractors consolidate vendor relationships around single-source accountability for air-tightness warranties. EU Green Deal carbon border adjustments elevate compliance costs for non-EU feedstock imports. The Rotterdam-Antwerp chemical cluster anchors European blowing agent formulation capacity.
China
Building energy efficiency codes in tier-one cities specify high-performance envelope sealing for commercial retrofits. GB standards and dual carbon goals pressure domestic formulators toward low-GWP blowing agent transitions. The Yangtze River Delta concentrates polyurethane prepolymer manufacturing for Asia-Pacific supply.
One-Component Foam Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive isocyanate supply and specialized construction chemical houses with specification-driven distribution control. Structure tiers across feedstock-integrated multinationals, regional formulation specialists, and private-label contract manufacturers. Dominant competitive moves include backward integration into polymeric MDI production and direct contractor specification relationships bypassing traditional distribution.
Within the feedstock-integrated tier, Dow Inc. and BASF SE exemplify archetypes leveraging captive monomer supply to defend position against reformulation cost pressures. Among specialized construction chemical houses, Henkel AG & Co KGaA and Sika AG occupy positions anchored in adhesive chemistry heritage and direct contractor channel control respectively. These four entities represent the competitive poles around which mid-cap formulators and regional distributors organize their market participation strategies.
| Leading Market Players |
|---|
| Henkel AG & Co KGaA |
| Sika AG |
| BASF SE |
| Dow Inc. |
| Huntsman Corporation |
| Soudal Group |
| Selena Group |
| Tremco CPG Inc |
| Polypag AG |
| Others |
Value Chain & Pricing Dynamics
Sixty-day polymeric MDI inventory cycles at European formulators compress working capital flexibility and amplify feedstock cost pass-through into cartridge system pricing. This lead-time band concentrates pricing power with backward-integrated suppliers who control captive monomer supply, while non-integrated competitors absorb margin compression during MDI spot volatility.
Pricing Analysis
Cost-plus contracts with polymeric MDI indexation dominate procurement between integrated suppliers and specification-grade distributors. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered hybrid formulations from legacy chemical systems and unlicensed private-label imports. Pricing pressure stems from mineral wool substitution in high-rise facades where fire ratings disqualify foam specifications. Residential DIY aerosol buyers exhibit highest price sensitivity, while German passive house contractors prioritize air-tightness performance over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites feedstock security calculations for Middle Eastern MDI exporters serving Indian and Chinese formulators. Polymeric MDI production clusters in Germany, the Netherlands, and the US Gulf Coast anchor global supply, with pentane and hydrofluoroolefin blowing agents sourced from Belgian and Japanese specialty chemical producers. Single-source vulnerability concentrates in European isocyanate terminals where REACH registration timelines delay alternative supplier qualification. Distribution runs through specification-driven channel partners who bundle certified installer training with product warranties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against mineral wool and aerogel insulation systems that capture specification share in fire-sensitive high-rise construction. Incumbents must navigate reformulation cost pressures while defending installed base relationships.
For Market Incumbents: Secure captive polymeric MDI supply through backward integration or long-term offtake agreements with Rhine-Main cluster producers. Deepen specification-engineered relationships with Benelux facade contractors who consolidate vendor accountability around single-source air-tightness warranties. Counter mineral wool substitution by front-loading fire-performance testing investments for hybrid formulations ahead of BIS IS 17056 enforcement expansion. For New Entrants and Emerging Players: Anchor in Indian state-level ECBC adoption gaps across Maharashtra and Gujarat where certified distributor networks remain underdeveloped. Target cartridge precision dispensing for commercial EnerPHit renovation crews who demand controlled expansion ratios unavailable from aerosol alternatives. Accelerate BIS fire certification timelines through local laboratory partnerships to compress 90-day validation windows. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH and EPA SNAP divergence creates parallel product portfolio requirements that favor multi-jurisdictional formulators with batch traceability infrastructure. Acquisition candidates include regional European specialists with ECHA-registered prepolymer dossiers and Indian distributors with BIS-certified import pathways. Watch hydrocarbon-hybrid patent filing velocity as inflection indicator for white-space availability outside legacy HFC licensing networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstocks | Captive supply from Rhine-Main and Gulf Coast clusters insulates margins from polymeric MDI spot volatility. |
| Hybrid Blowing Agent Patent Development | Pentane-integrated formulations navigate ECHA and EPA SNAP restrictions outside legacy HFC licensing networks. |
| Direct Contractor Specification Relationships | Benelux facade contractors consolidate vendor accountability around unified air-tightness performance warranties. |
| BIS Certification Infrastructure Investment | Ninety-day IS 17056 fire testing timelines create entry barriers that certified Indian distributors can monetize. |
| Installer Training Program Expansion | Certified application crews differentiate cartridge systems from DIY aerosols in EnerPHit-compliant passive house retrofits. |
Study Parameters
A standing panel of envelope contractor procurement managers, polyurethane formulation chemists, BIS certification laboratory directors, and passive house specification engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, EPA SNAP program dockets, Indian customs import records under IS 17056, and European construction chemical trade association reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, end user, application, and technology segmentation dimensions. CAGRs derived from regression analysis of historical shipment data and forward-projected regulatory compliance timelines. Industry-specific forecast inputs incorporated EnerPHit renovation penetration rates and state-level ECBC adoption curves for Indian construction markets.
Material uncertainties — REACH substance evaluation acceleration, EPA SNAP enforcement timing, and Indian BIS laboratory capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory divergence persistence and feedstock supply continuity. Practitioners should keep alternative scenarios live as hydrocarbon-hybrid patent landscapes and carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Technical Foam Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market