
 America Lubricants Market | 2026-2036
America Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
America Lubricants Market Intelligence
Asset-light leasing models for lubricant blending and distribution infrastructure are reconfiguring competitive entry barriers across the Americas. ExxonMobil Corporation leverages its integrated base oil production network to sustain margin control from feedstock through finished product. Chevron Corporation anchors its position through proprietary additive chemistry developed at its Richmond Technology Center. Valvoline Inc. competes via its quick-lube service channel, which locks in recurring aftermarket volume.
America lubricants encompass formulated fluids and greases engineered from base oils combined with performance additives to reduce friction, dissipate heat, and prevent wear in mechanical systems. Synthetic lubricants, produced through catalytic hydrocracking and isomerization of petroleum feedstocks or polyalphaolefin synthesis, deliver viscosity stability across extreme temperature ranges for high-performance engines and industrial gearboxes. Mineral oil formulations still occupy the largest share of total volume due to cost-sensitive fleet and industrial maintenance budgets, though biodegradable lubricants are gaining traction in marine and environmentally sensitive applications where spill regulations tighten. The automotive application segment leads value generation, while industrial machinery represents the most fragmented competitive arena with numerous regional formulators.
The U.S. EPA, NHTSA, and the American Petroleum Institute's engine service categories collectively shape product specifications and market access across the Americas. Corporate Average Fuel Economy standards from NHTSA push OEMs toward 0W-16 and 0W-8 viscosity grades that demand advanced synthetic base stocks and friction modifier packages. The API's SP and CK-4 licensing protocols create compliance thresholds that filter out smaller blenders lacking certification investment capacity. Stakeholders must monitor how California's Air Resources Board extends its low-emission vehicle rules into lubricant lifecycle carbon accounting, as this could restructure sourcing requirements for base oils and additive packages.
Market Dynamics
Fleet operators across the Americas are consolidating lubricant procurement around synthetic formulations that extend drain intervals, while the U.S. EPA and NHTSA pressure formulators toward lower-viscosity grades through tightening fuel economy mandates. This regulatory-technological squeeze is compressing the addressable market for conventional mineral oil products and rewarding integrated producers with captive base oil supply.
Growth Catalysts
- NHTSA CAFE Standards:Corporate Average Fuel Economy mandates force OEMs toward 0W-16 and 0W-8 grades, accelerating demand for advanced synthetic base stocks and friction modifier packages in passenger vehicle applications.
- Commercial Fleet Consolidation:Large trucking operators in the U.S. and Mexico are standardizing on synthetic lubricants to reduce vehicle downtime and extend maintenance intervals across distributed asset networks.
- Gulf Coast Petrochemical Corridor:Concentrated base oil refining and additive blending clusters in Texas and Louisiana enable integrated supply networks that compress logistics costs for regional formulators.
Market Restraints
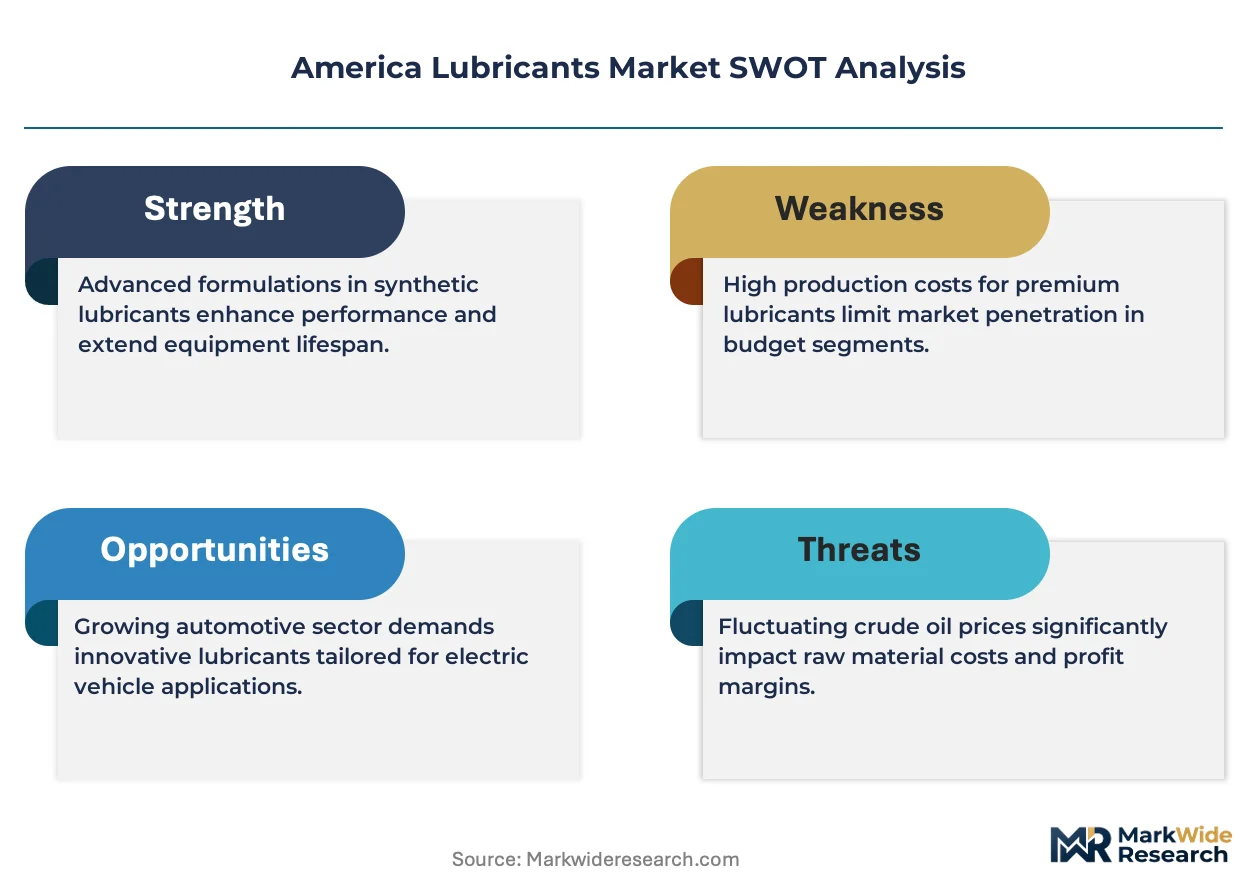
- Group III+ Base Oil Supply Concentration:Production of high-performance synthetic base stocks concentrates among a limited set of integrated refiners, creating bottleneck risk for independent blenders lacking backward integration.
- API Certification Investment Barriers:The American Petroleum Institute's SP and CK-4 licensing protocols require substantial testing expenditure, filtering smaller regional blenders from premium product segments.
- Mineral Oil Cost Sensitivity:Price-conscious fleet and industrial maintenance budgets in Latin America continue favoring conventional mineral formulations, limiting synthetic penetration in cost-driven segments.
Strategic Opportunities
- Brazilian Industrial Expansion:Manufacturing growth in São Paulo and Minas Gerais states creates underpenetrated demand for high-performance industrial gear oils and hydraulic fluids.
- California CARB Lifecycle Rules:The state's Air Resources Board is extending low-emission vehicle regulations into lubricant carbon accounting, creating first-mover advantage for formulators with renewable base oil sourcing.
- Quick-Lube Channel Digitization:Subscription-based predictive maintenance platforms are emerging as a new distribution vector, locking in recurring aftermarket volume through telematics-enabled oil life monitoring.
Industry Challenges
- Additive Chemist Talent Scarcity:Formulation expertise in friction modifier and detergent chemistry concentrates among a shrinking cohort of experienced specialists, inflating R&D compensation costs.
- Re-refining Infrastructure Capex:Used oil collection and re-refining capacity expansion requires substantial capital deployment, straining mid-size blenders attempting circular economy positioning.
- Multi-Jurisdiction Certification Timelines:Simultaneous compliance with API, ACEA, and OEM proprietary specifications stretches product development cycles and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Lubricants Market |
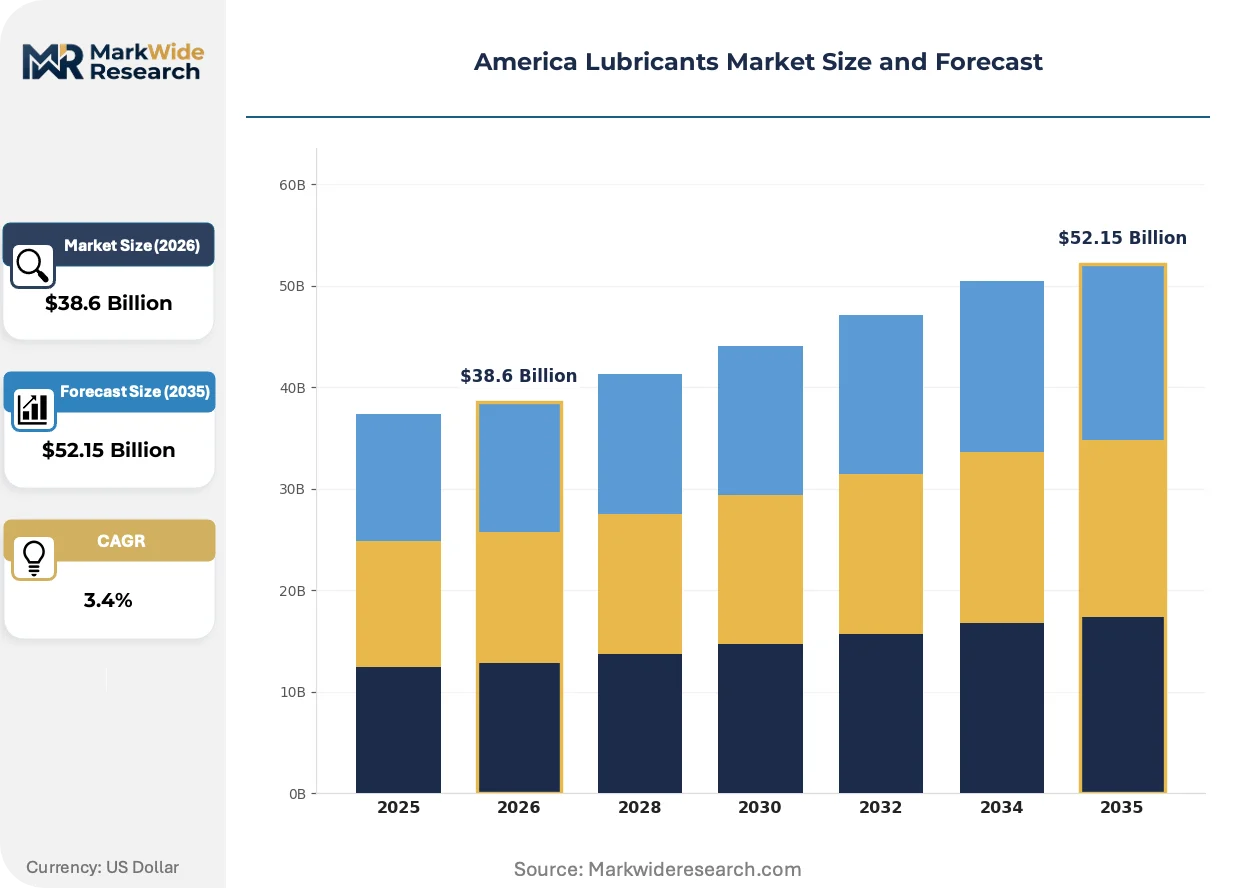
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $52.15 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Biodegradable Lubricants, Greases Application: Automotive, Industrial Machinery, Marine, Aerospace End User: OEMs, Aftermarket Providers, Maintenance Services, Personal Use Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell Oil Company, Phillips 66, Valvoline Inc., TotalEnergies, Fuchs Lubricants Co, BP America Inc., The Lubrizol Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Lubricants Market Strategic Shifts & Innovations
Formulation chemistry and distribution architecture are converging around performance verification and predictive service models. The market is witnessing simultaneous pressure toward lower-viscosity synthetic grades and circular feedstock sourcing, with digital channels beginning to disintermediate traditional distributor relationships.
Polyalphaolefin (PAO) and gas-to-liquids base stocks are hybridizing with ester co-base oils to achieve viscosity stability across extreme temperature ranges while meeting biodegradability thresholds for marine and environmentally sensitive applications. Off-highway equipment manufacturers in the U.S. Midwest are adopting these hybrid formulations for cold-start reliability. The technology is hybridizing the traditional boundary between synthetic performance and environmental compliance, compressing the viable market for single-attribute lubricants.
The U.S. EPA's evolving greenhouse gas standards for heavy-duty vehicles are cascading into lubricant specifications through OEM warranty requirements and factory-fill mandates. Engine manufacturers are tightening oil approval protocols to protect emissions control systems, forcing formulators to accelerate additive package redevelopment. The commercial trucking segment across the U.S. Interstate highway corridor is responding by consolidating supplier relationships around vertically integrated producers with in-house testing capacity.
Telematics-enabled oil condition monitoring is compressing traditional fixed-interval maintenance schedules into usage-based replacement cycles. Fleet management platforms are disintermediating distributor relationships by directing lubricant purchases through integrated procurement dashboards. This behavioral shift is most visible among large for-hire carriers operating across the U.S.-Mexico-Canada trade corridor, where cross-border compliance documentation favors single-source supplier arrangements.
America Lubricants Market Segmentation
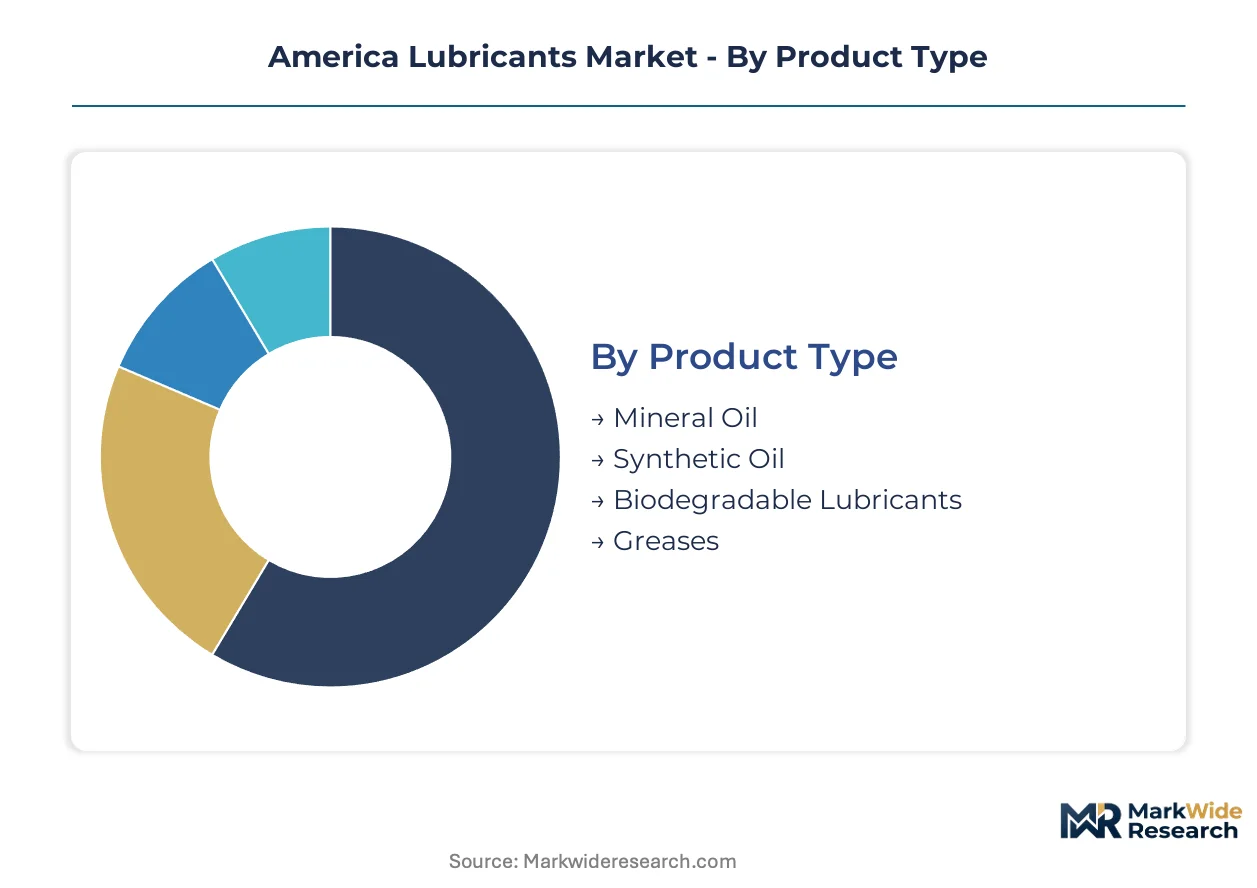
Segmentation in the America lubricants market reveals distinct service intensity profiles across product and channel combinations. Fleet operators and industrial maintenance services demand divergent formulation specifications and replenishment cadences, creating tiered margin structures for suppliers.
Product Type:
After-sales service intensity varies sharply across lubricant chemistries, with synthetic formulations requiring technical consultation during specification but extending drain intervals, while mineral oils demand frequent replenishment with lower touch per transaction.
- Mineral Oil:Refined petroleum base stocks with additive packages meeting API SP and CK-4 specifications dominate cost-sensitive fleet procurement across Mexico and Central America. Demand concentrates among regional trucking operators and aging industrial machinery in Brazilian manufacturing corridors where procurement prioritizes unit cost over extended drain intervals.
- Synthetic Oil:Polyalphaolefin and Group III+ hydrocracked base stocks deliver viscosity stability from -40°C to 150°C for OEM factory-fill and premium aftermarket segments. Adoption concentrates among U.S. Class 8 fleet operators along the Interstate highway network seeking to compress vehicle downtime through extended oil change intervals.
- Biodegradable Lubricants:Ester-based formulations with aquatic toxicity compliance serve marine and environmentally sensitive applications where spill regulations tighten.
- Greases:Thickened lubricants with lithium, calcium, or polyurea soap structures protect bearings and chassis components in off-highway equipment.
By volume, Mineral Oil leads. By growth pace, Synthetic Oil is ahead.
Application:
Cost tier differentiation separates specification-intensive automotive applications from price-elastic industrial machinery segments, with marine and aerospace occupying premium niches defined by regulatory compliance burdens rather than volume scale.
- Automotive:Passenger vehicle and commercial truck engine oils, transmission fluids, and axle lubricants formulated to OEM warranty requirements and API licensing protocols. Demand concentrates in U.S. quick-lube service channels and Mexican fleet maintenance depots where drain interval extension drives synthetic conversion.
- Industrial Machinery:Hydraulic fluids, compressor oils, and gear lubricants serving manufacturing, mining, and energy production equipment. Procurement fragments across regional maintenance contractors in São Paulo state and Gulf Coast petrochemical facilities with divergent specification sophistication.
- Marine:Cylinder oils and system lubricants for two-stroke and four-stroke marine engines operating on residual fuels.
- Aerospace:Synthetic ester-based turbine oils and hydraulic fluids meeting SAE AS5780 and OEM proprietary approvals.
Automotive commands the largest revenue pool. Industrial Machinery exhibits the steepest expansion trajectory in absolute volume terms.
End User:
Customer type determines contract structure and margin capture, with OEM factory-fill agreements locking in multi-year supply relationships and aftermarket providers competing on fill-speed and inventory availability.
- OEMs:Engine and equipment manufacturers specifying factory-fill lubricants to protect warranty coverage and emissions system durability. Relationships concentrate among Detroit-based heavy-duty truck manufacturers and Brazilian agricultural equipment producers with captive fluid requirements.
- Aftermarket Providers:Quick-lube chains, parts retailers, and independent distributors serving vehicle owners post-warranty. Channel consolidation in the U.S. Midwest and Southeast is compressing supplier counts around vertically integrated producers with national distribution reach.
- Maintenance Services:Third-party fleet management and industrial contractor lubrication programs.
- Personal Use:Consumer-directed purchases through retail and e-commerce channels for DIY vehicle maintenance.
OEMs anchor the highest-margin tier. Aftermarket Providers are gaining share fastest through service channel digitization.
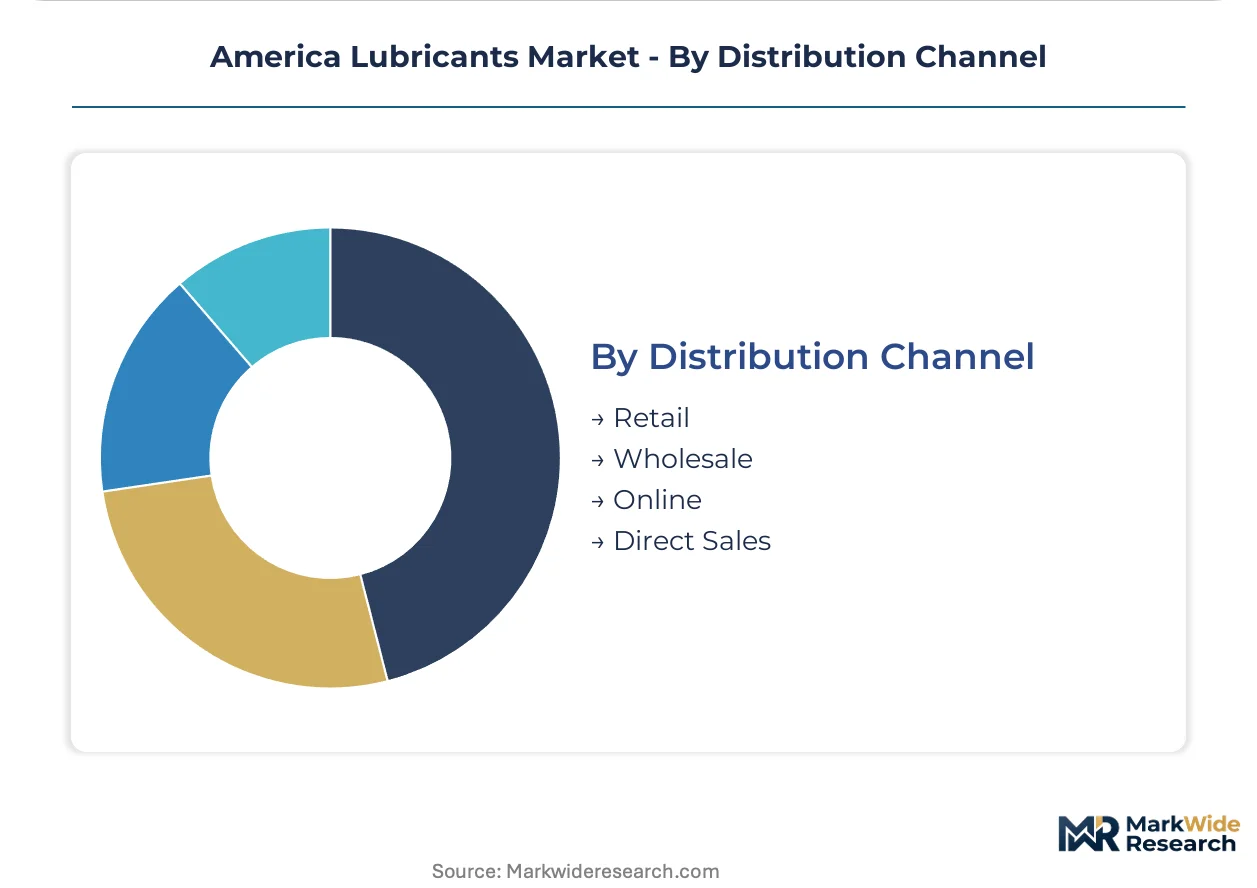
Distribution Channel:
Supply concentration in the Gulf Coast petrochemical corridor advantages wholesale and direct sales channels for large volume accounts, while retail and online segments serve fragmented demand with higher logistics cost absorption.
- Retail:Auto parts stores, mass merchants, and farm supply outlets stocking consumer-packaged lubricants. Shelf space competition intensifies in U.S. suburban markets where brand recognition drives purchase decisions.
- Wholesale:Distributors serving commercial garages, fleet maintenance facilities, and industrial plants with bulk and packaged product. Network density concentrates in Texas and Louisiana proximate to base oil refining and additive blending clusters.
- Online:E-commerce platforms and direct-to-consumer fulfillment capturing DIY and small fleet procurement.
- Direct Sales:Manufacturer-account relationships with national fleet operators and industrial end users eliminating distributor margin.
Wholesale moves the largest physical volume. Online is climbing the fastest as fleet procurement platforms digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA fuel economy mandates and EPA emissions standards are redirecting formulation demand toward lower-viscosity synthetic grades across the Americas, while state-level carbon accounting rules in California create compliance complexity for base oil sourcing.
United States
Class 8 fleet operators along the Interstate highway network are consolidating supplier relationships around synthetic formulations that compress vehicle downtime. The EPA's evolving greenhouse gas standards for heavy-duty vehicles cascade into lubricant specifications through OEM warranty requirements. Base oil refining and additive blending clusters in Texas and Louisiana enable integrated supply networks that compress logistics costs for regional formulators.
Brazil
Manufacturing growth in São Paulo and Minas Gerais states generates underpenetrated demand for high-performance industrial gear oils and hydraulic fluids. ANVISA maintains pharmaceutical-grade standards that indirectly shape lubricant purity benchmarks for food-contact machinery applications. Regional trucking operators and aging industrial machinery in Brazilian manufacturing corridors prioritize unit cost over extended drain intervals, sustaining mineral oil volume.
Mexico
Cross-border trade corridor logistics favor single-source supplier arrangements for large for-hire carriers operating across the U.S.-Mexico-Canada agreement zone. Mexican fleet maintenance depots are converting to synthetic lubricants as drain interval extension drives procurement decisions. The Nuevo León industrial corridor anchors automotive manufacturing clusters that demand OEM-compliant factory-fill specifications.
Canada
Alberta's oil sands extraction equipment and prairie agricultural machinery create specialized demand for cold-start reliable formulations. Environment and Climate Change Canada regulations on marine spill response are tightening biodegradability requirements for Great Lakes shipping lubricants. The Ontario-Quebec manufacturing belt concentrates industrial lubricant procurement among automotive parts suppliers and aerospace contractors.
Argentina
Grain export logistics and mining operations in the Pampas and Andean foothills sustain demand for heavy-duty diesel engine oils and open-gear lubricants. The country's national industrial standards body maintains alignment with API service categories while adding local content requirements for public procurement. Buenos Aires province anchors petrochemical refining capacity that supplies regional blenders with Group I and Group II base stocks.
America Lubricants Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that rewards backward integration into base oil production. The vendor base concentrates around vertically integrated refiners with captive additive development capability and national quick-lube networks that lock in recurring aftermarket volume. Three archetypes dominate: integrated majors with Gulf Coast refining assets, formulation specialists with proprietary additive chemistry, and service-channel operators with predictive maintenance platforms. Competitive moves center on capacity expansion in Group III+ base oil production and strategic partnerships linking telematics providers to lubricant procurement dashboards.
Within the integrated major tier, ExxonMobil Corporation and Chevron Corporation exemplify players leveraging captive base oil networks to sustain margin control from feedstock through finished product. Valvoline Inc. occupies a position representing the service-channel archetype, competing through quick-lube infrastructure that captures recurring aftermarket volume. These three companies anchor the competitive structure, with independent blenders and regional distributors occupying fragmented positions between them.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell Oil Company |
| Phillips 66 |
| Valvoline Inc. |
| TotalEnergies |
| Fuchs Lubricants Co |
| BP America Inc. |
| The Lubrizol Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Gulf Coast Group III+ base oil refining is compressing supplier margins while simultaneously granting integrated producers pricing power over independent blenders lacking backward integration. This utilization asymmetry forces non-integrated formulators toward mineral oil cost positioning or premium synthetic differentiation with no viable middle ground.
Pricing Analysis
API certification tier creates the primary spread between premium and economy positioning, with SP and CK-4 licensed products commanding substantial premiums over unlicensed regional alternatives. Contract-based long-term offtake agreements dominate fleet procurement, while spot purchasing persists among small industrial maintenance contractors. Price differentiation hinges on additive package sophistication and drain interval extension claims, with California CARB lifecycle compliance emerging as a new premium tier. Cost compression in conventional mineral formulations is intensifying because Latin American fleet procurement prioritizes unit economics over performance metrics. Regional trucking operators in Mexico and Central America exhibit highest price sensitivity, while OEM factory-fill agreements demonstrate lowest sensitivity due to warranty protection requirements.
Supply Chain Analysis
Export control regimes on advanced catalytic hydrocracking catalysts and polyalphaolefin synthesis technology limit technology transfer to emerging regional blenders, constraining supply expansion outside integrated major networks. Geographic supply concentration centers on the United States Gulf Coast, with secondary clusters in Alberta and Buenos Aires province anchoring regional feedstock availability. Raw material dependencies include Group II/III base stocks from hydrocracked vacuum gas oil, proprietary additive packages from Lubrizol and Infineum, and friction modifier chemicals from specialized chemical producers. Single-source vulnerability concentrates in high-performance synthetic base oil production, where four integrated refiners control majority capacity. Distribution runs through wholesale distributors serving bulk fleet accounts, with direct sales channels penetrating national quick-lube chains and OEM factory-fill agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from telematics-enabled predictive maintenance platforms that disintermediate traditional lubricant procurement through usage-based replacement cycles rather than fixed-interval bulk purchasing.
For Market Incumbents: Pre-empt platform disintermediation by embedding lubricant supply contracts within fleet management software partnerships, locking in recurring volume through API integration rather than distributor relationships. Accelerate captive supply of Group III+ base stocks through capacity expansion in Texas and Louisiana to defend margin structure against independent blenders sourcing at spot differentials. Channel control through quick-lube network digitization represents the critical defensive lever against emerging predictive maintenance entrants. For New Entrants and Emerging Players: Brazilian industrial corridor underpenetration in high-performance hydraulic fluids and gear oils offers white-space expansion without confronting entrenched quick-lube channel control in the United States. Target São Paulo and Minas Gerais manufacturing facilities with technical consultation-heavy specification support, differentiating through biodegradable formulation compliance for food-contact machinery applications. Subscription-based oil condition monitoring platforms provide the most viable go-to-market angle for bypassing established wholesale distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among quick-lube service channel operators with telematics integration capabilities, positioning these assets for premium valuation multiples relative to commodity blending operations. Long-term viability over the coming decade favors formulators with renewable base oil sourcing capabilities aligned to California CARB lifecycle accounting expansion. Acquisition target archetype: mid-size blenders with established API certification and regional fleet relationships but lacking digital channel infrastructure. Monitor NHTSA CAFE standard stringency acceleration as the primary inflection signal for synthetic grade demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Oil Production | Captive supply from Texas and Louisiana refining clusters compresses feedstock cost volatility for integrated formulators. |
| Telematics Platform Partnership | API integration with fleet management software locks in recurring aftermarket volume through usage-based procurement triggers. |
| California CARB Compliance Investment | Renewable base oil sourcing certification creates first-mover positioning as lifecycle carbon accounting extends to lubricant specifications. |
| Quick-Lube Channel Digitization | Predictive maintenance dashboards disintermediate wholesale distributors by directing lubricant purchases through integrated procurement interfaces. |
| Brazilian Industrial Market Entry | São Paulo manufacturing growth generates underpenetrated demand for high-performance hydraulic fluids without entrenched competitor channel control. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, quick-lube chain procurement officers, base oil refinery planning managers, additive package R&D chemists, and industrial lubrication contractors across the Americas. Secondary validation drew from U.S. EPA regulatory filings, NHTSA CAFE standard documentation, API licensing protocols, ANVISA pharmaceutical-grade purity benchmarks, and SEC 10-K disclosures from integrated petroleum majors. Bottom-up volume estimates from end-use segment interviews were triangulated against top-down base oil production and trade flow data to reconcile demand and supply perspectives.
Calibration against historical API certification adoption curves and synthetic penetration rates in Class 8 trucking fleets anchored the forward projection framework. The analytical approach modeled volume and value across product type, application, end user, and distribution channel dimensions, with additional segmentation by base oil group and viscosity grade tier. CAGRs were derived from regression analysis of segment-level growth drivers rather than simple extrapolation. Key forecast inputs included NHTSA regulatory stringency scenarios, Gulf Coast refining capacity expansion timelines, and telematics platform adoption curves in commercial fleet management.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, crude oil price volatility, and cross-border trade corridor freight volumes would shift the trajectory of lubricant demand across automotive and industrial applications. Forecasts reflect assumptions regarding regulatory implementation timelines and OEM specification adoption rates that remain subject to revision. Cross-checking against API licensing volume disclosures and base oil refinery utilization reports from the U.S. Energy Information Administration is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Slideway Oil Market
Lubricants
Vietnam Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Middle East Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Anti-Static Oil Market
Lubricants
Yarn Lubricant Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Bangladesh Lubricants Market
Lubricants
India Lubricants Market
Lubricants
Global Lubricants Market