
 Global Automotive Engine Oils Market | 2026-2036
Global Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engine Oils Market Foresight
Southeast Asia is rewriting regional supply dynamics as Indonesia and Thailand expand blending capacity for 5W-30 and 0W-20 grades. ExxonMobil Corporation leverages its Singapore hub to anchor Asia-Pacific distribution. Royal Dutch Shell competes through backward integration into Group III base oil production. Sinopec Group dominates domestic Chinese formulation with captive additive supply.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, with synthetic variants using polyalphaolefin or ester bases to achieve viscosity stability across temperature extremes. Synthetic formulations command premium positioning as OEMs mandate lower viscosity grades for fuel economy compliance. The passenger vehicle application segment leads volume but commercial vehicles generate higher per-unit revenue through severe-duty formulations. Aftermarket channels sustain margin pools while OEM supply contracts lock in long-term formulation partnerships.
EPA fuel economy standards and the EU F-Gas Regulation shape lubricant demand by forcing lower viscosity grades and reduced volatility specifications. China's MIIT implements GB standards that converge with ILSAC GF-6 and ACEA C sequences for domestic vehicle production. ACEA, API, and JASO classification systems create compliance complexity that rewards formulation specialists with multi-certification capabilities. Stakeholders must monitor how hybrid powertrain proliferation splits lubricant requirements between dedicated hybrid oils and legacy ICE formulations.
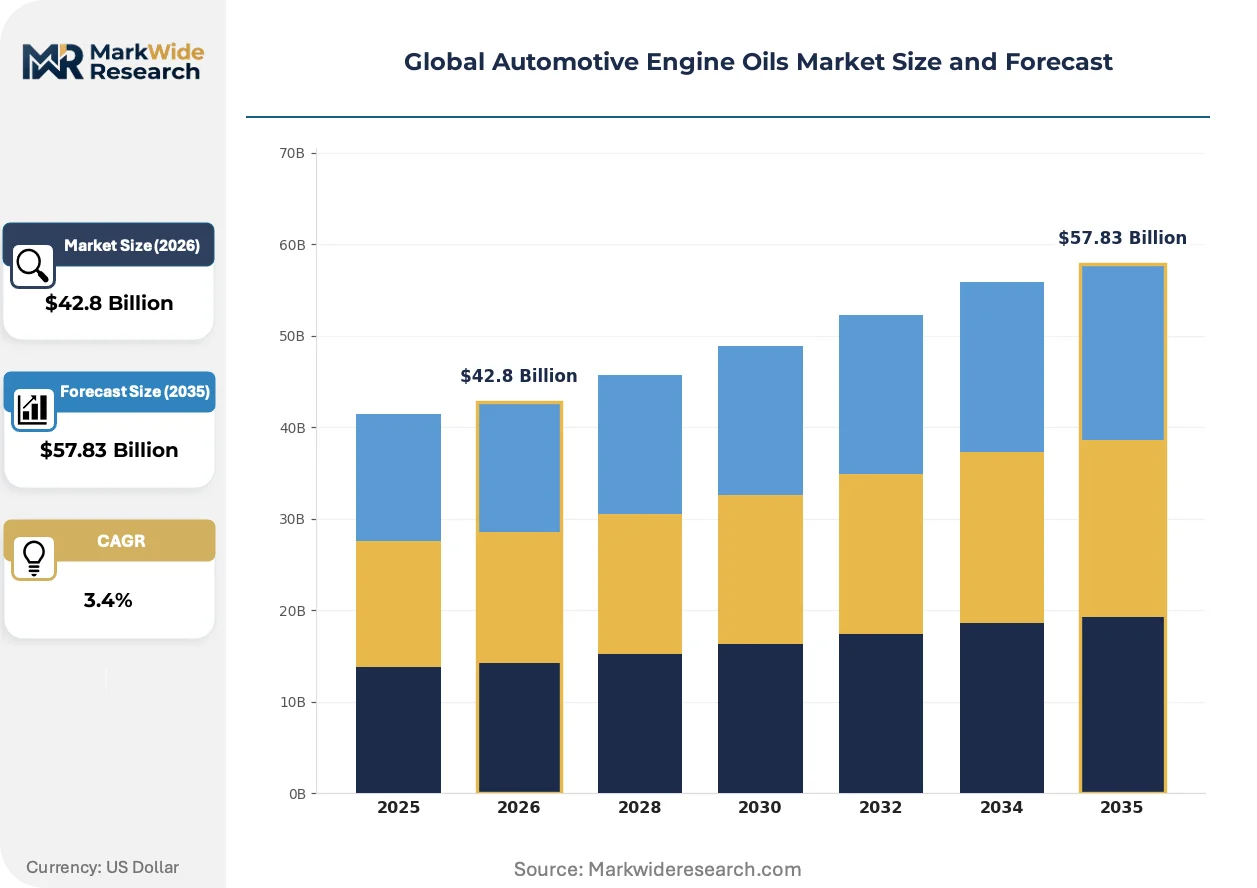
Market Dynamics
Fleet operators and OEMs are forcing a viscosity-grade compression across the lubricant value chain as fuel-economy mandates harden and hybrid powertrains proliferate, fragmenting legacy formulation portfolios.
Growth Catalysts
- EU Green Deal compliance pressure:ACEA C sequences and tightened CO2 targets are mandating lower-viscosity formulations that extend drain intervals and reduce frictional losses in passenger vehicles.
- China's NEV-hybrid scaling:Domestic vehicle production is surging and MIIT GB standards are converging with ILSAC GF-6, creating captive demand for compatible lubricant chemistries.
- Commercial fleet economics:Severe-duty operators are prioritizing synthetic PAO and ester-base stocks to compress total cost of ownership through extended service intervals.
Market Restraints
- Group II/III base oil supply concentration:Asian refinery capacity expansions in South Korea and Singapore are creating dependency on a narrow supplier base for high-quality feedstocks.
- Additive package cost volatility:Molybdenum and phosphorus chemistries face price instability driven by mining concentration and export restrictions.
- Technical ceiling on viscosity reduction:Boundary lubrication failures at sub-0W-16 grades limit how far formulations can stretch without compromising engine protection.
Strategic Opportunities
- Indonesia blending capacity expansion:Jakarta and Surabaya are emerging as ASEAN formulation hubs for 5W-30 and 0W-20 grades serving right-hand-drive markets.
- Hybrid-dedicated oil segmentation:Stop-start wear protection and electrical compatibility requirements are opening formulation white space distinct from legacy ICE products.
- US IRA clean-vehicle incentives:Tax credits for domestic EV and hybrid production are indirectly stimulating lubricant demand through powertrain diversification.
Industry Challenges
- Multi-certification complexity:Simultaneous compliance with API SP, ILSAC GF-6, ACEA C5, and JASO MA2 is stretching R&D timelines and testing budgets.
- Formulation chemist scarcity:Deep expertise in tribology and additive synergy is concentrating at a handful of legacy suppliers, constraining new market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engine Oils Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $57.83 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, Semi-Synthetic, High Mileage Application: Passenger Vehicles, Commercial Vehicles, Off-Highway Vehicles, Marine Engines Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-40, 20W-50 Distribution Channel: Aftermarket, OEM Supply, Online Retail, Specialty Stores |
| Companies Covered | Chevron Corporation, Valvoline, ExxonMobil Corporation, Sinopec Group, PetroChina, Royal Dutch Shell, TotalEnergies, Fuchs Petrolub, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engine Oils Market Shifts & Advancements
Formulation science is pivoting toward powertrain-agnostic chemistries as hybrid architectures blur the line between dedicated electric and combustion lubrication requirements.
Synthetic base stocks are migrating from polyalphaolefin dominance toward Group III+ and gas-to-liquid hybrids that balance cost and performance. Japanese OEMs are accelerating adoption of 0W-8 and 0W-12 grades for next-generation Atkinson-cycle engines. This viscosity compression is forcing additive suppliers to redesign dispersant and anti-wear packages around thinner film regimes.
REACH and the EU F-Gas Regulation are tightening volatility specifications and restricting certain sulfur and phosphorus chemistries in passenger vehicle lubricants. The industrial consequence is a reformulation wave across mid-tier products previously optimized for cost rather than emissions compliance. Germany and France are seeing the fastest compliance-driven product turnover as domestic OEMs advance their electrification timelines.
Fleet procurement is consolidating around total-fluid-management contracts that bundle oil analysis, filtration, and disposal services. Independent workshops and quick-lube chains are losing share to OEM-captive service networks and direct fleet relationships. This channel compression is most visible in the US and Germany where telematics-enabled condition monitoring enables predictive drain scheduling.
Global Automotive Engine Oils Market Segmentation
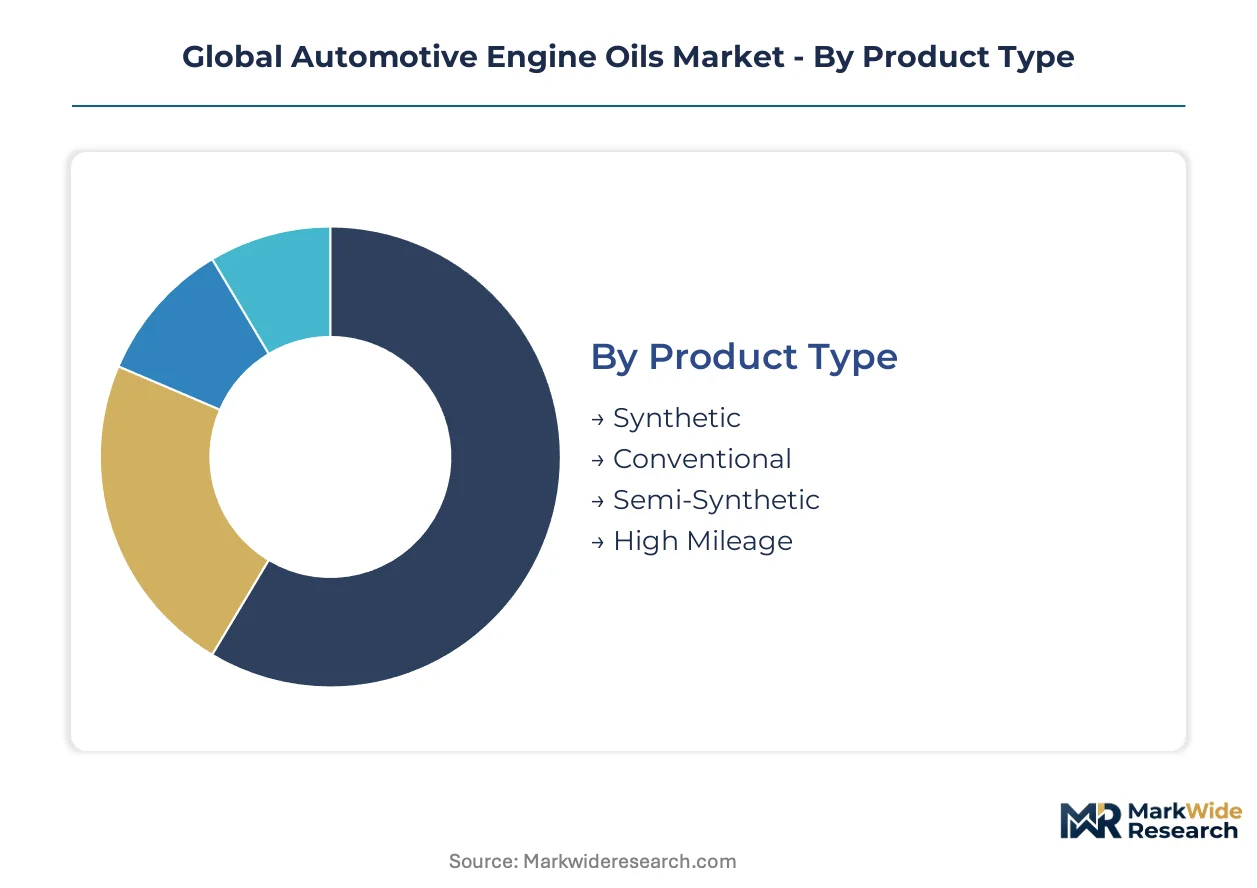
Segmentation in automotive engine oils reveals distinct margin architectures and service intensity profiles. Aftermarket channels demand broad SKU coverage and technical support infrastructure, while OEM supply contracts prioritize formulation lock-in and certification compliance. Understanding these segment boundaries guides resource allocation across base stock procurement, additive R&D, and distribution partnerships.
Product Type:
After-sales service intensity varies sharply across lubricant chemistries, with synthetic formulations requiring diagnostic support for extended drain intervals and conventional products demanding higher transaction frequency.
- Synthetic:Polyalphaolefin and ester-based formulations achieve viscosity stability across temperature extremes. Fleet operators in Germany and Japan concentrate procurement here, driven by total-cost-of-ownership compression through extended service intervals. OEM fill specifications from Toyota and Volkswagen mandate synthetic chemistry for warranty compliance.
- Conventional:Mineral base stocks dominate emerging market price-sensitive segments. Demand concentrates in India and Indonesia where independent workshops service aging vehicle parc with high-frequency oil changes.
- Semi-Synthetic:Group II/III blends balance performance and cost for mid-tier passenger vehicles in Brazil and Mexico.
- High Mileage:Seal conditioners and anti-wear additives target vehicles exceeding 120,000 kilometers, with strongest uptake in the US and Australia where light-duty truck parc ages.
By volume, Conventional leads. By growth pace, Synthetic is expanding most quickly.
Application:
Cost tier separation defines competitive positioning across vehicle categories, with commercial vehicles generating per-unit revenue premiums through severe-duty formulations.
- Passenger Vehicles:Lower viscosity grades dominate as EPA and EU fuel economy standards harden. ILSAC GF-6 and ACEA C5 specifications drive formulation complexity in the US and France.
- Commercial Vehicles:Heavy-duty diesel engines in long-haul fleets across the US and China demand 15W-40 and 10W-40 grades with extended drain capability. Severe-duty operators prioritize synthetic PAO stocks to minimize downtime.
- Off-Highway Vehicles:Construction and mining equipment in Australia and Canada requires high-detergent packages for contaminant-heavy operating environments.
- Marine Engines:Saltwater corrosion resistance and biodegradability specifications shape demand in Norway and Japan where coastal regulations tighten.
Passenger Vehicles generate the highest absolute volume. Commercial Vehicles command the steepest expansion trajectory in value terms.
Viscosity Grade:
Volume concentration clusters around grades balancing cold-start protection and high-temperature film strength, with OEM mandates compressing the portfolio toward thinner formulations.
- 0W-20:Ultra-low viscosity for hybrid and Atkinson-cycle engines. Japanese OEMs in Toyota City and Honda's Saitama operations specify this grade for next-generation powertrains.
- 5W-30:The workhorse specification bridging fuel economy and protection. European OEMs in Stuttgart and Wolfsburg mandate this grade for turbocharged gasoline direct injection engines.
- 10W-40:Legacy fleet maintenance and warmer climate markets in Thailand and Vietnam sustain demand.
- 15W-40:Heavy-duty diesel standard for commercial fleets in the US and China where API CK-4 and FA-4 specifications apply.
- 20W-50:High-temperature protection for older vehicles and tropical climates in Nigeria and Saudi Arabia.
5W-30 commands the largest volume share. 0W-20 is climbing the fastest as hybrid penetration accelerates.
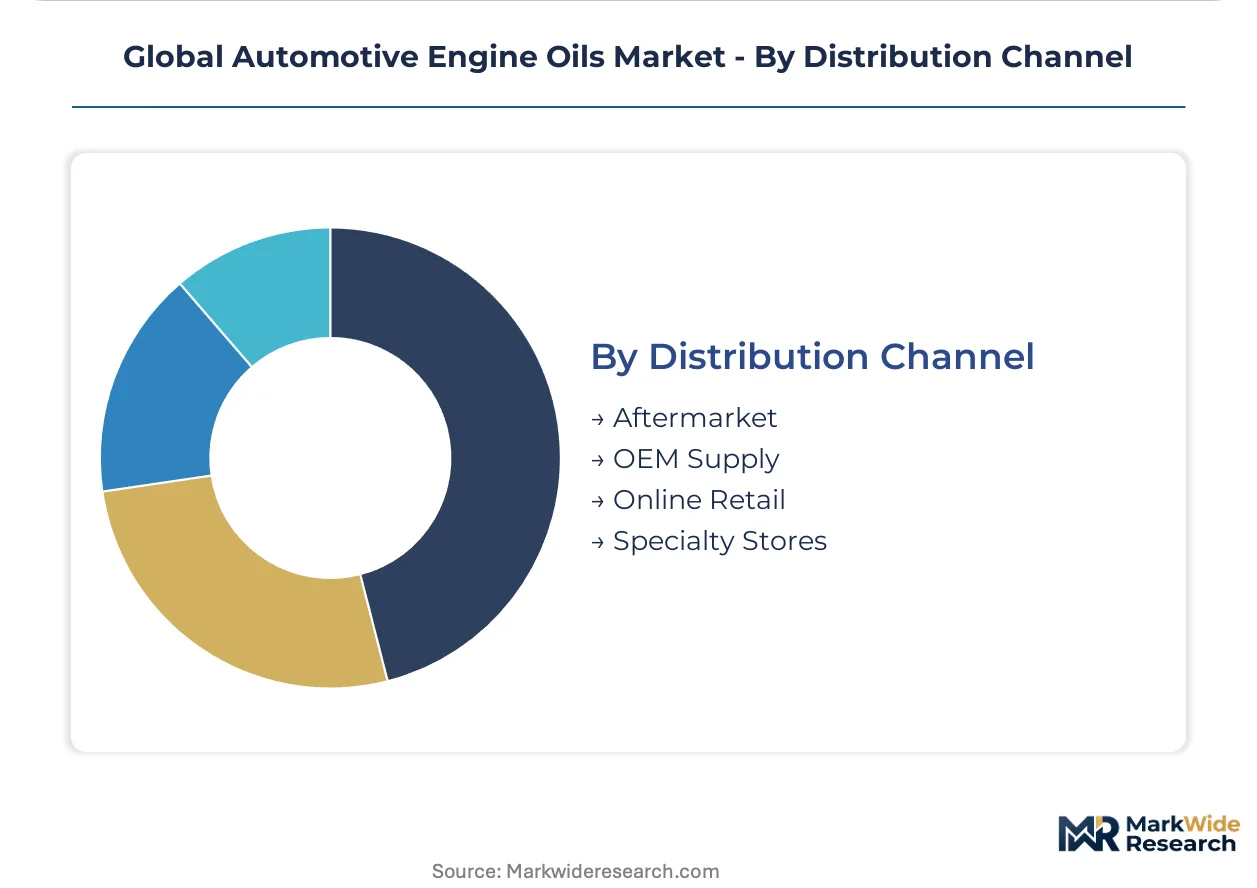
Distribution Channel:
Customer type fragmentation separates transactional retail from relationship-driven fleet and OEM supply, with channel choice determining margin capture and inventory risk.
- Aftermarket:Independent workshops, quick-lube chains, and auto parts retailers in the US and Germany sustain high SKU breadth. Service bays require technical training support and oil analysis programs.
- OEM Supply:Factory fill and captive service networks lock in long-term formulation partnerships. Volkswagen's Wolfsburg operations and Toyota's Kentucky plants specify approved supplier lists with multi-year contracts.
- Online Retail:Amazon and specialized lubricant e-commerce in the UK and South Korea gain share among DIY enthusiasts and small fleet operators.
- Specialty Stores:Performance automotive retailers in California and Tokyo serve enthusiast segments with racing-specification formulations.
Aftermarket channels dominate volume throughput. OEM Supply contracts are gaining share fastest as telematics-enabled predictive maintenance consolidates fleet relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes automotive engine oils at volumes reflecting its vehicle production dominance, while Germany and Japan prioritize ultra-low viscosity synthetic grades for fuel economy compliance. The United States sustains bifurcated demand across conventional fleet maintenance and premium synthetic factory fill.
China
Domestic vehicle production scaling and NEV-hybrid proliferation are reshaping lubricant specifications. MIIT GB standards convergence with ILSAC GF-6 mandates compatible formulations for domestic OEMs. Shanghai and Guangzhou blending clusters are expanding Group III base oil processing to serve captive demand from BYD and Gelectric vehicle supply chains.
Germany
ACEA C5 and C6 sequences are accelerating 0W-20 and 5W-30 adoption across Stuttgart and Wolfsburg OEM operations. The EU Green Deal tightens CO2-linked lubricant specifications through 2035. Bavaria's additive R&D corridor concentrates formulation expertise for turbocharged gasoline direct injection engines.
United States
Commercial fleet operators in Texas and California are compressing total cost of ownership through extended drain interval synthetics. EPA fuel economy standards and IRA clean-vehicle incentives are indirectly stimulating powertrain-diversified lubricant demand. The Gulf Coast petrochemical corridor anchors Group II/III base oil supply for North American formulation.
Japan
Atkinson-cycle engine proliferation and hybrid stop-start architectures are mandating 0W-8 and 0W-12 grades from Toyota and Honda. METI efficiency regulations align lubricant specifications with corporate average fuel economy targets. Nagoya and Saitama formulation centers specialize in electrical compatibility and wear protection chemistries.
India
Price-sensitive independent workshops in Maharashtra and Gujarat sustain conventional oil demand for aging vehicle parc. BIS standards evolution and commercial fleet modernization are gradually penetrating synthetic adoption. The Jamnagar refining complex is expanding Group II capacity to reduce import dependency for high-quality base stocks.
Global Automotive Engine Oils Market Competitive Landscape
Capability concentration sits with formulation specialists commanding multi-certification expertise; scale advantage sits with integrated energy majors controlling base oil supply. The market structures around three tiers: global lubricant majors with captive additive development, regional blenders with distribution density, and national oil companies with feedstock security. Dominant competitive moves include backward integration into Group III base oil production and strategic partnerships with OEMs for factory fill approval.
Among integrated energy majors, ExxonMobil Corporation, Royal Dutch Shell, and Sinopec Group exemplify divergent geographic anchoring and supply chain configurations. ExxonMobil Corporation leverages Singapore hub operations for Asia-Pacific distribution reach. Royal Dutch Shell represents European formulation leadership with upstream base oil control. Sinopec Group occupies a position as captive supplier to domestic Chinese vehicle production, reflecting national oil company vertical integration patterns.
| Leading Market Players |
|---|
| Chevron Corporation |
| Valvoline |
| ExxonMobil Corporation |
| Sinopec Group |
| PetroChina |
| Royal Dutch Shell |
| TotalEnergies |
| Fuchs Petrolub |
| BP |
| Others |
Supply & Pricing Matrix
Singapore's Jurong Island petrochemical cluster anchors Asia-Pacific base oil supply, with capacity expansions in South Korea and Thailand compressing regional feedstock costs and redistributing formulation pricing power toward integrated blenders with captive Group III output.
Pricing Analysis
Geographic price spreads between Rotterdam and Singapore spot markets for Group III base oils routinely exceed fifteen percent, reflecting freight differentials and regional demand imbalances. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy conventional levels segments buyers by total-cost-of-ownership sophistication. Cost compression in the conventional tier is intensifying because Indonesian and Indian independent workshops prioritize transaction value over drain interval extension. Fleet operators in Germany and Japan demonstrate lowest price sensitivity, accepting synthetic premiums for warranty compliance and predictive maintenance integration.
Supply Chain Analysis
Upstream feedstock concentration in South Korea, Singapore, and the US Gulf Coast creates dependency on a narrow supplier base for high-quality Group II and Group III base stocks. Formulation chemistry draws from molybdenum disulfide, phosphorus-based anti-wear packages, and polyalphaolefin synthetic bases. Single-source vulnerability concentrates in specialty additive packages where four global suppliers control dispersant and detergent intellectual property. Distribution runs through regional blending hubs serving OEM factory fill contracts and aftermarket service bay networks with diverging inventory velocity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
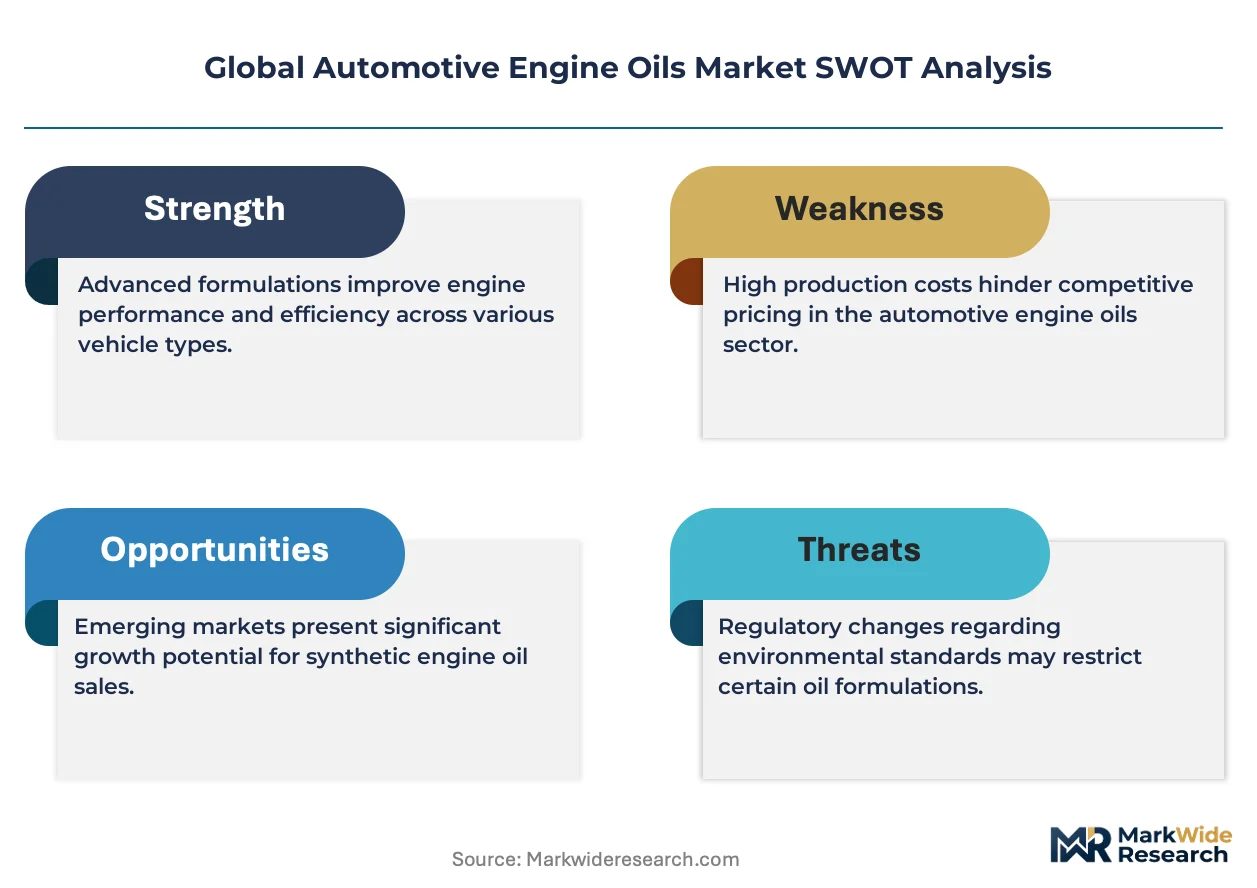
The automotive engine oils market sits at a high-growth inflection as hybrid powertrain proliferation fragments legacy ICE formulation portfolios and EU Green Deal compliance mandates accelerate specification turnover.
For Market Incumbents: Build certification moats by securing simultaneous API SP, ILSAC GF-6, ACEA C5, and JASO MA2 approvals before specification windows close. Anchor capacity in Indonesia and Thailand to capture ASEAN demand for 0W-20 and 5W-30 grades. Defensive consolidation through additive package supplier partnerships mitigates raw material volatility threatening margin stability. For New Entrants and Emerging Players: Establish a beachhead in hybrid-dedicated oil formulations where electrical compatibility and stop-start wear protection requirements create formulation white space distinct from legacy products. Target Indonesia's expanding blending capacity corridor for right-hand-drive market access. Go-to-market through direct fleet procurement relationships bypassing consolidated OEM-captive service networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because additive R&D expertise concentrates at legacy suppliers while regional blenders face feedstock security pressures. Acquisition targets include mid-tier blenders with ASEAN distribution density and captive Group III supply arrangements. Monitor ACEA C6 sequence adoption velocity as the signal for specification complexity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Shell's Pernis refinery and Sinopec's Zhenhai complex secure feedstock autonomy against Asian supply concentration. |
| Hybrid-Dedicated Formulation Development | Toyota and Honda factory fill specifications for 0W-8 grades open premium positioning beyond legacy ICE portfolios. |
| Multi-Certification R&D Investment | Simultaneous ACEA C5, API SP, and ILSAC GF-6 compliance stretches competitor timelines and consolidates share among formulation specialists. |
| ASEAN Blending Capacity Expansion | Indonesia's Jakarta and Surabaya hubs capture right-hand-drive demand growth while reducing freight exposure to Singapore supply. |
| Fleet Total-Fluid-Management Contracts | Telematics-enabled predictive drain scheduling locks in long-term relationships and displaces independent workshop channel volume. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with lubricant formulation chemists, OEM platform engineers, aftermarket distribution managers, and commercial fleet procurement officers; and secondary validation through ACEA oil sequence documentation, API licensing records, MIIT GB standard publications, and customs trade data for base oil flows. Bottom-up triangulation across regional blending capacity and top-down reconciliation against vehicle production forecasts anchored volume estimates.
Forecast inputs considered viscosity grade compression trajectories, NEV-hybrid penetration curves, and regulatory specification evolution across the projection horizon. Segmentation modeling spanned product chemistry tiers, vehicle application categories, viscosity grade specifications, and distribution channel structures. CAGRs derived from elasticity-adjusted demand functions incorporating OEM fill specification mandates and fleet operator total-cost-of-ownership preferences.
Stress conditions across base oil supply disruptions, additive chemistry export restrictions, and accelerated electrification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about specification convergence and hybrid powertrain lubricant demand splits. Cross-checking against IHS Markit vehicle production databases and ACEA registration statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Germany Automotive Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Specialty Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Italy Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Malaysia Automotive Engine Oils Market