
 Bangladesh Lubricants Market | 2026-2036
Bangladesh Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Lubricants Market Insights
Buyer concentration among fleet operators and large transport contractors is realigning procurement patterns across the Bangladesh lubricants aftermarket. Castrol Bangladesh leverages its blending facility in Narayanganj to sustain proximity advantages for industrial accounts. MJL Bangladesh Limited anchors its position through backward integration into base oil trading, while Padma Oil Company Limited competes via its state-linked distribution network reaching rural service stations.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades and oxidation stability determining performance under thermal stress. Engine oil dominates product type revenue due to Bangladesh's expanding vehicle parc and stringent drain interval requirements from OEMs. Industrial oil applications in textile and jute processing machinery represent the fastest-growing segment as factory automation spreads through Gazipur and Ashulia. Marine lubricants command premium positioning through specialized high-base-number formulations for two-stroke crosshead engines serving Chittagong port traffic.
The Bangladesh Standards and Testing Institution enforces lubricant quality benchmarks under BIS-equivalent protocols, while the Department of Environment monitors used oil disposal under hazardous waste rules. These frameworks compel reformulation toward higher-tier API specifications and certified recycling infrastructure. Stakeholders must weigh import dependency against local blending capacity investments as regulatory compliance costs reshape margin structures.
Market Dynamics
Fleet consolidation across Bangladesh's road freight sector is compressing procurement cycles and forcing blenders to negotiate volume contracts with fewer, larger buyers holding concentrated purchasing power.
Growth Catalysts
- API SP/SP-RC specifications:The Bangladesh Energy Regulatory Commission's tightening fuel quality standards mandate higher-grade lubricant formulations for diesel and gasoline engines, pulling demand toward premium synthetic blends.
- Textile automation clusters:Factory automation spreading through Gazipur and Ashulia is generating fresh demand for hydraulic and compressor oils in spinning and weaving machinery.
- Chittagong port traffic:Container throughput growth at Bangladesh's primary maritime gateway sustains specialized marine lubricant demand for two-stroke crosshead engines.
Market Restraints
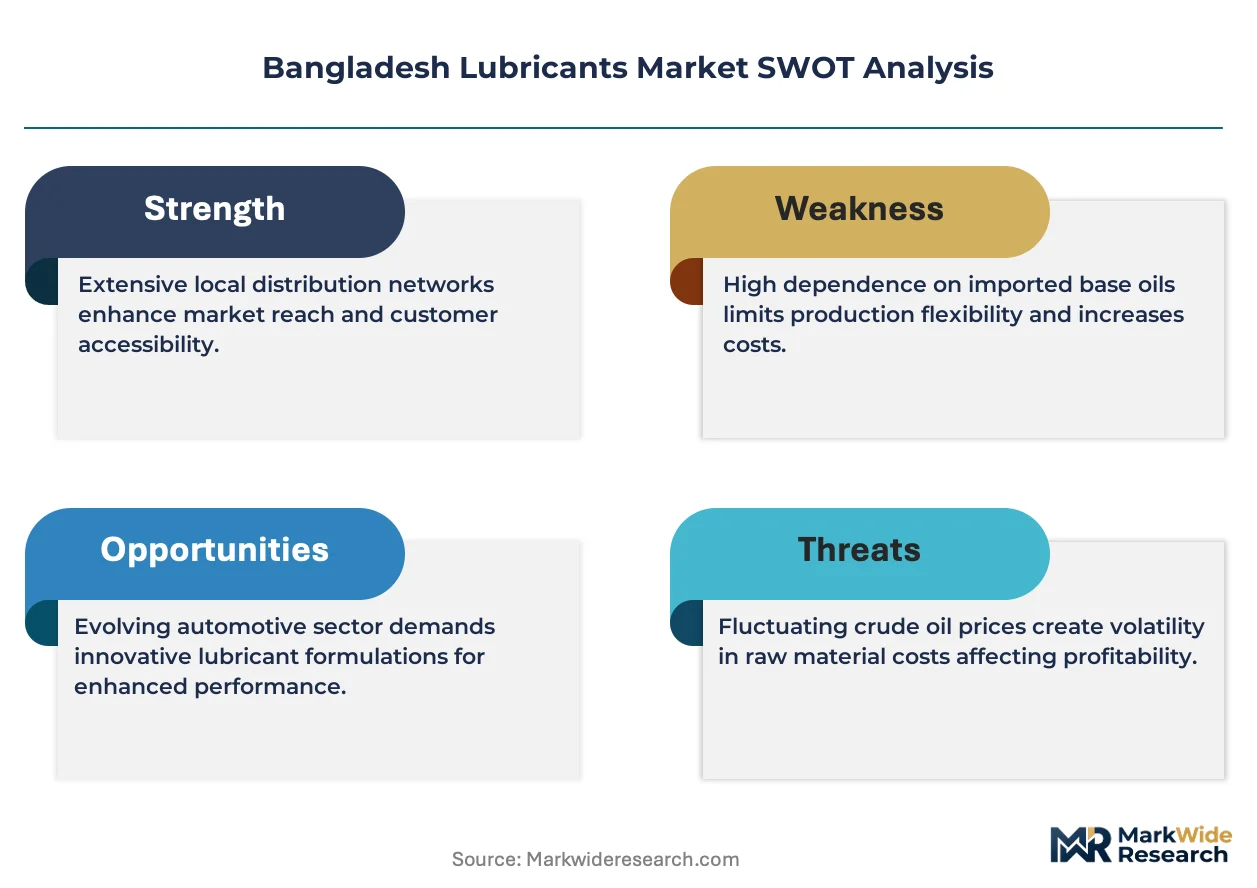
- Base oil import dependency:Bangladesh lacks domestic Group II/III base oil refining, exposing blenders to freight cost volatility and currency fluctuation risks on Singapore-sourced feedstock.
- Used oil disposal infrastructure gaps:The Department of Environment's hazardous waste rules lack certified collection networks, creating compliance friction for drain oil recycling mandates.
- Counterfeit lubricant penetration:Unbranded repackaging operations in informal channels erode quality assurance and price discipline for licensed distributors.
Strategic Opportunities
- Sylhet and Rangpur hinterlands:Agricultural mechanization in northern and northeastern districts remains underpenetrated by branded lubricant distribution, offering first-mover expansion potential.
- Renewable energy lubricants:Wind turbine gear oils and transformer fluids for grid-scale solar installations represent nascent product categories with limited domestic competition.
- Bangladesh Standards and Testing Institution certification:Early alignment with BIS-equivalent quality protocols positions suppliers for preferential treatment in public sector procurement tenders.
Industry Challenges
- Formulation chemist scarcity:Local technical talent pools lack depth in additive chemistry and tribology, forcing reliance on foreign technical service support.
- Blending facility capex cycles:Automated batching systems and in-line blending investments require capital deployment ahead of demand confirmation in a price-sensitive market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Lubricants Market |
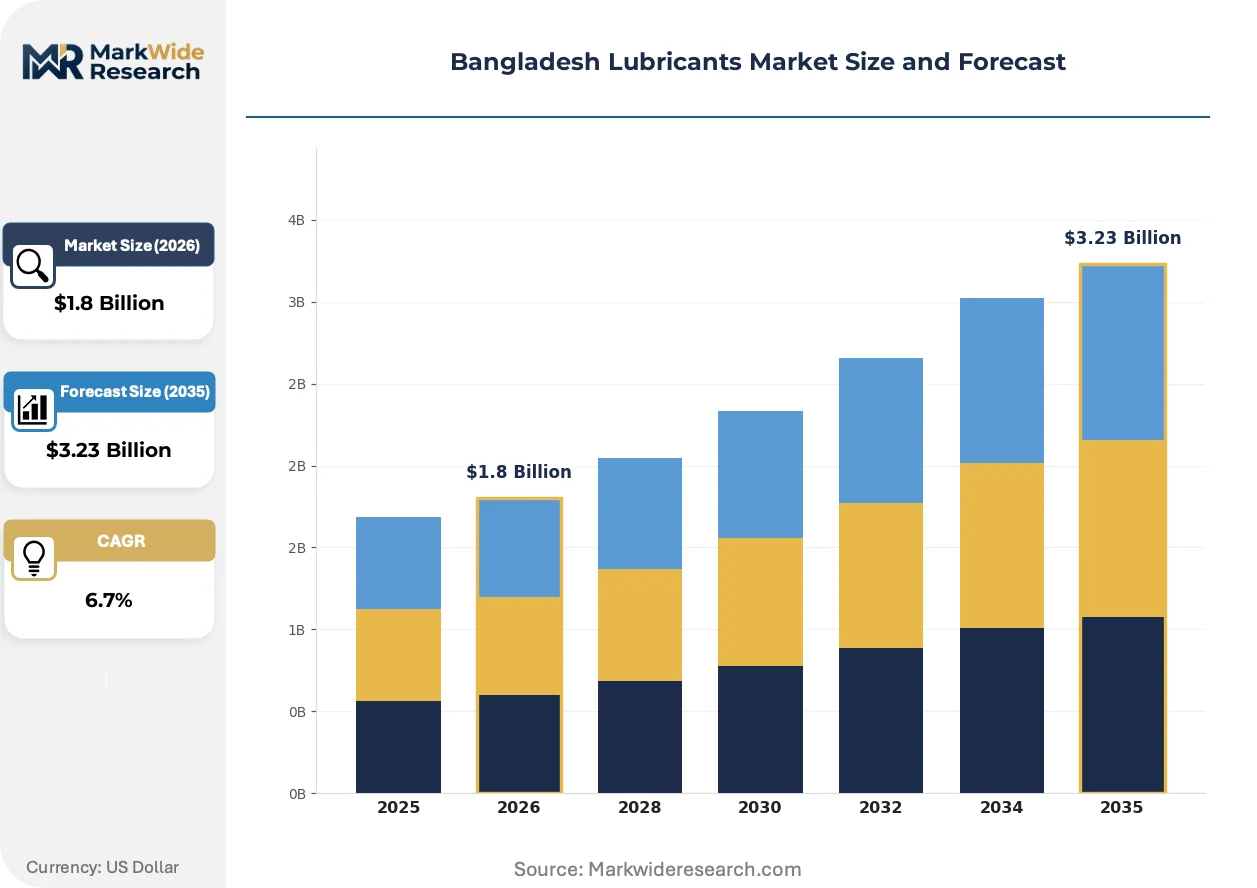
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Industrial Oil Application: Automotive, Marine, Industrial Machinery, Heavy Equipment End User: OEMs, Aftermarket, Manufacturing, Transportation Packaging Type: Bulk, Drums, Pails, Bottles |
| Companies Covered | BP p.l.c., Castrol Bangladesh, Padma Oil Company Limited, TotalEnergies, ExxonMobil, MJL Bangladesh Limited, Shell plc, Sigma Oil Industries Ltd, Lub-rref (Bangladesh) Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Lubricants Market Trends and Innovations
Reformulation toward higher thermal stability and extended drain intervals is reshaping product development priorities across Bangladesh's lubricant value chain. Blenders are racing to align with evolving OEM specifications while managing input cost pressures.
Synthetic base stock technology is integrating Group III and PAO blends into mainstream automotive and industrial formulations. Fleet operators with centralized maintenance contracts are adopting these products to compress vehicle downtime and extend service intervals. This shift is enabling premium pricing for products demonstrating measurable total cost of ownership reduction against mineral oil benchmarks.
The Bangladesh Energy Regulatory Commission's fuel quality standards are tightening additive specifications nationwide. Blenders must reformulate detergents, dispersants, and anti-wear packages to maintain compliance with sulfur and phosphorus limits. Engine oil product lines face the steepest reformulation costs, with industrial accounts in the Dhaka-Chittagong corridor absorbing price adjustments more readily than dispersed agricultural buyers.
Consolidated fleet procurement is displacing fragmented retail purchasing among large transport contractors. Volume-based annual contracts with direct blender relationships are replacing distributor-mediated spot buying. This concentration is most visible along the Dhaka-Chittagong highway corridor where logistics companies operate centralized maintenance depots.
Bangladesh Lubricants Market Segmentation
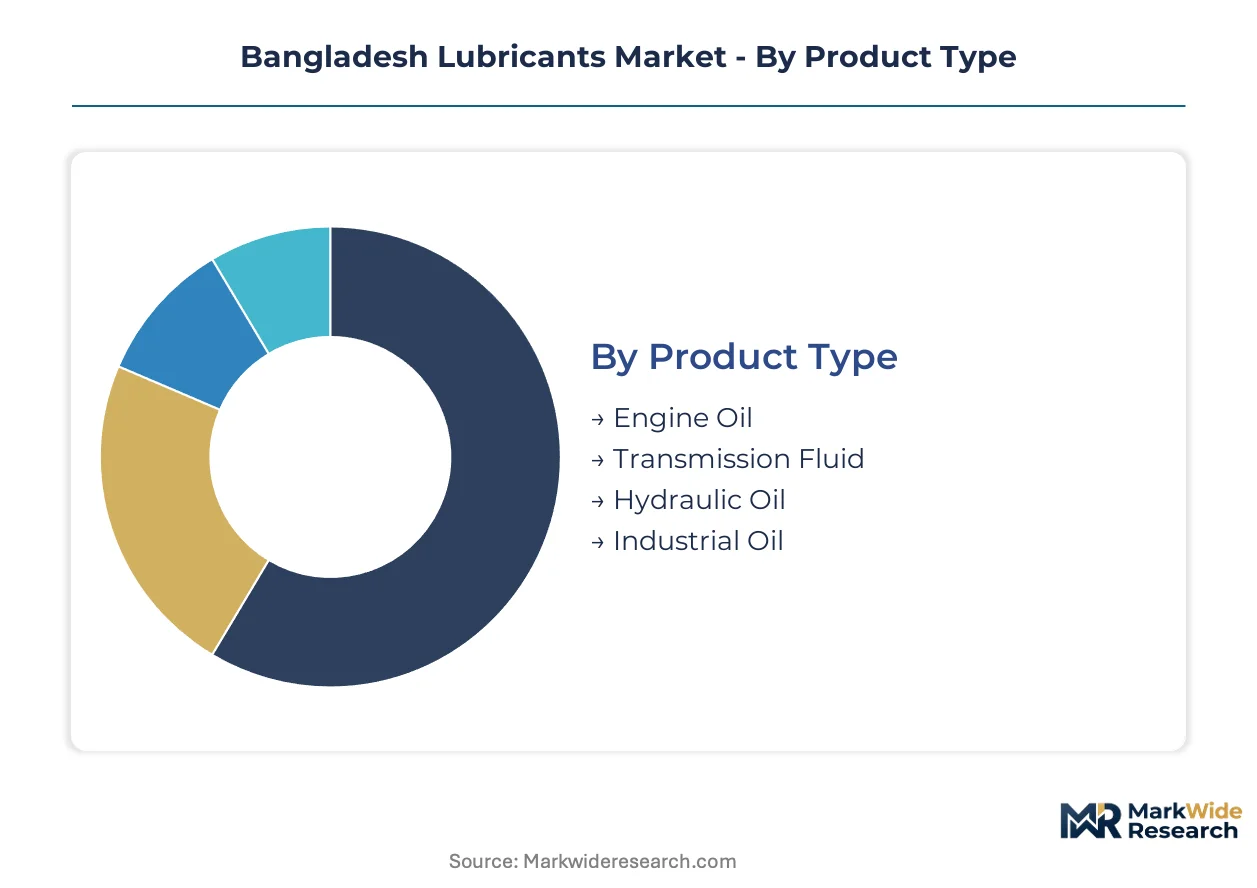
Lubricant demand in Bangladesh fragments across distinct performance tiers and procurement channels. Fleet consolidation and factory automation are compressing these segments into fewer, larger purchasing relationships with specific technical requirements.
Product Type:
Engine oil commands the volume premium, while industrial formulations capture margin expansion from automation-driven specification upgrades.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages meeting API SP specifications. Demand concentrates in Dhaka-Chittagong fleet depots where consolidated transport contractors negotiate annual volume contracts against drain interval guarantees.
- Industrial Oil:Hydraulic, compressor, and turbine formulations serving textile automation in Gazipur-Ashulia clusters. Factory modernization programs specify higher viscosity index and oxidation stability, pulling procurement toward synthetic blends despite price sensitivity in dispersed agricultural markets.
- Transmission Fluid:ATF and gear oil formulations for commercial vehicle drivetrains, with demand tracking HCV parc expansion along the Dhaka-Chittagong corridor.
- Hydraulic Oil:Anti-wear formulations for construction and material handling equipment, concentrated in infrastructure project zones.
Today's leader: Engine Oil. Tomorrow's challenger: Industrial Oil.
Application:
Automotive applications anchor volume throughput, while marine lubricants sustain premium positioning through specialized formulation requirements.
- Automotive:Passenger car and commercial vehicle lubrication spanning engine, transmission, and axle applications. Fleet operators in the Dhaka-Chittagong industrial corridor are consolidating procurement through direct blender relationships, displacing fragmented retail purchasing.
- Marine:High-base-number cylinder oils and system oils for two-stroke crosshead engines serving Chittagong port container traffic. Specialized formulations command technical service bundling and long-term supply agreements with shipping lines.
- Industrial Machinery:Textile spinning, weaving, and processing equipment in Gazipur and Ashulia manufacturing zones.
- Heavy Equipment:Construction and mining machinery lubrication tied to infrastructure development cycles.
Marine applications retain the steepest pricing power. Industrial machinery is expanding most quickly.
End User:
Aftermarket consolidation is outpacing OEM fill demand, while manufacturing accounts absorb specification upgrades faster than transport buyers.
- Aftermarket:Service stations, independent workshops, and fleet maintenance depots purchasing packaged lubricants for drain-and-fill operations. Concentrated buying power among large transport contractors is compressing distributor margins and favoring direct blender contracts.
- Manufacturing:Textile, jute processing, and light industrial facilities procuring hydraulic and compressor oils for automated production lines. Ashulia and Gazipur factory clusters demonstrate higher specification tolerance than dispersed rural equipment owners.
- OEMs:Factory-fill agreements with vehicle and machinery assemblers for initial lubricant charge.
- Transportation:Fleet operators and logistics companies with centralized maintenance infrastructure.
Aftermarket volume dominates current procurement. Manufacturing specifications are climbing fastest.
Packaging Type:
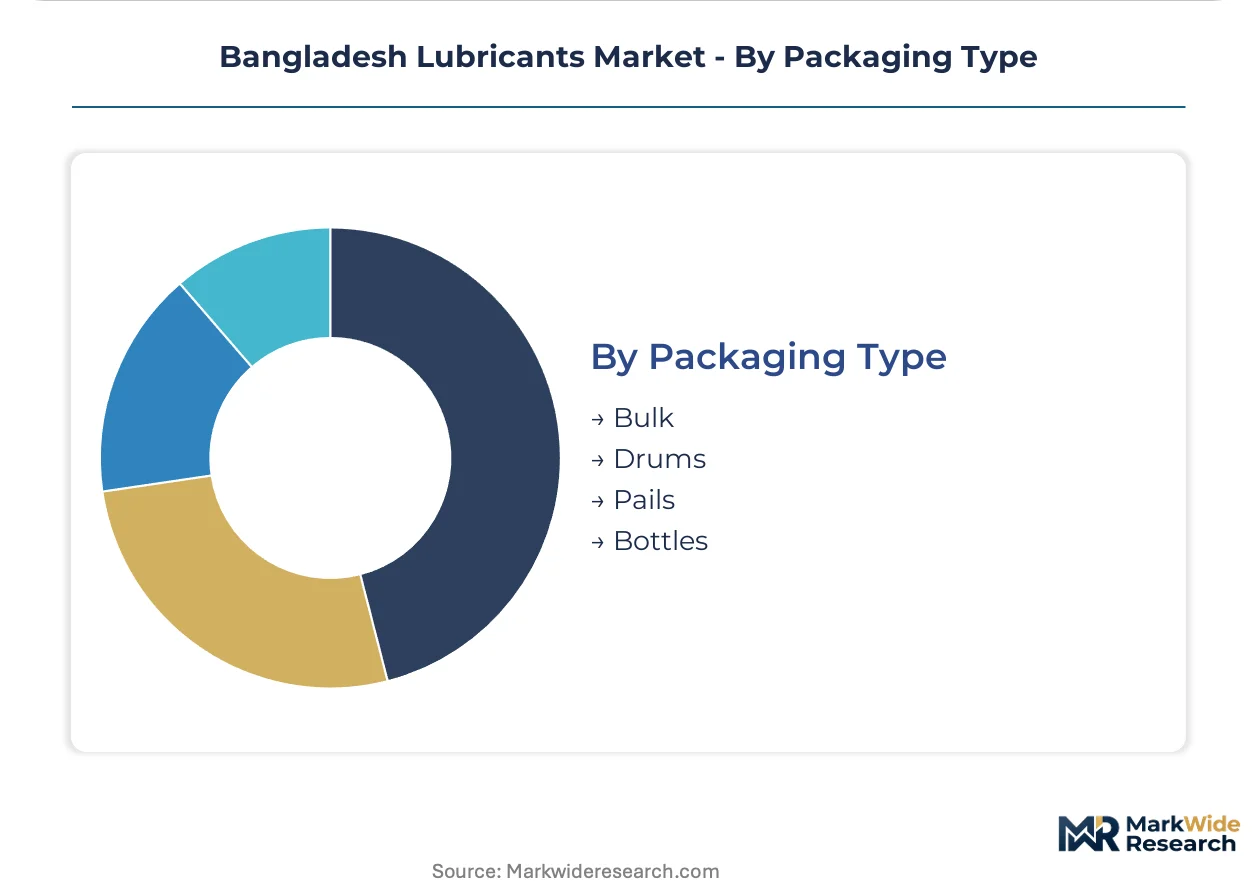
Bulk delivery serves consolidated industrial accounts, while packaged formats retain relevance in fragmented retail channels.
- Bulk:Tanker truck and flexitank delivery to fleet depots and manufacturing facilities with on-site storage. Dhaka-Chittagong corridor logistics companies favor this format for cost compression and inventory reduction.
- Drums:Standard 200-liter steel containers for mid-scale industrial and commercial vehicle workshop consumption.
- Pails:20-liter plastic containers bridging workshop and retail service applications.
- Bottles:1-liter to 5-liter retail packaging for passenger car DIY and small workshop segments, facing counterfeit infiltration in informal channels.
Bulk formats lead industrial procurement. Bottle packaging faces the steepest competitive pressure from unbranded repackaging operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent pools in tribology and additive chemistry concentrate in Dhaka and Chittagong, anchoring formulation expertise for the national market. These clusters support blending operations and quality testing infrastructure across the industrial corridor.
Dhaka Division
Fleet consolidation among road freight operators and textile automation in Gazipur-Ashulia drive lubricant procurement volumes. The Bangladesh Standards and Testing Institution enforces BIS-equivalent quality protocols from its capital-based laboratories. Narayanganj hosts blending facilities supplying industrial accounts with hydraulic and compressor oils for automated spinning machinery.
Chittagong Division
Container throughput growth at the port sustains specialized marine lubricant demand for two-stroke crosshead engines. The Department of Environment monitors used oil disposal under hazardous waste rules with regional enforcement offices. Chittagong city anchors distribution networks reaching shipping lines and heavy equipment maintenance depots.
Khulna Division
Mongla port activity and jute processing machinery create industrial oil demand outside the primary corridor. The Bangladesh Energy Regulatory Commission's fuel quality standards apply uniform additive specifications nationwide. Khulna city clusters smaller blending operations serving southwestern manufacturing and agricultural equipment markets.
Rajshahi Division
Agricultural mechanization in northern districts generates diesel engine oil demand from tractor and power tiller fleets. The country's national environmental regulator extends hazardous waste compliance requirements to regional collection points. Bogra and Rangpur cities remain underpenetrated by branded distribution, offering expansion potential for packaged lubricant formats.
Sylhet Division
Tea estate machinery and emerging gas field equipment sustain niche industrial lubricant requirements. The Bangladesh Standards and Testing Institution's certification protocols enable public sector procurement participation for compliant suppliers. Sylhet city serves as a distribution node for northeastern hinterland markets with limited direct blender presence.
Bangladesh Lubricants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Bangladesh's lubricant value chain. The market structure shows moderate consolidation, with multinational blenders holding industrial accounts while local distributors retain rural retail penetration. Three archetypes dominate: global majors with captive blending infrastructure, state-linked entities leveraging distribution networks, and independent blenders competing on price in fragmented channels. Capacity expansion and backward integration into base oil trading represent the primary competitive vectors.
Among global majors with local blending presence, Castrol Bangladesh and Shell plc exemplify the integrated multinational archetype. MJL Bangladesh Limited anchors the independent blender tier through upstream control over base oil sourcing. Padma Oil Company Limited occupies a position within the state-linked distribution segment, leveraging its network reach across rural service stations.
| Leading Market Players |
|---|
| BP p.l.c. |
| Castrol Bangladesh |
| Padma Oil Company Limited |
| TotalEnergies |
| ExxonMobil |
| MJL Bangladesh Limited |
| Shell plc |
| Sigma Oil Industries Ltd |
| Lub-rref (Bangladesh) Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fleet operator consolidation across the Dhaka-Chittagong corridor is compressing procurement cycles and forcing blenders toward volume-based contract structures that sacrifice margin for throughput security. The Bangladesh Energy Regulatory Commission's additive specification tightening adds reformulation costs that suppliers must recover through premium tier positioning or absorb through base oil trading efficiencies.
Pricing Analysis
Capacity additions in Narayanganj and Chittagong are reshaping price floors for industrial lubricant contracts. Three-tier pricing structure across premium synthetic, standard mineral, and economy repackaged levels dominates the market, with API SP certification grade and volume scale serving as the primary differentiation drivers. Cost compression in the economy tier is intensifying because unbranded repackaging operations exploit distribution gaps. Fleet operators with centralized maintenance contracts demonstrate the lowest price sensitivity, while dispersed agricultural equipment owners in Rajshahi and Sylhet divisions resist specification upgrades.
Supply Chain Analysis
Direct-to-industrial channels handle consolidated fleet demand, while distributor networks retain fragmented retail penetration. Geographic supply concentrates in Singapore, South Korea, and Thailand for Group II/III base oil feedstock. Local blending operations draw from imported additive packages and steel drum packaging sourced from regional manufacturing hubs. Single-source vulnerability in Singapore-sourced base oil creates exposure to freight cost volatility and currency fluctuation. Distribution runs through state-linked rural service stations, independent workshops, and direct blender relationships with large transport contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh lubricant production offers geographic-arbitrage potential against Indian and Southeast Asian supply bases due to lower labor costs and preferential tariff treatment under regional trade frameworks. The country's position as a base oil deficit market with growing industrial demand creates structural margin capture opportunities for integrated operators.
For Market Incumbents: Anticipate margin compression from fleet procurement consolidation by securing backward integration into base oil trading and expanding Narayanganj blending capacity ahead of competitor additions. Counterfeit lubricant infiltration through informal channels threatens brand equity and requires channel control investments in certified distributor authentication programs. For New Entrants and Emerging Players: Capture first-mover positioning in Sylhet and Rangpur agricultural mechanization segments where branded distribution remains underpenetrated. The renewable energy lubricant category for wind turbine gear oils presents white-space expansion with limited domestic competition. A go-to-market angle bundling technical service support with Bangladesh Standards and Testing Institution certification compliance accelerates public sector procurement access. For Investors and Strategic Acquirers: Asymmetric upside sits with independent blenders possessing captive base oil sourcing relationships and established industrial account portfolios. Long-term viability hinges on regulatory compliance infrastructure and formulation chemistry capabilities rather than pure distribution scale. Watch API specification upgrade announcements from the Bangladesh Energy Regulatory Commission as the inflection signal for premium product mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Trading | MJL Bangladesh Limited's upstream control reduces Singapore feedstock exposure and stabilizes margin structures. |
| Blending Facility Capacity Expansion | Narayanganj investments by Castrol Bangladesh secure proximity advantages for Dhaka-Chittagong industrial corridor accounts. |
| Bangladesh Standards and Testing Institution Certification | Early BIS-equivalent alignment positions suppliers for preferential public sector procurement tender treatment. |
| Renewable Energy Lubricant Product Development | Wind turbine gear oils and solar transformer fluids address nascent grid-scale installation demand with limited competition. |
| Direct Fleet Contracting Model | Volume-based annual agreements with consolidated transport operators displace distributor-mediated spot purchasing. |
Research Methodology
Direct dialogue with blending plant managers, fleet procurement directors, textile factory maintenance heads, and base oil trading specialists grounded this analysis in operational reality. Secondary validation drew from Bangladesh Standards and Testing Institution certification records, Bangladesh Energy Regulatory Commission fuel quality directives, Department of Environment hazardous waste compliance filings, and customs trade data on base oil imports. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification of volume estimates.
Bottom-up modeling anchored forecasts in product-type demand drivers, application-specific growth rates, and end-user procurement pattern shifts across the projection horizon. Segmentation dimensions included product formulation tier, end-use industry cluster, packaging format preference, and regional distribution density. CAGRs emerged from trend extrapolation against vehicle parc expansion, factory automation penetration, and port traffic growth assumptions. Base oil price volatility and currency fluctuation scenarios informed sensitivity testing.
Underlying measurement precision varies by segment; engine oil and industrial lubricant categories carry tighter precision than emerging renewable energy applications. Forecasts reflect assumptions regarding regulatory enforcement consistency, fleet consolidation velocity, and counterfeit market containment. Periodic stress-testing of base assumptions is recommended against Bangladesh Bank monetary policy shifts and Singapore refinery output fluctuations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Textile Machine Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Global Grease Market
Lubricants
Synthetic Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Industrial Gear Oil Market
Lubricants
Global Engineered Fluids Market
Lubricants
Europe Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Global Grease Cartridges Market
Lubricants
Argentina Lubricants Market