
 Vietnam Lubricants Market | 2026-2036
Vietnam Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Lubricants Market Outlook
The capital-intensity gap between integrated refiners and independent blenders is collapsing as national oil companies expand in-house additive compounding. Petrolimex leverages its nationwide fuel station network to lock in retail distribution for passenger car motor oils. PVOIL anchors industrial volume through direct supply contracts with steel and cement plants in Hai Phong and Quang Ninh provinces. Shell Vietnam differentiates via synthetic product lines targeting Japanese and Korean automotive OEMs operating assembly plants in the country.
Lubricants are formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to ISO VG 680 for industrial applications and SAE 0W-20 to 20W-50 for automotive engines. Their primary purpose is extending equipment life and optimizing energy efficiency across powertrain and machinery operations. Engine oils dominate product-type revenue due to Vietnam's twenty-million-plus two-wheeler population and rising passenger vehicle ownership. Industrial applications in manufacturing and transportation end-user segments are outpacing marine and agricultural growth as foreign direct investment flows into electronics and textile factories.
Vietnam's Ministry of Industry and Trade enforces national technical regulations on lubricant quality, while the Directorate for Standards, Metrology and Quality administers TCVN standards that increasingly reference API and ACEA performance categories for import compliance. The country's central bank and planning ministry shape infrastructure spending that indirectly governs construction equipment and heavy truck lubricant demand through state project pipelines. Stakeholders must monitor whether domestic base oil refining investments at Nghi Son and Dung Quat complexes alter import dependency and margin structures for finished lubricant producers.
Market Dynamics
Vietnam's lubricant demand structure is being reconfigured by Euro 5 emission compliance deadlines, which force immediate reformulation of engine oil portfolios toward lower viscosity grades and higher additive loading. This regulatory compression is squeezing independent blenders while rewarding integrated suppliers with captive additive sourcing.
Growth Catalysts
- Industrial FDI Inflows:Foreign electronics and textile manufacturers in the Red River Delta are signing multi-year lubricant supply contracts that lock in volume growth for industrial-grade products.
- Euro 5 Alignment:Vietnam's Ministry of Transport emission standards are mandating API SN Plus and ACEA C3 performance categories, creating mandatory upgrade cycles across the motorcycle and passenger car fleet.
- Base Oil Localization:Refinery investments at Nghi Son and Dung Quat are reducing import dependency for Group II and Group III base stocks, improving margin capture for domestic compounders.
Market Restraints
- Feedstock Volatility:Vietnamese lubricant blenders remain exposed to Singapore spot market pricing for Group II base oil and polyalphaolefin imports, compressing working capital cycles.
- Import Concentration:Additive packages from Singapore and Thailand dominate the technical supply chain, creating single-source vulnerability for small and mid-tier blenders.
- Substitution Pressure:Extended-drain synthetic formulations are compressing lubricant consumption per vehicle-kilometer, offsetting fleet growth in volume terms.
Strategic Opportunities
- Central Highlands Agriculture:Mechanization of coffee and rubber plantations in Dak Lak and Lam Dong provinces is opening demand for tractor hydraulic fluids and transmission oils outside traditional industrial corridors.
- Marine Lubricant Gap:Vietnam's container port expansion at Cai Mep-Thi Vai lacks dedicated marine lubricant bunkering infrastructure, creating white space for coastal supply depots.
- EV Thermal Fluids:Battery electric vehicle assembly by VinFast and foreign OEMs is generating demand for dielectric coolants and e-axle lubricants that existing portfolios do not address.
Industry Challenges
- Formulation Talent Scarcity:Vietnamese universities produce limited lubricant chemists and tribology specialists, forcing blenders to recruit from Thailand and Singapore at premium compensation.
- API Certification Timelines:Third-party testing for API SP and ILSAC GF-6 claims requires 18-24 month validation cycles, delaying product launches behind regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Lubricants Market |
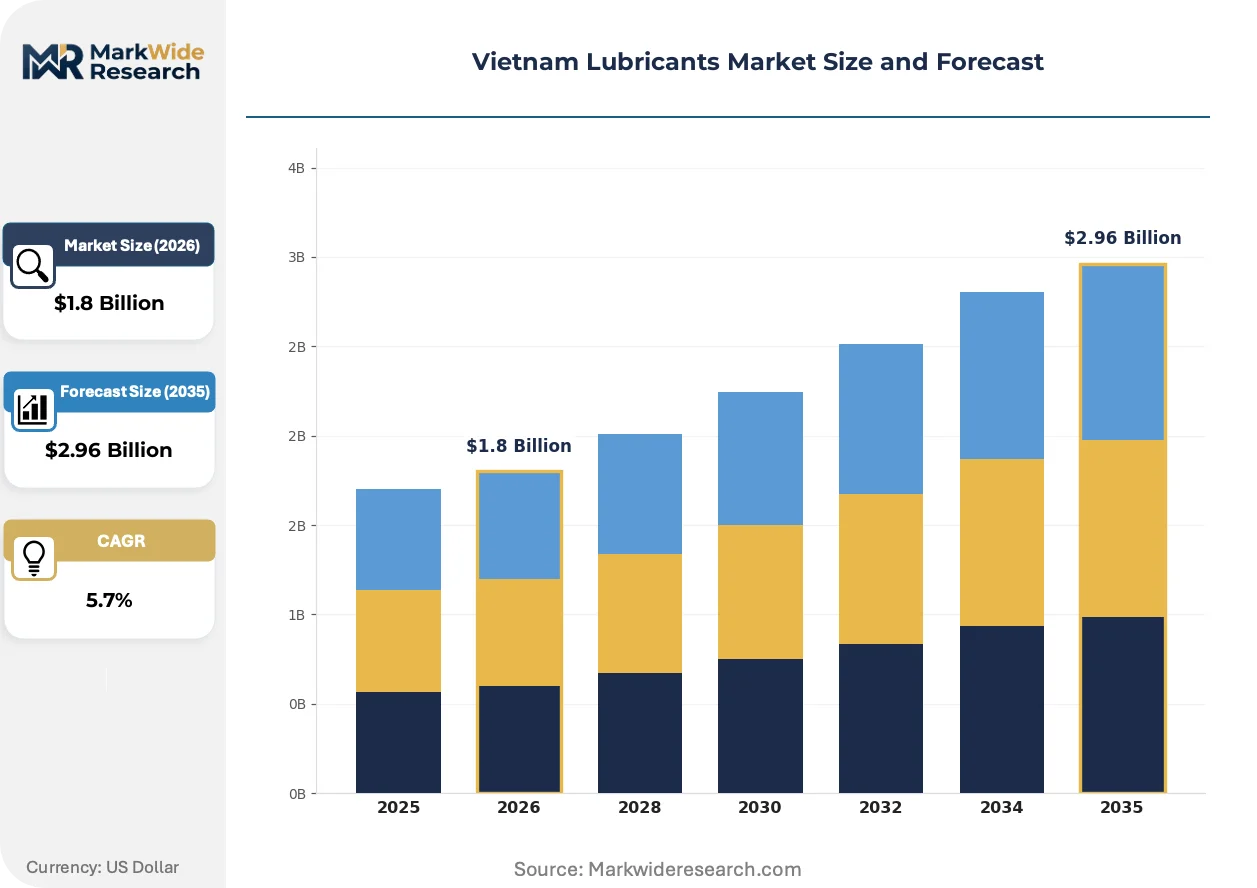
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Gear Oils, Hydraulic Fluids, Greases Application: Automotive, Industrial, Marine, Agricultural End User: Manufacturing, Transportation, Construction, OEMs Distribution Channel: Retail, Wholesale, Online, Distributors |
| Companies Covered | TotalEnergies, Motul Vietnam JSC, Castrol BP Petco, ExxonMobil Corporation, Chevron Corporation, Shell Vietnam, Mekong Petrochemical JSC, PVOIL, Petrolimex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Lubricants Market Strategic Shifts
Reformulation chemistry and supply chain digitization are converging to alter how lubricant specifications are developed, tested, and deployed across Vietnam's fragmented distributor network. These shifts are compressing product lifecycles while raising technical barriers to market entry.
Polyalkylene glycol-based compressor lubricants are fragmenting the industrial maintenance market by offering compatibility with ammonia refrigeration systems now mandated for cold chain expansion. Food processing plants in Long An and Binh Duong provinces are adopting these synthetic alternatives at replacement rates exceeding conventional mineral oils. The technology is fragmenting procurement patterns by forcing maintenance managers to abandon legacy supplier relationships and re-qualify equipment for synthetic chemistries.
Vietnam's Ministry of Industry and Trade is enforcing TCVN 6586 updates that incorporate ACEA C5 and API SP performance benchmarks for all imported passenger car motor oils. This regulatory harmonization is disqualifying lower-tier products from Thailand and Malaysia that previously captured price-sensitive segments. Japanese and Korean OEM assembly plants in Thai Nguyen and Vinh Phuc provinces are now requiring proof of local testing laboratory certification before approving supplier lists.
Fleet operators in Ho Chi Minh City's ride-hailing and delivery segments are consolidating lubricant purchasing through direct distributor agreements rather than retail workshop channels. This buyer concentration is disintermediating traditional motorbike service stations that historically captured 60% of two-wheeler lubricant volume. The shift is most visible among Grab and Be drivers operating under vehicle-leasing programs that specify bulk oil supply contracts with standardized drain intervals.
Vietnam Lubricants Market Segmentation
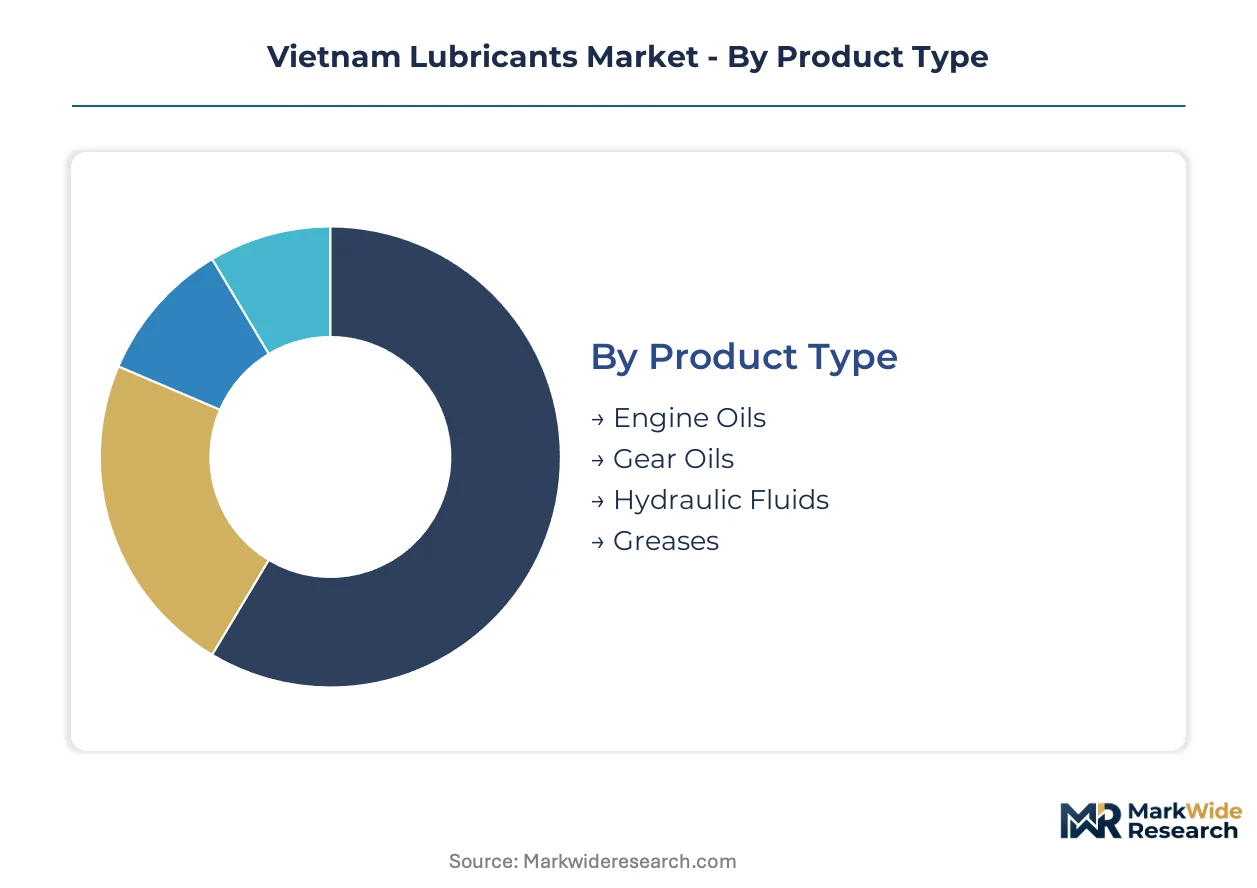
Vietnam's lubricant segmentation reflects a bifurcated demand structure: automotive products flow through Ho Chi Minh City's dense retail networks, while industrial grades anchor foreign-invested manufacturing clusters in the Red River Delta. Understanding these segment boundaries clarifies where formulation investments and distribution infrastructure must concentrate.
Product Type:
Domestic consumption dominates engine oil volumes through Vietnam's twenty-million-plus motorcycle fleet, whereas gear oils and hydraulic fluids increasingly serve export-oriented manufacturing equipment.
- Engine Oils:Formulated from Group II and Group III base stocks with additive packages meeting API SP and ACEA C3 specifications, these lubricants reduce friction in internal combustion powertrains. Demand concentrates in Ho Chi Minh City and Hanoi metropolitan zones, where Euro 5 emission compliance is forcing rapid reformulation toward 0W-20 and 5W-30 viscosity grades.
- Hydraulic Fluids:ISO VG 32 to VG 68 mineral and synthetic formulations transmit power in industrial machinery while providing corrosion protection. Consumption clusters in Hai Phong and Binh Duong province factories, where Japanese and Korean electronics manufacturers specify extended-drain synthetic variants under multi-year maintenance contracts.
- Gear Oils:EP-additive fortified lubricants protect transmission and differential components in commercial vehicles and industrial gearboxes.
- Greases:Thickened oil formulations for bearings and chassis points in agricultural equipment and construction machinery.
Engine oils command the established base. The steepest expansion runs through hydraulic fluids.
Application:
Cost-tier stratification separates premium synthetic formulations for foreign OEM assembly plants from economy mineral oils serving price-sensitive independent workshops.
- Automotive:Passenger car motor oils and two-wheeler lubricants formulated for drain intervals ranging from 3,000 to 15,000 kilometers. Volume concentrates in ride-hailing fleet consolidation across Ho Chi Minh City, where Grab and Be vehicle-leasing programs now specify bulk supply contracts with standardized service intervals.
- Industrial:Compressor, turbine, and metalworking fluids serving factory maintenance schedules. Demand anchors in Thai Nguyen and Vinh Phuc province electronics clusters, where foreign manufacturers require local laboratory certification before approving supplier lists.
- Marine:Cylinder and system oils for coastal shipping and port operations at Cai Mep-Thi Vai.
- Agricultural:Tractor hydraulic fluids and transmission oils for mechanizing coffee and rubber plantations in Dak Lak and Lam Dong provinces.
Automotive applications generate the volume foundation. Industrial applications are climbing the fastest as manufacturing FDI accelerates.
End User:
Customer-type fragmentation distinguishes multinational OEM procurement teams with technical qualification requirements from domestic construction firms prioritizing price and availability.
- Manufacturing:Electronics and textile factories in the Red River Delta specifying synthetic industrial lubricants with predictive maintenance compatibility. Procurement concentrates in foreign-invested facilities where technical audits precede contract awards.
- Transportation:Fleet operators and logistics companies managing vehicle lubrication across regional distribution networks. Activity clusters in Hanoi-Hai Phong and Ho Chi Minh City-Vung Tau corridors, where highway freight expansion is extending drain interval specifications.
- Construction:State infrastructure projects and private developers consuming hydraulic fluids and greases for earthmoving equipment.
- OEMs:VinFast and foreign automotive assembly plants requiring initial fill and service fill lubricants with direct supplier relationships.
Manufacturing end users anchor contract value. Transportation fleets are gaining share fastest through operational consolidation.
Distribution Channel:
Supply concentration varies dramatically: Petrolimex's 500-plus retail stations dominate consumer access, while industrial volumes flow through direct manufacturer contracts bypassing traditional wholesale.
- Retail:Branded service stations and independent motorbike workshops serving individual vehicle owners. Volume concentrates in urban Vietnam, where workshop density in Ho Chi Minh City districts exceeds 200 service points per square kilometer.
- Wholesale:Bulk supply to regional distributors and industrial procurement hubs. Activity clusters in Hai Phong and Da Nang logistics zones, where inventory financing requirements filter out undercapitalized blenders.
- Online:E-commerce platforms and lubricant-specific marketplaces reaching fleet operators and DIY consumers.
- Distributors:Authorized networks with technical service capabilities for industrial account management.
Retail channels maintain the volume base. Direct distributor relationships with fleet and industrial accounts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's lubricant consumption concentrates in distinct regional patterns: the Red River Delta anchors industrial-grade demand through foreign-invested manufacturing, while the Southeast region channels automotive volumes through Ho Chi Minh City's dense retail networks. This geographic split shapes formulation priorities and distribution infrastructure investments differently across the country.
Red River Delta
Foreign electronics and textile manufacturers in Thai Nguyen and Vinh Phuc provinces specify synthetic industrial lubricants with extended-drain capabilities. Vietnam's Ministry of Industry and Trade enforces TCVN standards that increasingly reference API and ACEA performance categories for import compliance. Hai Phong's steel and cement plants anchor industrial lubricant offtake through direct supply contracts with national oil companies.
Southeast Region
Ho Chi Minh City's twenty-million-plus motorcycle fleet drives engine oil volumes through retail service stations and independent workshops. The Ministry of Transport's Euro 5 emission standards alignment is pushing reformulation toward lower-viscosity grades in this automotive-heavy zone. Binh Duong province's food processing plants are adopting polyalkylene glycol-based compressor lubricants for ammonia refrigeration systems.
North Central Coast
Thanh Hoa and Nghe An provinces host refinery investments at Nghi Son that are reducing import dependency for Group II and Group III base stocks. The central bank and planning ministry shape infrastructure spending that governs construction equipment lubricant demand through state project pipelines. Dung Quat complex developments are improving margin capture for domestic compounders in this emerging supply corridor.
Central Highlands
Mechanization of coffee and rubber plantations in Dak Lak and Lam Dong provinces is opening demand for tractor hydraulic fluids and transmission oils. Agricultural equipment fleets in this region historically relied on generic mineral formulations, creating upgrade potential as foreign machinery brands penetrate. Provincial agricultural extension programs are gradually introducing equipment maintenance standards that specify lubricant quality tiers.
Mekong Delta
Container port expansion at Cai Mep-Thi Vai lacks dedicated marine lubricant bunkering infrastructure, creating white space for coastal supply depots. The maritime logistics corridor connecting Ho Chi Minh City to Vung Tau generates cylinder and system oil demand for coastal shipping operations. Provincial industrial zones are attracting smaller-scale manufacturing that consumes economy-grade hydraulic fluids through wholesale distribution channels.
Vietnam Lubricants Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Vietnam's lubricant market structure. National oil companies with captive refinery access and nationwide fuel station networks occupy the upper tier, while independent blenders and foreign specialty suppliers cluster below. The competitive terrain separates into three archetypes: integrated refiners with backward base oil control, multinational formulators with synthetic technology portfolios, and domestic compounders serving price-sensitive segments. Capacity expansion at Nghi Son and Dung Quat is altering supply-side positioning, while portfolio diversification into EV thermal fluids represents an emerging competitive vector.
Among the integrated national oil companies, Petrolimex and PVOIL exemplify the refinery-linked archetype with distribution infrastructure spanning retail and industrial channels. Shell Vietnam represents the multinational technology-led position, differentiated through synthetic product lines targeting Japanese and Korean automotive OEMs. These three anchors illustrate how competitive positioning stratifies between captive supply control, technical formulation capability, and foreign brand equity in a market undergoing regulatory compression toward higher performance categories.
| Leading Market Players |
|---|
| TotalEnergies |
| Motul Vietnam JSC |
| Castrol BP Petco |
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell Vietnam |
| Mekong Petrochemical JSC |
| PVOIL |
| Petrolimex |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of inventory coverage among Vietnamese independent blenders compresses working capital cycles while amplifying price volatility exposure, concentrating pricing power with integrated refiners who control captive base oil supply. This inventory-lead asymmetry rewards Petrolimex and PVOIL with margin stability that spot-dependent compounders cannot replicate.
Pricing Analysis
Long-term offtake contracts anchor industrial lubricant pricing in the Red River Delta, where foreign electronics manufacturers lock in synthetic hydraulic fluid supply through multi-year agreements with fixed volume escalators. Spot market exposure dominates the motorcycle service segment, where Ho Chi Minh City workshops source engine oils through weekly price negotiations tied to Singapore Group II base oil quotations. Certification-grade differentiation separates API SP-compliant formulations from economy mineral oils, with Euro 5 compliance timelines compressing margins on lower-tier products. Fleet operators consolidating through Grab and Be vehicle-leasing programs extract volume discounts that independent retailers cannot match, intensifying price erosion across the retail channel.
Supply Chain Analysis
Singapore Strait bunkering and port congestion chokepoints govern additive package transit times for Vietnamese blenders, with 70-80 percent of functional additive concentrates originating from Singapore and Thailand compounding facilities. Base oil supply draws from South Korean and Thai Group II/III refineries, while polyalphaolefin synthetic stocks hinge on Japanese and Singaporean specialty chemical producers. Single-source vulnerability concentrates in the additive technical supply chain, where small blenders lack qualification pathways to alternative suppliers. Distribution runs through Petrolimex's 500-plus retail station network for consumer volumes, while industrial accounts receive direct tanker delivery bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against extended-drain synthetic formulations that compress per-vehicle consumption rates, requiring portfolio repositioning toward service revenue and technical advisory rather than volume-dependent sales.
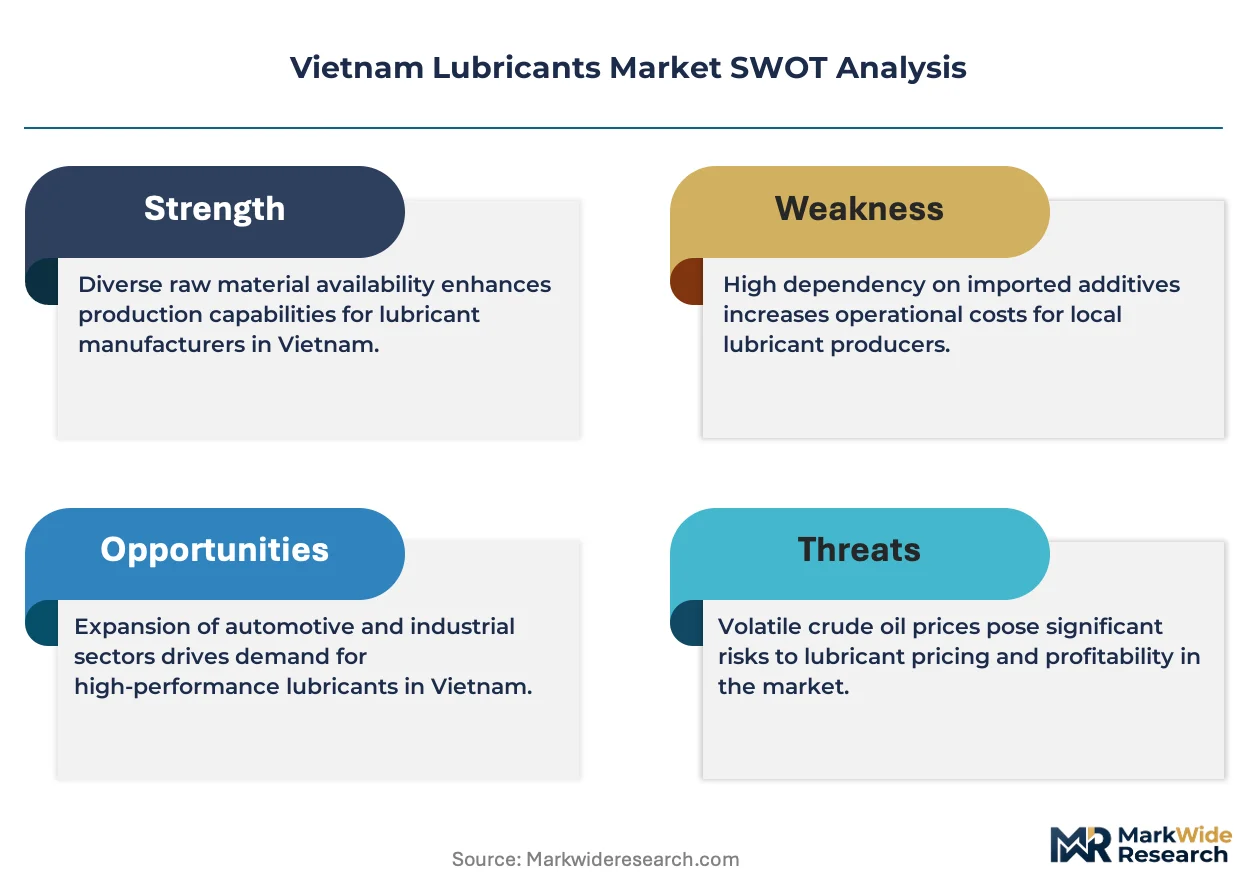
For Market Incumbents: Shield core industrial accounts by embedding predictive maintenance compatibility into hydraulic fluid contracts, locking out competitors through equipment monitoring integration. Accelerate captive additive compounding investments at Nghi Son to neutralize import dependency that independent blenders exploit for price competition. Euro 5 compliance deadlines create a certification barrier that rewards early API SP portfolio conversion with stranded competitor volume. For New Entrants and Emerging Players: Anchor in the Central Highlands agricultural mechanization corridor, where Dak Lak and Lam Dong provinces lack established lubricant technical service infrastructure for expanding coffee and rubber plantation equipment fleets. Target marine lubricant bunkering at Cai Mep-Thi Vai container port expansion, a white space absent dedicated coastal supply depots despite growing cylinder oil demand. Pursue direct distributor relationships with VinFast authorized service networks for EV thermal fluid initial fill specifications. For Investors and Strategic Acquirers: Carve-out targets emerge from national oil company lubricant divisions seeking operational focus on core fuel retail, presenting acquisition opportunities for distribution infrastructure and industrial account portfolios. Mid-term viability hinges on successful EV thermal fluid portfolio pivots that capture dielectric coolant and e-axle lubricant demand from battery electric vehicle assembly expansion. Monitor base oil localization progress at Dung Quat as the inflection signal for domestic compounder margin structure improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Compounding | Captive additive production at Nghi Son reduces Singapore import dependency for domestic blenders. |
| EV Thermal Fluid Portfolio Development | VinFast battery electric vehicle assembly creates specification demand for dielectric coolants and e-axle lubricants. |
| Central Highlands Distribution Network Buildout | Agricultural mechanization in Dak Lak and Lam Dong opens tractor hydraulic fluid demand outside industrial corridors. |
| Marine Lubricant Bunkering Infrastructure | Cai Mep-Thi Vai port expansion lacks dedicated coastal supply depots for container shipping cylinder oils. |
| API SP Certification Acceleration | Euro 5 alignment compresses timelines for third-party testing validation of lower-viscosity engine oil formulations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade records, Ministry of Industry and Trade technical regulation filings, and API certification registry data. Interviews with lubricant blending plant managers, procurement leads at Red River Delta electronics manufacturers, Petrolimex retail operations directors, and automotive OEM technical service heads informed demand segmentation. Bottom-up volume estimates from distributor channel checks triangulate against top-down refinery output and import statistics from Vietnam Customs.
Segmentation dimensions modeled include product type viscosity grade, application end-use intensity, customer procurement consolidation level, and geographic regional demand cluster across the projection horizon. CAGRs derive from elasticity-adjusted extrapolation of base oil consumption trends and equipment fleet expansion rates. Forecast inputs incorporate Euro 5 regulatory compliance timelines, FDI manufacturing project pipelines, and EV assembly capacity announcements without specific year attribution.
Decision-makers should treat outputs as directional under assumptions of sustained manufacturing FDI inflows and emission standard enforcement continuity; material deviation in base oil localization progress or EV adoption velocity would warrant model refresh. Practitioners should keep alternative scenarios live as regulatory harmonization pace and refinery investment completion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Aerospace Lubricant Market
Lubricants
ASEAN Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Yarn Lubricant Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Poland Lubricants Market