
 Global Aerospace Lubricant Market | 2026-2036
Global Aerospace Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Lubricant Market Foresight
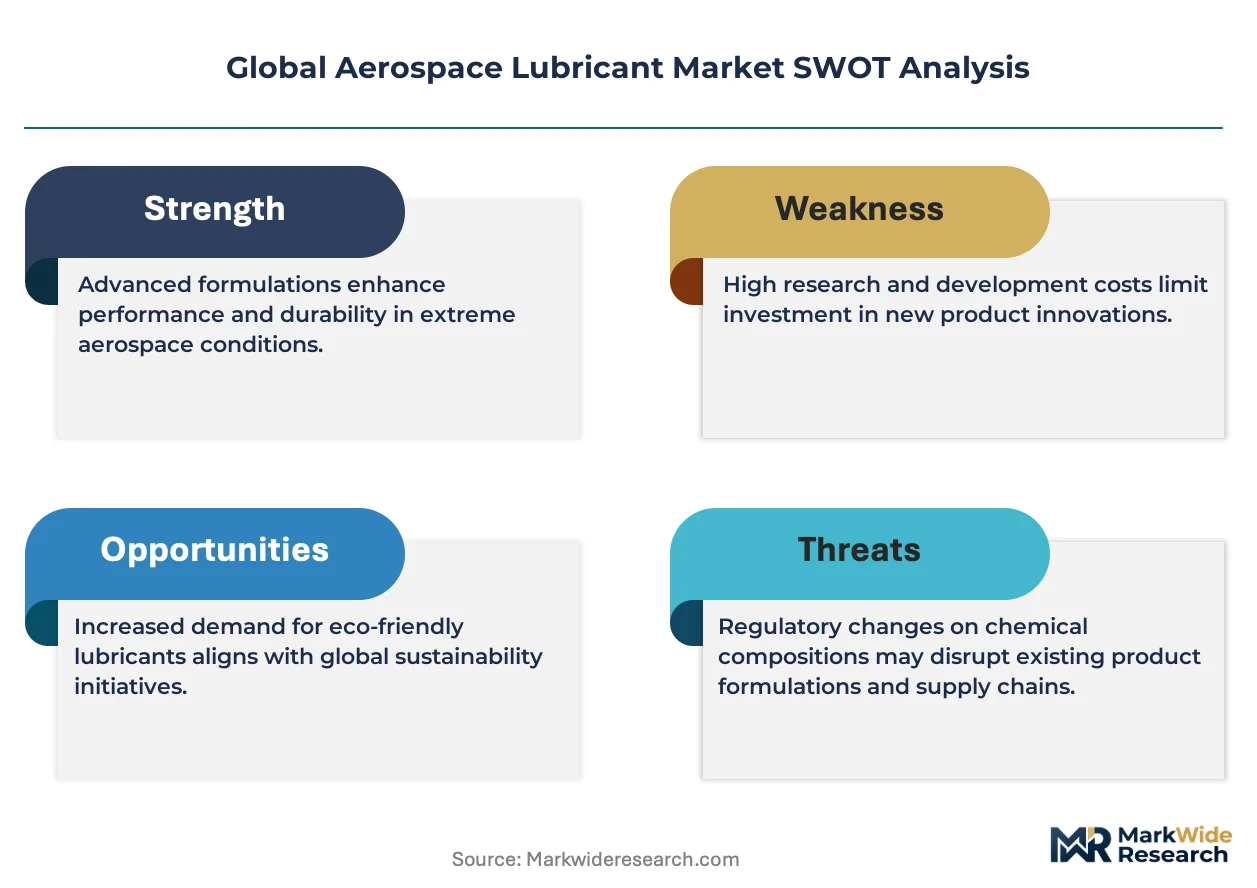
REACH compliance is expanding the cost-of-entry calculus for aerospace lubricant suppliers, forcing reformulation investments that favor incumbents with dedicated regulatory teams. Exxon Mobil Corporation leverages its integrated base oil and additive supply chain to absorb these compliance costs. Shell plc sustains competitive positioning through deep relationships with turbine OEMs across multiple continents.
Aerospace lubricants are thermally stable fluid formulations engineered to operate across temperature extremes from minus 65 to over 400 degrees Fahrenheit, delivering friction reduction, corrosion inhibition, and thermal transfer in turbine engines, hydraulic actuators, and transmission systems. Synthetic technology leads the technology dimension due to its oxidative stability and extended drain intervals, while bio-based formulations represent the fastest-growing niche as military procurement specifications begin incorporating sustainability criteria. Engine oils dominate the product type landscape by value, though hydraulic fluids capture disproportionate margin pools in aftermarket channels.
EMA, FAA, and China's GB standards collectively shape product registration pathways, with each jurisdiction imposing distinct toxicity, flammability, and performance testing protocols that fragment certification requirements. The EU F-Gas Regulation and evolving EPA guidelines on per- and polyfluoroalkyl substances are converging to restrict certain fluorinated lubricant chemistries, redirecting R&D investment toward alternative synthetic platforms. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which formulation investments will unlock multi-regional market access.
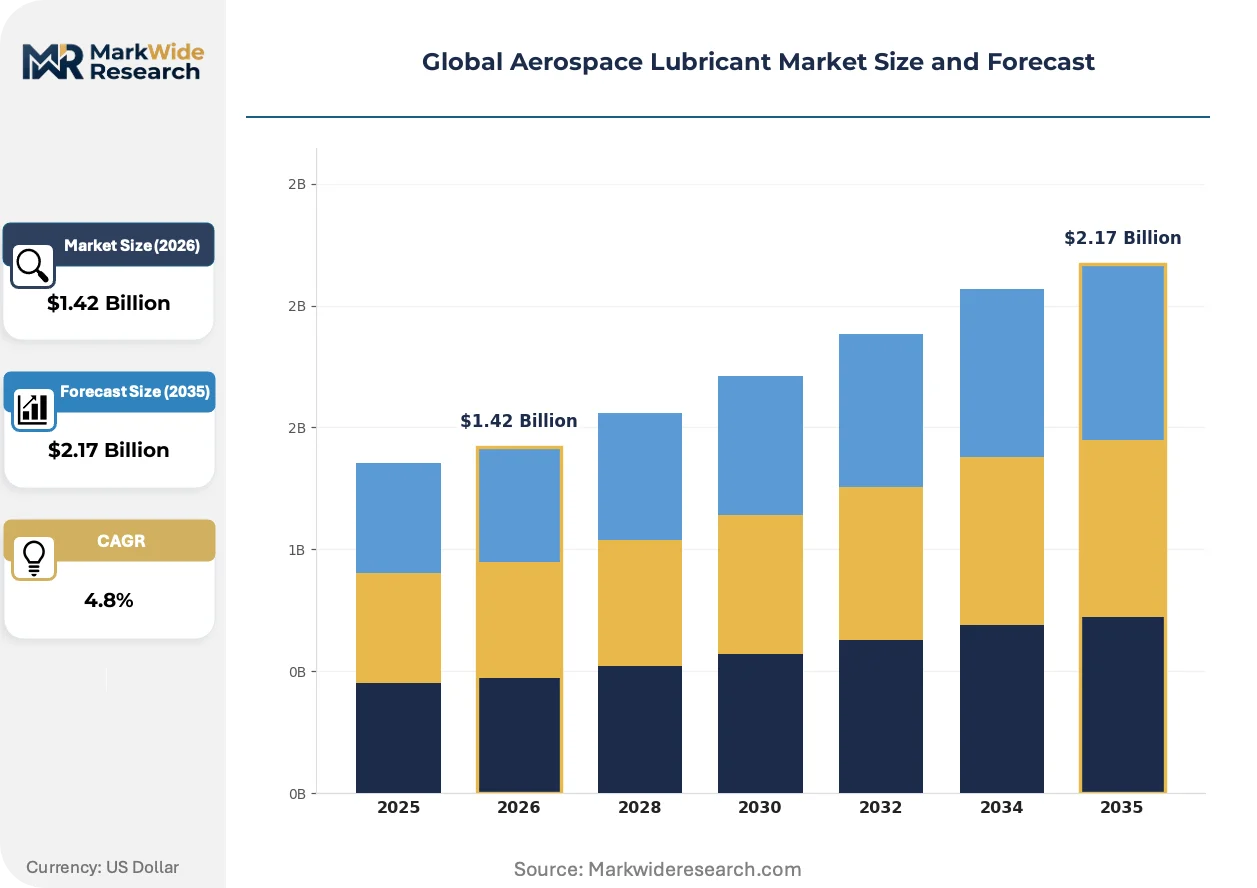
Market Dynamics
Extended oil-drain intervals mandated by turbine OEMs are compressing lubricant consumption per flight hour while demanding higher-performance synthetic formulations that command premium positioning.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement is accelerating reformulation toward Group V synthetics that extend service life.
- China's civil aviation fleet:GB standards alignment with SAE specifications is opening certification pathways for imported lubricant technologies.
- Thermal management demands:Next-generation geared turbofans require lubricants with oxidative stability above 200 degrees Celsius.
Market Restraints
- PAO base oil concentration:Four integrated majors control over seventy percent of aerospace-grade polyalphaolefin supply.
- F-Gas Regulation restrictions:EU fluorinated compound phase-downs are eliminating certain PFPE lubricant chemistries from civil applications.
- Additive package validation:FAA certification timelines for new anti-wear chemistries extend beyond thirty-six months.
Strategic Opportunities
- India defense procurement:BIS adoption of MIL-PRF specifications creates first-mover advantage for qualified suppliers.
- Space launch recovery:Reusable rocket turbopumps require lubricants with ultra-low vapor pressure and wide-temperature operability.
- Urban air mobility:Electric-vertical-takeoff airframers are specifying lubricants compatible with integrated electric motor cooling loops.
Industry Challenges
- Tribology expertise scarcity:Formulation chemists with turbine-specific experience command compensation premiums that strain mid-tier R&D budgets.
- Dual-certification burden:Simultaneous FAA and EASA qualification for new products requires parallel testing protocols that duplicate capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Lubricant Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Hydraulic Fluids, Greases, Transmission Fluids, Cooling Oils Technology: Synthetic, Semi-Synthetic, Mineral-Based, Bio-Based, Fluorinated Application: Commercial Aircraft, Military Aircraft, Spacecraft, Unmanned Aerial Vehicles, Rotorcraft End User: OEMs, MRO Providers, Defense Contractors, Research Laboratories, Component Manufacturers |
| Companies Covered | Exxon Mobil Corporation, Shell plc, TotalEnergies Company, Aerospace Lubricants, Inc., Nye Lubricants, Inc., Fuchs, Eastman Chemical Company, The Chemours Company, NYCO S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Lubricant Market Shifts & Advancements
Synthetic base oil platforms are displacing mineral formulations across all temperature-critical applications, while regulatory pressure on fluorinated chemistries redirects innovation toward ester and alkylated naphthalene architectures.
Ionic liquid lubricants are rewriting thermal stability benchmarks in aerospace bearing applications. Major turbine OEMs are qualifying these non-volatile formulations for auxiliary power units. The technology is compressing traditional PAO-ester blend market share in high-heat zones.
EPA guidelines on per- and polyfluoroalkyl substances are converging with EU F-Gas Regulation restrictions to eliminate certain PFPE chemistries from new platform certifications. Formulators are redirecting R&D toward phosphate ester and silicate ester alternatives. Military specifications are lagging civil restrictions, creating a two-tier regulatory environment.
Airline procurement consolidation is compressing supplier counts to three approved vendors per lubricant category. Network carriers are unbundling lubricant supply from engine maintenance contracts. This pattern is most visible among US legacy carriers with centralized fleet management.
Global Aerospace Lubricant Market Segmentation
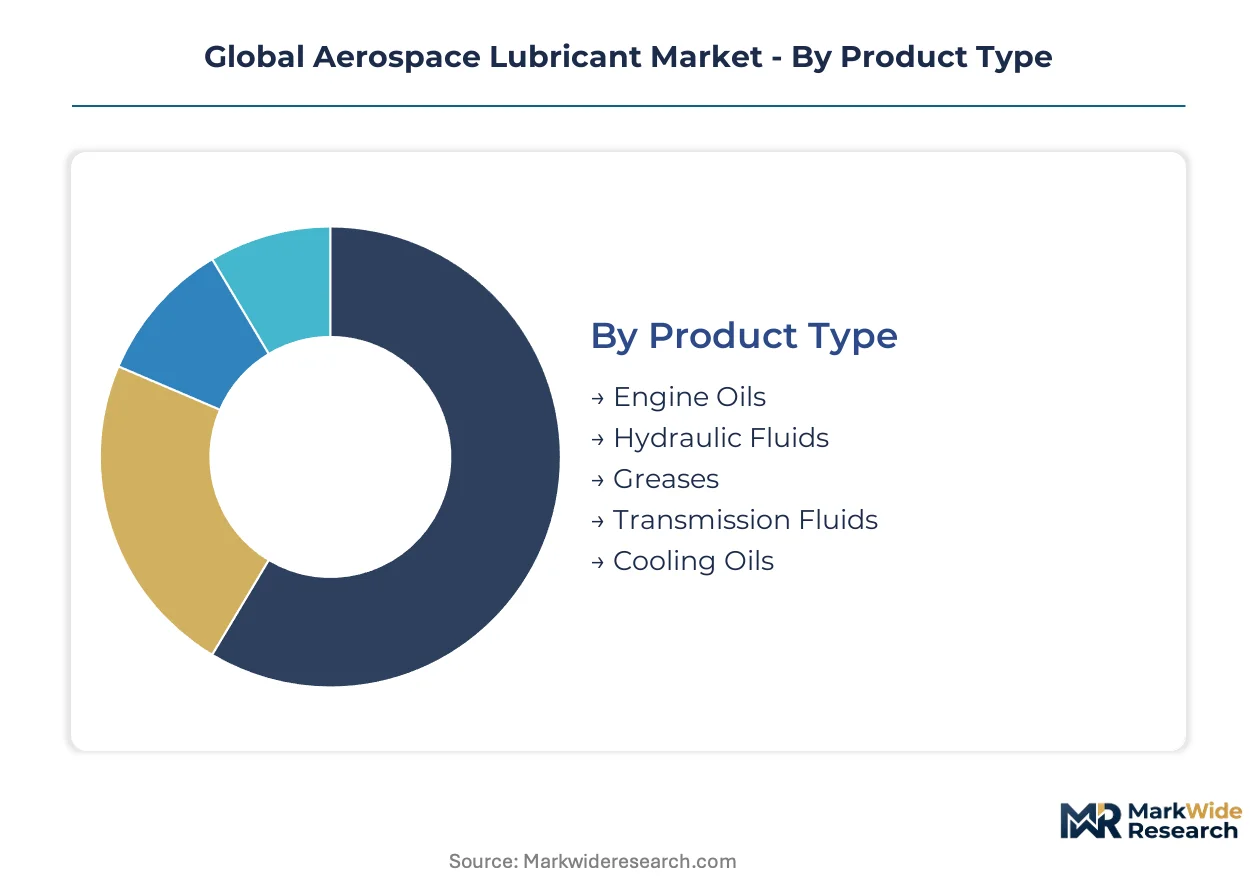
Aerospace lubricant procurement splits across performance tiers, regulatory jurisdictions, and maintenance philosophies. Capital allocation patterns differ sharply between OEM specification work and aftermarket replenishment cycles.
Product Type:
Engine oils demand the heaviest upfront formulation investment due to FAA and EASA certification requirements for high-temperature oxidative stability.
- Engine Oils:Thermally stable synthetic formulations engineered for turbine core bearings and gearbox interfaces. Demand concentrates in United States and China where next-generation geared turbofan production lines are scaling. OEM-mandated drain interval extensions are compressing volume per flight hour while elevating performance specifications.
- Hydraulic Fluids:Fire-resistant phosphate ester formulations serving flight control actuators and landing gear systems. Aftermarket channels in Germany and France capture disproportionate margin pools due to MRO hub density. REACH compliance is accelerating Group V synthetic adoption.
- Greases:Thickened lubricants for bearing assemblies and spline couplings.
- Transmission Fluids:Specialized formulations for rotorcraft and auxiliary power unit gearboxes.
- Cooling Oils:Heat transfer fluids for integrated drive generators and starter-generators.
Most installed capacity flows through Engine Oils. Expansion is steepest in Hydraulic Fluids.
Technology:
Synthetic platforms command premium positioning through extended service life, while bio-based alternatives attract sustainability-driven procurement.
- Synthetic:PAO and ester base stocks delivering oxidative stability above 200 degrees Celsius. Commercial aviation fleets in United States and China are standardizing on these formulations for drain interval extension. ECHA enforcement timelines are redirecting formulation investment toward Group V architectures.
- Fluorinated:PFPE chemistries for extreme-temperature bearing applications in spacecraft and military platforms. EU F-Gas Regulation phase-downs are eliminating certain formulations from civil certifications. Military specifications are lagging these restrictions.
- Semi-Synthetic:Blended formulations balancing cost and performance for legacy fleet support.
- Mineral-Based:Conventional base stocks retaining niche presence in temperature-stable applications.
- Bio-Based:Renewable feedstock formulations gaining traction in military procurement specifications.
Volume leadership sits with Synthetic. Bio-Based is climbing the fastest as sustainability criteria penetrate defense procurement.
Application:
Commercial aircraft specifications set the performance baseline that other segments adapt for mission-specific requirements.
- Commercial Aircraft:Turbine engine and hydraulic system lubricants governed by SAE and GB standards. Fleet expansion in China and aftermarket consolidation among United States network carriers are reshaping supplier counts. Airlines are unbundling lubricant supply from engine maintenance contracts.
- Military Aircraft:MIL-PRF specifications dominating procurement with slower adoption of fluorinated chemistry restrictions. India defense procurement is adopting these specifications, creating qualification opportunities.
- Spacecraft:Ultra-low vapor pressure formulations for reusable rocket turbopumps. United States launch recovery programs are driving specification evolution.
- Unmanned Aerial Vehicles:Lightweight lubricants for extended endurance missions.
- Rotorcraft:Transmission and gearbox fluids for helicopter main and tail rotor systems.
Specification investment concentrates in Commercial Aircraft. Steepest specification evolution is occurring in Spacecraft.
End User:
OEM qualification gates filter supplier access, while MRO procurement patterns determine aftermarket profitability.
- OEMs:Turbine and airframe manufacturers specifying lubricants during platform certification. Boeing and Airbus supply chains in United States and Germany require dual FAA-EASA qualification. OEM consolidation to three approved vendors per category is compressing competitive sets.
- MRO Providers:Maintenance hubs in Singapore and Netherlands managing replenishment cycles. Centralized fleet management among legacy carriers is shifting procurement leverage.
- Defense Contractors:Military platform integrators with distinct specification pathways.
- Research Laboratories:Ionic liquid and advanced synthetic development programs.
- Component Manufacturers:Subsystem suppliers qualifying lubricants for actuators, pumps, and generators.
Qualification investment flows heaviest through OEMs. Procurement autonomy is expanding fastest among MRO Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tribology chemists cluster in aerospace manufacturing corridors across Germany, the United States, and China, where turbine OEM assembly lines and MRO hubs concentrate demand for high-performance lubricant formulations.
United States
Next-generation geared turbofan production lines at Pratt & Whitney and GE Aerospace facilities in Connecticut and Ohio are scaling specification requirements for oxidative stability above 200 degrees Celsius. FAA certification timelines for new anti-wear chemistries extend beyond thirty-six months, compressing supplier qualification windows. Houston and Dallas-Fort Worth MRO hubs are unbundling lubricant supply from engine maintenance contracts among legacy network carriers.
Germany
REACH compliance deadlines enforced by ECHA are accelerating reformulation investments toward Group V synthetic architectures. Hamburg and Frankfurt maintenance hubs capture disproportionate margin pools in hydraulic fluid aftermarket channels. Munich-based turbine OEM supply chains require dual FAA-EASA qualification gates that favor incumbents with dedicated regulatory teams.
China
Civil aviation fleet expansion under GB standards alignment with SAE specifications is opening certification pathways for imported lubricant technologies. COMAC assembly lines in Shanghai are standardizing on synthetic formulations for drain interval extension. Beijing-Tianjin-Hebei industrial corridors are clustering domestic blending capacity to serve indigenous narrowbody programs.
France
EU F-Gas Regulation phase-downs are eliminating certain PFPE lubricant chemistries from civil platform certifications. Toulouse-based Airbus supply chains are consolidating approved vendor counts to three per lubricant category. Lyon and Paris MRO networks are adopting phosphate ester alternatives for fire-resistant hydraulic applications.
India
BIS adoption of MIL-PRF specifications is creating first-mover qualification opportunities for defense procurement. Bengaluru and Hyderabad aerospace clusters are specifying lubricants for indigenous fighter and transport programs. Mumbai-Pune industrial corridors are developing captive blending capacity to reduce import dependency for military aviation fluids.
Global Aerospace Lubricant Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors with captive base oil supply. Four integrated players control over seventy percent of aerospace-grade polyalphaolefin supply, creating tiered access to feedstock. Strategic archetypes span integrated energy conglomerates, specialty chemical pure-plays, and national oil company lubricant divisions. Dominant competitive moves include backward integration into additive package manufacturing and parallel FAA-EASA qualification investments to compress certification timelines.
Within the integrated energy tier, Exxon Mobil Corporation and Shell plc exemplify archetypes with upstream control over base oil and additive supply chains. Among specialty chemical fabricators, Eastman Chemical Company and The Chemours Company occupy positions shaped by regulatory pressure on fluorinated and ester chemistries. NYCO S.A. represents the national oil company lubricant division model with defense-centric specification focus.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell plc |
| TotalEnergies Company |
| Aerospace Lubricants, Inc. |
| Nye Lubricants, Inc. |
| Fuchs |
| Eastman Chemical Company |
| The Chemours Company |
| NYCO S.A. |
| Others |
Supply & Pricing Matrix
Integrated petrochemical majors with captive base oil supply anchor pricing discipline across the aerospace lubricant value chain, compressing margin capture for non-integrated blenders while sustaining premium positioning for synthetic formulations. Their upstream control over polyalphaolefin feedstock insulates cost structures from spot volatility, translating into stable contract pricing for turbine OEMs.
Pricing Analysis
The bundled-versus-unbundled service split between OEM specification work and aftermarket replenishment defines pricing architecture across the value chain. OEM qualification gates command three-tier pricing structure across premium, standard, and economy levels, with FAA-EASA dual-certified formulations capturing 40-60% premiums over single-jurisdiction alternatives. Cost compression in hydraulic fluid aftermarket channels is intensifying because airline procurement consolidation has reduced approved vendor counts to three per category. MRO providers exhibit highest price sensitivity due to centralized fleet management mandates, while spacecraft launch operators show lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Aerospace-grade polyalphaolefin supply rests on integrated production complexes in the United States, Germany, and South Korea, where four majors control upstream feedstock access. Formulation draws from Group V synthetic base stocks, phosphate ester hydraulic fluids, and ionic liquid bearing lubricants as primary inputs. Single-source vulnerability concentrates in anti-wear additive packages requiring 36-month FAA validation timelines. Distribution runs through turbine OEM supply chains in Connecticut and Hamburg, with MRO hubs in Singapore and Dallas-Fort Worth managing replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where extended drain intervals and REACH compliance are redirecting procurement toward premium synthetic specifications. Fleet operators now prioritize total cost of ownership over unit price.
For Market Incumbents: Acquire tribology expertise clusters in Germany and the United States to defend against ionic liquid substitution in high-heat bearing applications. Deepen backward integration into additive package manufacturing to compress 36-month FAA certification timelines. Channel control through direct MRO relationships in Singapore and Dallas-Fort Worth offsets airline procurement consolidation pressure. For New Entrants and Emerging Players: Begin with defense procurement specifications in India where BIS adoption of MIL-PRF standards creates qualification windows before civil market saturation. Spacecraft reusable rocket turbopumps represent the most penetrable white-space segment given ultra-low vapor pressure specification evolution. Urban air mobility electric motor cooling compatibility offers a technical differentiation angle for early OEM engagement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier blenders lacking captive base oil supply but holding dual FAA-EASA qualification assets. Five-to-ten year viability hinges on successful navigation of fluorinated chemistry phase-downs and ester alternative scale-up. The signal to watch is ionic liquid qualification velocity at major turbine OEM auxiliary power unit programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Compresses FAA certification timelines from 36 months toward 24-month competitive benchmarks. |
| Dual FAA-EASA Qualification Investment | Unlocks Pratt & Whitney and Airbus supply chain access in Connecticut and Toulouse simultaneously. |
| Ionic Liquid Formulation Development | Captures auxiliary power unit market share from traditional PAO-ester blends at GE Aerospace. |
| India Defense Procurement Qualification | Establishes first-mover positioning before BIS MIL-PRF specification windows close to new entrants. |
| MRO Channel Direct Relationships | Offsets airline unbundling of lubricant supply from engine maintenance contracts at US legacy carriers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant formulation chemists, turbine OEM procurement directors, MRO fleet managers, and ECHA regulatory affairs specialists against secondary validation through FAA certification databases, EASA type certificate records, SEC 10-K filings of integrated majors, and customs trade data on polyalphaolefin feedstock flows. Bottom-up volume modeling across product type and technology segments was triangulated against top-down market sizing from OEM production forecasts.
Historical reference periods anchored the projection horizon to pre-pandemic fleet utilization baselines and post-recovery maintenance interval extensions. The analytical framework modeled segmentation across product type, technology platform, application, and end-user channel, with CAGRs derived from flight hour recovery trajectories and synthetic formulation penetration curves. Key inputs included geared turbofan production schedules at Pratt & Whitney and COMAC, REACH compliance cost absorption rates, and ionic liquid qualification timelines at major turbine OEMs.
Several conditions sit outside the modeled scope, including abrupt military specification revisions, breakthrough solid-state lubricant technologies, and geopolitical disruption of South Korean base oil supply. Forecasts reflect assumptions about regulatory alignment between FAA and EASA, sustained airline fleet expansion in China, and gradual fluorinated chemistry phase-down timelines. A small set of named triggers warrants ongoing watch: ionic liquid scale-up economics, India defense procurement award schedules, and reusable rocket launch recovery rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
India Industrial Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Drilling Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Russia Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market