
 Cooling Tower Chemicals Market | 2026-2036
Cooling Tower Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Tower Chemicals Market Analytics
Power generation utilities are collapsing their historical reliance on commodity biocide suppliers in favor of integrated water management contracts. Nalco Company leverages its digital monitoring platform to anchor long-term service agreements with independent power producers across the US Midwest. Evoqua Water Technologies competes through regional service density, sustaining technician networks that reduce response times for cooling tower upsets in manufacturing corridors.
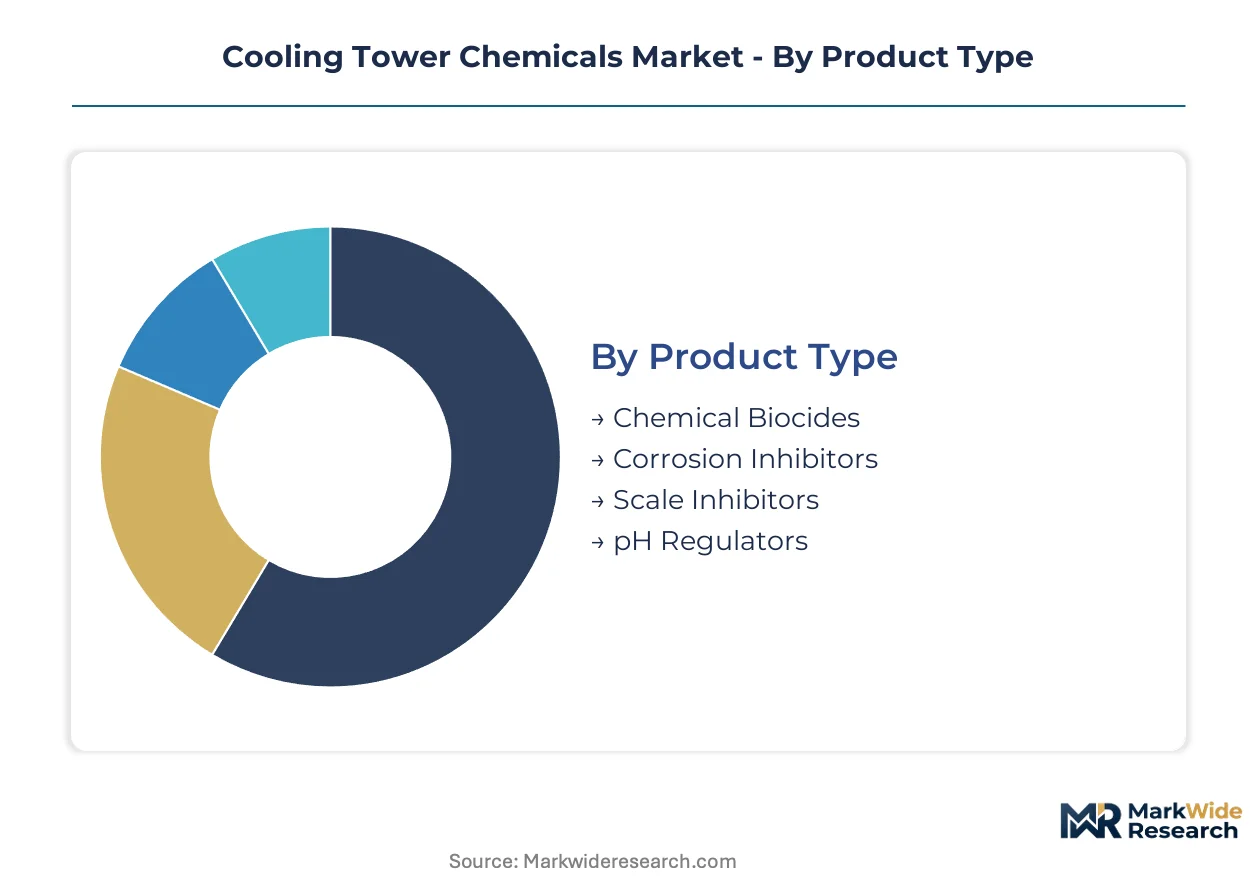
Cooling tower chemicals comprise formulated blends of biocides, corrosion inhibitors, scale inhibitors, and pH regulators designed to maintain thermal efficiency and prevent microbiologically induced corrosion in evaporative cooling systems. These formulations typically operate within specified pH ranges of 6.5 to 9.0 and conductivity thresholds to optimize heat transfer surface protection. Chemical biocides command the largest share of product-type revenue due to recurring dosing requirements, while corrosion inhibitors represent the fastest-expanding segment as operators extend asset life cycles in aging infrastructure. Among end users, power generation absorbs the highest absolute volume, though HVAC systems present tighter margin pools through specification-driven contractor channels.
The US EPA regulates cooling tower discharge through NPDES permitting and effluent limitation guidelines, while OSHA enforces worker exposure standards for biocide handling and storage. REACH registration requirements in Europe constrain biocide active ingredient availability, reshaping supplier formulation strategies for multinational accounts. Water scarcity regulations in water-stressed jurisdictions are forcing zero-liquid-discharge designs that demand higher chemical intensities and novel scale control polymers. Stakeholders must monitor how regional water stress indices and biocide reauthorization timelines reshape product portfolios and geographic market access.
Market Dynamics
Power producers and industrial operators are consolidating chemical supply relationships around integrated water management platforms that bundle monitoring hardware, predictive analytics, and on-site technical service. This shift collapses the traditional spot-market procurement of commodity biocides and inhibitors.
Growth Catalysts
- Thermal capacity expansion in China:New coal and gas-fired power plants in Shandong and Guangdong provinces require specialized scale inhibitor formulations for high-cycles-of-concentration operation.
- US EPA Clean Water Act enforcement:Stricter NPDES permitting on cooling water intake structures forces facilities to upgrade chemical treatment programs for biofouling control.
- Zero-liquid-discharge mandates:Water scarcity regulations in South Africa and Australia drive adoption of high-intensity chemical regimes for evaporative cooling in mining and smelting operations.
Market Restraints
- Active ingredient supply concentration:REACH registration requirements in Europe constrain biocide raw material availability, forcing reformulation cycles that extend 18-24 months.
- Halogenated biocide substitution pressure:Chlorine and bromine-based treatments face displacement by non-oxidizing alternatives in food-processing and pharmaceutical cooling applications.
- Technical limitation in high-salinity blowdown:Conventional scale polymers lose efficacy above 10,000 µS/cm conductivity, creating untreated scaling zones in coastal power plants.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Vietnam and Indonesia petrochemical cluster expansions lack established chemical service infrastructure, opening first-mover positioning for integrated providers.
- Smart dosing system convergence:Integration of IoT conductivity sensors with automated chemical feed pumps enables real-time optimization that reduces overdosing waste.
- EU F-Gas Regulation phase-down:Cooling system efficiency mandates drive chemical treatment intensity to compensate for reduced refrigerant charge and higher thermal loads.
Industry Challenges
- Certified water treatment operator shortages:OSHA biocide handling requirements and state-level licensing create recruitment bottlenecks for field service technician networks.
- Legacy DCS integration complexity:New digital monitoring platforms require costly middleware development to connect with aging distributed control systems in 1970s-era power plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Tower Chemicals Market |
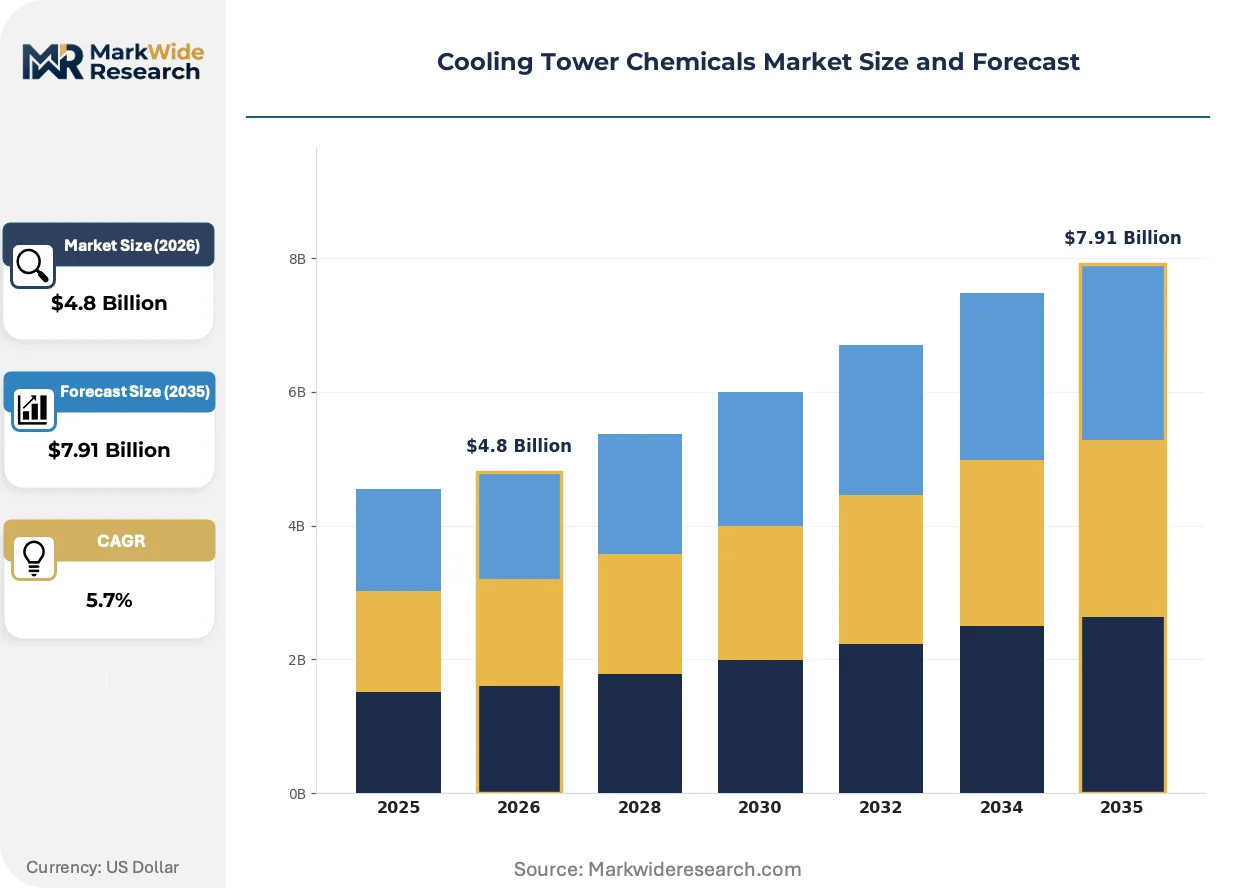
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
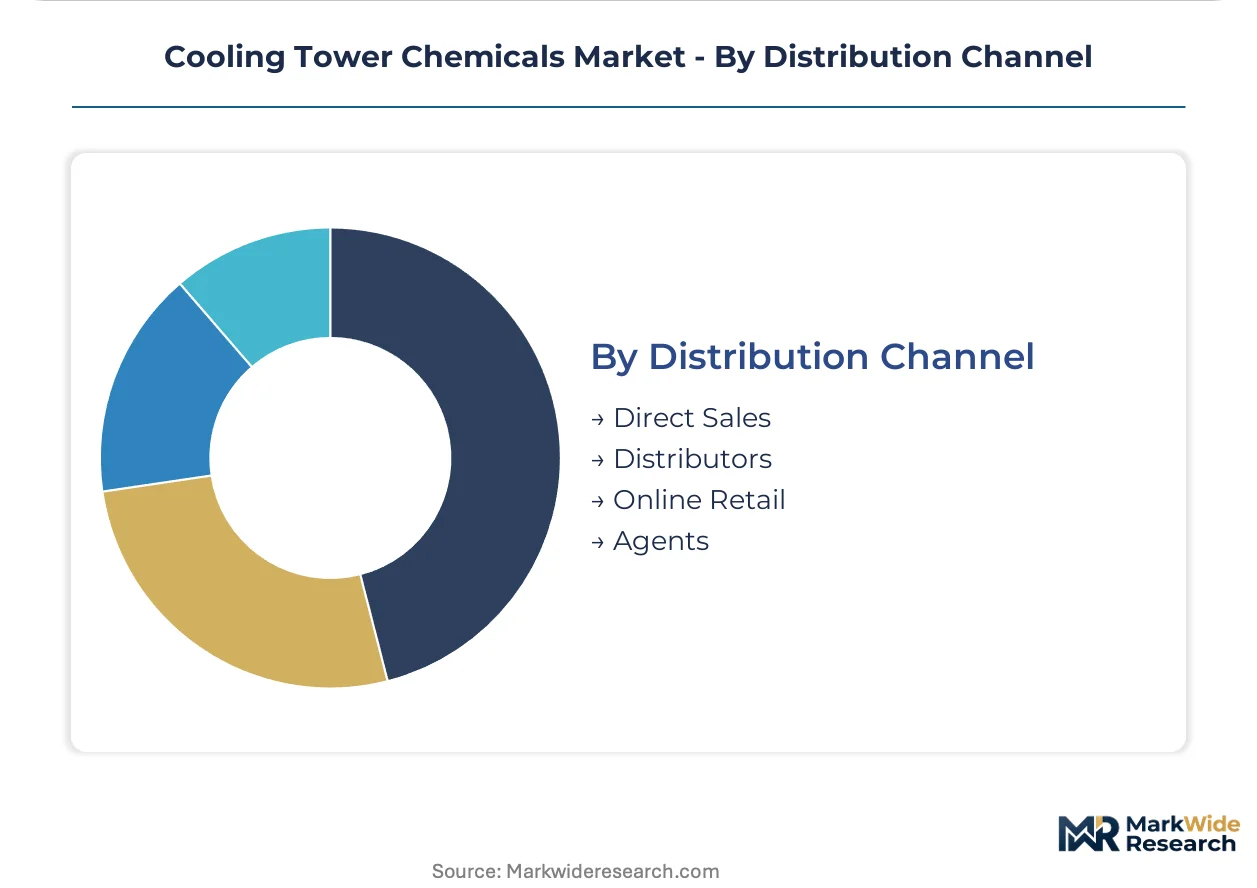
| Segmentation | Product Type: Chemical Biocides, Corrosion Inhibitors, Scale Inhibitors, pH Regulators End User: Power Generation, Manufacturing, HVAC Systems, Oil & Gas Application: Cooling Systems, Water Treatment, Industrial Processes, Chemical Processing Distribution Channel: Direct Sales, Distributors, Online Retail, Agents |
| Companies Covered | Nalco Company, Evoqua Water Technologies, GE Water and Process Technologies, Siemens, IDE Technology, SPX Technologies, Johnson Controls International, Cooling Tower Systems, Paharpur Cooling Towers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Tower Chemicals Market Evolving Landscape
Formulation chemistry and application hardware are diverging into distinct innovation tracks. Specialty chemical producers pursue bio-based active ingredients while equipment vendors embed predictive analytics into dosing skids.
Enzyme-based biofilm dispersants are bifurcating the biocide category by attacking extracellular polymeric substances without oxidizing metal surfaces. Food and beverage processors in Germany and the Netherlands are piloting these alternatives to meet EFSA discharge limits. The technology is compressing demand for traditional oxidizing biocides in sensitive applications while creating parallel specification channels.
REACH biocide product regulation reauthorization timelines are forcing suppliers to retire legacy active ingredients before 2026 submission deadlines. Industrial operators in EU member states face reformulation transitions that disrupt established dosing protocols. Cooling tower maintenance contracts now incorporate chemical substitution clauses to manage regulatory uncertainty.
Buyers are unbundling chemical supply from technical service, requesting separate pricing for delivered product versus on-site water analysis and system troubleshooting. Independent power producers in Texas and Ohio are driving this disintermediation to compare commodity chemical costs across multiple distributors. The separation is most visible in the US Midwest where regional service density allows competitive technician dispatch rates.
Cooling Tower Chemicals Market Segmentation
Cooling tower chemicals serve distinct operational regimes governed by water chemistry, heat load intensity, and discharge permitting. Segmentation reveals how formulation chemistry diverges across thermal power cycles, closed-loop HVAC networks, and zero-liquid-discharge mining operations.
Product Type:
REACH biocide reauthorization timelines and EPA NPDES discharge limits differentiate formulation strategies across active ingredient classes.
- Chemical Biocides:Oxidizing formulations based on chlorine, bromine, or chlorine dioxide dominate high-volume recirculating systems. Power generation utilities in China and the United States absorb the largest absolute volumes due to biofouling control mandates under the US EPA Clean Water Act and China's MEE water quality standards.
- Corrosion Inhibitors:Blended organic compounds and molybdate-based treatments protect carbon steel and copper alloys in aging infrastructure. These formulations are expanding most quickly as European operators extend asset life cycles under EU Green Deal decarbonization pressures that delay new capital investment.
- Scale Inhibitors:Polyphosphate and polymer-based dispersants control calcium carbonate and silica deposition in high-cycles-of-concentration operation.
- pH Regulators:Sulfuric acid and caustic soda dosing maintains alkalinity within 6.5-9.0 operational bands for heat transfer efficiency.
Established volume favors chemical biocides; emerging adoption favors corrosion inhibitors.
End User:
Capital intensity and water throughput separate continuous-process industries from intermittent-load commercial systems.
- Power Generation:Coal, gas, and nuclear thermal plants require the highest chemical dosing rates per megawatt of installed capacity. Facilities in Shandong province and the US Midwest sustain demand for specialized scale inhibitor formulations.
- Manufacturing:Steel, cement, and automotive plants operate smaller cooling towers with standardized chemical programs.
- HVAC Systems:Commercial building contractors specify pre-formulated inhibitor-biocide blends through distributor channels with tighter margin structures.
- Oil & Gas:Refinery cooling networks and petrochemical crackers in the US Gulf Coast and Rotterdam corridor demand high-performance treatments for hydrocarbon-contaminated water.
Power generation commands absolute tonnage; oil and gas offers specification premiums.
Application:
Process integration depth determines whether chemicals serve primary heat rejection or secondary utility loops.
- Cooling Systems:Evaporative towers and closed-loop chillers represent the core consumption channel with recurring biocide demand cycles.
- Water Treatment:Pretreatment chemicals for makeup water softening and filtration support cooling tower chemistry balance.
- Industrial Processes:Direct-contact cooling in smelters and chemical reactors requires specialized high-temperature formulations.
- Chemical Processing:Petrochemical and specialty chemical plants integrate cooling tower chemicals with broader process water management.
Cooling systems anchor recurring revenue; industrial processes enable technical differentiation.
Distribution Channel:
Service bundling requirements reshape procurement patterns between integrated providers and commodity distributors.
- Direct Sales:Nalco and Evoqua anchor long-term service agreements with on-site technical support and digital monitoring platforms.
- Distributors:Regional chemical distributors serve independent power producers and manufacturing facilities with spot-market procurement flexibility.
- Online Retail:Standardized biocide and inhibitor formulations move through e-commerce channels for small commercial HVAC contractors.
- Agents:Commission-based representatives penetrate underdeveloped service infrastructure in Vietnam and Indonesia petrochemical corridors.
Direct sales capture integrated contracts; distributors retain price-sensitive volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical exports supply corrosion inhibitor formulations to power utilities across Poland and the Czech Republic. This trade corridor reflects broader patterns where formulation expertise concentrates in industrialized economies while demand growth shifts toward thermal capacity expansion zones.
United States
Independent power producers in Texas and Ohio drive disintermediation trends by unbundling chemical supply from technical service. The US EPA enforces stricter NPDES permitting on cooling water intake structures under the Clean Water Act. Facilities along the Gulf Coast petrochemical corridor upgrade biofouling control programs to meet discharge limits.
China
Thermal power capacity additions in Shandong and Guangdong provinces absorb specialized scale inhibitor formulations for high-cycles-of-concentration operation. The MEE implements water quality standards that tighten discharge requirements across industrial cooling systems. Petrochemical cluster expansions in the Yangtze River Delta require integrated water management contracts.
Germany
Food and beverage processors pilot enzyme-based biofilm dispersants to meet EFSA discharge limits. The EU F-Gas Regulation phase-down drives chemical treatment intensity to compensate for reduced refrigerant charge. Industrial operators in the Ruhr region face REACH biocide reauthorization deadlines that force reformulation transitions.
Australia
Mining and smelting operations adopt high-intensity chemical regimes under zero-liquid-discharge mandates in water-stressed jurisdictions. State-level water scarcity regulations force evaporative cooling designs with elevated chemical dosing requirements. Western Australian iron ore processing hubs source scale control polymers for coastal high-salinity blowdown conditions.
Vietnam
Petrochemical cluster expansions lack established chemical service infrastructure, creating first-mover positioning opportunities. The country's national environmental regulator tightens industrial discharge standards as foreign direct investment flows into manufacturing. Formulation suppliers deploy agent networks to penetrate underdeveloped service corridors around the Cái Mép industrial zone.
Cooling Tower Chemicals Market Competitive Landscape
Listed leaders compete with private specialists across integrated service bundling. The vendor base separates into three tiers: multinational water treatment platforms with digital monitoring capabilities, regional chemical distributors serving spot-market procurement, and equipment-integrated formulators supplying packaged solutions. Consolidation pressures favor players with captive technician networks and predictive analytics platforms. Dominant competitive moves include geographic expansion through agent networks in Southeast Asia and portfolio diversification into enzyme-based biofilm control.
Within the integrated service tier, Nalco Company and Evoqua Water Technologies exemplify divergent geographic anchoring strategies. Nalco leverages its digital monitoring platform to secure long-term agreements with Midwest independent power producers. Evoqua sustains regional service density that compresses response times for cooling tower upsets in manufacturing corridors. Siemens occupies a position bridging equipment manufacturing with chemical formulation supply. These three players represent distinct archetypes: technology-anchored service integration, technician-network regional density, and industrial automation convergence.
| Leading Market Players |
|---|
| Nalco Company |
| Evoqua Water Technologies |
| GE Water and Process Technologies |
| Siemens |
| IDE Technology |
| SPX Technologies |
| Johnson Controls International |
| Cooling Tower Systems |
| Paharpur Cooling Towers |
| Others |
Value Network & Pricing Analysis
Long-term service agreements with integrated water management providers lock in supply access while flattening price visibility for power generation utilities across the US Midwest and China's Shandong province. These multi-year contracts bundle chemical delivery, digital monitoring hardware, and on-site technical response into predictable operational expenditure structures that insulate buyers from spot-market volatility in biocide active ingredients.
Pricing Analysis
Next-generation enzyme-based biofilm dispersants command formulation premiums over legacy oxidizing biocides in European food and beverage processing applications. Three-tier pricing structure across premium, standard, and economy levels separates integrated service contracts with predictive analytics from commodity distributor spot purchases and basic biocide blends for commercial HVAC. Pricing pressure stems from REACH reauthorization cycles forcing 18-24 month reformulation investments. Independent power producers in Texas and Ohio exhibit highest price sensitivity through unbundled procurement, while zero-liquid-discharge mining operations in Australia accept premium positioning for specialized scale control polymers.
Supply Chain Analysis
Inventory buffers for biocide active ingredients stretch to 12-16 weeks as European REACH registration deadlines constrain raw material availability. Manufacturing concentration centers on Germany for corrosion inhibitor formulation expertise, China for scale inhibitor polymer production, and the United States for integrated service platform assembly. Raw material dependencies include isothiazolinone biocide actives, molybdate corrosion inhibitors, and polyacrylate scale dispersants. Single-source vulnerability runs through specialty chemical intermediate suppliers in the Rhine-Ruhr corridor. Distribution runs through direct sales teams for integrated contracts and regional chemical distributors for spot-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across service intensity tiers creates entry niches as buyers disaggregate chemical supply from technical support. Digital monitoring platform differentiation and regional technician density separate competitive positioning in ways that favor focused specialists over broad-line suppliers.
For Market Incumbents: Consolidate technician network coverage in manufacturing corridors where response time compression anchors contract renewal rates. Deepen backward integration into biocide active ingredient synthesis to mitigate REACH supply disruption exposure. Capture emerging enzyme-based formulation capabilities through targeted R&D partnerships with German food and beverage processors piloting EFSA-compliant alternatives.
For New Entrants and Emerging Players: Lead with smart dosing system integration combining IoT conductivity sensors with automated chemical feed pumps as the technical wedge for mid-sized independent power producers. Target Vietnam and Indonesia petrochemical corridors where established service infrastructure remains underdeveloped. Deploy agent-based distribution to penetrate Cái Mép industrial zone before integrated providers achieve technician density.
For Investors and Strategic Acquirers: Capital is best deployed toward regional service specialists with captive technician networks and existing digital monitoring deployments across the analysis window. Acquisition candidates exhibiting predictive analytics platform integration and zero-liquid-discharge project experience command positioning premiums. Monitor EU F-Gas Regulation implementation pace as inflection indicator for cooling system efficiency-driven chemical treatment intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide Actives | Mitigates REACH reauthorization supply disruption for multinational formulation portfolios. |
| Smart Dosing System Deployment | Enables real-time optimization that reduces overdosing waste for power generation utilities. |
| Enzyme-Based Formulation Development | Captures EFSA-compliant substitution demand from German food and beverage processors. |
| Regional Technician Network Expansion | Compresses response times for cooling tower upsets in US Midwest manufacturing corridors. |
| Zero-Liquid-Discharge Capability Buildout | Addresses South African and Australian mining regulatory mandates with specialized polymer formulations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, chemical industry association reports, and regulatory filing databases covering EPA NPDES permits and REACH biocide registrations. Plant managers at thermal power facilities, procurement leads at independent power producers, distribution channel partners in Southeast Asia, and technical R&D directors at specialty chemical formulators provided operational perspective. Bottom-up demand modeling across end-use segments triangulates against top-down market sizing from production capacity and consumption intensity benchmarks.
Segmentation dimensions modeled include product type tier, end-use industry vertical, application process integration depth, and distribution channel service bundling level across the projection horizon. CAGRs derive from installed capacity expansion trajectories, regulatory enforcement intensity indices, and chemical dosing rate evolution assumptions. Forecast inputs incorporate thermal power capacity addition schedules in China, US EPA Clean Water Act implementation pace, and water scarcity regulation expansion patterns in mining-intensive economies.
The analysis sits within stated boundaries; outcomes outside sustained thermal capacity investment, stable regulatory enforcement trajectories, or continued water stress index deterioration would require recalibration. Forecasts reflect documented assumptions regarding biocide active ingredient supply continuity and digital platform adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Rodenticides Market