
 Hydraulic Oil Additives Market | 2026-2036
Hydraulic Oil Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Oil Additives Market Analytics
Fluid-condition monitoring subscriptions bundled with additive replenishment is realigning how hydraulic oil additives reach end users. The Lubrizol Corporation leverages its diagnostics partnerships to embed additive dosing within predictive maintenance contracts. Afton Chemical Corporation anchors its position through captive supply of phosphorus-free anti-wear packages to European OEMs. BASF SE differentiates via backward integration into polyalkylene glycol base stocks for fire-resistant hydraulic fluids.
Hydraulic oil additives are chemical compounds blended into base hydraulic fluids to enhance oxidation stability, reduce wear on pump components, and maintain viscosity across temperature extremes; typical treat rates range from 0.1% to 5% by volume depending on the additive function and system severity. Their primary commercial purpose is to extend fluid service life and protect high-pressure hydraulic systems in mobile and stationary equipment. Anti-wear agents command the largest volume share within the type segment, though ashless variants are gaining fastest as zinc-free formulations displace traditional ZDDP chemistry in environmentally sensitive applications. The construction equipment application segment carries the deepest margin pools due to severe-duty cycles and OEM-mandated fluid specifications that lock in approved supplier lists.
EPA regulations on zinc and phosphorus discharge limits constrain conventional ZDDP formulations in the United States, while REACH registration requirements in Europe enforce full toxicity profiling for new additive chemistries. Japan's METI has tightened energy-efficiency standards for hydraulic systems, indirectly elevating demand for friction-modifying additives that reduce pump energy losses. Formulators and end users must track divergence between regional chemical restriction timelines when designing unified additive platforms.
Market Dynamics
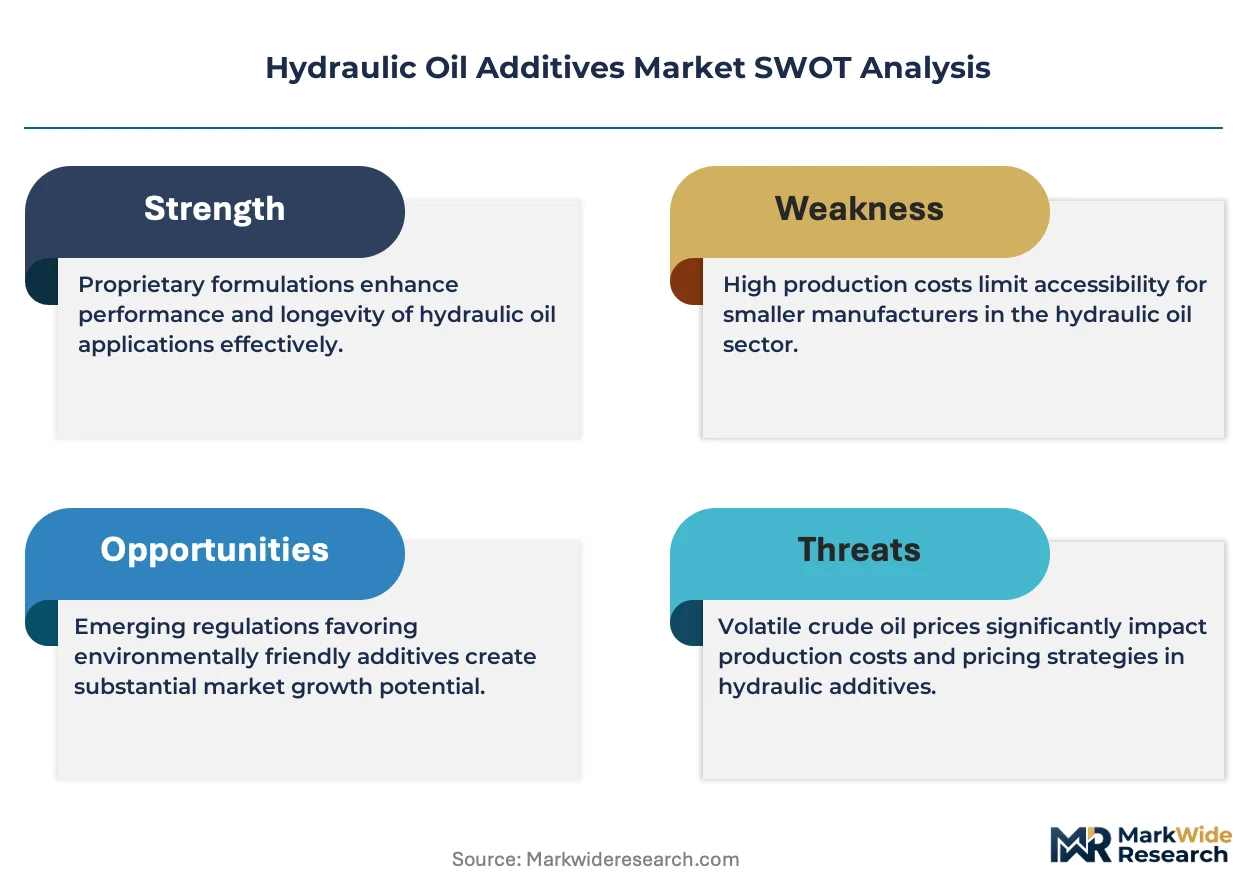
EU REACH restrictions on zinc and phosphorus content are forcing formulators to abandon conventional ZDDP chemistry, compressing margins for additive suppliers while opening premium positioning for ashless alternatives. This regulatory pivot is reshaping competitive advantage around toxicology dossier depth rather than cost efficiency.
Growth Catalysts
- Extended drain intervals:Construction equipment OEMs in Germany and the United States now specify 4,000-hour fluid life, requiring high-dose antioxidant and anti-wear packages that lock in approved supplier relationships.
- Fire-resistant fluid mandates:Germany's metalworking sector drives demand for polyalkylene glycol base stocks, which cannot function without specialized additive chemistries for viscosity and oxidation control.
- Energy-efficiency standards:Japan's METI regulations on hydraulic system efficiency elevate friction modifier treat rates to reduce pump energy losses in industrial machinery.
Market Restraints
- Base stock supply concentration:Group II/III paraffinic base oil production clusters in the US Gulf Coast and Singapore, creating freight cost penalties for European compounders.
- REACH registration costs:Full toxicity profiling for novel ashless anti-wear molecules demands seven-figure dossier investments that freeze mid-tier formulators out of premium segments.
- Mineral oil substitution:Synthetic ester and vegetable-based hydraulic fluids in Scandinavian markets bypass conventional additive architectures entirely.
Strategic Opportunities
- Fluid-condition monitoring bundling:Predictive maintenance platforms in German automotive stamping plants create attach-rate potential for automated additive replenishment systems.
- Phosphorus-free approvals:OEM factory-fill specifications from Volvo Construction Equipment and Caterpillar open captive supply positions for REACH-compliant anti-wear packages.
- Remanufactured equipment channels:Rebuilt hydraulic systems in US construction fleets require reformulated break-in additives with different friction profiles than virgin fills.
Industry Challenges
- Tribochemistry expertise scarcity:Formulators struggle to recruit specialists capable of modeling ashless anti-wear film formation under mixed lubrication regimes in high-pressure piston pumps.
- Dual-certification timelines:Additive packages must simultaneously secure OEM approvals and REACH registration, extending commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Oil Additives Market |
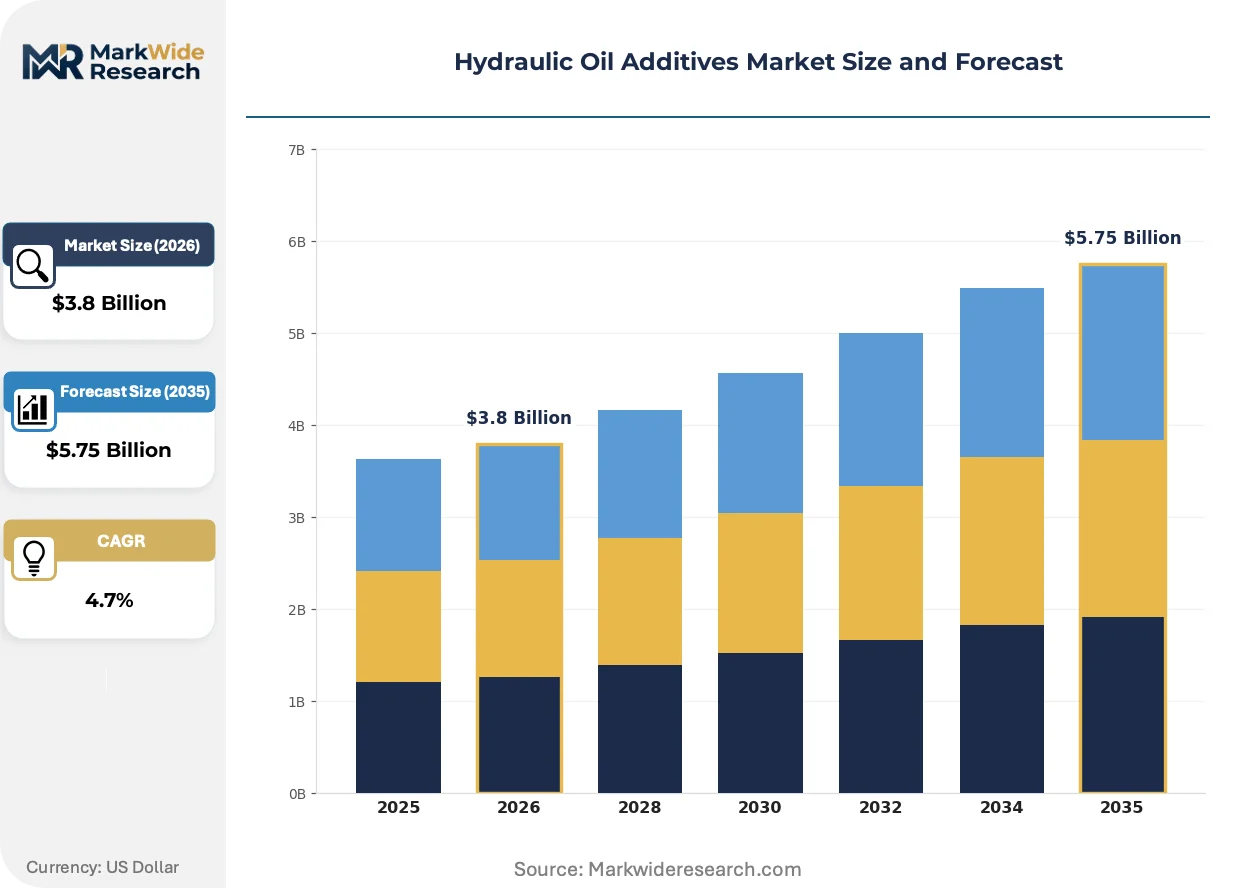
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Antioxidants, Anti-Wear Agents, Corrosion Inhibitors, Viscosity Improvers Application: Industrial Machinery, Automotive, Marine, Construction Equipment Form: Liquid, Powder, Emulsion, Concentrate End User: Manufacturers, Service Providers, Distributors, Maintenance Facilities |
| Companies Covered | The Lubrizol Corporation, Afton Chemical Corporation, Chevron Oronite Company LLC, BASF SE, Evonik Industries AG, Infineum International Limited, Vanderbilt Chemicals LLC, Croda International PLC, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Oil Additives Market Evolving Landscape
Ashless anti-wear chemistry is overtaking zinc-based formulations as the dominant technical platform, redefining R&D priorities and supplier qualification criteria across mobile and stationary hydraulic systems. This transition is compressing the viable product portfolio for traditional ZDDP compounders.
Boron-based friction modifiers is overtaking traditional sulfur-phosphorus chemistry in high-precision servo valves, where deposit control outweighs extreme-pressure performance. Japanese machine tool builders specify these formulations for energy-efficient hydrostatic guideways. The technology is overtaking legacy packages in applications where varnish formation risks catastrophic valve seizure.
EPA discharge limits on zinc and phosphorus in US industrial wastewater are tightening enforcement thresholds for metalworking shops using conventional hydraulic fluids. Facilities in Ohio and Michigan now face monthly reporting obligations that elevate compliance costs above the price premium for zinc-free alternatives. California's Safer Consumer Products regulations are extending scrutiny to hydraulic fluid formulations used near sensitive watersheds.
Subscription-based fluid management is displacing spot purchasing in multi-site construction fleets, bundling analysis, filtration, and additive replenishment into per-hour contracts. Equipment rental companies in Texas and Florida pilot these arrangements to transfer technical risk from site managers to fluid service providers. The model concentrates procurement authority at fleet headquarters, reducing the addressable market for regional lubricant distributors.
Hydraulic Oil Additives Market Segmentation
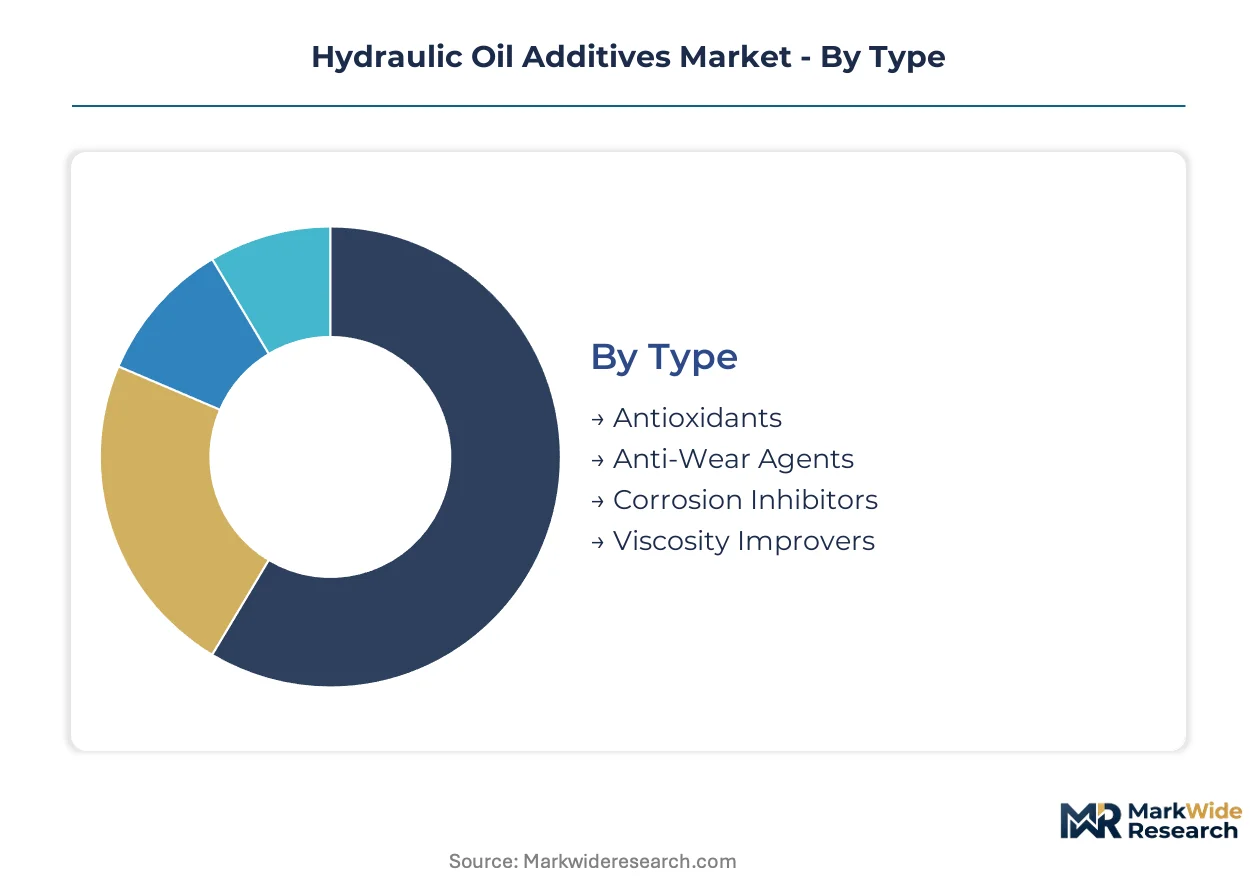
Hydraulic oil additives serve distinct functional roles across equipment types, with formulation chemistry and delivery form determining compatibility with base stocks and system severity. Segmentation reveals where specification premiums concentrate and which upgrade cycles drive volume.
Type:
Replacement cycles for high-pressure hydraulic systems are extending, forcing additive portfolios to cover longer service intervals with fewer reformulations.
- Antioxidants:Phenolic and aminic compounds scavenge free radicals to prevent base oil oxidation and sludge formation in high-temperature circuits. Demand clusters in German plastics injection molding machinery, where 6,000-hour fluid life specifications now dominate OEM approvals.
- Anti-Wear Agents:Zinc dialkyldithiophosphate (ZDDP) and ashless phosphorus-sulfur alternatives form protective tribofilms on pump vanes and piston slippers. REACH-compliant ashless variants are displacing conventional chemistry in Volvo Construction Equipment and Caterpillar factory-fill specifications across European assembly plants.
- Corrosion Inhibitors:Carboxylic acid derivatives and amine-based rust preventers protect ferrous components in humid environments.
- Viscosity Improvers:Polymethacrylate and olefin copolymer thickeners maintain fluid film thickness across arctic-to-desert temperature swings.
Anti-wear agents sit at the top of the volume ranking, with antioxidants climbing the fastest as drain interval extensions outpace equipment fleet growth.
Application:
Cost tier segmentation separates specification-locked OEM factory fills from aftermarket replenishment, with premium pricing attaching to severe-duty cycles.
- Industrial Machinery:Metal stamping presses, injection molding equipment, and machine tool hydraulics require friction modifiers for energy-efficient servo valves. Japanese METI efficiency standards are elevating treat rates in Osaka and Nagoya manufacturing clusters.
- Construction Equipment:Excavators, loaders, and mobile cranes operate under high-pressure, high-contamination conditions that demand complete additive packages. OEM-mandated 4,000-hour fluid life in German and US fleets locks in approved supplier relationships and deepest margin pools.
- Automotive:Power steering and suspension hydraulics use lower-dose additive systems with tighter compatibility constraints.
- Marine:Offshore deck machinery and stabilizer systems face saltwater corrosion challenges and fire-resistant fluid requirements.
Construction equipment commands the specification premium tier, with industrial machinery expanding most quickly on energy-efficiency regulatory pressure.
Form:
Supply concentration around liquid bulk logistics favors high-volume delivery modes, though concentrate economics reshape procurement at fleet scale.
- Liquid:Ready-to-blend additive packages dissolve directly into base stocks at formulator blending plants. Standard bulk delivery dominates US Gulf Coast and Singapore compounding clusters.
- Concentrate:High-potency additive streams reduce freight costs for remote mining and construction sites. Australian iron ore operations and Canadian oil sands projects specify concentrate dosing systems to cut inbound logistics spend.
- Powder:Solid-state delivery for specialized grease compounding and extreme-temperature applications.
- Emulsion:Water-based formulations for fire-resistant hydraulic fluids in steel mills and underground mining.
Liquid form retains the highest shipment volumes, with concentrate gaining share fastest in remote resource extraction logistics chains.
End User:
Customer type determines whether procurement authority sits with technical staff or centralized fleet management, reshaping distribution channel economics.
- Manufacturers:OEM factory-fill specifications demand pre-approved additive packages with locked chemistry and traceability documentation. German automotive stamping press builders and Japanese machine tool makers maintain captive supplier lists with 24-month qualification cycles.
- Maintenance Facilities:Independent repair shops and dealer service centers perform in-warranty fluid changes and top-off services. Subscription-based fluid management platforms in Texas and Florida construction fleets are consolidating procurement authority away from site-level purchasing.
- Service Providers:Fluid analysis and filtration contractors bundle additive replenishment into predictive maintenance contracts.
- Distributors:Regional lubricant blenders and jobbers serve spot-purchase aftermarket demand.
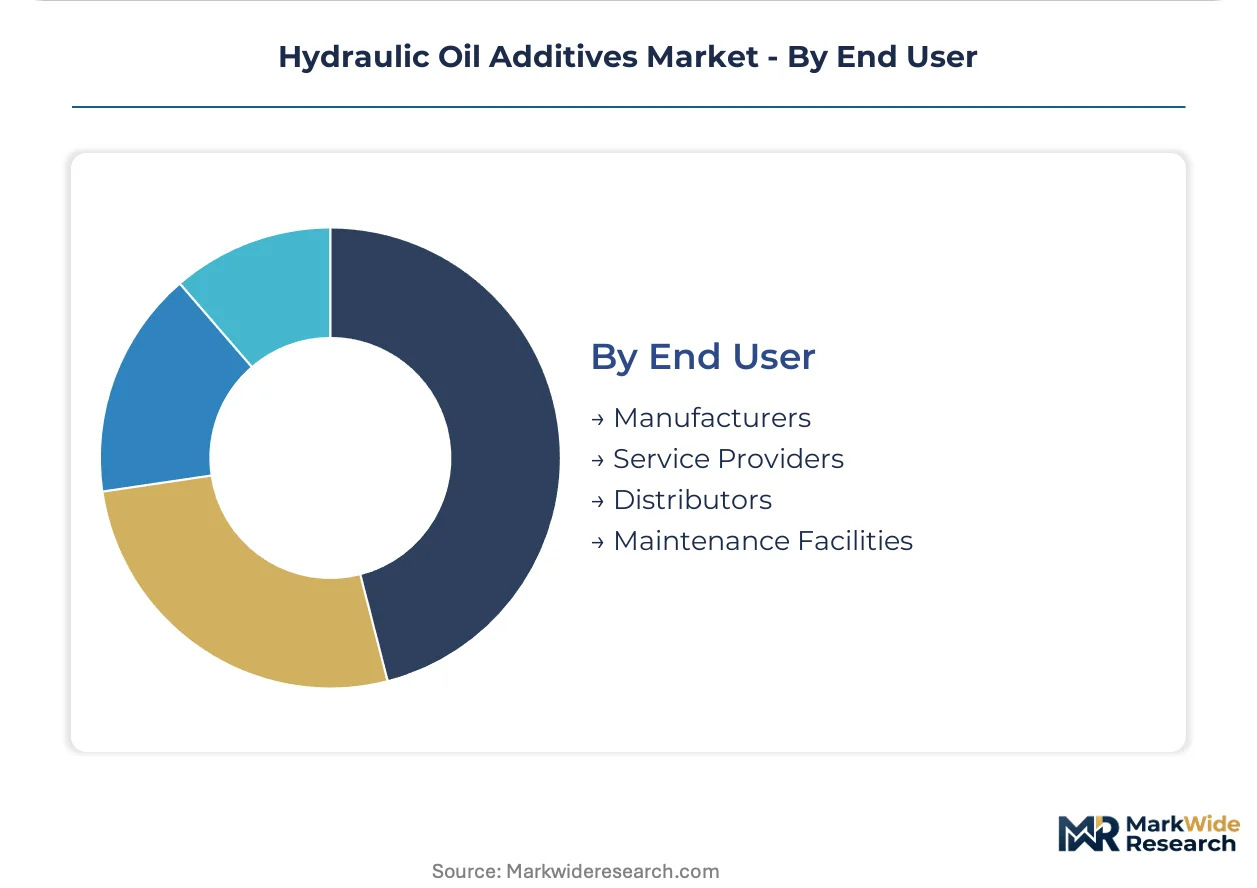
Manufacturers control the highest-value factory-fill segment, with maintenance facilities showing the steepest channel transformation toward bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hydraulic system density in metalworking machinery outpaces US construction equipment fleets in additive consumption per installed base, while Japan's energy-efficiency mandates create distinct formulation requirements absent in North American specifications.
United States
Construction equipment rental fleets in Texas and Florida pilot subscription-based fluid management contracts that bundle additive replenishment with predictive maintenance. EPA discharge limits on zinc and phosphorus in industrial wastewater tighten enforcement thresholds for metalworking shops in Ohio and Michigan. The US Gulf Coast hosts concentrated Group II/III paraffinic base oil production that supplies regional compounders.
Germany
Plastics injection molding machinery and automotive stamping presses specify 6,000-hour fluid life, demanding high-dose antioxidant packages that lock in approved supplier relationships. EU REACH registration requirements enforce full toxicity profiling for new additive chemistries, freezing mid-tier formulators out of premium segments. The metalworking sector in Bavaria and North Rhine-Westphalia drives demand for polyalkylene glycol base stocks with specialized additive chemistries.
Japan
METI energy-efficiency standards for hydraulic systems elevate friction modifier treat rates to reduce pump energy losses in Osaka and Nagoya manufacturing clusters. Machine tool builders specify boron-based friction modifiers for hydrostatic guideways where varnish formation risks catastrophic valve seizure. Japanese OEM factory-fill specifications maintain 24-month qualification cycles with captive supplier lists.
China
Dual carbon goals and tightening environmental standards accelerate displacement of conventional additive architectures in industrial machinery. The national chemical regulator enforces stricter toxicity profiling for hydraulic fluid formulations used in sensitive watersheds. Yangtze River Delta manufacturing clusters concentrate demand for fire-resistant hydraulic fluids in steel production and underground mining equipment.
Australia
Iron ore operations in Western Australia specify concentrate dosing systems to cut inbound logistics spend on remote mining sites. The country's mining sector drives demand for extreme-duty additive packages in high-contamination hydraulic systems. Queensland and New South Wales construction fleets extend drain intervals through fluid-condition monitoring platforms.
Hydraulic Oil Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation houses controlling OEM factory-fill specifications and regional blenders capturing aftermarket replenishment. The vendor base concentrates around toxicology dossier depth rather than manufacturing scale, advantaging incumbents with seven-figure REACH registration investments. Three archetypes dominate: integrated petrochemical majors with captive additive supply, independent formulators with OEM approval depth, and regional compounders serving spot-purchase demand. Competitive moves center on diagnostics partnerships for predictive maintenance bundling and backward integration into polyalkylene glycol base stocks for fire-resistant fluid lines.
Within the integrated majors tier, BASF SE and Evonik Industries AG exemplify petrochemical conglomerates with upstream control over specialty chemical feedstocks. Among independent formulators, The Lubrizol Corporation and Afton Chemical Corporation occupy positions defined by OEM approval breadth and factory-fill specification capture. LANXESS AG represents the mid-tier European specialist archetype with concentrated exposure to REACH-compliant industrial applications.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Afton Chemical Corporation |
| Chevron Oronite Company LLC |
| BASF SE |
| Evonik Industries AG |
| Infineum International Limited |
| Vanderbilt Chemicals LLC |
| Croda International PLC |
| LANXESS AG |
| Others |
Value Network & Pricing Analysis
Group II/III paraffinic base oil spot indices on the US Gulf Coast cascade through hydraulic additive pricing tiers, compressing margins for European compounders facing Atlantic freight premiums while rewarding backward-integrated majors with captive feedstock supply.
Pricing Analysis
Capacity additions in Singapore and the US Gulf Coast are reshaping price floors for antioxidant and anti-wear packages, forcing European formulators into premium positioning around REACH-compliant ashless chemistry to defend margin structures. Three-tier pricing stratifies across OEM-approved factory fills, dealer service channels, and spot-purchase aftermarket tiers, with certification depth and toxicity dossier investment as the primary price differentiation drivers. Cost compression in mid-tier ZDDP formulations is intensifying because REACH registration timelines freeze out smaller compounders. Fleet operators and rental companies show lowest price sensitivity due to bundled predictive maintenance contracts, while independent maintenance facilities face acute margin pressure from subscription-based fluid management platforms.
Supply Chain Analysis
OEM qualification gates and REACH toxicity dossier requirements fragment supply chain access, advantaging incumbents with seven-figure registration investments over mid-tier challengers. Geographic concentration centers on Germany for polyalkylene glycol base stocks, the United States for Group II/III paraffinic oils, and Japan for boron-based friction modifier feedstocks. Raw material dependencies rest on phosphorus pentasulfide for ZDDP production, alkylated diphenylamines for antioxidants, and boron esters for servo valve formulations. Single-source vulnerability in ashless anti-wear molecule supply creates structural risk as formulators abandon conventional ZDDP chemistry. Distribution runs through captive direct supply to OEM blending plants for factory fills, with regional distributors serving fragmented aftermarket replenishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-registered European formulations commanding specification premiums and US Gulf Coast compounders leveraging feedstock proximity, with regulatory compliance cost differentials exceeding freight penalties for cross-Atlantic supply.
For Market Incumbents: Anticipate accelerated displacement of ZDDP chemistry by positioning ashless anti-wear portfolios ahead of EPA discharge limit enforcement in Ohio and Michigan metalworking clusters. Deepen toxicology dossier libraries to extend qualification moats against mid-tier formulators frozen out by seven-figure REACH investments. Prioritize diagnostics partnerships with German automotive stamping press builders to embed additive replenishment within predictive maintenance contracts and lock out spot-purchase competitors. For New Entrants and Emerging Players: Launch via concentrate dosing systems targeting remote Australian iron ore operations and Canadian oil sands projects where inbound logistics costs dominate procurement decisions. White-space opportunity concentrates in phosphorus-free break-in additives for US remanufactured construction equipment channels, where friction profiles differ from virgin OEM specifications. Penetrate Scandinavian markets through synthetic ester and vegetable-based hydraulic fluid formulations that bypass conventional additive architectures entirely. For Investors and Strategic Acquirers: Asymmetric upside sits with independent formulators possessing deep OEM approval breadth but lacking backward integration into specialty chemical feedstocks, creating acquisition targets for petrochemical majors seeking REACH-compliant positioning. Long-term viability hinges on toxicology expertise scarcity and dual-certification timeline barriers that extend commercialization cycles. Watch for inflection signals in Volvo Construction Equipment and Caterpillar factory-fill specification migrations toward ashless chemistry as leading indicators of captive supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyalkylene Glycol Base Stocks | BASF SE's captive supply of fire-resistant fluid feedstocks locks in German metalworking sector demand. |
| Diagnostics Partnership for Predictive Maintenance Bundling | Lubrizol's fluid-condition monitoring subscriptions realign procurement authority toward fleet headquarters. |
| REACH-Compliant Ashless Anti-Wear Package Development | Afton Chemical's phosphorus-free approvals capture Caterpillar and Volvo factory-fill specifications. |
| Concentrate Dosing System Deployment | Remote mining operations in Western Australia cut logistics spend through high-potency additive streams. |
| Boron-Based Friction Modifier Qualification | Japanese machine tool builders specify these formulations for METI-compliant energy-efficient hydrostatic guideways. |
Research Methodology
Multiple input streams — technical discussions with hydraulic fluid formulators and OEM procurement teams, trade data analysis from customs and chemical industry associations, and regulatory filing review from EPA and ECHA databases — were reconciled through bottom-up volume modeling and top-down market sizing validation. Primary engagement encompassed plant managers at German plastics injection molding machinery operators, maintenance directors at Texas construction equipment rental fleets, R&D directors at additive compounders, and service heads at fluid analysis contractors. Secondary sources included SEC 10-K filings from listed chemical majors, Cefic sector reports, and REACH registration dossier summaries.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling covered additive function type, application severity tier, delivery form, and end-user procurement authority structure. CAGRs were derived from equipment fleet growth rates, drain interval extension trends, and regulatory-driven chemistry transition timelines. Forecast inputs incorporated OEM factory-fill specification migration patterns and METI energy-efficiency standard implementation progress in Japanese manufacturing clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA enforcement of zinc discharge limits or unexpected delays in ashless anti-wear tribochemistry qualification. Model outputs reflect assumptions around REACH registration timelines, base oil price volatility, and OEM approval cycle durations. A model refresh is warranted upon material change in Volvo Construction Equipment or Caterpillar factory-fill specification announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Anti-Static Oil Market
Lubricants
Norway Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Aviation Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Germany Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Thailand Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market