
 Italy Commercial Vehicles Lubricants Market | 2026-2036
Italy Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Commercial Vehicles Lubricants Market Foresight
Fleet operators are unwinding the historical preference for independent workshop procurement. Small transport companies and owner-operators still dominate unit volume. Eni SpA leverages its integrated refining network to anchor supply security across the Po Valley. Shell competes through premium synthetic formulations calibrated for Euro VI powertrains. FUCHS specializes in high-performance hydraulic oils targeting construction machinery applications.
Italy commercial vehicles lubricants encompass formulated petroleum-based and synthetic fluids engineered to reduce friction, dissipate heat, and prevent wear in diesel engines, transmissions, and auxiliary systems operating under severe load cycles. These products typically meet SAE viscosity grades 10W-40 and 5W-30 for engine oils, with total base numbers ranging from 9 to 14 mg KOH/g to neutralize acidic combustion byproducts. Engine oils command the dominant value share given extended drain intervals and OEM specification complexity. Transmission fluids represent the fastest-growing product category as automated manual transmissions proliferate in heavy-duty trucks. Hydraulic oils maintain stable margin pools in construction and agricultural vehicle segments where equipment utilization rates remain elevated.
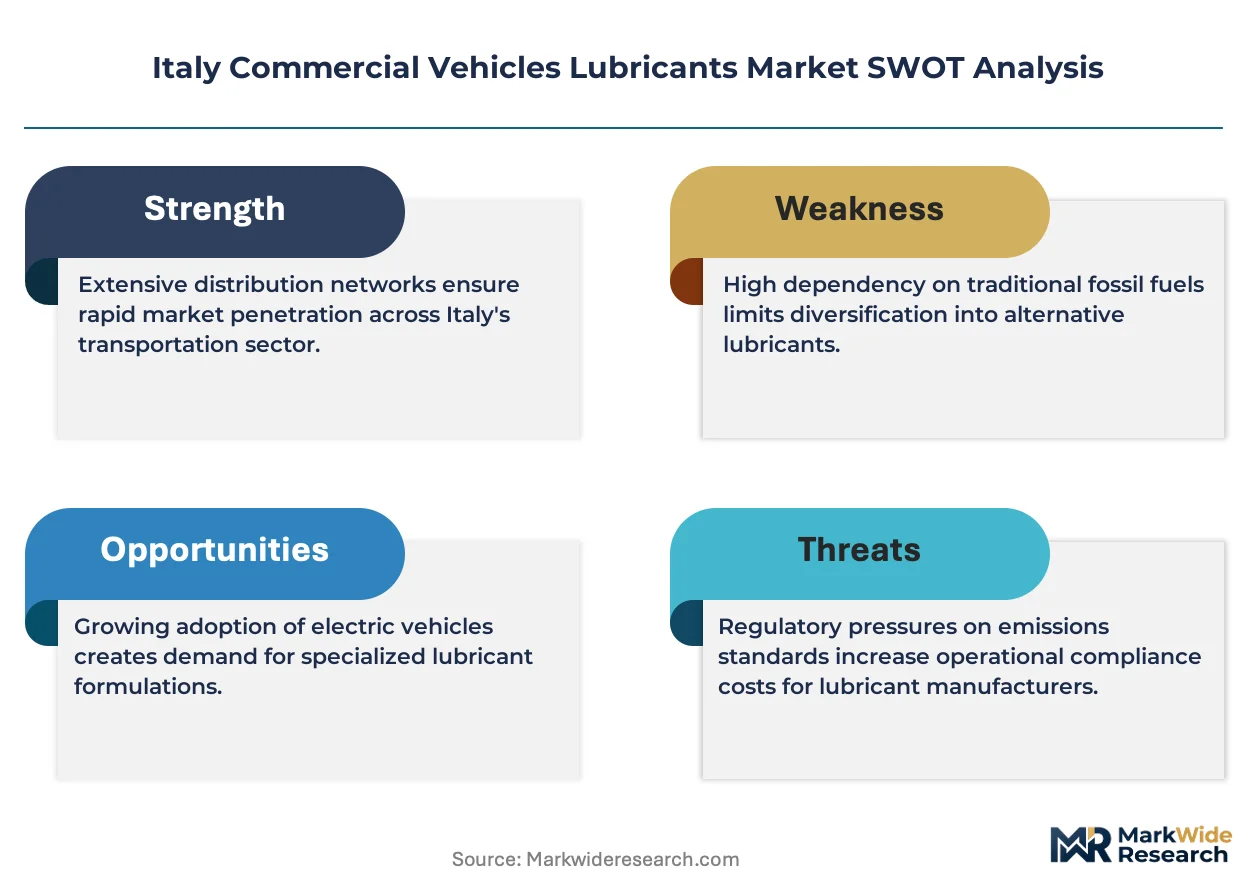
Italy's lubricant market operates under REACH chemical registration requirements, EU F-Gas Regulation constraints on fluorinated greenhouse gases in mobile air conditioning, and CE marking obligations for products entering the broader European Economic Area. These frameworks compel reformulation investments, tighten supply chain documentation, and elevate compliance costs for imported formulations. Stakeholders must monitor the interplay between EU Green Deal implementation timelines and fleet electrification trajectories that could structurally compress engine oil demand while creating new thermal management fluid requirements.
Market Dynamics
The EU Green Deal emission standards are forcing reformulation across the entire lubricant value chain, as fleet operators accelerate adoption of lower-viscosity synthetic grades to meet Euro VI powertrain requirements while maintaining drain interval performance.
Growth Catalysts
- Automated manual transmission proliferation:Heavy-duty truck fleets are upgrading drivetrain configurations, creating demand for specialized transmission fluids with enhanced shear stability and thermal management properties.
- REACH chemical registration compliance:The regulatory framework mandates documented supply chain transparency, rewarding domestic blenders with established registration portfolios and technical dossiers.
- Construction machinery utilization rates:Northern Italy's infrastructure project pipeline sustains elevated equipment operating hours, driving consumption of high-performance hydraulic oils in excavators and mobile cranes.
Market Restraints
- Base oil supply concentration:European Group II/III base stock production clusters in Rotterdam and Antwerp create import dependency for Italian blenders, exposing margins to freight rate volatility and currency fluctuations.
- Group III+ synthetic feedstock cost structure:Gas-to-liquids and hydrocracked base oils command premium pricing that compresses formulation flexibility for mid-tier product lines serving price-sensitive owner-operators.
- Fleet electrification trajectory uncertainty:Battery-electric and hydrogen fuel cell commercial vehicle pilot programs threaten long-term engine oil demand volumes without clear timeline visibility for thermal management fluid replacement economics.
Strategic Opportunities
- Southern Italy logistics corridor development:Port expansion at Gioia Tauro and Bari combined with Adriatic freight routing investments could redistribute commercial vehicle density away from the saturated Po Valley.
- EU F-Gas Regulation mobile air conditioning mandates:Low-global-warming-potential refrigerant transitions require compatible compressor lubricants, opening formulation partnerships with HVAC system suppliers.
- Telematics-enabled predictive maintenance:Integration of oil condition sensors with fleet management platforms allows lubricant suppliers to embed themselves in subscription-based service ecosystems.
Industry Challenges
- Additive chemistry technical specialist scarcity:Formulation chemists with expertise in friction modifier synergy and dispersant optimization for extended-drain applications command premium compensation that strains mid-size blender R&D budgets.
- OEM specification certification timelines:Volvo, MAN, and Iveco powertrain approvals require 18-24 month validation cycles, delaying product launches and locking competitors into specification hierarchies.
- Legacy workshop inventory system integration:Independent service providers operate on paper-based or basic ERP platforms that resist API connectivity for automated replenishment and technical bulletin distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Commercial Vehicles Lubricants Market |
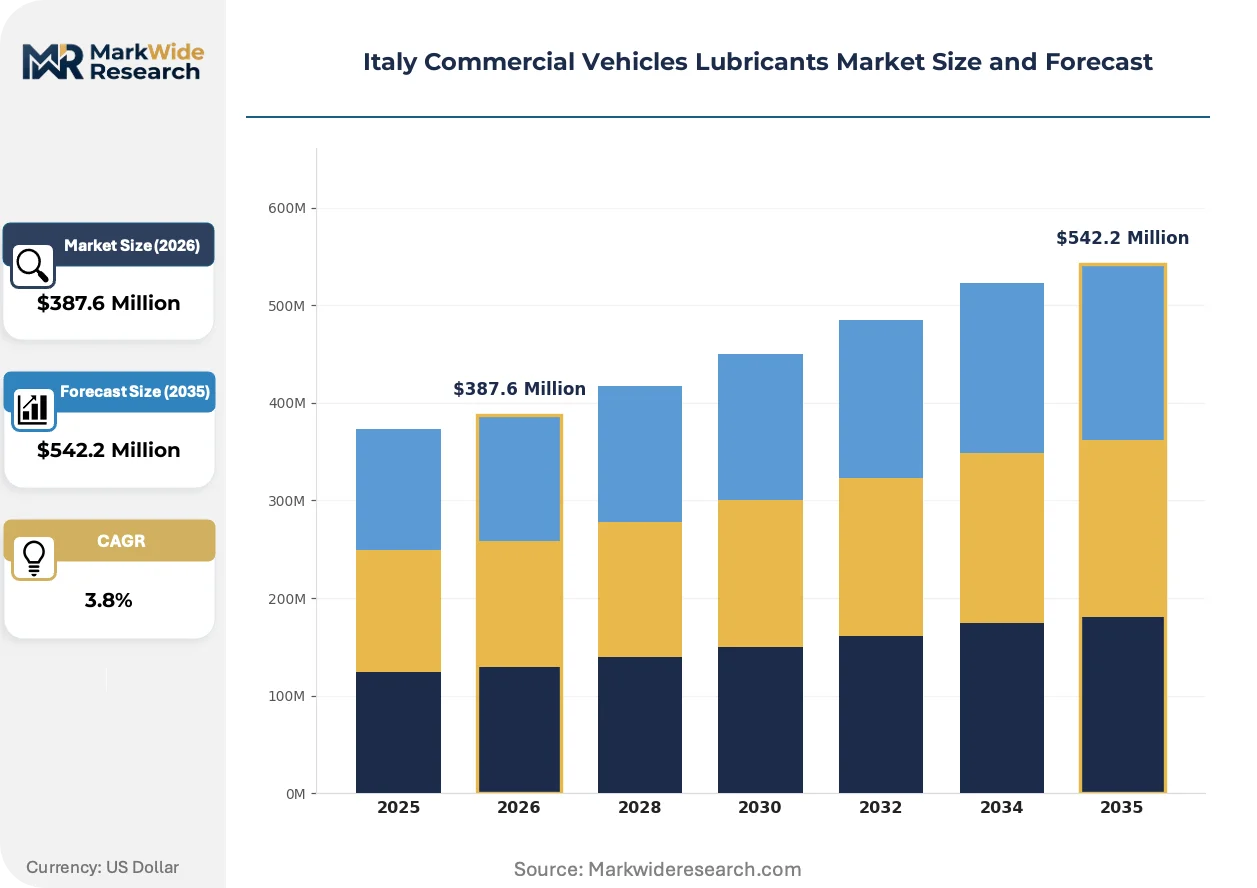
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $542.2 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Transmission Fluids, Hydraulic Oils, Greases End User: Fleet Operators, Transport Companies, Logistics Providers, Maintenance Centers Application: Heavy-Duty Trucks, Buses, Construction Machinery, Agricultural Vehicles Distribution Channel: Retail Stores, Online Platforms, Distributors, Direct Sales |
| Companies Covered | Eni SpA, BP PLC (Castrol), Royal Dutch Shell Plc, PETRONAS Lubricants International, Q8Oils, ExxonMobil Corporation, FUCHS, TotalEnergies, Repsol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Commercial Vehicles Lubricants Market Shifts & Advancements
Synthetic base oil technology is fragmenting traditional product hierarchies while regulatory chemistry constraints and fleet digitization reshape how lubricant value is captured and delivered across the Italian commercial vehicle ecosystem.
Polyalphaolefin and ester-based synthetic formulations are fragmenting the conventional mineral oil segment by enabling 100,000-kilometer drain intervals in long-haul trucking applications. Fleet operators with centralized maintenance programs are adopting these fluids at accelerated replacement cycles. The technology is fragmenting historical volume-based revenue models toward performance-contracting structures where suppliers assume utilization risk.
The EU F-Gas Regulation constraints on hydrofluorocarbon refrigerants are mandating compressor lubricant compatibility with HFO-1234yf and CO2 systems in truck and bus climate control. Italian blenders must reformulate polyalkylene glycol and polyolester chemistries to maintain miscibility and thermal stability under transcritical CO2 pressures. Construction vehicle air conditioning retrofits represent the most affected segment, with equipment owners facing system conversion costs that delay lubricant upgrade decisions.
Consolidated procurement through national leasing and rental companies is compressing supplier negotiation cycles and standardizing specification requirements across multi-brand fleets. The independent workshop channel faces margin pressure as these centralized buyers negotiate direct supply agreements with lubricant manufacturers. The Po Valley logistics corridor exhibits the most pronounced concentration, where multinational fleet operators have established preferred supplier frameworks that exclude regional distributors from high-volume accounts.
Italy Commercial Vehicles Lubricants Market Segmentation
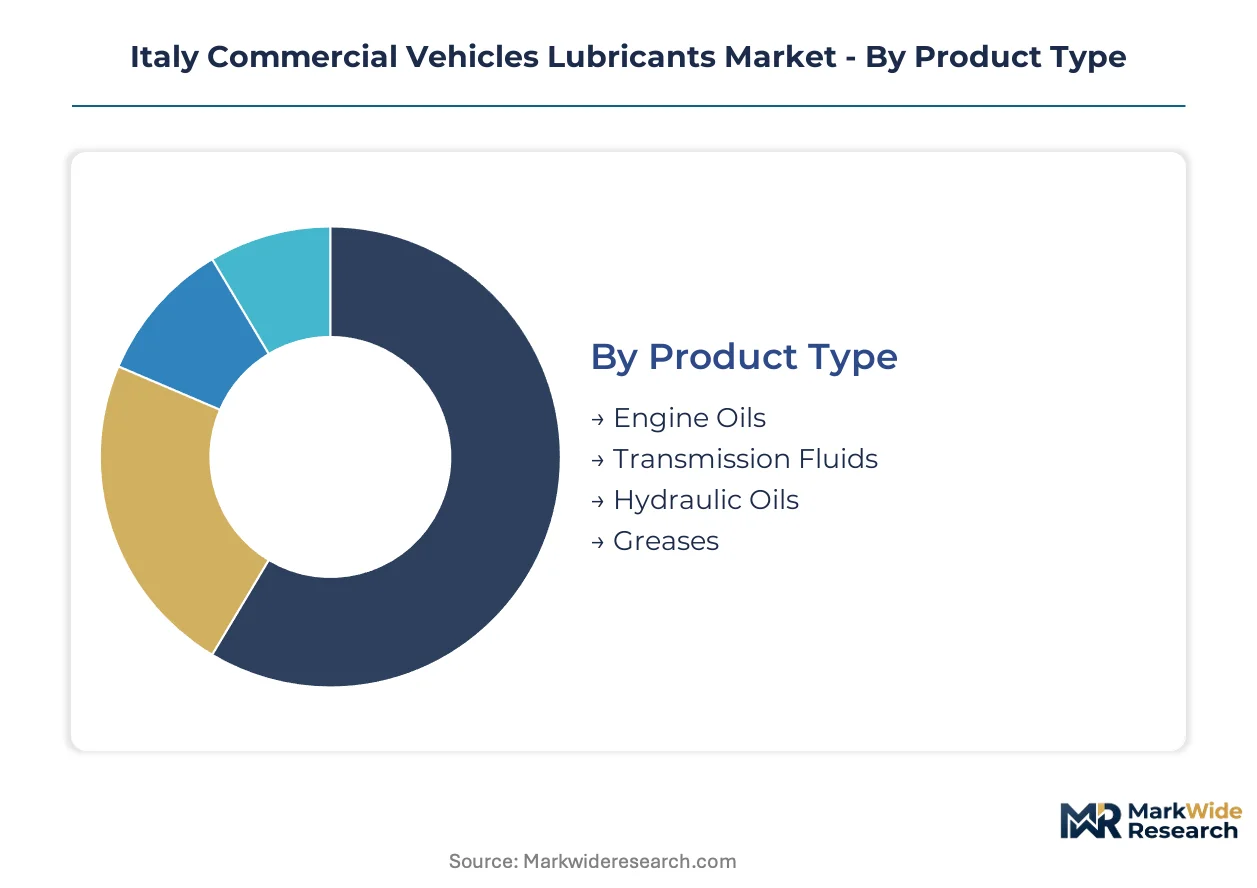
Segmentation in Italy's commercial vehicles lubricants market reveals how margin capture varies dramatically across procurement channels and application intensity. Fleet consolidation and OEM specification complexity are rewiring traditional volume-value relationships across every category.
Product Type:
Engine oils concentrate the highest margin pools through extended-drain formulations and Euro VI certification requirements, while transmission fluids are climbing fastest on drivetrain technology shifts.
- Engine Oils:Formulated petroleum-based and synthetic fluids meeting SAE 10W-40 and 5W-30 grades with total base numbers of 9-14 mg KOH/g for acid neutralization. Northern Italy's Milan-Turin-Bologna logistics corridor drives premium synthetic adoption as fleet operators extend drain intervals under centralized maintenance programs.
- Transmission Fluids:Specialized formulations with enhanced shear stability and thermal management for automated manual transmissions. Heavy-duty truck fleets across the Po Valley are upgrading drivetrain configurations, creating specification-intensive demand that rewards technical formulation partnerships.
- Hydraulic Oils:High-performance fluids targeting construction machinery applications where equipment utilization rates remain elevated. FUCHS maintains specialized positioning here through viscosity index improvers and anti-wear additive packages.
- Greases:Lithium complex and calcium sulfonate thickened lubricants for chassis, wheel bearings, and fifth-wheel applications. Maintenance centers serving agricultural vehicles in Emilia-Romagna represent stable recurring demand.
Engine oils hold installed capacity. Transmission fluids are rotating up the share rankings.
End User:
Procurement centralization is splitting the customer base between volume-contracted national accounts and fragmented owner-operator segments with diverging price-performance tradeoffs.
- Fleet Operators:National leasing and rental companies with consolidated procurement frameworks negotiating direct manufacturer agreements. These buyers standardize specifications across multi-brand fleets, compressing regional distributor margins in the Po Valley corridor.
- Transport Companies:Small and mid-size operators dominating unit volume through independent workshop networks. REACH compliance documentation and technical support requirements favor domestic blenders with established registration portfolios.
- Logistics Providers:Third-party fulfillment operators with telematics-enabled predictive maintenance programs. Oil condition sensor integration creates subscription-based service opportunities for lubricant suppliers embedding in fleet management platforms.
- Maintenance Centers:Independent service providers operating on paper-based or basic ERP systems resisting API connectivity. Legacy inventory management constrains automated replenishment and technical bulletin distribution.
Fleet operators command pricing leverage. Transport companies still move the volume base.
Application:
Equipment utilization intensity and emission regulatory exposure determine formulation premium capture across vehicle categories.
- Heavy-Duty Trucks:Long-haul applications demanding 100,000-kilometer drain intervals through polyalphaolefin and ester-based synthetics. Euro VI powertrain calibration requirements are fragmenting historical mineral oil segments toward performance-contracting structures.
- Buses:Urban transit with frequent stop-start cycles and mobile air conditioning thermal loads. EU F-Gas Regulation mandates on HFO-1234yf and CO2 refrigerant compatibility drive compressor lubricant reformulation investments.
- Construction Machinery:Excavators and mobile cranes operating under severe load cycles with elevated hydraulic oil consumption. Northern Italy's infrastructure project pipeline sustains above-average equipment operating hours.
- Agricultural Vehicles:Seasonal utilization patterns with grease-intensive maintenance protocols. Emilia-Romagna and Lombardy equipment densities support regional distributor networks.
Heavy-duty trucks anchor formulation R&D spending. Buses are gaining specification complexity fastest.
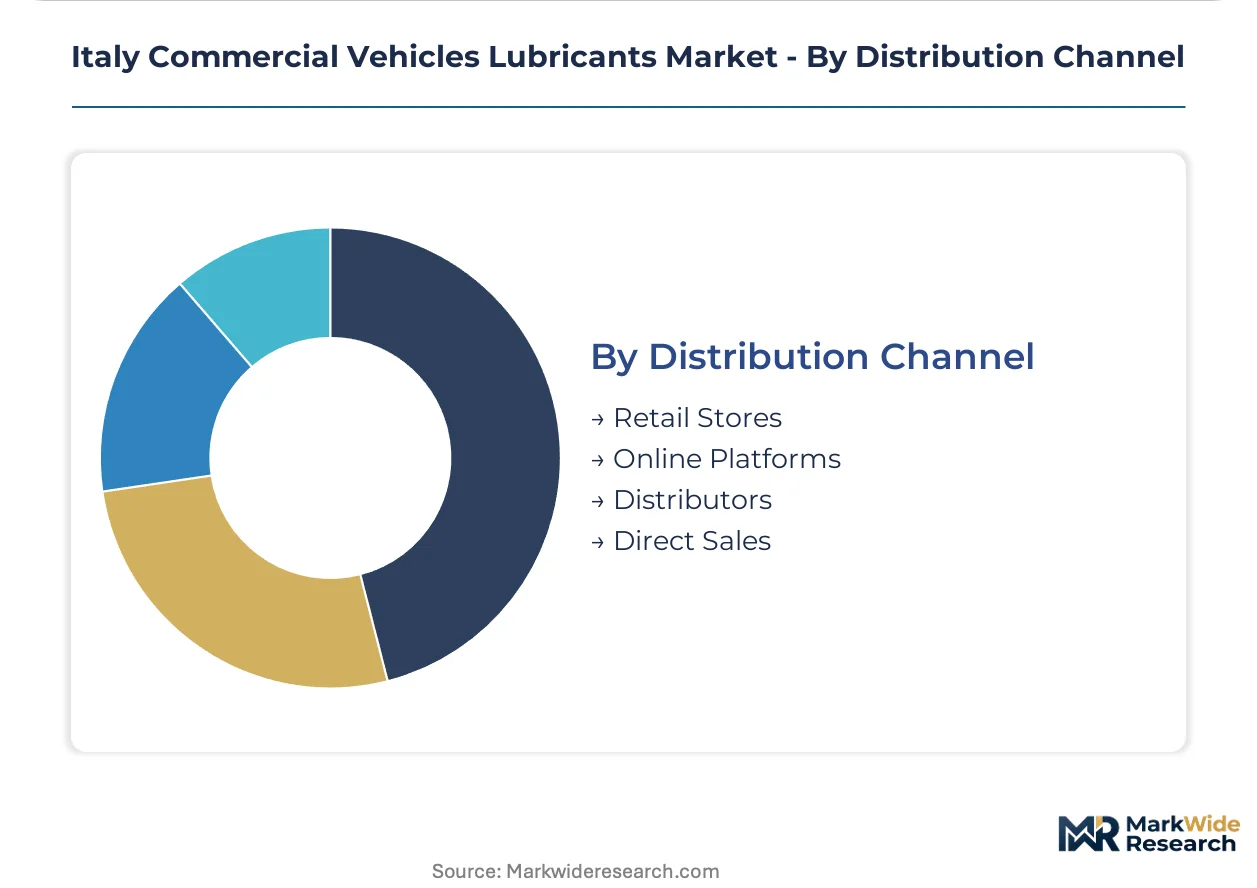
Distribution Channel:
Channel economics reflect inventory velocity, technical service requirements, and customer scale fragmentation across the procurement landscape.
- Distributors:Regional logistics networks with bulk storage and technical field support capabilities. The Po Valley concentration rewards distributors with fleet density and workshop relationship depth.
- Direct Sales:Manufacturer-to-fleet agreements bypassing intermediaries for national accounts with standardized volume commitments. Consolidated procurement through leasing companies accelerates this channel's expansion.
- Retail Stores:Automotive parts outlets serving owner-operators and small transport companies with immediate availability needs. Price transparency pressures margin retention.
- Online Platforms:Emerging procurement channel for standardized specifications with documented technical datasheets. Independent workshops adopt gradually given legacy system constraints.
Distributors retain workshop relationships. Direct sales is climbing the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German lubricant exports flow southward through Alpine corridors to supply Italian fleet operators adapting to Euro VI powertrain standards. This trade pattern shapes competitive positioning across Central European supply chains.
Germany
Automotive OEM specification development drives lubricant chemistry innovation from Stuttgart and Munich research centers. KBA type-approval requirements for commercial vehicle components create certification benchmarks that Italian blenders must match. Bavarian chemical clusters export additive packages through Brenner Pass logistics nodes serving Lombardy distribution networks.
France
TotalEnergies maintains cross-border supply infrastructure feeding Lyon-Turin freight corridors with synthetic base stock formulations. ANSM chemical safety documentation requirements align with REACH protocols, easing regulatory friction for products entering Italian workshops. Auvergne-Rhône-Alpes lubricant blending capacity supports just-in-time replenishment for transalpine transport fleets.
Netherlands
Rotterdam and Antwerp harbor concentration determines Group II/III base oil pricing for Italian formulators dependent on imported feedstocks. Port Authority Rotterdam sustainability mandates accelerate low-carbon shipping options that affect landed cost structures. Randstad chemical logistics hubs coordinate bulk transfers through Adriatic routing alternatives.
Spain
Repsol leverages Iberian refining integration to supply Mediterranean coastal markets competing with Italian domestic production. Spanish fleet electrification pilot programs offer preview scenarios for thermal management fluid demand transitions. Barcelona-Genoa maritime corridors provide alternative supply paths bypassing Alpine congestion.
Switzerland
Swissmedic chemical purity standards influence premium lubricant specifications for cross-border pharmaceutical logistics fleets operating temperature-controlled trailers. Alpine tunnel maintenance contracts sustain construction machinery lubricant demand from Ticino-based equipment lessors. Swiss franc pricing stability attracts hedging activity from Italian procurement managers.
Italy Commercial Vehicles Lubricants Market Competitive Landscape
Player mix skews toward integrated petroleum majors with captive refining networks and specialized chemical formulators serving niche equipment segments. Market structure concentrates around three strategic tiers: multinational energy corporations with downstream lubricant divisions, mid-size European blenders with regional distribution density, and focused hydraulic fluid specialists targeting construction applications. Competitive dynamics center on OEM specification certification races and direct fleet procurement bypass arrangements that compress distributor margins.
Among Italy-based integrated operators, Eni SpA anchors the domestic supply security position through Po Valley refining infrastructure. Royal Dutch Shell Plc and BP PLC (Castrol) occupy multinational formulation leadership roles calibrated for Euro VI powertrain complexity. FUCHS exemplifies the specialized hydraulic oil archetype with construction machinery technical positioning. These three represent distinct competitive vectors: captive feedstock control, premium synthetic branding, and application-specific performance engineering.
| Leading Market Players |
|---|
| Eni SpA |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| PETRONAS Lubricants International |
| Q8Oils |
| ExxonMobil Corporation |
| FUCHS |
| TotalEnergies |
| Repsol |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp base oil cluster capacity utilization above regional averages compresses Italian blender margins while anchoring price floors for Group II/III feedstocks. Fleet procurement consolidation across the Po Valley amplifies volume-discount leverage, forcing mid-tier suppliers to absorb freight volatility or surrender share to integrated majors with captive refining networks.
Pricing Analysis
Euro VI synthetic formulations command 40-60% premiums over mineral-based predecessors, while next-generation thermal management fluids for electrified powertrains remain pre-commercial with undetermined value capture. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral tiers stratifies by drain interval certification and OEM approval status. Cost compression in the economy tier intensifies because owner-operators prioritize immediate unit cost over lifecycle value. Fleet operators with centralized maintenance programs exhibit lowest price sensitivity, while independent transport companies in Southern Italy demonstrate highest elasticity.
Supply Chain Analysis
Adriatic port congestion and container availability constraints on Rotterdam-Genoa lanes elevate inbound logistics costs for Italian blenders lacking Alpine pipeline access. Feedstock supply concentrates in the Netherlands, Belgium, and Germany for Group II/III base stocks, with Italian formulators drawing from these North Sea clusters. Raw material dependencies span hydrocracked base oils, polyalphaolefin synthetics, and friction modifier additive packages. Single-source vulnerability runs through Rotterdam harbor concentration for Group III+ synthetic feedstocks. Distribution runs through regional bulk terminals serving independent workshop networks, with direct-to-fleet agreements bypassing intermediaries for national accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists capable of Euro VI certification navigation represent the scarcest capability layer, with OEM validation timelines extending 18-24 months and locking competitors into specification hierarchies. This talent bottleneck constrains R&D throughput for mid-size blenders while rewarding integrated majors with established technical dossiers.
For Market Incumbents: Compound specification certification advantages by accelerating Iveco, MAN, and Volvo powertrain approval pipelines before regulatory thresholds tighten further. Prioritize backward integration into additive package blending to reduce dependency on Bavarian chemical cluster imports. Channel control through telematics-enabled predictive maintenance partnerships defends against direct-to-fleet procurement erosion. For New Entrants and Emerging Players: Anchor in Southern Italy logistics corridor development at Gioia Tauro and Bari, where port expansion and Adriatic freight routing investments redistribute commercial vehicle density away from saturated Po Valley incumbents. Target construction machinery hydraulic oil segments where FUCHS positioning leaves mid-tier price-performance gaps. Pursue EU F-Gas Regulation compressor lubricant partnerships with HVAC system suppliers as a technical credibility entry point. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated lubricant suppliers embedding in fleet management platforms through oil condition sensor subscriptions. Long-term viability hinges on thermal management fluid portfolios positioned for electrification transitions. Acquisition target archetype: mid-size blenders with REACH registration portfolios and Southern Italy distribution density. Watch battery-electric heavy-duty truck pilot program scale as the inflection signal for engine oil demand compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Specification Certification Investment | Euro VI powertrain approvals from Iveco and MAN lock competitors into 18-24 month validation cycles. |
| Backward Integration into Additive Blending | In-house friction modifier production reduces dependency on Brenner Pass logistics nodes serving Lombardy. |
| Telematics Platform Partnership | Oil condition sensor integration creates subscription revenue streams with fleet management software providers. |
| Southern Distribution Network Expansion | Gioia Tauro port capacity additions enable Adriatic routing alternatives bypassing Alpine congestion. |
| Thermal Management Fluid R&D | Battery-electric commercial vehicle pilot programs create first-mover positioning for next-generation coolants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed petroleum majors, and additive industry technical publications. Primary interviews engaged lubricant formulation chemists, fleet procurement directors at national leasing companies, independent workshop operators across Emilia-Romagna and Lombardy, and distribution channel managers serving the Po Valley corridor. Secondary validation drew from REACH registration databases, EU F-Gas Regulation implementation bulletins, and OEM powertrain specification sheets. Bottom-up volume modeling triangulated against top-down value estimates from industry association aggregates.
Segmentation dimensions modeled include product type, end-user procurement structure, vehicle application intensity, and distribution channel configuration across the projection horizon. CAGRs derived from regression analysis of historical volume trends adjusted for fleet electrification scenario weightings. Forecast inputs incorporated base oil price indices, commercial vehicle registration trajectories, and regulatory compliance cost pass-through assumptions.
Underlying assumptions cover stable EU Green Deal implementation timelines and gradual fleet electrification penetration, with deviation risk concentrated in battery-electric heavy-duty truck commercialization acceleration or synthetic feedstock supply disruptions from North Sea refining clusters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Lube Skid Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Drilling Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Canada Lubricants Market