
 India Lubricants Market | 2026-2036
India Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
India Lubricants Market Foresight
Multi-source procurement among fleet operators and industrial buyers is rebalancing supplier relationships across the India lubricants sector. Indian Oil Corporation Limited leverages its nationwide fuel-station network to secure last-mile distribution dominance in semi-urban and rural catchments. Castrol India sustains premium positioning through sustained investment in synthetic formulations for passenger vehicles. Gulf Oil Lubricants India Limited specializes in high-performance industrial grades, anchoring its presence in manufacturing-heavy western states.
Lubricants are formulated mixtures of base oils and additive packages engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems operating across temperature ranges from minus forty to above two hundred degrees Celsius. Their primary commercial purpose spans engine protection in automotive powertrains, hydraulic system efficiency in industrial machinery, and corrosion resistance in marine propulsion. Mineral lubricants occupy the largest volume share due to entrenched cost sensitivity among price-driven fleet operators and agricultural equipment users. Synthetic grades command disproportionate margin pools as automotive OEMs specify longer drain intervals and tighter viscosity tolerances. The industrial application segment is accelerating fastest, propelled by capacity expansion in steel, cement, and textile processing plants.
BIS certification requirements and Automotive Research Association of India (ARAI) test protocols determine product eligibility for domestic sale, while state pollution control boards enforce waste-oil disposal rules that shape aftermarket collection economics. The central government's PLI scheme for automotive components indirectly stimulates demand for higher-specification lubricants through advanced engine manufacturing incentives. Stakeholders must monitor evolving BIS standards for biodegradable base stocks and track state-level enforcement of extended producer responsibility frameworks for used lubricant recovery.
Market Dynamics
The India lubricants sector is rebalancing around BIS certification mandates that are forcing wholesale reformulation of base stock portfolios and additive packages across domestic blenders.
Growth Catalysts
- Automotive Research Association of India test protocols:Tighter emission norms under BS-VI Stage II are compelling lubricant upgrades in commercial vehicle powertrains, creating specification-driven replacement cycles.
- Steel and cement capacity expansion:Industrial lubricant offtake is accelerating in western state manufacturing corridors as process automation intensifies hydraulic and gear oil consumption.
- Maharashtra automotive clusters:Concentrated OEM assembly operations generate captive demand for factory-fill and service-fill lubricants with extended drain interval specifications.
Market Restraints
- Group II/III base oil import dependency:Domestic refiners lack sufficient hydrocracking capacity, exposing blenders to freight and currency volatility from Middle Eastern and Southeast Asian supply sources.
- Price-sensitive fleet operator procurement:Road freight contractors prioritize volume discounts over performance specifications, compressing margin pools for premium synthetic grades.
- Mineral oil substitution inertia:Agricultural equipment owners resist drain interval extensions despite synthetic performance benefits, locking in low-margin volume segments.
Strategic Opportunities
- Gujarat industrial corridor deepening:Petrochemical hub infrastructure supports backward integration into additive manufacturing and base oil refining for western market capture.
- PLI scheme for automotive components:Advanced engine manufacturing incentives are stimulating demand for higher-specification lubricants in precision powertrain applications.
- Extended producer responsibility frameworks:State pollution control board enforcement of waste-oil collection mandates is creating aftermarket service bundling opportunities.
Industry Challenges
- Biodegradable base stock certification timelines:Evolving BIS standards for environmentally acceptable lubricants require multi-year reformulation and testing investments without guaranteed commercial uptake.
- Multi-grade viscosity blending precision:Synthetic formulation capabilities demand capital-intensive in-house testing infrastructure that mid-tier blenders struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lubricants Market |
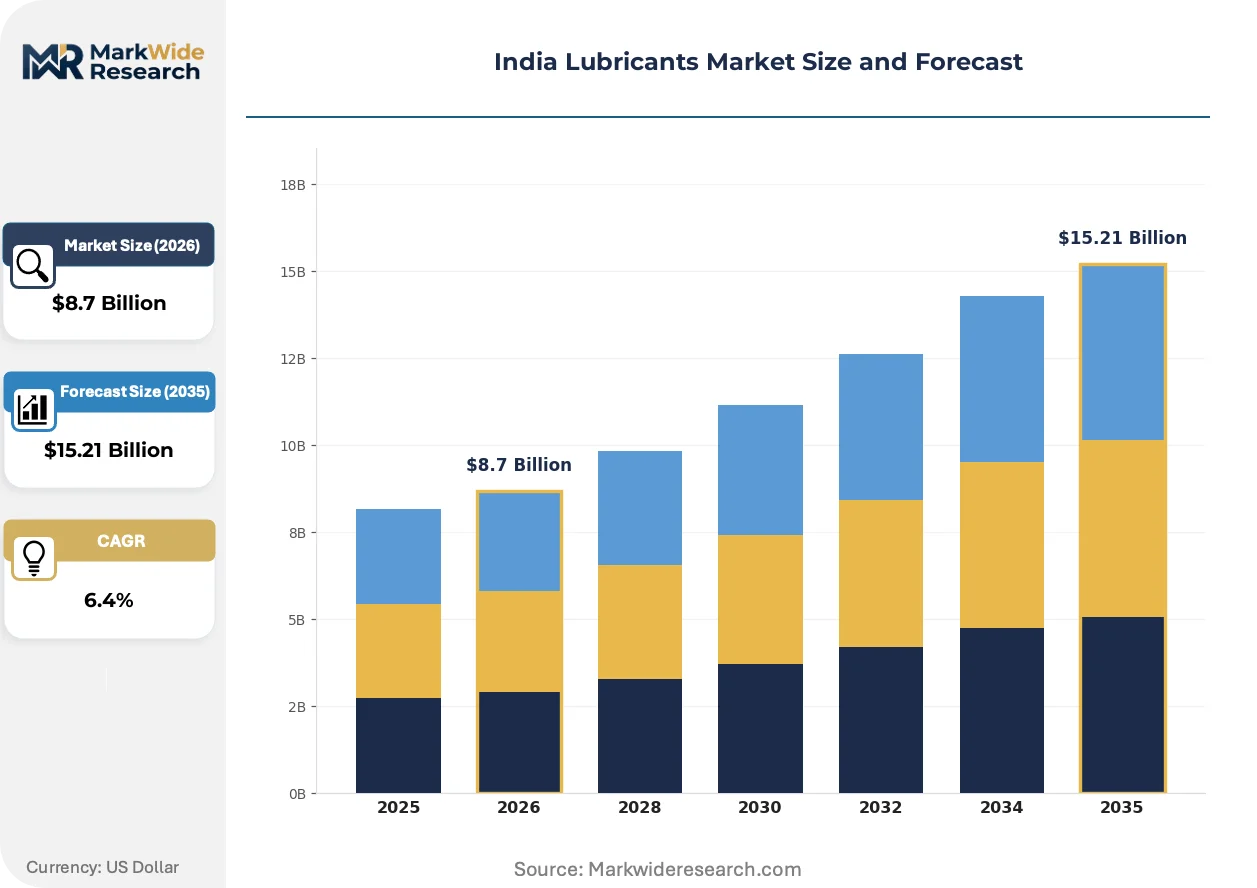
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Biodegradable, Semi-Synthetic Application: Automotive, Industrial, Marine, Aviation Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales End User: Manufacturing, Transportation, Automotive Services, Agriculture |
| Companies Covered | BP p.l.c., TotalEnergies, Indian Oil Corporation Limited, Gulf Oil Lubricants India Limited, Exxon Mobil Corporation, Bharat Petroleum Corporation Limited, Castrol India, Hindustan Petroleum Corporation Limited, Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lubricants Market Shifts & Advancements
Reformulation priorities are pivoting toward thermal stability and lower viscosity grades as powertrain electrification and emission tightening reshape lubricant performance requirements across automotive and industrial segments.
Polyalphaolefin synthetic base stocks are absorbing the specification upgrade burden in passenger vehicle engine oils, enabling thinner film strength at elevated operating temperatures. Maruti Suzuki and Hyundai Motor India are specifying 0W-16 and 0W-20 grades for new compact car platforms, forcing domestic blenders to secure Group III supply commitments. This chemistry shift is absorbing the technical resources of formulators previously dedicated to mineral oil optimization.
BIS revised automotive norms are tightening lubricant quality specifications through mandatory bench and engine test sequences for factory-fill approval. The Bureau of Indian Standards certification process now requires documented additive package performance against oxidation and deposit control parameters. Passenger vehicle OEMs are responding by qualifying fewer approved suppliers per specification tier, consolidating procurement leverage.
Fleet operators are consolidating lubricant purchasing through direct distributor relationships rather than retail channel procurement, compressing intermediary margins. Large road freight contractors in Tamil Nadu and Karnataka are negotiating annual volume contracts with Castrol India and Gulf Oil Lubricants for bulk delivery to centralized maintenance depots. This channel migration is most visible in the southern state logistics corridors where organized fleet penetration exceeds national averages.
India Lubricants Market Segmentation
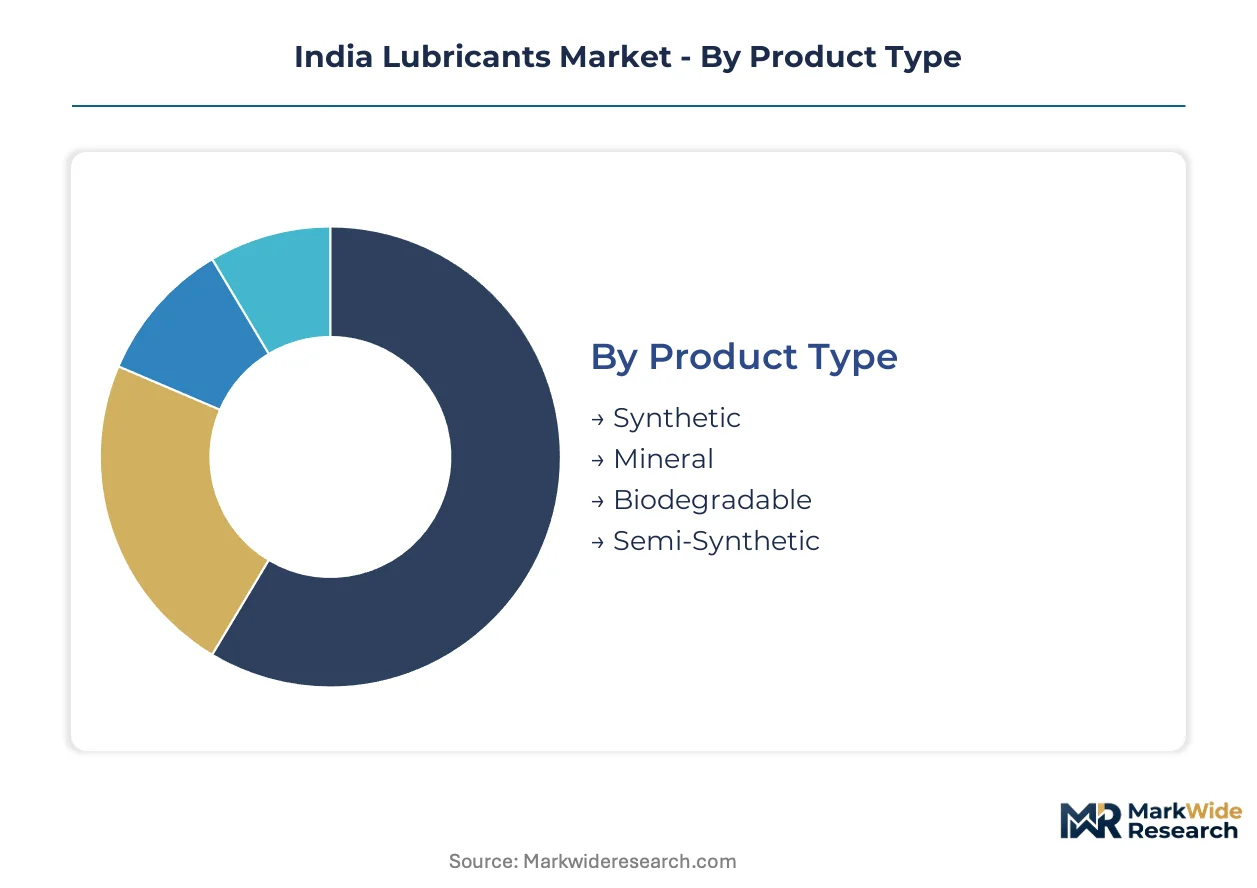
Segmentation in India's lubricants sector reveals how price sensitivity, regulatory pressure, and supply chain configuration split demand across incompatible buyer profiles. Understanding these fault lines exposes where reformulation investments convert to margin and where volume competes on cost alone.
Product Type:
Cost tier separates buyers most sharply in this category, with fleet operators, OEMs, and industrial users occupying distinct willingness-to-pay bands.
- Mineral:Refined petroleum base stocks dominate volume through entrenched cost advantages. Agricultural equipment owners in Punjab and Haryana prioritize per-litre pricing over drain interval extension, locking in low-margin procurement patterns despite synthetic alternatives.
- Synthetic:Polyalphaolefin and Group III formulations enable 0W-16 and 0W-20 viscosity grades for BS-VI Stage II powertrains. Maruti Suzuki and Hyundai Motor India factory-fill specifications are concentrating demand among approved blenders with ARAI certification.
- Semi-Synthetic:Blended formulations bridge price-performance gaps for mid-market passenger vehicle owners.
- Biodegradable:Ester-based stocks face BIS certification timelines and uncertain commercial uptake despite environmental pressure.
Mineral lubricants lead volumes today; synthetic grades are gaining share fastest.
Application:
Application splits the market between mobility-linked replacement cycles and stationary asset maintenance economics.
- Automotive:Engine oils, transmission fluids, and coolants serve passenger vehicles, commercial fleets, and two-wheelers. Maharashtra automotive clusters generate captive factory-fill demand with extended drain specifications.
- Industrial:Hydraulic fluids, gear oils, and compressor lubricants support steel, cement, and textile processing. Gujarat manufacturing corridors are accelerating offtake as process automation intensifies.
- Marine:Stern tube oils and cylinder lubricants serve coastal shipping and inland waterway fleets.
- Aviation:Jet engine oils and hydraulic fluids follow DGCA certification paths with concentrated airline procurement.
Automotive applications dominate revenue; industrial lubricants are expanding most quickly.
Distribution Channel:
Channel selection tracks fleet size and procurement sophistication, with large buyers bypassing retail entirely.
- Wholesale:Bulk contracts to fleet operators and industrial accounts concentrate volume. Tamil Nadu and Karnataka logistics contractors negotiate annual agreements with direct distributor relationships.
- Retail:Fuel station networks and automotive workshops serve fragmented passenger vehicle and small fleet demand.
- Direct Sales:OEM factory-fill and large industrial accounts bypass intermediaries for technical service bundling.
- E-commerce:Digital platforms capture DIY maintenance and rural penetration where physical distribution is thin.
Wholesale channels capture the largest volume blocks; direct sales are climbing the fastest.
End User:
End-user category captures how asset ownership structure shapes lubricant specification authority and contract terms.
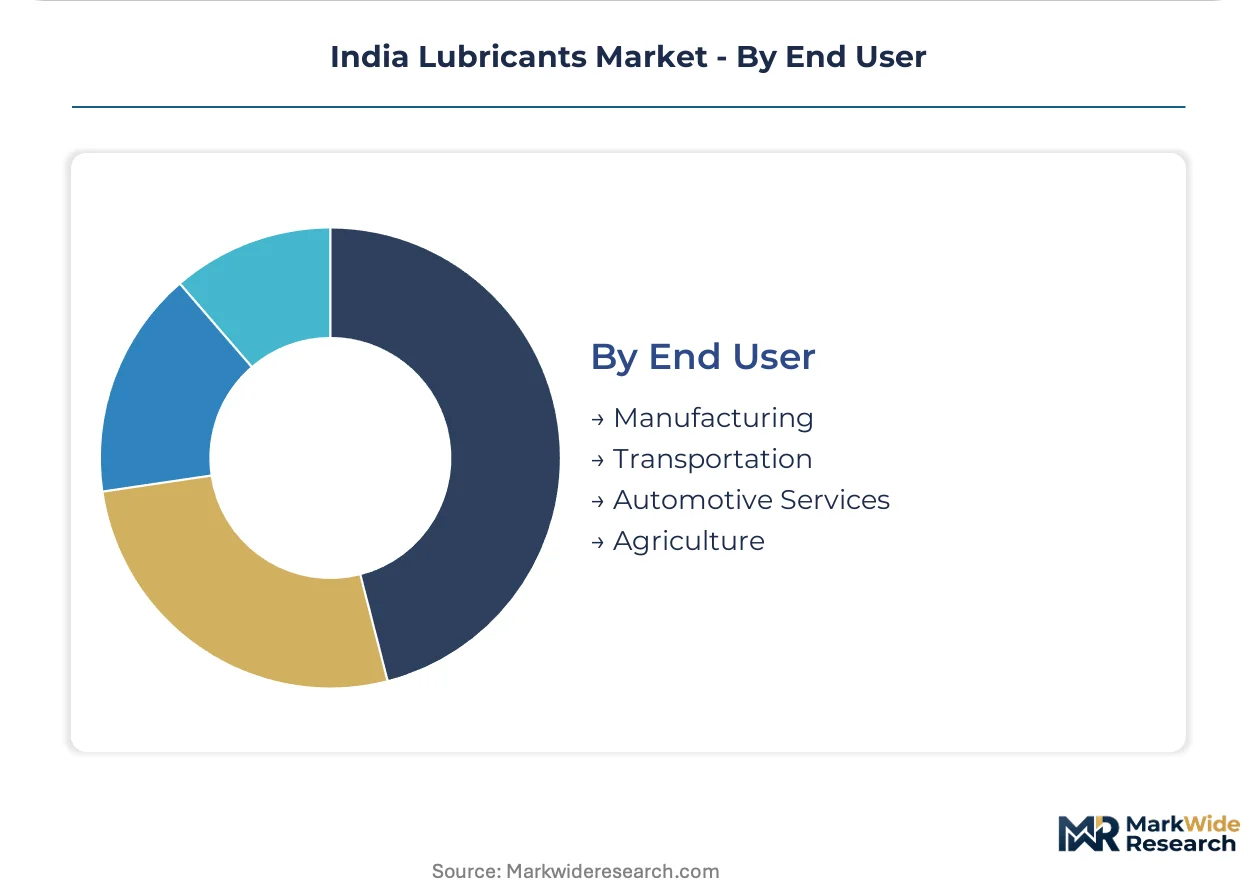
- Transportation:Road freight contractors and logistics operators prioritize volume discounts and centralized depot delivery. Organized fleet penetration in southern states exceeds national averages.
- Manufacturing:Steel, cement, and textile plants specify hydraulic and gear oils with process automation requirements. Western state industrial corridors generate concentrated offtake.
- Automotive Services:Workshops and service centers balance OEM-approved specifications against customer price sensitivity.
- Agriculture:Tractor and equipment owners resist specification upgrades despite synthetic performance benefits.
Transportation end users lead volume consumption; manufacturing buyers are driving steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's automotive manufacturing corridor anchors India's lubricant demand geography, with concentrated OEM assembly operations generating factory-fill specifications that cascade through service networks nationwide.
Maharashtra
Maruti Suzuki and Hyundai Motor India assembly plants in Pune and Nashik districts drive captive demand for 0W-16 and 0W-20 synthetic grades. BIS certification mandates under revised automotive norms require documented additive package performance for factory-fill approval. Mumbai-Pune industrial belt blenders are consolidating procurement leverage as OEMs qualify fewer approved suppliers per specification tier.
Gujarat
Petrochemical hub infrastructure in Vadodara and Jamnagar supports backward integration opportunities into additive manufacturing and base oil refining. State pollution control board enforcement of waste-oil disposal rules shapes aftermarket collection economics in Surat and Ahmedabad manufacturing zones. Steel and cement capacity expansion across the Delhi-Mumbai Industrial Corridor accelerates hydraulic and gear oil consumption.
Karnataka
Organized road freight contractors in Bengaluru and Mangaluru logistics corridors negotiate annual volume contracts for bulk lubricant delivery to centralized maintenance depots. PLI scheme incentives for automotive components stimulate demand for higher-specification lubricants in precision powertrain applications. Tamil Nadu border region fleet penetration exceeds national averages, compressing intermediary margins through direct distributor relationships.
Tamil Nadu
Commercial vehicle activity intensifies around Chennai and Coimbatore industrial zones, with fleet operators consolidating purchasing through direct channels rather than retail procurement. Automotive Research Association of India test protocols under BS-VI Stage II compel lubricant upgrades in commercial vehicle powertrains. Sriperumbudur automotive cluster generates specification-driven replacement cycles for extended drain interval products.
Haryana
Agricultural equipment owners in Punjab-adjacent districts prioritize per-litre pricing over drain interval extension, locking in low-margin mineral oil procurement patterns. Price-sensitive fleet operator procurement across the Delhi-NCR freight corridor compresses margin pools for premium synthetic grades. Gurugram industrial belt maintains residual demand for mid-market semi-synthetic formulations bridging cost-performance gaps.
India Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulations and biodegradable base stocks to differentiate positioning. The sector exhibits moderate consolidation around integrated energy majors with captive distribution infrastructure, while mid-tier blenders face capital constraints for synthetic formulation capabilities. Three archetypes dominate: state-owned enterprises leveraging fuel-station networks, international majors anchoring premium synthetic positioning, and regional specialists concentrating on industrial grades. Competitive moves center on direct sales channel expansion for fleet accounts and backward integration into additive manufacturing.
Among international energy majors, BP p.l.c. and Shell plc exemplify the premium-tier archetype through sustained synthetic formulation investment. Indian Oil Corporation Limited occupies a distinctive position as a state-owned enterprise with nationwide last-mile distribution dominance. Gulf Oil Lubricants India Limited represents the regional specialist model, anchoring presence in manufacturing-heavy western states through industrial-grade concentration.
| Leading Market Players |
|---|
| BP p.l.c. |
| TotalEnergies |
| Indian Oil Corporation Limited |
| Gulf Oil Lubricants India Limited |
| Exxon Mobil Corporation |
| Bharat Petroleum Corporation Limited |
| Castrol India |
| Hindustan Petroleum Corporation Limited |
| Shell plc |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ARAI-approved synthetic formulations and commodity mineral blends manifests in divergent margin structures and supply chain configurations across India's lubricants sector. BIS-mandated test protocols for BS-VI Stage II compliance concentrate premium pricing power among blenders with documented additive package performance, while price-sensitive fleet operators in road freight channels lock in volume discounts that compress intermediary margins.
Pricing Analysis
Base oil import costs from Middle Eastern and Southeast Asian refiners pass through directly into blender pricing schedules, with Group II/III hydrocracked stocks commanding premiums over domestic mineral base supplies. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels tracks certification tier and drain interval specification, with Maruti Suzuki and Hyundai Motor India factory-fill approvals serving as the primary price differentiation driver. Pricing pressure stems from currency volatility exposing blenders without hedging capabilities, while agricultural equipment owners in Punjab and Haryana exhibit the highest price sensitivity, resisting specification upgrades despite synthetic performance benefits.
Supply Chain Analysis
Extended producer responsibility frameworks for waste-oil collection are creating reverse-logistics infrastructure requirements that reshape aftermarket service economics across state pollution control board jurisdictions. Domestic blending capacity concentrates in Maharashtra and Gujarat, with raw material dependencies on imported Group II/III base oils, polyalphaolefin synthetic stocks, and additive packages from Singapore and South Korea. Single-source vulnerability in hydrocracked base oil supply exposes mid-tier blenders to freight cost spikes, while distribution runs through Indian Oil Corporation's fuel-station network for rural catchments and direct distributor relationships for organized fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India lubricants market functions as a regulatory compounder where BIS certification mandates under revised automotive norms continuously upgrade specification requirements and consolidate procurement leverage among approved suppliers.
For Market Incumbents: Deepen backward integration into additive manufacturing at Gujarat petrochemical hubs to secure supply continuity against Middle Eastern freight volatility. Expand ARAI certification coverage for 0W-16 and 0W-20 grades to defend factory-fill positions as Maruti Suzuki and Hyundai Motor India qualify fewer approved suppliers per specification tier. For New Entrants and Emerging Players: Fleet operators in Tamil Nadu and Karnataka logistics corridors represent the most penetrable channel target, with annual volume contract structures already displacing retail procurement. Pursue biodegradable base stock formulations ahead of evolving BIS environmental standards to establish differentiation before certification timelines solidify competitive positions. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier blenders lack capital for synthetic formulation testing infrastructure and Group III supply commitments. Target regional specialists with established western state industrial presence and documented waste-oil collection licenses under state pollution control board frameworks. Monitor BIS timelines for biodegradable lubricant standards as the signal for specification-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Gujarat petrochemical hub infrastructure enables captive supply of performance chemicals for BS-VI Stage II formulations. |
| ARAI Certification Expansion | Documented additive package performance against oxidation parameters secures factory-fill approvals from passenger vehicle OEMs. |
| Direct Fleet Channel Development | Annual volume contracts with Tamil Nadu and Karnataka logistics contractors bypass retail intermediaries and compress competitor access. |
| Waste-Oil Collection Infrastructure | State pollution control board extended producer responsibility mandates create aftermarket service bundling and recurring revenue streams. |
| Biodegradable Base Stock Reformulation | Ester-based stocks aligned with evolving BIS environmental standards preempt regulatory displacement of mineral lubricant volumes. |
Research Methodology
Multiple input streams — primary interviews with lubricant blender technical directors, fleet procurement managers, and ARAI certification officials, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at western state manufacturing facilities, aftermarket service heads at organized fleet operators, and BIS standard-setting committee participants. Secondary sources encompassed customs trade data on base oil imports, Bureau of Indian Standards publication records, and Automotive Research Association of India test protocol documentation.
Cross-referencing historical volume trajectories against panel-derived specification upgrade timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, application category, distribution channel structure, and regional industrial cluster concentration. CAGRs were derived from spline-interpolated annual growth paths adjusted for PLI scheme incentive impacts and BS-VI Stage II implementation phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS biodegradable standard finalization and Group II/III import tariff adjustments. Practitioners should monitor state pollution control board enforcement intensity and OEM factory-fill specification tier consolidation for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Chile Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
Industrial Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Global Finished Lubricant Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Europe Marine Lubricants Market