
 Yarn Lubricant Market | 2026-2036
Yarn Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Yarn Lubricant Market Intelligence
The unbundling of bulk lubricant supply into application-specific, pre-dosed formulations is rebalancing buyer choice toward performance and waste reduction. Klüber Lubrication specializes in high-performance synthetic products for demanding textile applications. Zschimmer & Schwarz competes with a broad portfolio covering multiple stages of textile processing. TotalEnergies leverages its significant scale in base oil production to offer cost-effective solutions for high-volume segments.
Yarn lubricants are chemical agents applied to fibers and yarns to reduce the coefficient of friction during high-speed processing. These formulations provide critical antistatic properties and prevent breakage in spinning, weaving, and knitting. While oil-based and emulsion-based products represent the core market volume, silicone-based lubricants are gaining share in technical applications. Formulations for air-jet spinning and draw texturing demand higher performance standards compared to traditional ring spinning.
Regulatory frameworks including the EU's REACH, the US EPA's oversight of chemical substances, and China's GB standards define market access. These rules govern the use of certain chemicals, mandate biodegradability testing, and set limits for skin-contact safety. The central strategic decision for formulators is whether to invest in novel bio-based chemistries or optimize existing synthetic platforms for new performance benchmarks.
Market Dynamics
The central dynamic shaping the yarn lubricant market is the strategic tension between the need for higher-performance formulations for advanced textile machinery and the escalating regulatory pressure for biodegradable, skin-safe chemistries, particularly under frameworks like the EU's REACH.
Growth Catalysts
- Advanced Processing Technologies:The adoption of high-speed equipment such as air-jet spinning and draw texturing machinery necessitates lubricants with superior friction reduction and antistatic properties to prevent yarn breakage and ensure consistent quality.
- Technical Fabricators Segment:Expansion in the production of technical textiles for automotive, medical, and industrial applications creates demand for specialized, high-performance lubricants that meet stringent performance and safety criteria.
- Manufacturing Consolidation:The concentration of textile production in hubs like Vietnam and Bangladesh creates dense ecosystems of demand, allowing lubricant suppliers to achieve economies of scale in distribution and technical support.
Market Restraints
- Raw Material Volatility:The pricing of conventional oil-based and synthetic lubricants is directly tied to fluctuations in crude oil and base oil markets, creating margin pressure for formulators and cost uncertainty for textile mills.
- Regulatory Compliance Burden:The complexity of meeting disparate international standards, such as the EU's REACH and China's GB standards, increases R&D costs and lengthens time-to-market for new formulations.
- Substitution by Lower-Tier Products:In high-volume, less demanding segments like basic apparel, some manufacturers opt for lower-cost, commodity-grade finishing oils, limiting the addressable market for premium, specialized yarn lubricants.
Strategic Opportunities
- Bio-Based Formulations:Investing in the development and certification of biodegradable lubricants derived from plant-based esters or other renewable feedstocks offers a path to capture value from sustainability mandates and brand-owner requirements.
- Application-Specific Dosing:The development of pre-dosed, single-use, or application-specific packaging moves the value proposition from bulk chemical supply to process optimization, waste reduction, and performance assurance.
- Silicone-Based Lubricants for Technical Textiles:Expanding offerings of silicone-based lubricants can capture share in high-growth technical applications, such as medical textiles and high-temperature industrial fabrics, where their thermal stability is critical.
Industry Challenges
- Formulation Expertise Scarcity:A skills gap exists for chemical engineers and formulators who possess dual expertise in both high-performance synthetic chemistry and the emerging field of bio-based lubricant science.
- Biodegradability Certification:Navigating the costly and time-consuming testing protocols required to certify products as readily biodegradable under various international standards creates a significant barrier to entry for new bio-based formulations.
- Feedstock Supply Chain Development:Establishing stable, cost-effective supply chains for novel bio-based raw materials presents a logistical challenge compared to the mature and scaled infrastructure for petrochemical feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yarn Lubricant Market |
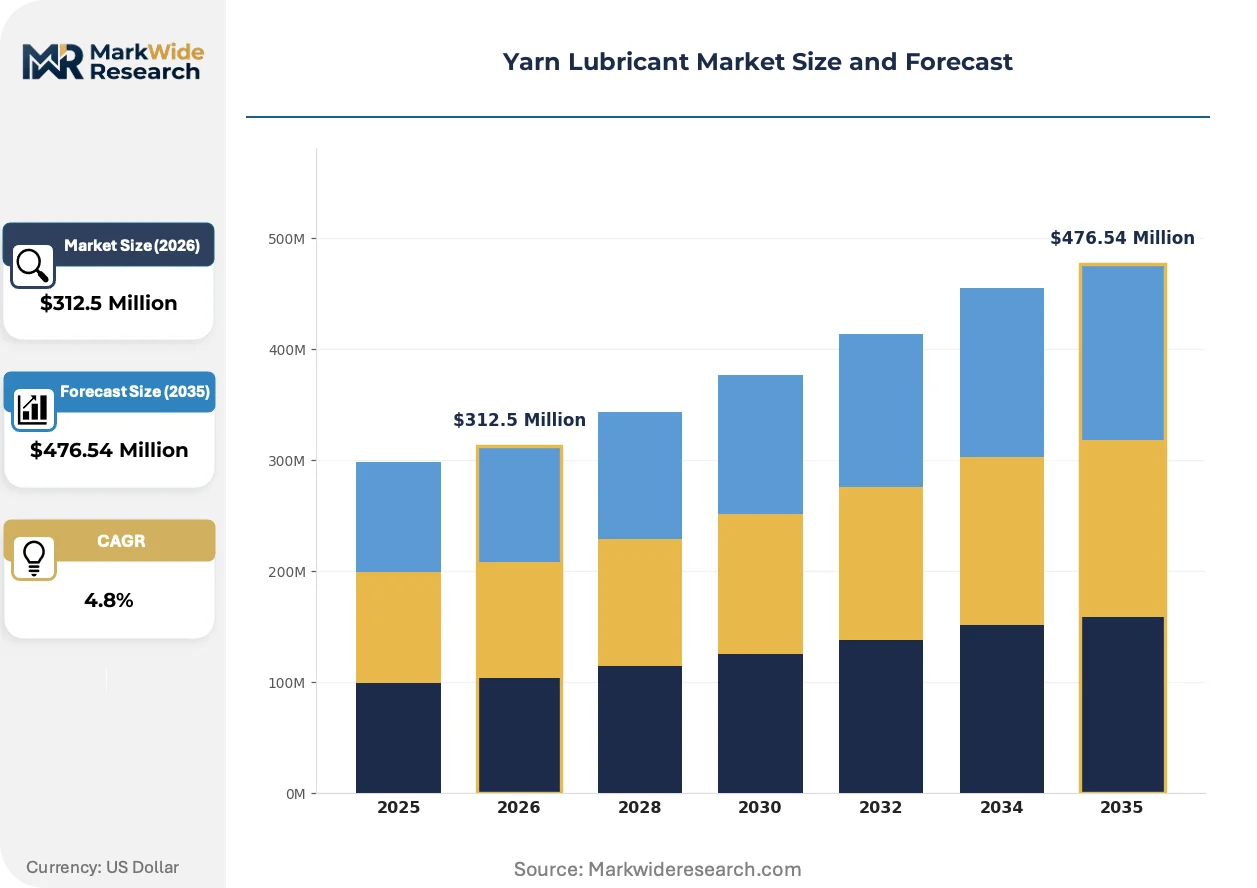
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Based, Emulsion-Based, Silicone-Based, Water-Based, Fatty Acid-Based Application: Ring Spinning, Open-End Spinning, Air-Jet Spinning, Draw Texturing End User Industry: Textile Mills, Apparel Manufacturers, Home Textile Producers, Technical Fabricators Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesale Market |
| Companies Covered | SIAM PRO DYECHEM GROUP, Klüber Lubrication, Achitex Minerva S.p.A., Zschimmer & Schwarz, TAKEMOTO OIL & FAT CO., LTD., Clearco Products Co., Inc., Giovanni Bozzetto S.p.A., TotalEnergies, Rudolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yarn Lubricant Market Strategic Shifts & Innovations
Performance demands from next-generation textile machinery are converging with sustainability mandates from regulators and consumers. This convergence is compelling a fundamental shift in lubricant chemistry, moving beyond simple friction reduction to encompass biodegradability, skin safety, and process efficiency.
Smart dosing systems integrated directly into textile processing machinery represent a key technological evolution. Major textile mills are adopting these systems to ensure precise and consistent lubricant application, reducing overuse and improving yarn quality. This technology is automating lubricant delivery, minimizing manual error and enabling dynamic adjustments based on real-time sensor data from spinning or knitting machines.
The European Union's REACH regulation imposes stringent controls on chemical substances, directly impacting lubricant formulations sold within the bloc. This forces manufacturers to systematically replace restricted chemicals, such as certain ethoxylates, with compliant, safer alternatives without degrading performance. Formulators with significant European exposure are prioritizing investment in green chemistry to maintain market access and build a competitive advantage.
A notable behavioral shift is occurring as textile producers move from purchasing lubricants in bulk drums to preferring unit-dosed or application-specific formats. This change is driven by a focus on process control and waste reduction, replacing manual mixing with precise, error-proof application methods. This trend is most pronounced in the advanced textile manufacturing centers of Vietnam and Bangladesh, where quality consistency is paramount.
Yarn Lubricant Market Segmentation
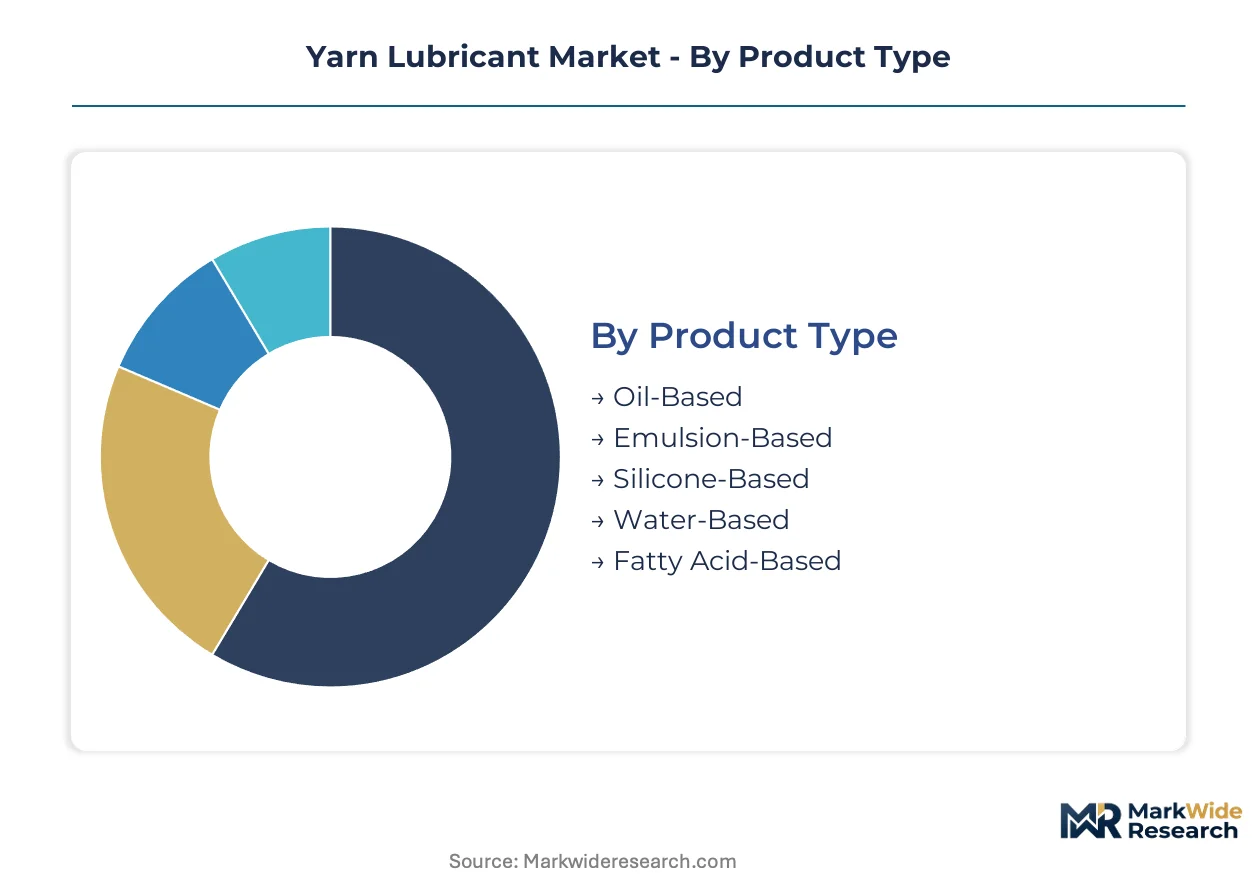
Understanding the varied requirements across different product types, applications, and end-user industries is critical for yarn lubricant manufacturers. This segmentation provides a granular view of demand drivers and performance benchmarks, enabling targeted product development and market penetration strategies within the textile sector.
Product Type:
The technical specifications of yarn lubricants delineate distinct market segments based on chemical composition and performance characteristics.
- Oil-Based:These lubricants, often derived from mineral oils or synthetic esters, provide fundamental friction reduction and antistatic properties for general textile processing. Demand concentrates in high-volume apparel manufacturing in Bangladesh, driven by cost-effectiveness for traditional spinning methods.
- Silicone-Based:Silicone-based lubricants offer superior thermal stability and a low coefficient of friction, making them suitable for demanding technical applications. Their use is expanding in medical textiles in Germany, where high-performance and inertness are critical requirements.
- Emulsion-Based:These products are water-dispersible formulations, offering good lubrication and easy removal during subsequent textile finishing processes.
- Water-Based:Water-based lubricants provide environmentally friendlier options with easy wash-off properties, particularly for sensitive applications.
- Fatty Acid-Based:Derived from natural sources, fatty acid-based lubricants offer biodegradability and skin-friendly properties for sustainable textile production.
Oil-Based products lead on market scale; Silicone-Based solutions lead on momentum.
Application:
The specific textile manufacturing processes dictate the required performance profile for yarn lubricants across various applications.
- Air-Jet Spinning:Air-jet spinning applications require lubricants with exceptional antistatic properties and low fiber-to-metal friction to prevent yarn breaks at very high speeds. Demand is significant in advanced textile production facilities in Vietnam, supporting efficient output of synthetic fibers.
- Draw Texturing:Draw texturing processes necessitate lubricants that can withstand high temperatures and pressures while maintaining consistent yarn quality and elongation. This segment sees high demand from producers of performance sportswear in China, seeking durable and resilient yarns.
- Ring Spinning:Ring spinning, a traditional method, requires lubricants that ensure consistent yarn tension and reduce friction during fiber twisting.
- Open-End Spinning:Open-end spinning benefits from lubricants that minimize fiber entanglement and improve processing efficiency for coarser yarns.
Ring Spinning maintains foundational market volume; Air-Jet Spinning applications are expanding most quickly.
End User Industry:
Customer types define distinct procurement patterns and performance expectations for yarn lubricants.
- Technical Fabricators:Technical Fabricators produce textiles for automotive, medical, and industrial uses, requiring lubricants that meet stringent performance and safety standards. This segment drives demand for specialized, high-performance formulations in regions with strong industrial bases, such as Germany and Japan.
- Textile Mills:Textile Mills represent the foundational consumer base for yarn lubricants, utilizing them across a broad spectrum of spinning, weaving, and knitting operations. Their demand is concentrated in major production hubs like India and Pakistan, seeking cost-effective and efficient processing aids.
- Apparel Manufacturers:These producers use yarn lubricants to ensure smooth processing of fibers into clothing, focusing on aesthetic and tactile qualities.
- Home Textile Producers:Home textile producers require lubricants that contribute to the durability and finish of fabrics for bedding, upholstery, and curtains.
Textile Mills comprise the largest volume; Technical Fabricators exhibit the steepest expansion trajectory.
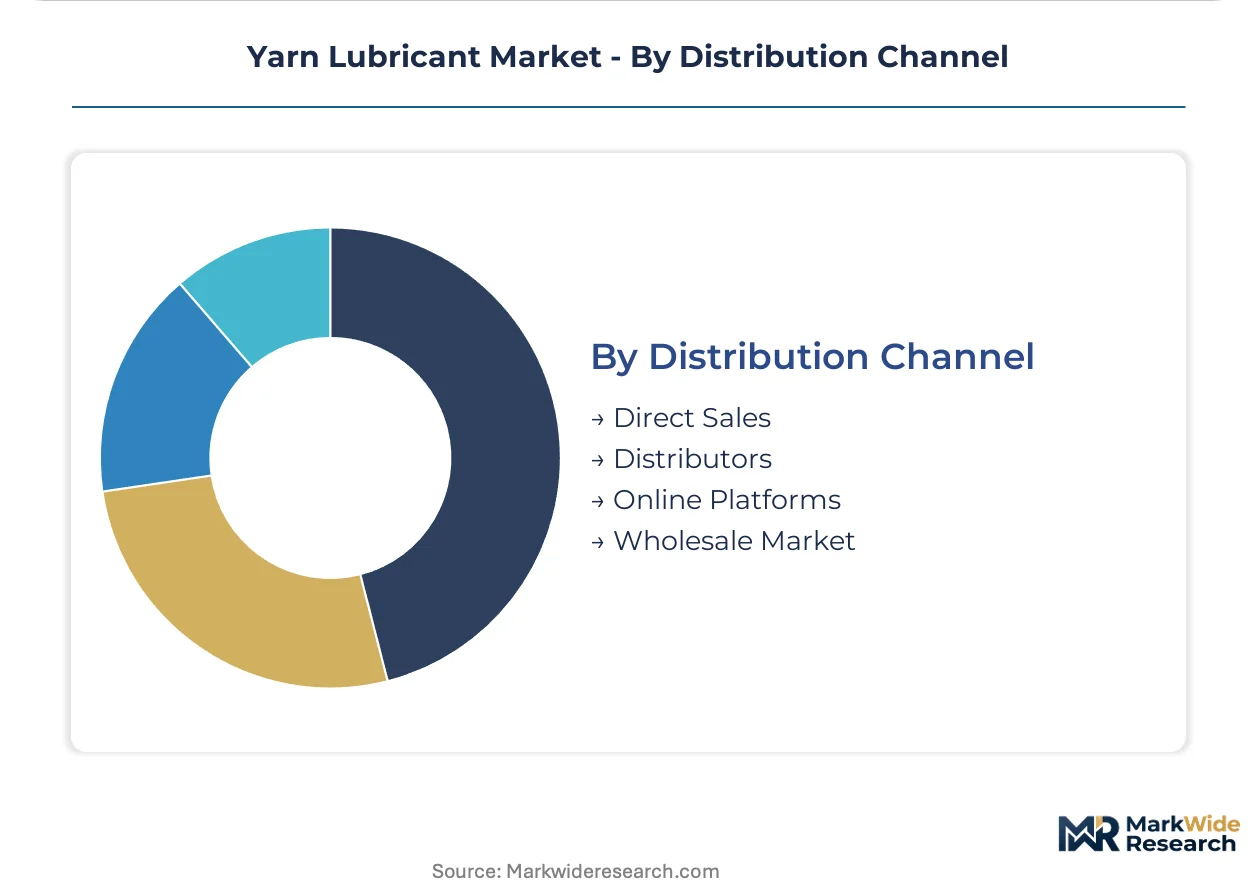
Distribution Channel:
The procurement strategies of textile manufacturers shape the preferred distribution channels for yarn lubricants.
- Direct Sales:Direct Sales involve lubricant manufacturers supplying products directly to large textile mills or specialized fabricators, often with technical support and customized solutions. This channel is prevalent for high-value, specialized formulations in markets like the US and Europe.
- Distributors:Distributors serve as intermediaries, providing regional access and logistical support for a wide range of lubricant products to numerous textile producers. This channel is crucial for reaching smaller and medium-sized mills across diverse geographies, including Brazil and Turkey.
- Online Platforms:Online platforms are gaining traction, offering convenience and broader product access, particularly for smaller orders and standardized products.
- Wholesale Market:The wholesale market caters to bulk purchases, often for commodity-grade lubricants, serving a wide array of textile manufacturing operations.
Direct Sales provide primary market access; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The yarn lubricant market's historical lineage traces back to the foundational requirements of textile manufacturing. Early formulations were essential for the smooth operation of basic spinning and weaving machinery. Demand subsequently evolved significantly with industrialization and the establishment of major global textile production hubs.
China
Demand for draw texturing lubricants for performance sportswear drives significant volume. China's GB standards define critical market access requirements for chemical substances. Textile production clusters in Jiangsu and Zhejiang provinces foster continuous innovation in lubricant formulations.
Vietnam
High-speed air-jet spinning applications necessitate advanced antistatic lubricants in Vietnam. Government policies actively support textile industry modernization and export growth. Manufacturing hubs around Ho Chi Minh City focus on efficient synthetic fiber output.
Bangladesh
Cost-effective oil-based lubricants dominate high-volume apparel manufacturing segments in Bangladesh. REACH compliance impacts export-oriented textile mills seeking international market access. The dense garment industry in Dhaka creates a concentrated demand ecosystem.
Germany
Technical fabricators in Germany require specialized silicone-based lubricants for medical textiles and high-performance applications. The EU's REACH framework mandates stringent biodegradability and safety standards. Baden-Württemberg hosts advanced textile and chemical industries, driving specialized lubricant demand.
United States
Specialized formulations for technical textiles drive direct sales channels within the United States. EPA oversight influences chemical substance use and product development for market entry. North Carolina's textile research triangle fosters innovation in advanced materials and processing aids.
Yarn Lubricant Market Key Industry Players
Premium-margin players sit above commodity-margin players across performance and sustainability criteria. The market structure exhibits a tiered consolidation, with specialized innovators and integrated chemical suppliers competing alongside cost-focused volume providers. Key competitive moves include portfolio diversification into bio-based solutions and strategic partnerships with textile machinery manufacturers.
Klüber Lubrication represents the high-performance synthetic product segment for demanding textile applications. Zschimmer & Schwarz exemplifies broad portfolio coverage across multiple stages of textile processing. TotalEnergies anchors the cost-effective, high-volume segment, leveraging its significant scale in base oil production.
| Leading Market Players |
|---|
| SIAM PRO DYECHEM GROUP |
| Klüber Lubrication |
| Achitex Minerva S.p.A. |
| Zschimmer & Schwarz |
| TAKEMOTO OIL & FAT CO., LTD. |
| Clearco Products Co., Inc. |
| Giovanni Bozzetto S.p.A. |
| TotalEnergies |
| Rudolf GmbH |
| Others |
Cost & Logistics Intelligence
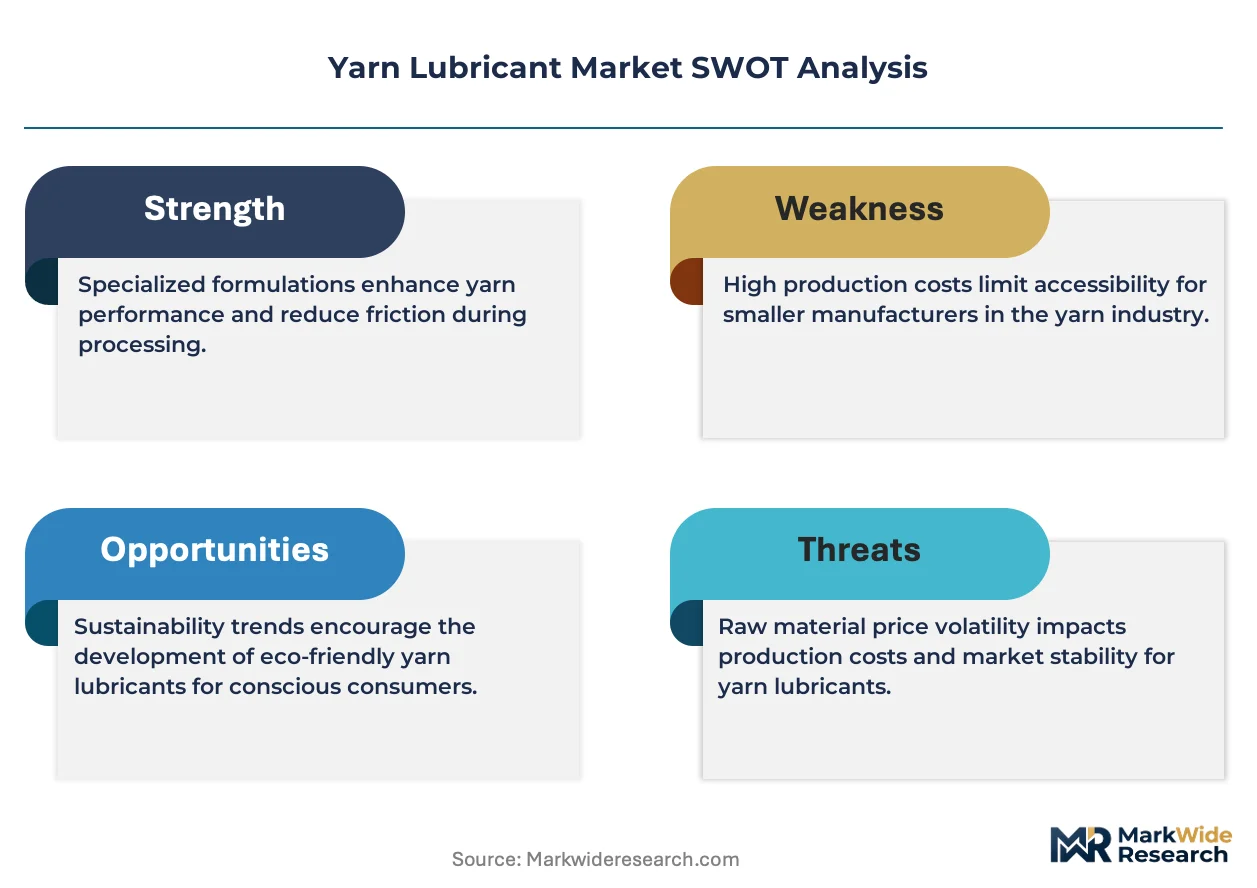
EU's REACH framework and brand owner sustainability mandates are compelling lubricant formulators to invest in novel bio-based chemistries, which impacts raw material sourcing and adds cost to the supply chain.
Pricing Analysis
Value-based tiered pricing structures characterize the yarn lubricant market, reflecting performance differentiation and application specificity. Price differentiation stems from factors like high-performance chemistries for advanced textile machinery and certification for biodegradability or skin-contact safety. Pricing pressure stems from raw material volatility, particularly for conventional oil-based formulations tied to crude oil markets. Textile mills in high-volume, less demanding segments like basic apparel exhibit the highest price sensitivity.
Supply Chain Analysis
Regulatory qualification for chemical substances, such as China's GB standards and the EU's REACH, gates market access for lubricant suppliers. The supply of formulated lubricants concentrates in Europe and Asia, leveraging established chemical industries and proximity to textile hubs. Supply chains draw from global base oil markets and increasingly from plant-based esters for bio-based alternatives. Commodity price volatility for crude oil and base oils represents a significant structural risk. Distribution runs through direct sales channels for specialized solutions and distributors for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yarn lubricant market is a stable compounder, with steady growth driven by continuous advancements in textile processing technologies.
For Market Incumbents: Anchor market share by optimizing existing synthetic platforms while concurrently investing in novel bio-based chemistries. This dual strategy addresses the escalating regulatory pressure for skin-safe formulations and the skills gap in bio-based science. Enhance application-specific dosing solutions to improve process efficiency for textile mills.
For New Entrants and Emerging Players: Launch via strategic partnerships with textile machinery manufacturers to integrate smart dosing systems directly. Target the technical fabricators segment with specialized silicone-based lubricants, leveraging their superior thermal stability for high-performance applications. Focus initial market penetration on advanced textile manufacturing centers like Vietnam and Bangladesh, where quality consistency is paramount.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized innovators possessing dual expertise in high-performance synthetic chemistry and bio-based lubricant science. This market offers long-term viability driven by technological evolution and sustainability mandates. A signal to watch for acquisition targets is successful biodegradability certification under stringent international standards, indicating future market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Shifts production towards bio-based lubricants, aligning with sustainability mandates and brand owner requirements. |
| Product Launch: Bio-Based Formulations | Captures value from growing demand for environmentally friendly and skin-safe textile processing aids. |
| Strategic Partnership with Machinery OEMs | Integrates lubricant delivery with advanced textile equipment, enhancing process control and efficiency. |
| Distribution Channel Expansion via Online Platforms | Broadens market reach and offers convenient access for smaller orders and standardized lubricant products. |
| Capacity Expansion for Silicone-Based Products | Supports the growing demand from technical fabricators for high-performance and thermally stable lubricants. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Primary research involved discussions with chemical engineers, textile mill procurement managers, R&D directors at lubricant formulators, and regulatory compliance officers. Secondary data sources included industry association reports, patent databases for new formulations, and government regulatory filings from bodies like REACH and EPA. A bottom-up and top-down triangulation approach ensured data consistency.
A segment-weighting approach formed the core of the analytical framework across the modeling period. Segmentation dimensions modeled included product type, application, end-user industry, and regional regulatory landscape. Compound annual growth rates were derived from historical trends, competitive landscape shifts, and technological advancements. Key industry-specific forecast inputs included raw material price forecasts and textile machinery adoption rates.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events affecting supply chains or rapid disruptive material innovations. Forecasts reflect assumptions documented through the research process. A model refresh is warranted upon material change in global trade policies or major regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Global Finished Lubricant Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Egypt Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Food Grade Lubricant Market