
 North America Active Pharmaceutical Ingredients Market | 2026-2036
North America Active Pharmaceutical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Active Pharmaceutical Ingredients Market Intelligence
Peptide-based synthesis is decoupling from conventional small-molecule chemistry across North American API manufacturing, altering cost structures for complex therapeutics. Pfizer Inc. leverages integrated biologics capacity to capture margin in high-potency segments, while Amgen Inc. anchors its position through captive mammalian-cell production infrastructure. AbbVie Inc. differentiates via antibody-drug conjugate expertise that commands premium positioning in oncology supply chains.
Active pharmaceutical ingredients constitute the biologically active components in drug formulations, typically synthesized through chemical routes or biotechnological expression systems with purity thresholds exceeding 99.5% for most commercial applications. These substances serve as the therapeutic foundation for finished dosage forms across prescription and generic medicine portfolios. Synthetic APIs retain the largest revenue share due to mature process economics and broad therapeutic applicability, yet biotech APIs represent the fastest-expanding category driven by monoclonal antibody and cell-therapy pipelines. Contract manufacturing organizations now absorb a disproportionate share of biotech API volume as pharmaceutical manufacturers outsource capital-intensive bioreactor operations.
FDA Current Good Manufacturing Practice enforcement and the IRA Medicare price negotiation provisions collectively compress pricing flexibility while elevating quality compliance burdens for market participants. Health Canada and PMRA standards further shape cross-border supply qualifications, particularly for APIs destined for dual US-Canada labeling. Stakeholders must calibrate capacity investments against evolving regulatory clarity on biosimilar interchangeability and domestic sourcing incentives.
Market Dynamics
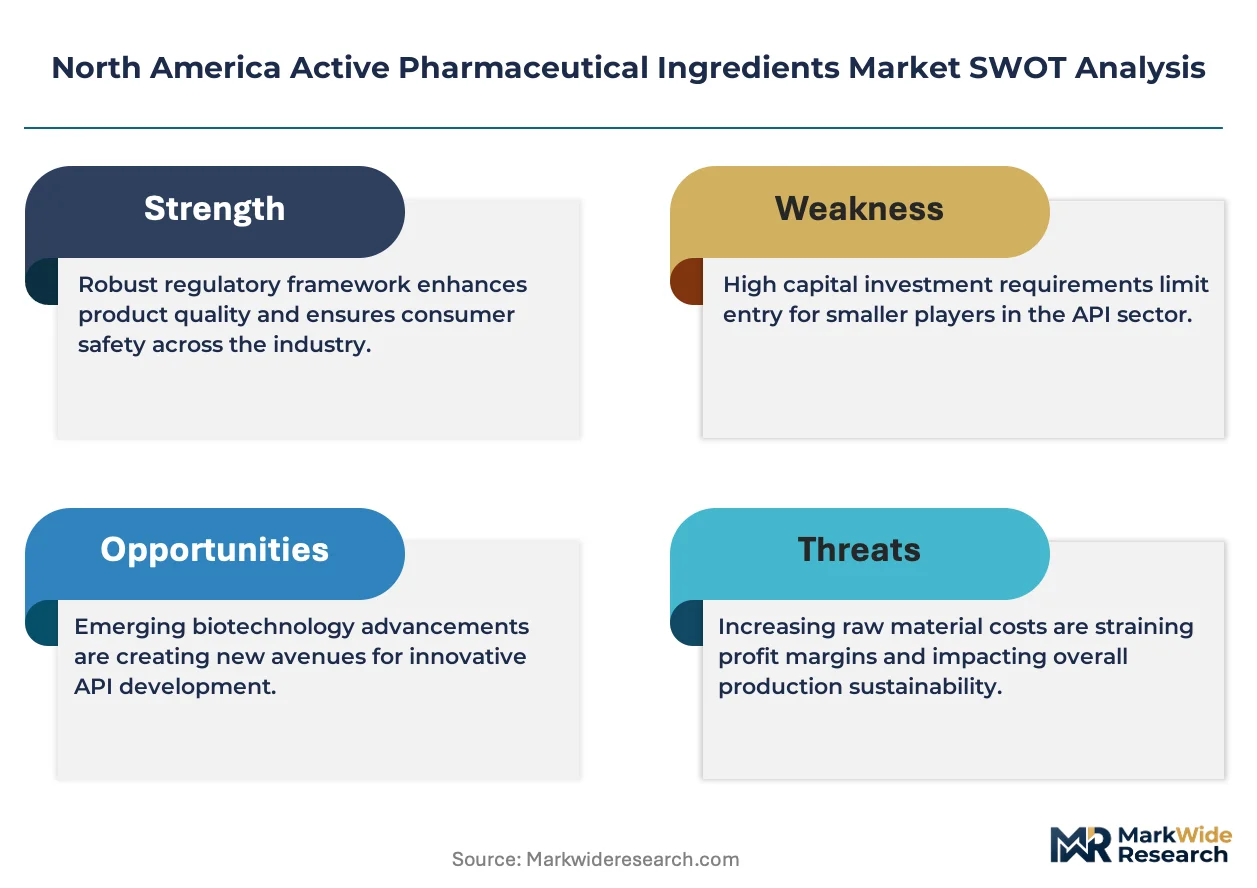
The IRA Medicare price negotiation framework is compressing pricing power across the North American API value chain while simultaneously accelerating domestic manufacturing incentives. Biotech capacity investments now hinge on clarity around biosimilar interchangeability standards and domestic sourcing credits.
Growth Catalysts
- Bioreactor capacity expansion:Contract manufacturing organizations are scaling mammalian-cell production to capture outsourced monoclonal antibody volume from pharmaceutical developers shedding capital intensity.
- Domestic sourcing incentives:The IRA's domestic manufacturing tax credits and FDA priority review vouchers for onshore API production are redirecting capital toward Massachusetts and New Jersey corridor facilities.
- Quality-by-design adoption:The FDA's QbD framework is reducing batch failure rates and accelerating regulatory approval timelines for sponsors integrating process analytical technology.
Market Restraints
- Specialized raw material concentration:Chromatography resins and single-use bioreactor components depend heavily on Asian suppliers, creating vulnerability in upstream chemical feedstock security.
- High-containment facility costs:Potent compound handling requires isolator technology and specialized HVAC infrastructure that extends depreciation schedules beyond conventional small-molecule plants.
- Interchangeability uncertainty:The FDA's evolving stance on automatic pharmacy-level biosimilar substitution without prescriber consultation creates demand forecasting risk for API planners.
Strategic Opportunities
- Antibody-drug conjugate expansion:Oncology pipelines are driving demand for cytotoxic payload-linker expertise that commands premium positioning in constrained high-potency manufacturing networks.
- Continuous processing technology:Flow chemistry integration with real-time release testing promises to compress batch cycle times and reduce solvent waste in synthetic API routes.
- Nearshoring to Mexico:Emerging pharmaceutical manufacturing clusters in Querétaro and Baja California offer tariff-advantaged export platforms serving dual US-Canada labeling requirements under USMCA provisions.
Industry Challenges
- Bioprocess engineering talent scarcity:Mammalian-cell culture expertise and cell-line development capabilities remain concentrated among a narrow cohort of specialists, constraining capacity ramp rates.
- Multi-product facility validation:Campaign changeover protocols for high-potency APIs require extensive cleaning validation and cross-contamination risk assessments that compress utilization rates.
- Legacy quality system integration:Paper-based batch records and siloed manufacturing execution systems impede real-time data integrity compliance with FDA 21 CFR Part 11 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Active Pharmaceutical Ingredients Market |
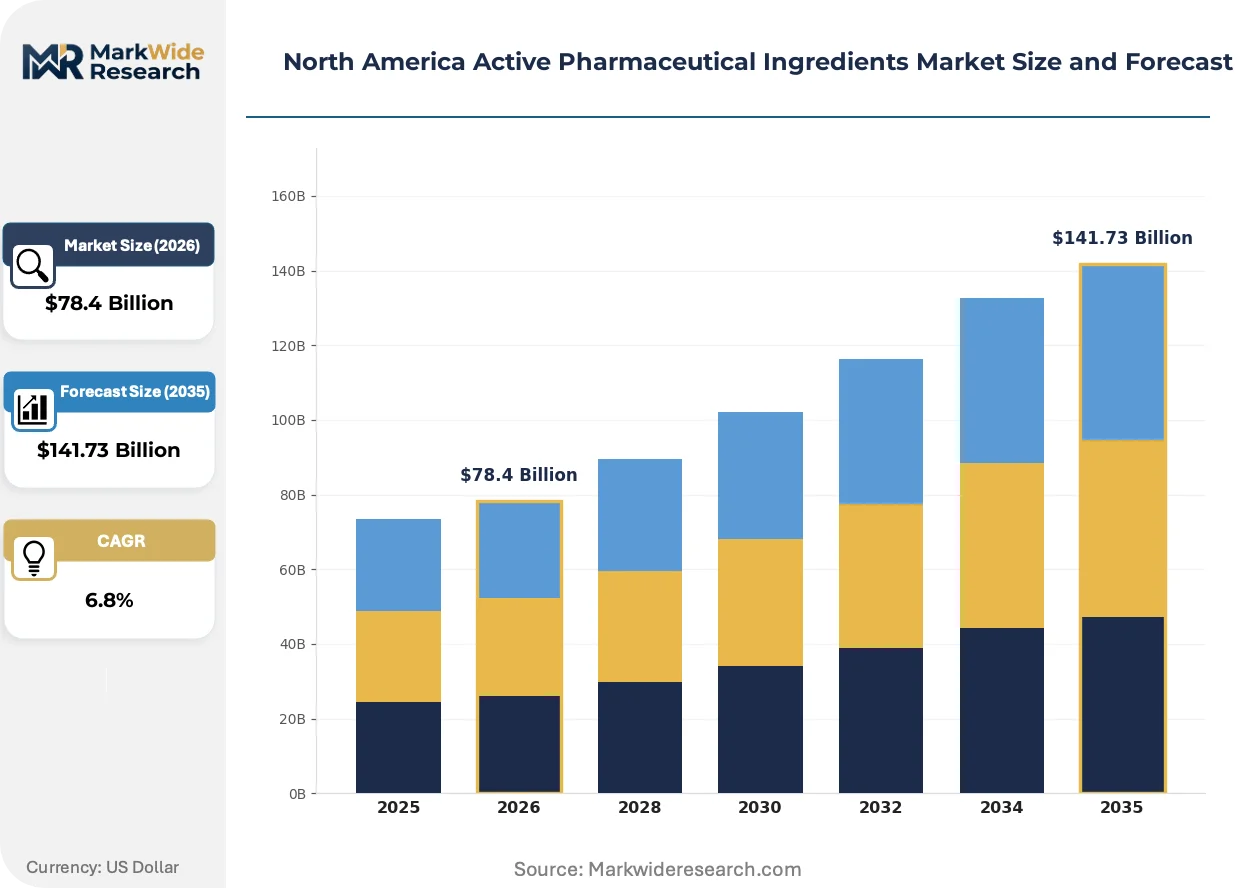
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic APIs, Biotech APIs, Traditional APIs, High Potency APIs End User: Pharmaceutical Manufacturers, Contract Research Organizations, Contract Manufacturing Organizations, Research Labs Application: Cardiovascular, Oncology, Neurology, Anti-infective Form: Powder, Liquid, Granule, Tablet |
| Companies Covered | Johnson & Johnson, Amgen Inc., AbbVie Inc., Fresenius Kabi AG, Catalent, Inc., Pfizer Inc., Bristol-Myers Squibb Company, Curia, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Active Pharmaceutical Ingredients Market Strategic Shifts & Innovations
Process intensification and modular manufacturing architectures are redrawing capital deployment patterns across North American API production. These shifts promise to compress facility construction timelines while enabling faster product changeovers.
Single-use bioreactor systems are decentralizing biologics manufacturing from centralized mega-facilities toward distributed, lower-volume production nodes. Mid-tier pharmaceutical developers are adopting 2,000-liter disposable bioreactor trains to retain in-house process control without committing to stainless-steel infrastructure. This technology is decentralizing geographic concentration of biotech API supply away from Massachusetts and New Jersey toward emerging secondary markets.
The FDA's enhanced quality management maturity program is elevating data integrity expectations for API suppliers seeking preferred vendor status. Sponsors now face heightened scrutiny of contract manufacturer deviation investigations and corrective action documentation. Small-volume parenteral and sterile API segments are responding by investing in automated environmental monitoring and electronic batch record systems.
Pharmaceutical procurement teams are consolidating supplier panels around integrated CDMO partners offering chemistry, manufacturing, and controls bundled under single accountability. This consolidation displaces fragmented sourcing across discrete chemical synthesis, formulation, and packaging vendors. The shift is most visible among emerging biotech sponsors in the San Francisco Bay Area and Research Triangle Park seeking to compress vendor management overhead.
North America Active Pharmaceutical Ingredients Market Segmentation
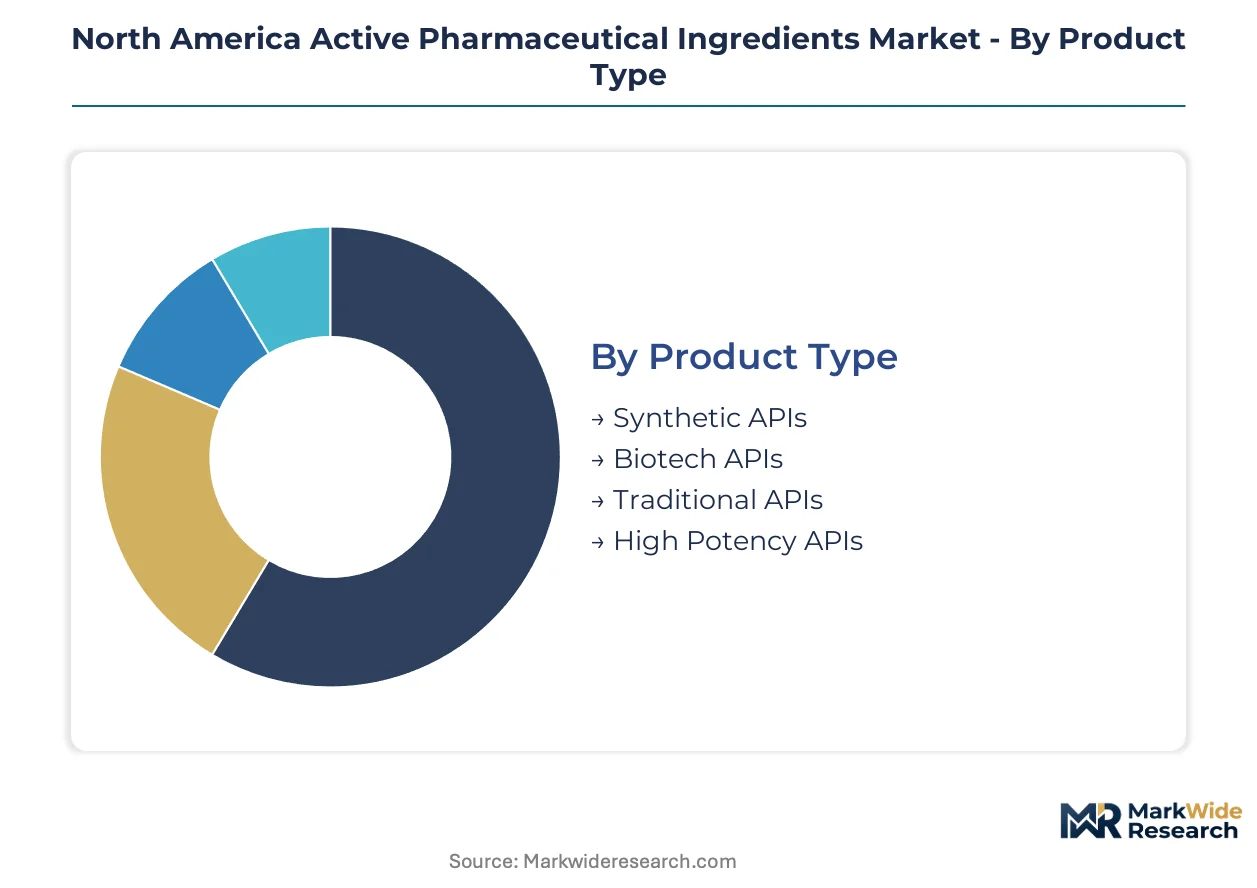
API segmentation in North America reflects divergent capital intensity and regulatory pathways across synthesis modalities. Pharmaceutical procurement teams now segment supplier panels by containment capability and bioreactor scale rather than chemistry type alone.
Product Type:
Supply concentration varies sharply across synthesis platforms, with stainless-steel infrastructure locking in geographic clustering while single-use systems enable distributed production.
- Synthetic APIs:Chemically synthesized small-molecule compounds manufactured through batch or continuous processing routes with established impurity profiling protocols. Demand concentrates among generic pharmaceutical manufacturers in New Jersey and Puerto Rico seeking cost-optimized supply security under FDA Current Good Manufacturing Practice enforcement. The IRA's domestic manufacturing incentives are redirecting capital toward onshore synthetic capacity.
- Biotech APIs:Recombinant proteins and monoclonal antibodies produced via mammalian-cell culture or microbial fermentation systems with stringent biosafety requirements. Massachusetts corridor facilities absorb the bulk of outsourced biotech volume as Amgen and Pfizer expand captive bioreactor networks. Cell-line development bottlenecks constrain capacity ramp rates despite surging oncology pipeline demand.
- Traditional APIs:Plant-derived and fermentation-based compounds with established pharmacopeial monographs serving mature therapeutic categories.
- High Potency APIs:Cytotoxic and hormone-active compounds requiring isolator technology and specialized containment infrastructure.
Synthetic APIs absorb the bulk of installed capacity; biotech APIs are expanding most quickly.
End User:
Customer type determines contract structure complexity, with integrated service agreements displacing transactional procurement across the value chain.
- Pharmaceutical Manufacturers:Vertically integrated drug developers maintaining captive API production for core franchise molecules while outsourcing non-strategic chemistries. Large-cap sponsors in the Northeast corridor are consolidating supplier panels around CDMO partners offering bundled chemistry, manufacturing, and controls accountability under single contractual frameworks.
- Contract Manufacturing Organizations:Third-party production specialists absorbing outsourced bioreactor operations from capital-constrained developers. CMOs in Massachusetts and North Carolina are scaling mammalian-cell capacity to capture monoclonal antibody volume from emerging biotech sponsors shedding fixed-asset intensity.
- Contract Research Organizations:Early-phase development partners supplying gram-scale API for toxicology and clinical pharmacology studies.
- Research Labs:Academic and government institutions sourcing reference standards and investigational compounds for preclinical research.
Pharmaceutical manufacturers dominate absolute volume; contract manufacturing organizations are climbing the fastest as outsourcing penetration deepens.
Application:
Therapeutic category shapes facility investment priorities, with oncology commanding premium positioning in constrained high-potency manufacturing networks.
- Oncology:Cytotoxic payloads, kinase inhibitors, and antibody-drug conjugates requiring containment infrastructure and specialized handling protocols. Demand concentrates in Boston and San Francisco sponsor pipelines, with AbbVie's ADC expertise anchoring premium supply positioning. The FDA's quality-by-design framework is accelerating approval timelines for sponsors integrating process analytical technology.
- Cardiovascular:Statins, anticoagulants, and antihypertensive compounds representing mature volume categories with compressed pricing flexibility under IRA Medicare negotiation provisions. New Jersey-based generic manufacturers dominate supply, with Puerto Rico facilities serving dual US-Canada labeling requirements.
- Neurology:CNS-active compounds with blood-brain barrier penetration challenges and specialized formulation requirements.
- Anti-infective:Antibiotics and antiviral APIs facing stewardship-driven demand volatility and generic commoditization pressures.
Cardiovascular applications retain the largest installed base; oncology commands the steepest expansion trajectory as ADC pipelines mature.
Form:
Physical presentation dictates supply chain configuration, with sterile powder requirements driving geographic concentration near formulation facilities.
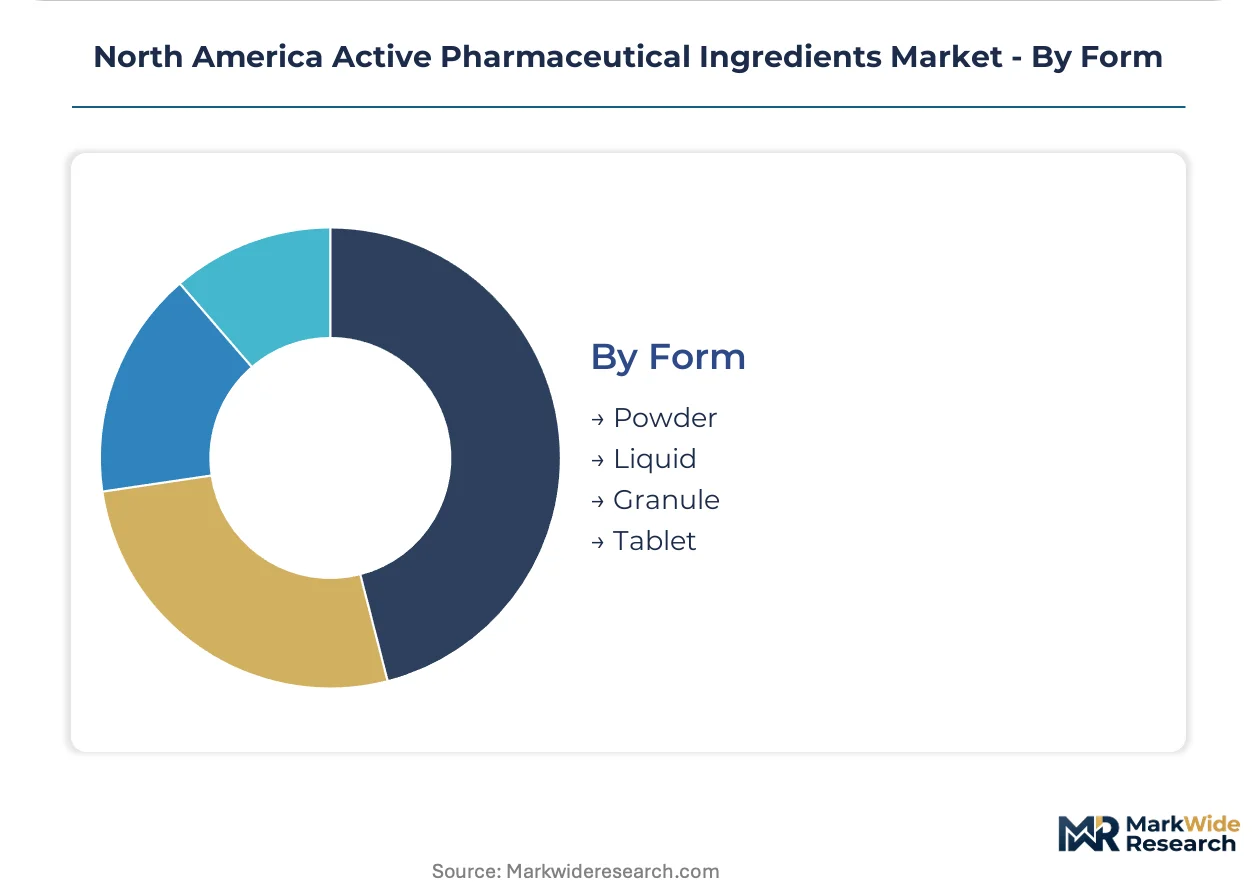
- Powder:Solid-state APIs requiring controlled humidity storage and specialized packaging for hygroscopic compounds. Bulk powder supply concentrates in Midwest chemical manufacturing clusters with rail-accessible distribution to New Jersey and Puerto Rico formulation sites.
- Liquid:Solution-phase APIs for parenteral formulations with cold-chain and sterile filtration requirements. Demand clusters near biologics fill-finish operations in Massachusetts and North Carolina, with single-use bag systems enabling just-in-time delivery.
- Granule:Intermediate processed forms for direct compression tableting operations.
- Tablet:Pre-formulated API-excipient combinations for specialty generic applications.
Powder form absorbs the bulk of synthetic API shipments; liquid form is gaining share fastest as biologics volume expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for active pharmaceutical ingredients concentrates along the Northeast pharmaceutical manufacturing corridor, where sponsor pipelines and CDMO capacity cluster in proximity to FDA headquarters and major research universities.
United States
Massachusetts and New Jersey anchor domestic biotech API production, with Boston-Cambridge biologics sponsors outsourcing mammalian-cell manufacturing to regional CDMOs. The IRA's domestic manufacturing tax credits redirect capital toward onshore stainless-steel and single-use bioreactor installations. Puerto Rico facilities serve dual US-Canada labeling requirements under FDA and Health Canada joint inspection protocols.
Canada
Ontario's pharmaceutical manufacturing base absorbs contract volume for sterile API finishing and packaging operations serving the US market. Health Canada and PMRA alignment on ICH Q7 guidelines streamlines cross-border regulatory submissions for API suppliers. Toronto-area CDMOs specialize in high-potency containment for oncology compounds destined for US formulation sites.
Mexico
Querétaro and Baja California pharmaceutical clusters emerge as tariff-advantaged export platforms under USMCA provisions. The country's national pharmaceutical regulator enforces COFEPRIS standards that converge with FDA Current Good Manufacturing Practice expectations. Foreign sponsors nearshore synthetic API production to Mexican facilities for just-in-time delivery to Texas and California formulation plants.
North America Active Pharmaceutical Ingredients Market Key Industry Players
Capacity expansion dominates the current landscape as contract manufacturing organizations race to capture outsourced bioreactor volume from capital-constrained pharmaceutical developers. The vendor base stratifies across three tiers: integrated innovators with captive biologics infrastructure, specialized CDMOs offering bundled chemistry-manufacturing-controls accountability, and regional synthetic API suppliers competing on cost-optimized scale. M&A activity and domestic facility construction represent the primary competitive vectors as sponsors consolidate supplier panels and qualify alternative sources.
Within the integrated innovator tier, Pfizer Inc. and Amgen Inc. exemplify divergent strategic postures. Pfizer leverages its biologics capacity network to retain high-potency manufacturing in-house, while Amgen anchors its position through captive mammalian-cell production infrastructure. AbbVie Inc. occupies a specialized position in antibody-drug conjugate expertise that commands premium supply chain positioning among oncology sponsors. These three entities represent distinct archetypes—scale-driven integration, bioprocess captive supply, and payload-linker specialization—that shape competitive dynamics across the North American API value chain.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Amgen Inc. |
| AbbVie Inc. |
| Fresenius Kabi AG |
| Catalent, Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Curia |
| Viatris Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up CDMO specialists now control substantial bioreactor capacity across Massachusetts and New Jersey, translating capital discipline into aggressive contract pricing that compresses margins for family-owned synthetic API producers in Puerto Rico and Midwest chemical corridors. This ownership concentration simultaneously tightens payment terms for upstream chromatography resin suppliers while amplifying price competition for generic pharmaceutical procurement teams.
Pricing Analysis
Volume-centric synthetic API contracts trade at thin margins while biotech API specialists capture premium positioning through mammalian-cell expertise and antibody-drug conjugate payload-linker capabilities. Price differentiation rests on FDA quality management maturity certification and containment infrastructure tier rather than chemistry complexity alone. Cost compression in cardiovascular and anti-infective categories intensifies as IRA Medicare negotiation provisions cascade through generic supply chains. Emerging biotech sponsors in Boston and San Francisco exhibit lowest price sensitivity for high-potency oncology APIs, while retail generic distributors drive hardest bargaining for commoditized small-molecule supply.
Supply Chain Analysis
Domestic sourcing incentives embedded in the IRA's manufacturing tax credits are redirecting API procurement toward Massachusetts, New Jersey, and emerging Puerto Rico expansion sites. Upstream production draws from specialized Asian suppliers for chromatography resins, single-use bioreactor bags, and cell culture media, creating single-source vulnerability in mammalian-cell manufacturing inputs. Tariff exposure runs through USMCA-dependent nearshoring routes into Querétaro and Baja California. Distribution runs through just-in-time liquid API delivery to biologics fill-finish operations clustered in North Carolina and the Northeast corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American API manufacturing is transitioning from stainless-steel bioreactor infrastructure toward single-use modular systems, with process intensification technologies displacing legacy batch processing economics across both synthetic and biotech routes.
For Market Incumbents: Acquire mammalian-cell culture expertise and cell-line development capabilities to offset talent scarcity constraining capacity expansion. Secure captive supply of high-potency containment infrastructure before oncology ADC demand saturates available isolator networks. Defensive consolidation around integrated CDMO partnerships protects against sponsor vertical integration back into bioreactor operations. For New Entrants and Emerging Players: Enter via specialized high-potency API manufacturing for antibody-drug conjugate payloads, where containment infrastructure shortages create supply gaps incumbent CDMOs cannot fill. Target secondary markets in Research Triangle Park and emerging Texas biotech corridors where real estate and talent costs undercut Massachusetts premiums. Lead with quality-by-design process development services that compress regulatory timelines for capital-constrained sponsors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier synthetic API specialists in Puerto Rico and Midwest chemical manufacturing clusters facing margin compression from IRA pricing provisions. Long-term viability hinges on qualifying for domestic manufacturing tax credits and FDA priority review voucher pathways. Watch biosimilar interchangeability guidance clarity as the inflection signal triggering biotech capacity valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | CDMOs scaling mammalian-cell infrastructure capture outsourced volume from Amgen and Pfizer pipeline demands. |
| Quality-by-Design Integration | FDA framework adoption reduces batch failure rates and accelerates approval timelines for oncology sponsors. |
| High-Potency Containment Investment | Isolator technology deployment commands premium positioning in constrained antibody-drug conjugate manufacturing networks. |
| Domestic Sourcing Qualification | IRA tax credit eligibility redirects capital toward Massachusetts and New Jersey corridor facility construction. |
| Continuous Processing Technology | Flow chemistry integration with real-time release testing compresses synthetic API batch cycle times and solvent waste. |
Research Approach
Document review covered FDA Current Good Manufacturing Practice enforcement records, IRA implementation guidance, and Health Canada ICH Q7 alignment protocols, complemented by interviews with CDMO operations directors, pharmaceutical procurement executives, regulatory affairs leads, and bioprocess engineering specialists. Secondary validation drew from FDA 483 inspection observations, EMA manufacturing authorization databases, clinical trial API supply disclosures, and customs trade data for chromatography resin and single-use component imports. Bottom-up capacity utilization assessments triangulated against top-down sponsor pipeline demand projections.
Market sizing and growth trajectory outputs reflect segmentation across synthesis modality, therapeutic application, end-user contract structure, and physical form presentation, with CAGRs derived from capacity expansion announcements, sponsor outsourcing disclosure patterns, and regulatory approval velocity metrics. Modeling incorporated bioreactor scale distribution, containment infrastructure deployment timelines, and domestic sourcing incentive qualification rates as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biosimilar interchangeability policy reversals, raw material trade restriction escalations, or bioprocess engineering talent availability shocks. Forecasts reflect documented assumptions regarding IRA provision durability, FDA quality management maturity program enforcement intensity, and USMCA tariff treatment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market