
 Middle East Lubricants Market | 2026-2036
Middle East Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Lubricants Market Outlook
Specialized lubricant formulation chemists is rotating toward synthetic and bio-based product lines as regional refiners upgrade output quality. Shell leverages its integrated supply chain from base oil production to finished lubricant distribution across Gulf markets. Saudi Aramco Base Oil Company - Luberef anchors the upstream segment through its Yanbu and Jeddah refining complexes, supplying Group II and III base stocks to regional blenders. ADNOC competes by extending its Ruwais refining footprint into specialized industrial lubricants for Abu Dhabi's energy sector.
Middle East lubricants comprise refined petroleum derivatives and synthetic esters formulated to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity indices typically ranging from 5 to 60 cSt at operating temperatures depending on service classification. These formulations serve critical protective functions in engines, transmissions, and hydraulic assemblies exposed to extreme thermal cycling and particulate contamination common to desert operating environments. Engine Oil commands the largest revenue share within product type segmentation due to the region's substantial vehicle parc and commercial fleet density, though Synthetic Oil within base oil categories is gaining fastest as OEM drain intervals extend and equipment precision tightens. Industrial Machinery applications generate stable offtake from Saudi Arabia's manufacturing cities and the UAE's aluminum smelting and steel fabrication complexes.
SFDA oversight of product registration and the UAE's Emirates Authority for Standardization and Metrology enforce labeling and performance claims that filter substandard imports from Asian trading routes. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for automotive fluids now reference API SP and ILSAC GF-6 specifications, compelling reformulation investments from distributors serving the Kingdom. Stakeholders must monitor how Iraq's rehabilitation of its Baiji refinery complex and Kuwait's Al-Zour facility ramp-up alter base oil trade flows and pricing power across Gulf blending operations.
Market Dynamics
SFDA tightening of biodegradability specifications and OEM drain interval extensions are forcing regional blenders to reformulate product portfolios and upgrade base oil sourcing strategies across Saudi Arabia's industrial corridor.
Growth Catalysts
- SFDA Product Registration Mandates:Saudi Arabia's pharmaceutical and food regulator now enforces stricter labeling and performance claims, filtering substandard imports and creating compliance-driven demand for certified domestic production.
- Fleet Operator Consolidation:Commercial transport logistics networks across the UAE and Saudi Arabia are modernizing, concentrating purchasing power among large fleet operators who specify synthetic formulations with extended service intervals.
- Group III Base Oil Upgrades:Regional refiners are expanding hydrocracking capacity, improving feedstock quality for high-performance lubricants serving precision machinery in aluminum smelting and steel fabrication.
Market Restraints
- Base Oil Import Concentration:Gulf blending operations remain dependent on Group II and III base stock flows from Yanbu and Jeddah refining complexes, creating single-source vulnerability during turnaround seasons.
- Reformulation Cost Burden:SASO technical regulations referencing API SP and ILSAC GF-6 specifications require capital investment in additive packages and testing infrastructure that smaller distributors cannot absorb.
- Synthetic Ester Price Volatility:Bio-based feedstock costs fluctuate with agricultural commodity markets, compressing margins on premium product lines targeted at environmentally certified buyers.
Strategic Opportunities
- Iraq Refinery Rehabilitation:Baiji complex restoration could diversify base oil supply sources for regional blenders currently sourcing through Gulf concentration points.
- Industrial Service Contracts:Abu Dhabi's energy sector and Saudi manufacturing cities are adopting total fluid management programs, bundling lubricant supply with condition monitoring and waste oil recovery.
- Kuwait Al-Zour Ramp-up:New refining capacity coming online creates alternative supply corridors and pricing leverage for blenders negotiating term contracts.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in synthetic ester chemistry and tribology testing remains concentrated among multinational technical centers, constraining regional R&D autonomy.
- Certification Timeline Compression:SFDA and Emirates Authority for Standardization and Metrology product registration cycles lag behind OEM specification updates, delaying market entry for reformulated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Lubricants Market |
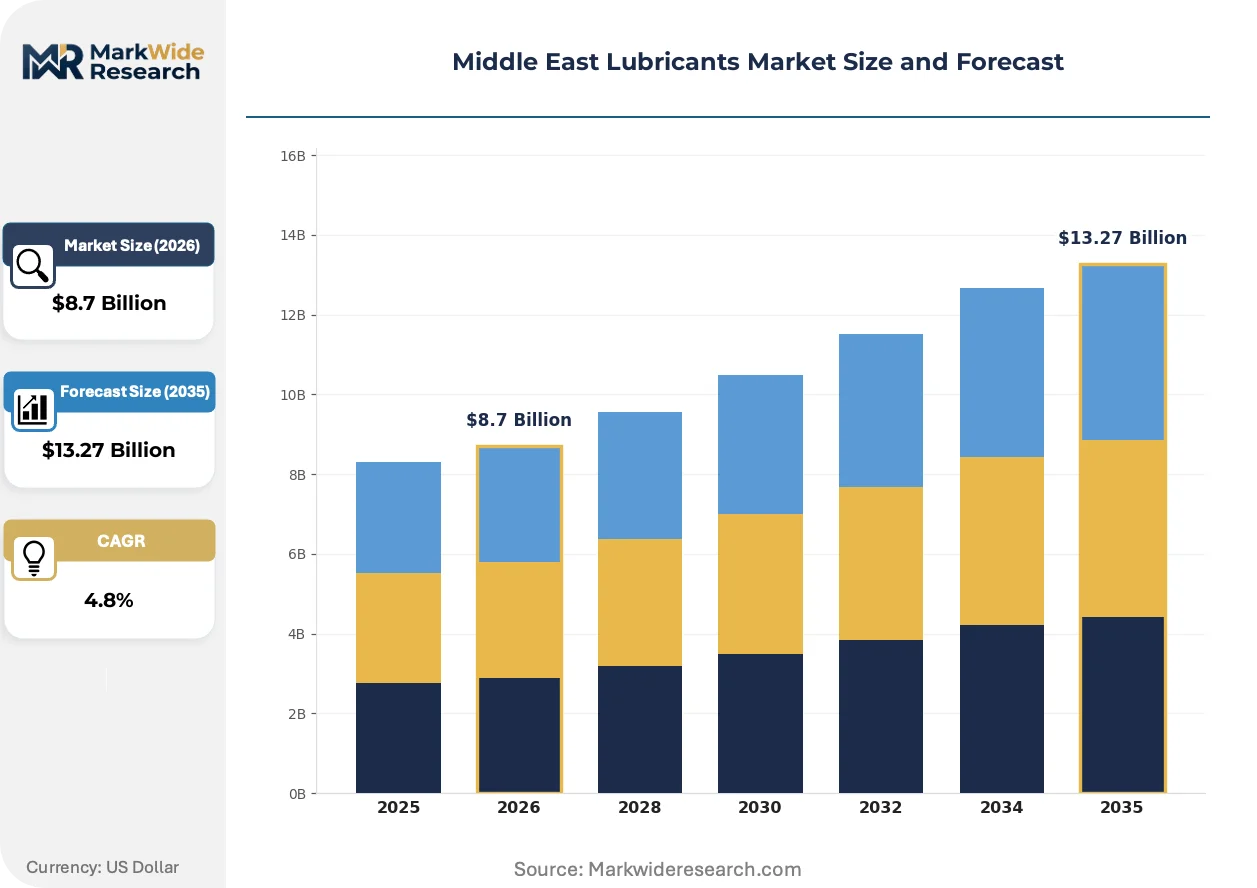
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil Base Oil Type: Mineral Oil, Synthetic Oil, Semi-Synthetic, Bio-Based Application: Automotive, Industrial Machinery, Marine, Aviation End User: Manufacturing, Transportation, Construction, Automotive Dealers |
| Companies Covered | Shell, Saudi Aramco Base Oil Company - Luberef, ExxonMobil Corporation, Petromin Corporation, FUCHS, BP p.l.c, ADNOC, Sepahan Oil Company, TotalEnergies, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Lubricants Market Strategic Shifts
Synthetic formulation chemistry and digital fluid monitoring systems are reconfiguring how lubricant value is captured across the Middle East, shifting revenue from product sales to performance-based service relationships.
Polyalphaolefin (PAO) and synthetic ester base stocks are fragmenting the traditional mineral oil hierarchy in high-temperature hydraulic and compressor applications. Petrochemical integrators in Saudi Arabia's industrial cities are adopting these formulations to extend equipment life in desert thermal cycling conditions. The technology is fragmenting supplier relationships as end-users bypass distributors to contract directly with base oil producers for customized blends.
SASO technical regulations for automotive fluids now explicitly reference API SP and ILSAC GF-6 specifications, eliminating grandfathered product registrations that previously allowed older formulation grades to remain in distribution. This regulatory compression forces inventory write-downs among distributors holding pre-specification stocks. The passenger vehicle service segment is responding fastest, with workshop chains consolidating supplier relationships to simplify compliance documentation.
Large fleet operators in commercial transport are consolidating lubricant procurement through annual tender frameworks that unbundle product supply from technical support services. Traditional distribution channels serving independent workshops face margin compression as volume concentrates among national logistics companies with in-house maintenance capabilities. This concentration is most visible in Saudi Arabia's long-haul freight corridor connecting Riyadh to Jeddah port operations.
Middle East Lubricants Market Segmentation
Channel configuration in Middle East lubricants varies sharply by segment. Product viscosity grades and certification requirements determine whether formulations move through distributor networks, direct refinery supply, or integrated service contracts.
Product Type:
Distributor margins compress where drain intervals extend and fleet operators consolidate purchasing power.
- Engine Oil:Formulations meeting API SP and ILSAC GF-6 specifications dominate volume flows. Saudi Arabia's commercial freight corridor between Riyadh and Jeddah concentrates demand as logistics operators specify synthetic grades with extended service intervals.
- Hydraulic Oil:Anti-wear additives and viscosity index improvers withstand extreme thermal cycling in desert operating environments. UAE aluminum smelting complexes and Saudi steel fabrication facilities generate stable offtake through annual technical service contracts.
- Gear Oil:Extreme pressure formulations protect differentials and transmissions in heavy-duty mining equipment.
- Transmission Fluid:OEM-specific friction modifiers serve automatic and dual-clutch applications across passenger vehicle service chains.
Engine Oil dominates installed base. Hydraulic Oil is where expansion concentrates.
Base Oil Type:
Cost tiers separate commodity mineral formulations from premium synthetic and bio-based alternatives.
- Mineral Oil:Group I and II base stocks refined from crude petroleum fractions serve price-sensitive applications. Traditional distribution channels in independent workshops and small fleet operators sustain volume despite margin pressure from specification upgrades.
- Synthetic Oil:Polyalphaolefin and synthetic ester chemistry delivers thermal stability for precision machinery. Saudi petrochemical integrators and UAE energy sector operators specify these grades to extend equipment life under extreme operating conditions.
- Semi-Synthetic:Blended formulations balance performance enhancement with cost containment for mid-tier commercial applications.
- Bio-Based:Vegetable oil derivatives and synthetic esters from renewable feedstocks target environmental certification requirements.
Mineral Oil retains volume leadership across price-sensitive channels. Synthetic Oil is climbing the fastest as OEM specifications tighten.
Application:
Customer type determines whether procurement flows through distributor inventory or direct technical partnerships.
- Automotive:Passenger vehicle service chains and commercial fleet operators generate the largest volume throughput. Workshop consolidation in Saudi Arabia and the UAE simplifies supplier relationships as chains standardize on certified formulations.
- Industrial Machinery:Total fluid management programs bundle lubricant supply with condition monitoring and waste oil recovery. Abu Dhabi's energy sector and Saudi manufacturing cities are adopting these integrated service models.
- Marine:Cylinder oils and system lubricants serve coastal shipping and offshore support vessel operations.
- Aviation:Jet engine oils and hydraulic fluids follow strict OEM approval cycles for commercial and military aircraft.
Automotive commands the broadest channel reach. Industrial Machinery is gaining share fastest through service contract bundling.
End User:
Supply concentration shapes pricing leverage across buyer categories.
- Transportation:National logistics companies with in-house maintenance capabilities concentrate purchasing power through annual tender frameworks. Long-haul freight operators across Saudi Arabia's primary corridors specify synthetic formulations with technical support services.
- Manufacturing:Aluminum smelting, steel fabrication, and petrochemical processing facilities source through direct refinery relationships. Yanbu and Jeddah refining complexes supply Group II and III base stocks to these integrated consumers.
- Construction:Project-based demand for hydraulic and engine oils flows through equipment rental companies and contractor supply chains.
- Automotive Dealers:OEM-affiliated service networks procure certified formulations through authorized distributor channels.
Transportation leads volume concentration. Manufacturing is where upstream integration is deepest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA product registration mandates and Yanbu-Jeddah refining concentration anchor Saudi Arabia's regulatory and supply influence across Gulf lubricant trade corridors.
Saudi Arabia
Commercial freight corridors between Riyadh and Jeddah port operations concentrate synthetic lubricant demand as logistics operators consolidate fleet purchasing through annual tender frameworks. SASO technical regulations referencing API SP and ILSAC GF-6 specifications eliminate grandfathered product registrations and compel reformulation investments. Yanbu and Jeddah refining complexes supply Group II and III base stocks to regional blenders serving petrochemical integrators in Saudi Arabia's industrial cities.
United Arab Emirates
Aluminum smelting complexes in Abu Dhabi and steel fabrication facilities in Dubai generate stable hydraulic oil offtake through direct refinery relationships and integrated service contracts. The Emirates Authority for Standardization and Metrology enforces labeling and performance claims that filter substandard imports from Asian trading routes. ADNOC's Ruwais refining footprint extends into specialized industrial lubricants for Abu Dhabi's energy sector operators.
Kuwait
Al-Zour refinery facility ramp-up creates alternative supply corridors for regional blenders currently dependent on Saudi base oil concentration points. The national oil company's downstream expansion alters pricing leverage in term contract negotiations across Gulf blending operations. Kuwait's manufacturing and transport sectors absorb Group III base stocks for precision machinery applications.
Iraq
Baiji refinery complex rehabilitation could diversify base oil supply sources for regional blenders currently sourcing through Gulf concentration points. National reconstruction programs and equipment fleet renewal generate demand for engine and hydraulic oils in construction and transport applications. Baghdad and Basra industrial zones represent latent consumption growth as security conditions stabilize.
Qatar
LNG sector maintenance operations and port logistics generate specialized lubricant demand for marine and heavy equipment applications. The country's energy sector procurement frameworks favor suppliers with integrated technical service capabilities. Doha-based distribution networks serve as transit points for premium synthetic formulations entering smaller Gulf markets.
Middle East Lubricants Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Middle East lubricants. Refinery-affiliated producers with captive base oil supply compete against multinational blenders with technical service networks. Three archetypes dominate: integrated national oil company lubricant divisions, global majors with Gulf distribution infrastructure, and regional distributors with workshop channel relationships. Competitive moves concentrate on backward integration into base oil production and portfolio diversification toward synthetic and bio-based formulations.
Among integrated national oil company lubricant divisions, Saudi Aramco Base Oil Company - Luberef anchors upstream supply through Yanbu and Jeddah refining complexes. Shell and ExxonMobil Corporation exemplify global majors with Gulf distribution infrastructure and technical service capabilities. These three entities represent the dominant competitive anchors shaping regional supply relationships and pricing benchmarks.
| Leading Market Players |
|---|
| Shell |
| Saudi Aramco Base Oil Company - Luberef |
| ExxonMobil Corporation |
| Petromin Corporation |
| FUCHS |
| BP p.l.c |
| ADNOC |
| Sepahan Oil Company |
| TotalEnergies |
| Others |
Value Chain & Pricing Dynamics
Yanbu and Jeddah refining complexes generate scale economies that compress base oil production costs while simultaneously concentrating pricing power among integrated producers serving Gulf blending operations. This supply-side density establishes regional price floors that smaller distributors struggle to undercut without sacrificing formulation quality or certification compliance.
Pricing Analysis
Price spreads between Saudi Arabia and the UAE narrow where direct refinery relationships bypass distributor markups, while wider spreads persist in spot markets serving independent workshops. Three-tier pricing structure across premium synthetic, standard mineral, and economy-grade mineral formulations dominates contract negotiations. Pricing pressure stems from fleet operator consolidation demanding extended-drain formulations at volume discounts. Small independent workshops exhibit highest price sensitivity, whereas petrochemical integrators prioritize thermal stability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites the security premium embedded in regional base oil logistics, with alternative routing through the Red Sea adding cost layers during geopolitical stress. Supply concentrates in Saudi Arabia, the UAE, and Kuwait as primary production hubs. Group II and III base stocks, polyalphaolefin feedstocks, and synthetic ester precursors constitute critical input dependencies. Single-source vulnerability around Yanbu-Jeddah turnaround seasons represents the dominant structural risk. Distribution runs through refinery-affiliated bulk terminals, national distributor networks, and direct technical service contracts to integrated industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East lubricants sector sits in early-cycle expansion as SFDA registration mandates and OEM specification upgrades force portfolio refresh across the installed base, creating replacement demand tailwinds for compliant formulations.
For Market Incumbents: Secure backward integration into Group III base oil production or captive additive blending capacity to defend margin compression from synthetic formulation mandates. Lock in multi-year technical service contracts with Saudi logistics operators and UAE aluminum smelters before Al-Zour ramp-up diversifies supply alternatives. Certification investment in bio-based product lines addresses emerging environmental procurement criteria. For New Entrants and Emerging Players: SFDA fast-track registration for API SP-compliant synthetic grades opens procurement channels among Saudi workshop chains consolidating supplier relationships. Target Iraq's rehabilitation-driven construction equipment segment where base oil supply diversification creates pricing leverage for new blenders. Pursue white-label manufacturing partnerships with Kuwaiti distributors seeking Al-Zour-sourced feedstock alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial fluid management providers bundling lubricant supply with condition monitoring services. Five-to-ten-year viability favors acquisition targets with established SFDA registration portfolios and direct relationships with Saudi Aramco Base Oil Company feedstock allocation. Monitor Baiji refinery rehabilitation timelines as inflection signal for regional supply diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Yanbu hydrocracking capacity captures margin from synthetic formulation upgrades across Saudi industrial cities. |
| SFDA Registration Fast-Track Investment | Accelerated compliance timelines filter substandard imports and consolidate domestic blender market share. |
| Total Fluid Management Service Contracts | Abu Dhabi energy sector adoption bundles lubricant supply with predictive maintenance and waste oil recovery. |
| Synthetic Ester Formulation R&D Partnership | Desert thermal cycling specifications drive PAO and bio-based adoption among precision machinery operators. |
| Al-Zour Supply Corridor Diversification | Kuwait refining expansion creates alternative term-contract leverage for regional blenders negotiating feedstock. |
Study Parameters
Initial hypotheses were tested against primary input from lubricant formulation chemists, fleet procurement managers at Saudi logistics operators, refinery technical directors, and aftermarket distribution channel heads and refined through secondary validation against SASO technical regulations, SFDA product registration databases, customs trade flow records, and petrochemical sector capex disclosures. Bottom-up volume builds from segment-level consumption rates triangulated against top-down refinery capacity and base oil output estimates.
Variance decomposition across product type, base oil grade, application sector, and end-user concentration shapes the analytical framework over the projection horizon. CAGRs derive from modeled replacement cycles, specification upgrade penetration curves, and industrial capacity expansion pipelines. Forecast inputs incorporate OEM drain interval extension trajectories and SFDA registration timeline compression effects.
Decision-makers should treat outputs as directional under stable geopolitical transit conditions and assumed Al-Zour ramp-up schedules; material deviation in Baiji rehabilitation progress or Hormuz routing disruptions would warrant model refresh. Practitioners should keep alternative scenarios live as Iraq supply integration and bio-based feedstock cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Marine Grease Market
Lubricants
Germany Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Construction Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Canada Lubricants Market