
 Anti-Static Oil Market | 2026-2036
Anti-Static Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Oil Market Outlook
Pharmaceutical-grade purity specifications are rotating toward the center of competitive strategy in the anti-static oil sector. Witmans Group leverages backward integration into specialty additive chemistry to sustain formulation consistency across batches. Hindustan Petroleum Corporation Limited anchors its position through captive refinery infrastructure serving domestic electronics corridors. Takemoto Oil & Fat Co. Ltd differentiates via long-standing supply relationships with precision equipment builders in East Asia.
Anti-static oil denotes a surface-active fluid engineered with controlled conductivity, typically achieving resistivity between 10^6 and 10^9 ohms per square, to dissipate electrostatic charges during precision manufacturing. The formulation prevents catastrophic discharge damage to sensitive components in semiconductor cleanrooms, automotive paint lines, and electronics assembly stations. Hydraulic oil occupies the largest volume share among product types due to pervasive deployment in automated manufacturing equipment. Synthetic technology commands premium pricing traction as fabs enforce stricter particulate and outgassing standards. Electronics manufacturers represent the most concentrated customer type, with procurement decisions increasingly tied to supplier audit protocols.
EPA regulations governing volatile organic compound emissions constrain solvent-based formulation options in the United States. REACH registration requirements in Europe mandate full chemical substance disclosure, elevating compliance costs for mineral-based imports. Semiconductor producers must now align procurement with both OSHA workplace exposure limits and fab-specific ionic contamination thresholds. Stakeholders should monitor how dual carbon targets in China reshape base oil sourcing requirements and whether biodegradable certification becomes a mandatory gate for automotive OEM qualification.
Market Dynamics
Semiconductor fabrication facilities in Taiwan and South Korea are expanding procurement of synthetic anti-static oil formulations, forcing mineral-based suppliers to accelerate reformulation timelines or exit high-specification segments entirely.
Growth Catalysts
- Synthetic formulation migration:Fabs enforce stricter particulate and outgassing standards, pulling demand toward engineered base stocks with controlled conductivity between 10^6 and 10^9 ohms per square.
- REACH compliance pressure:ECHA registration mandates in Europe elevate biodegradable base oils as qualifying criteria for automotive OEM supply contracts.
- East Asian electronics corridors:Concentrated manufacturing in Hsinchu Science Park and Yongin semiconductor clusters sustains volume pull for hydraulic-grade anti-static fluids.
Market Restraints
- Base oil supply concentration:Specialty ester and polyalphaolefin feedstocks concentrate among a limited cohort of European and North American chemical producers, exposing formulators to allocation risk.
- EPA VOC constraints:Stricter volatile organic compound rules in the United States eliminate solvent-based formulation pathways for domestic electronics assembly applications.
- Mineral oil substitution:Legacy paraffinic bases face displacement by synthetic alternatives, stranding capital invested in conventional blending infrastructure.
Strategic Opportunities
- Biodegradable certification tailwinds:EU Green Deal procurement guidelines and China's dual carbon targets create preferential channel access for certified sustainable formulations.
- Automotive paint line expansion:Electrostatic spray applications in EV manufacturing facilities generate incremental demand for conductivity-controlled process fluids.
- Precision equipment service contracts:Long-term supply relationships with semiconductor tool builders enable captive aftermarket revenue streams.
Industry Challenges
- Additive chemistry talent scarcity:Formulation expertise combining conductivity control with oxidative stability concentrates among a narrow specialist cohort, constraining R&D velocity.
- Dual compliance timelines:Semiconductor producers must simultaneously satisfy OSHA workplace exposure limits and fab-specific ionic contamination thresholds, extending qualification cycles.
- Legacy system integration:Mineral-based fluid users face switching costs from established filtration and handling infrastructure when migrating to synthetic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Oil Market |
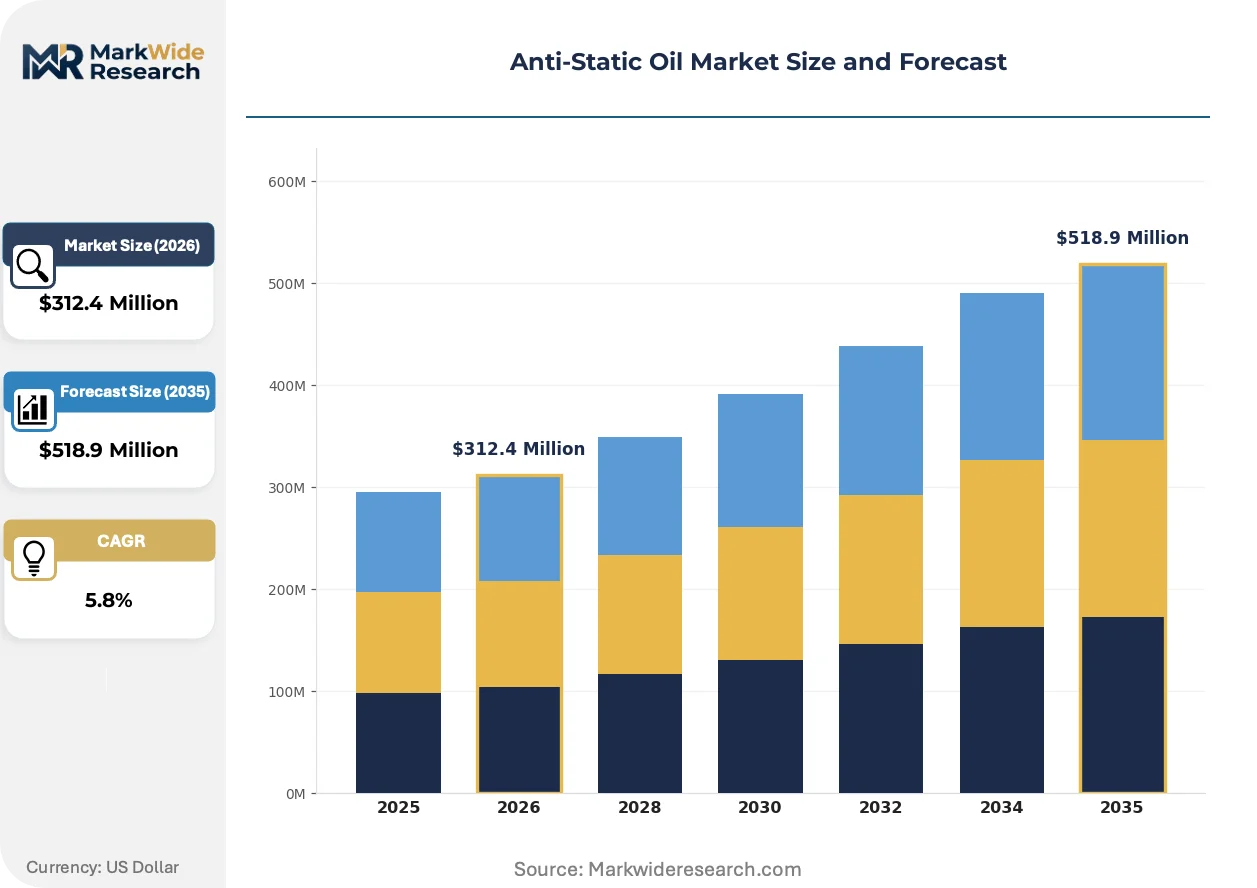
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Oil, Lubricant Oil, Cutting Fluid, Coating Oil Application: Manufacturing Equipment, Electronic Components, Automotive Assembly, Semiconductor Production Technology: Synthetic, Biodegradable, Natural, Mineral-Based Customer Type: Industrial Manufacturers, Automotive OEMs, Electronics Manufacturers, Aerospace Firms |
| Companies Covered | Witmans Group, Hansen & Rosenthal Group, Hindustan Petroleum Corporation Limited, Indian Oil Corporation Limited, Panama Petrochem Ltd, H&R GROUP, Takemoto Oil & Fat Co. Ltd, Ricci SpA, Transfar Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Oil Market Strategic Shifts
Synthetic base oil technology is actively restructuring competitive positioning in anti-static formulations, compressing the viable shelf life of mineral-derived alternatives while opening new specification tiers.
Ester-based synthetic formulations is supplanting Group II mineral oils in semiconductor cleanroom applications. Leading fabs in Taiwan and South Korea now mandate synthetic grades for ionic contamination-sensitive processes. This transition is compressing margin pools for conventional blenders while rewarding backward-integrated additive specialists.
REACH registration requirements in Europe mandate full chemical substance disclosure for mineral-based imports, elevating compliance costs and documentation burdens. ECHA scrutiny of persistent organic pollutants is narrowing the acceptable additive chemistry palette. Formulators serving European automotive OEMs are responding by accelerating biodegradable base oil development programs.
Supplier audit protocols now dominate procurement decisions among electronics manufacturers, displacing price-primary selection criteria. Third-party certification of conductivity stability and particulate cleanliness determines contract eligibility. This behavioral shift is most pronounced in South Korean semiconductor supply chains, where fab-specific qualification gates exceed industry-standard ISO specifications.
Anti-Static Oil Market Segmentation
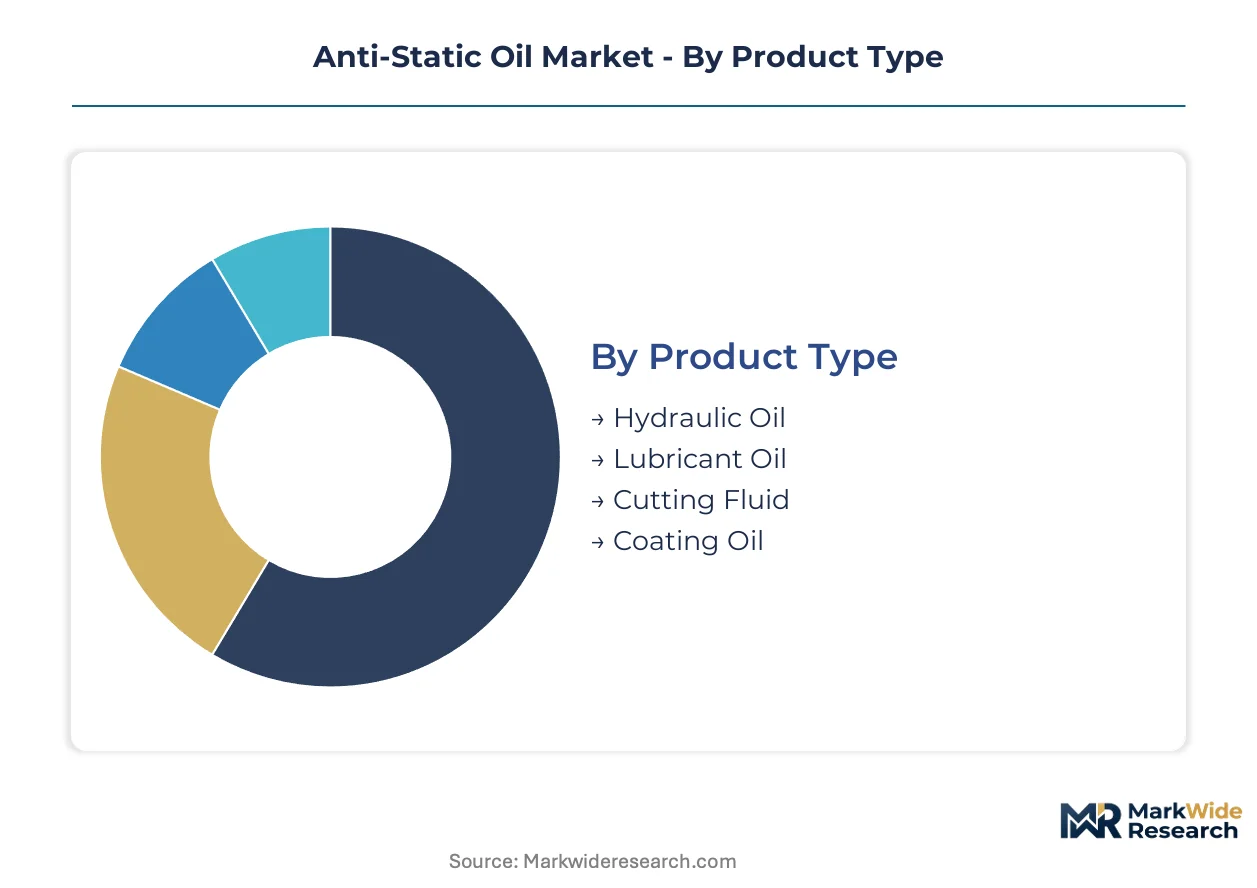
Segmentation in anti-static oil markets reveals how conductivity specifications, base stock chemistry, and end-use contamination thresholds fragment procurement requirements across precision manufacturing verticals.
Product Type:
Premium margin pools concentrate in formulations serving semiconductor cleanrooms where ionic contamination limits are tightest.
- Hydraulic Oil:Formulated with controlled resistivity between 10^6 and 10^9 ohms per square for automated manufacturing equipment. Demand concentrates in Hsinchu Science Park fabs where hydraulic systems power wafer handling robotics under strict particulate protocols.
- Lubricant Oil:Engineered for precision bearing and spindle applications with oxidative stability additives. South Korean semiconductor clusters sustain volume pull for high-purity lubricant grades that prevent electrostatic discharge during high-speed rotation.
- Cutting Fluid:Metalworking fluids with conductivity-modified bases for precision machining operations.
- Coating Oil:Surface treatment formulations for electrostatic spray applications in automotive paint lines.
The dominant share belongs to Hydraulic Oil, while Lubricant Oil is closing the gap fastest.
Application:
Volume distribution tracks the geographic density of electronics manufacturing corridors and their respective cleanroom standards.
- Semiconductor Production:Synthetic formulations dominate ionic contamination-sensitive processes in Taiwan and South Korean fabs. Yongin cluster procurement mandates now exceed ISO specifications for particulate cleanliness and outgassing thresholds.
- Electronic Components:Assembly line fluids for printed circuit board manufacturing and final device packaging. Shenzhen electronics corridors drive procurement of mid-tier mineral-based grades with conductivity stabilization additives.
- Manufacturing Equipment:General industrial automation fluids for non-cleanroom precision machinery.
- Automotive Assembly:Electrostatic spray process fluids for EV paint line expansion in European and East Asian facilities.
Semiconductor Production commands the largest volume position, with Electronic Components expanding most quickly as assembly automation spreads.
Technology:
Compliance timelines across multiple regulatory jurisdictions are accelerating base stock substitution patterns.
- Synthetic:Ester and polyalphaolefin base stocks engineered for controlled conductivity and minimal outgassing. Taiwan Semiconductor Manufacturing Company procurement specifications now exclude mineral-based alternatives for critical process steps.
- Biodegradable:Vegetable-derived ester formulations qualifying for EU Green Deal procurement guidelines. REACH registration requirements elevate biodegradable bases as gate criteria for automotive OEM supply contracts in Europe.
- Mineral-Based:Legacy Group II paraffinic oils facing displacement by synthetic alternatives in high-specification segments.
- Natural:Unmodified plant oil bases with limited conductivity control for non-critical applications.
Synthetic technology holds the dominant share, while Biodegradable formulations are gaining share fastest under regulatory pressure.
Customer Type:
Procurement sophistication varies sharply between fabs with captive qualification protocols and general industrial buyers.
- Electronics Manufacturers:Supplier audit protocols now dominate procurement decisions, displacing price-primary selection criteria. Third-party certification of conductivity stability determines contract eligibility in South Korean supply chains.
- Automotive OEMs:ECHA scrutiny of persistent organic pollutants and EPA VOC constraints are narrowing acceptable additive chemistry palettes for paint line process fluids.
- Industrial Manufacturers:General automation equipment operators with standardized ISO-based fluid specifications.
- Aerospace Firms:Specialty applications requiring MIL-spec conductivity control for fuel system and avionics manufacturing.
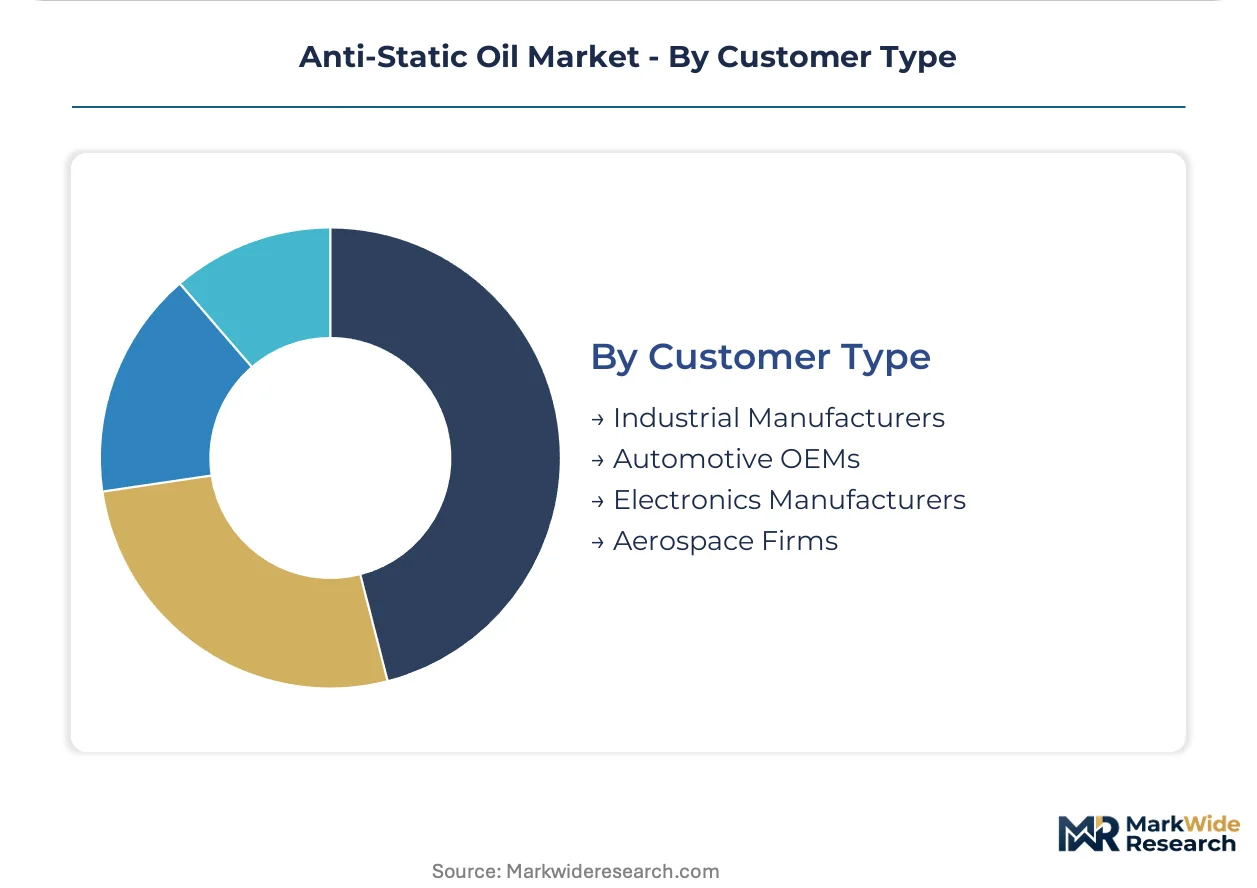
Electronics Manufacturers retain the dominant procurement volume, with Automotive OEMs climbing fastest as EV production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean synthetic anti-static oil exports flow primarily to Taiwan's semiconductor fabrication corridors, while European biodegradable formulations reach automotive OEMs across Germany and France. This trade pattern concentrates procurement decisions in East Asian electronics manufacturing clusters and Western European regulatory jurisdictions.
United States
EPA volatile organic compound rules constrain solvent-based formulation pathways for domestic electronics assembly applications. OSHA workplace exposure limits apply additional compliance layers for semiconductor tool maintenance operations. Austin and Phoenix semiconductor corridors sustain procurement of hydraulic-grade anti-static fluids for wafer handling robotics.
Taiwan
Hsinchu Science Park fabs mandate synthetic grades with resistivity between 10^6 and 10^9 ohms per square for ionic contamination-sensitive process steps. Taiwan Semiconductor Manufacturing Company procurement specifications now exclude mineral-based alternatives for critical manufacturing stages. Kaohsiung packaging facilities drive secondary demand for mid-tier conductivity-stabilized formulations.
South Korea
Yongin semiconductor clusters enforce fab-specific qualification gates exceeding ISO specifications for particulate cleanliness and outgassing thresholds. MFDS chemical substance registration requirements elevate documentation burdens for mineral-based imports. Samsung and SK Hynix supply chains dominate procurement volume for precision equipment service contracts.
Germany
ECHA scrutiny of persistent organic pollutants narrows acceptable additive chemistry palettes for automotive paint line process fluids. REACH registration mandates elevate biodegradable base oils as qualifying criteria for OEM supply contracts. Bavarian automotive manufacturing facilities generate incremental demand for conductivity-controlled electrostatic spray applications.
China
Dual carbon targets reshape base oil sourcing requirements for domestic electronics manufacturers. MEE environmental compliance timelines accelerate reformulation toward biodegradable ester bases in Yangtze River Delta manufacturing corridors. Shenzhen electronics assembly automation spreads procurement of mid-tier mineral-based grades with conductivity stabilization additives.
Anti-Static Oil Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and refinery infrastructure dimensions. The vendor base separates into three tiers: state-affiliated energy majors with captive blending capacity, independent additive specialists with backward integration into specialty chemistry, and regional distributors serving localized industrial corridors. Two dominant competitive moves define current positioning: synthetic base stock substitution programs that strand conventional mineral oil assets, and long-term supply relationships with semiconductor tool builders that lock in aftermarket revenue streams.
Among state-affiliated energy majors, Hindustan Petroleum Corporation Limited and Indian Oil Corporation Limited occupy positions anchored by captive refinery infrastructure serving domestic electronics manufacturing corridors. Witmans Group exemplifies the independent additive specialist archetype, while Takemoto Oil & Fat Co. Ltd represents the precision equipment service contract model through its established supply relationships with East Asian semiconductor tool builders.
| Leading Market Players |
|---|
| Witmans Group |
| Hansen & Rosenthal Group |
| Hindustan Petroleum Corporation Limited |
| Indian Oil Corporation Limited |
| Panama Petrochem Ltd |
| H&R GROUP |
| Takemoto Oil & Fat Co. Ltd |
| Ricci SpA |
| Transfar Chemicals |
| Others |
Value Chain & Pricing Dynamics
REACH registration requirements in Europe gate both supplier qualification and price differentiation simultaneously, as ECHA chemical substance disclosure mandates elevate compliance costs for mineral-based imports while creating premium positioning for biodegradable-certified formulations. Semiconductor fabs in Taiwan and South Korea enforce fab-specific ionic contamination thresholds that stratify procurement tiers, compressing margins for conventional blenders while rewarding backward-integrated additive specialists with pricing power.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with synthetic ester formulations commanding substantial premiums over Group II mineral bases due to Taiwan Semiconductor Manufacturing Company procurement exclusions. Price differentiation rests on certification grade—ISO particulate cleanliness tiers versus fab-specific qualification gates—and volume scale commitments from Hsinchu Science Park corridors. Cost compression in mid-tier mineral grades is intensifying because Yongin cluster procurement mandates now exceed industry-standard specifications. Contract electronics manufacturers in Shenzhen corridors exhibit highest price sensitivity, while captive semiconductor tool service contracts demonstrate lowest sensitivity due to aftermarket revenue lock-in.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Taiwan and South Korean semiconductor fabs, where wafer handling robotics require continuous hydraulic-grade fluid replenishment under strict particulate protocols. Geographic supply concentration centers on Germany, Belgium, and the United States for specialty ester and polyalphaolefin feedstocks, exposing formulators to allocation risk from European chemical producers. Raw material dependencies draw from vegetable-derived ester bases, synthetic base stock imports, and conductivity-control additive packages. Single-source vulnerability runs through a limited cohort of backward-integrated additive specialists. Distribution feeds from regional blending facilities into fab-specific qualification channels, with long-term supply agreements locking in semiconductor tool builder aftermarket streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise combining conductivity control with oxidative stability concentrates among a narrow specialist cohort, constraining R&D velocity and creating acquisition scarcity for additive chemistry capabilities. This capability gap shapes competitive positioning across synthetic base stock substitution programs and precision equipment service contract capture.
For Market Incumbents: Shield synthetic formulation margins by accelerating biodegradable base oil development programs ahead of EU Green Deal procurement guideline expansion. Lock in captive aftermarket revenue through long-term supply relationships with semiconductor tool builders in East Asian corridors, defending against emerging additive specialists with backward integration into specialty chemistry. Prioritize qualification gate navigation over price competition in Yongin and Hsinchu clusters where fab-specific protocols exceed ISO specifications. For New Entrants and Emerging Players: EU biodegradable certification fast-tracks create white-space access for vegetable-derived ester formulations serving automotive OEM paint line expansion in Bavarian and French manufacturing facilities. Target mid-tier mineral-based displacement in Shenzhen electronics assembly corridors where procurement remains price-primary and conductivity stabilization additives suffice. Pursue precision equipment service contract models through established relationships with semiconductor tool maintenance operations. For Investors and Strategic Acquirers: China's dual carbon targets reshaping base oil sourcing requirements reshape the acquisition landscape toward biodegradable ester formulation capabilities with Yangtze River Delta manufacturing corridor access. Long-term viability favors backward-integrated additive specialists with in-house production of conductivity-control chemistry and established fab qualification histories. Watch for MEE environmental compliance timeline acceleration as the inflection signal triggering accelerated mineral oil substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Witmans Group leverages captive specialty chemical production to sustain batch consistency across semiconductor fab qualifications. |
| Biodegradable Base Oil Development Program | REACH registration mandates elevate vegetable-derived ester formulations as gate criteria for European automotive OEM supply contracts. |
| Long-term Supply Agreement with Tool Builders | Takemoto Oil & Fat Co. Ltd locks in aftermarket revenue through established relationships with East Asian precision equipment manufacturers. |
| Synthetic Formulation Migration | Taiwan Semiconductor Manufacturing Company procurement exclusions now strand conventional mineral oil assets in critical process steps. |
| Fab-specific Qualification Gate Navigation | Samsung and SK Hynix supply chains demand conductivity stability certification exceeding ISO particulate cleanliness specifications. |
Study Parameters
The analysis maps hydraulic-grade, lubricant-grade, cutting fluid, and coating oil sub-sectors, each validated through procurement directors at semiconductor fabs, technical R&D heads at additive specialists, and plant managers at automotive paint line facilities. Primary interviews with distribution channel partners and aftermarket service heads combined with secondary validation from customs/trade data, ECHA registration databases, SEC 10-K filings, and semiconductor equipment capex disclosures. Bottom-up volume triangulation across formulation grades and top-down market sizing from electronics manufacturing corridor density checks ensured consistency.
Volume and value outputs were validated against external benchmarks including semiconductor fab capacity expansion announcements and automotive OEM electrostatic spray process fluid procurement patterns across the projection horizon. Segmentation dimensions modeled encompass product type, application vertical, base stock technology, and customer procurement sophistication tier. CAGRs were derived from elasticity-adjusted demand projections tied to synthetic formulation migration rates and regulatory compliance timeline acceleration. Industry-specific forecast inputs included Taiwan and South Korean fab ionic contamination threshold evolution and EPA VOC constraint enforcement patterns.
The analysis sits within stated boundaries; outcomes outside continued East Asian electronics manufacturing corridor concentration and stable REACH registration cost structures would require recalibration. Forecasts reflect assumptions regarding synthetic base stock substitution velocity and biodegradable certification adoption curves. Revision becomes warranted when China's dual carbon target implementation crosses thresholds triggering accelerated domestic base oil sourcing mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Argentina Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Specialty Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Thailand Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Myanmar Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Cutting Fluid Market
Lubricants
Nigeria Lubricants Market