
 America Airport Ground Handling Systems Market | 2026-2036
America Airport Ground Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
America Airport Ground Handling Systems Market Outlook
A capital-intensity divergence between legacy equipment manufacturers and automation-focused entrants is unwinding competitive dynamics across the America Airport Ground Handling Systems Market. John Bean Technologies Corporation leverages its vertical integration into refrigeration and cargo loading systems to sustain pricing power in North American hubs. TUG Technologies Corporation anchors its position through specialized tow tractor engineering for narrow-body fleets. Cavotec SA competes via electrified ground support equipment that reduces apron emissions for carriers operating under stricter environmental protocols.
America airport ground handling systems encompass the motorized, electro-hydraulic, and software-integrated equipment used to service aircraft during ground time, including baggage tugs rated for 60,000-pound drawbar pull and 400-Hz ground power units delivering regulated alternating current to parked jets. These systems enable sub-45-minute turnaround cycles that determine daily flight utilization and gate throughput at congested hubs. Automated Systems within the Technology dimension leads capital deployment as airports retrofit apron operations with autonomous baggage tractors and AI-guided cargo positioning. Ramp Services under Service Type captures the fastest operational expansion, driven by low-cost carriers demanding simultaneous passenger deplaning, catering exchange, and fueling to maximize aircraft availability. Mobile Applications support real-time equipment tracking but remain a smaller margin pool concentrated among handling agents managing distributed fleet logistics.
The FAA mandates ground support equipment emissions compliance through its Voluntary Airport Low Emissions program, while OSHA enforces apron worker safety standards that shape equipment guarding and proximity sensor requirements. Brazil's ANVISA coordinates with airport operators on cargo handling hygiene protocols for pharmaceutical freight, adding certification layers for temperature-controlled ground systems. Stakeholders must weigh electrification capital commitments against the operational flexibility of hybrid platforms as regulatory thresholds tighten across federal and state jurisdictions.
Market Dynamics
Fleet densification at southeastern US hubs is compressing turnaround windows below 40 minutes, forcing apron operators to prioritize automation-capable ground support equipment over legacy diesel fleets. This operational squeeze is restructuring procurement criteria across American airports.
Growth Catalysts
- FAA Voluntary Airport Low Emissions Program:Federal incentives for electrified ground power units and electric baggage tugs are accelerating equipment replacement cycles at Tier 1 airports.
- Pharmaceutical freight certification:Brazil's ANVISA temperature-control mandates for cargo handling are expanding demand for refrigerated dollies and climate-monitored loaders.
- Hub congestion in Atlanta and Charlotte:Gate scarcity at these southeastern nodes is forcing airlines to adopt simultaneous servicing protocols that require higher-capacity cargo loaders.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on Asian cell manufacturers creates input cost volatility and extended lead times for electric tug production.
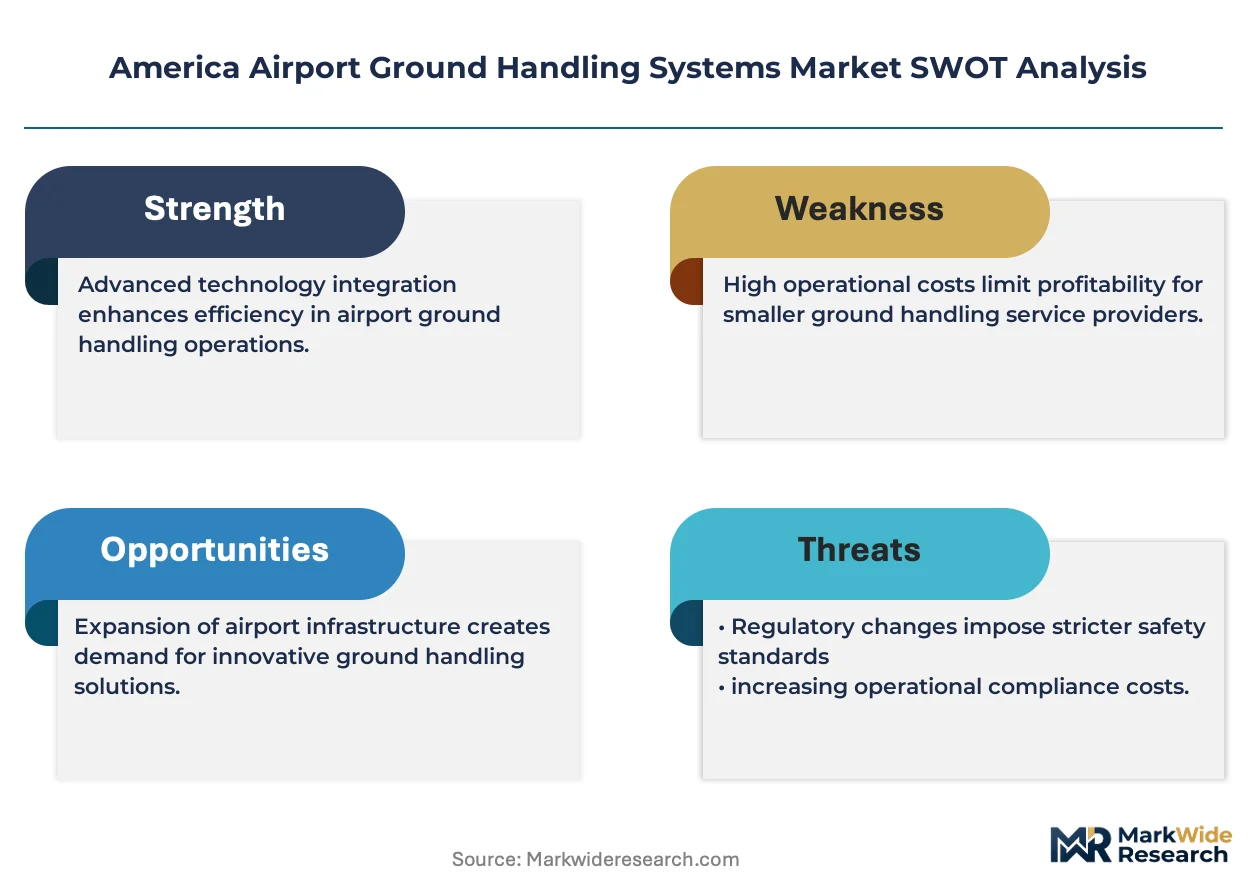
- OSHA proximity-sensor mandates:Retrofitting existing equipment fleets with collision-avoidance systems imposes capital burdens on regional ground handlers with thin margin profiles.
- Technical limitation in autonomous navigation:Current AI-guided tractors struggle with apron edge-case scenarios like severe weather and non-standard aircraft positioning.
Strategic Opportunities
- Canadian prairie airports:Underpenetrated facilities in Calgary and Edmonton lack dedicated cargo infrastructure, creating first-mover space for integrated handling system providers.
- 5G-enabled predictive maintenance:Convergence of cellular connectivity and equipment telematics allows real-time component monitoring, reducing unplanned downtime for narrow-body fleets.
- Hybrid platform leasing models:New equipment-as-a-service channels are emerging to bypass the capex barrier for mid-size ground handling agents.
Industry Challenges
- Certified aviation electrician shortage:FAA Part 65 licensing requirements for 400-Hz ground power unit technicians outpace vocational training program output.
- Legacy fleet integration friction:Automated baggage tractors must interface with decades-old warehouse management software at established hubs, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Airport Ground Handling Systems Market |
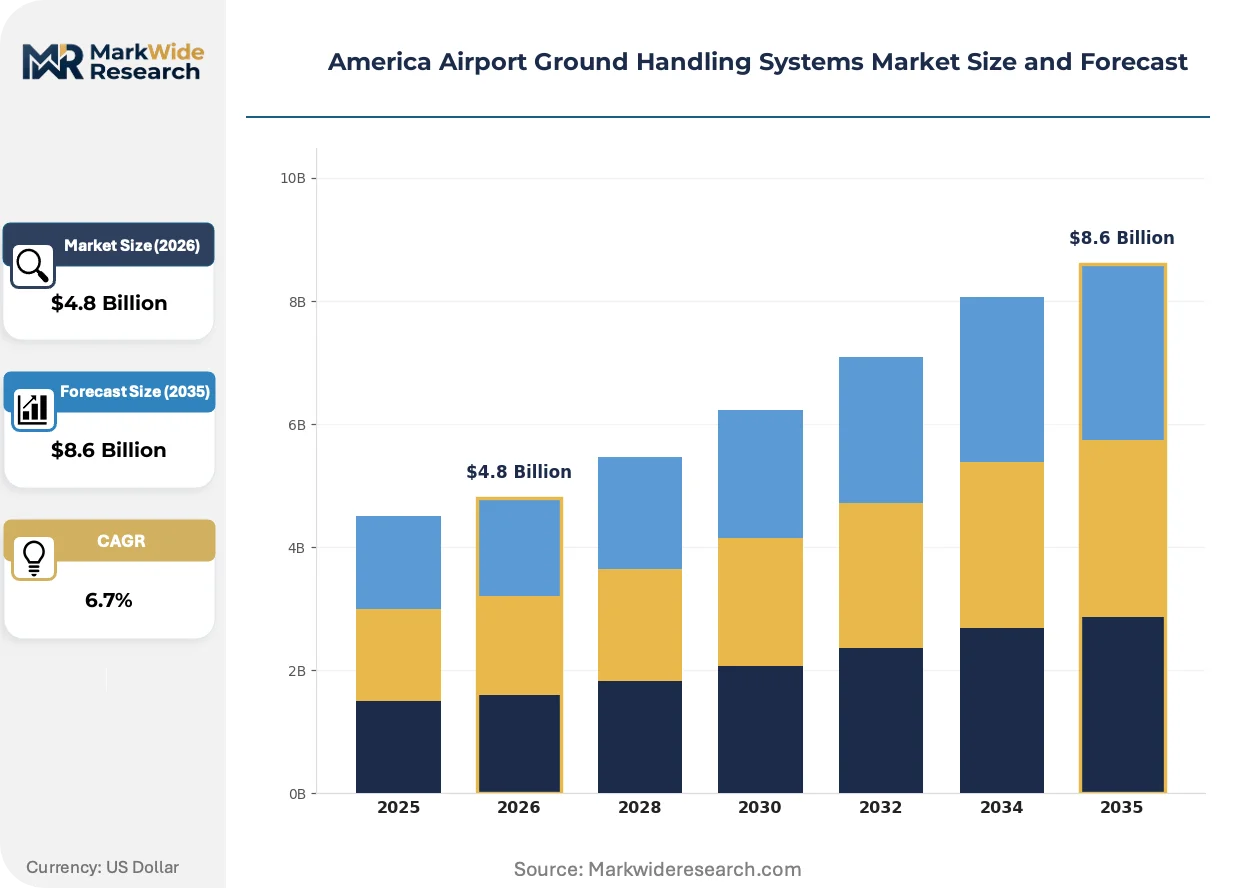
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Handling, Cargo Handling, Ramp Services, Aircraft Maintenance Technology: Automated Systems, Mobile Applications, Tracking Systems, Robotics Equipment Type: Baggage Tugs, Cargo Trucks, Ground Power Units, Baggage Carts End User: Airports, Airlines, Handling Agents, Freight Forwarders |
| Companies Covered | John Bean Technologies Corporation, TUG Technologies Corporation, Cavotec SA, Tronair, Inc., BEUMER Group A/S, Mototok International GmbH, Oshkosh Aerotech, Alliance Ground International, Swissport International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Airport Ground Handling Systems Market Strategic Shifts
Electrification and autonomy are colliding on the apron, creating divergent equipment categories that serve different operational profiles rather than converging on a single platform standard.
Autonomous baggage tractors equipped with lidar-based navigation and 5G backhaul are bifurcating the tow tractor segment into premium automation-ready units and stripped-down manual alternatives. Low-cost carriers operating high-frequency narrow-body routes are adopting these systems fastest, while legacy network carriers with mixed fleets maintain hybrid procurement. The technology is compressing labor deployment models at congested gates where single-operator oversight of multiple autonomous units replaces dedicated tractor drivers.
OSHA's updated powered industrial truck standards are mandating operator presence detection and automatic speed limitation in apron zones. These rules are forcing equipment redesigns that add sensor suites and control modules to existing chassis architectures. Ramp services contractors in the southeastern United States are responding fastest, driven by insurance liability pressures at high-volume hubs.
Consolidated fleet management platforms are displacing siloed equipment tracking systems across ground handling agents. These cloud-based tools aggregate telemetry from tugs, loaders, and power units into unified dashboards that optimize dispatch and maintenance scheduling. The shift is most visible among third-party handling providers managing distributed operations across multiple airport authorities, where equipment utilization visibility directly impacts contract profitability.
America Airport Ground Handling Systems Market Segmentation
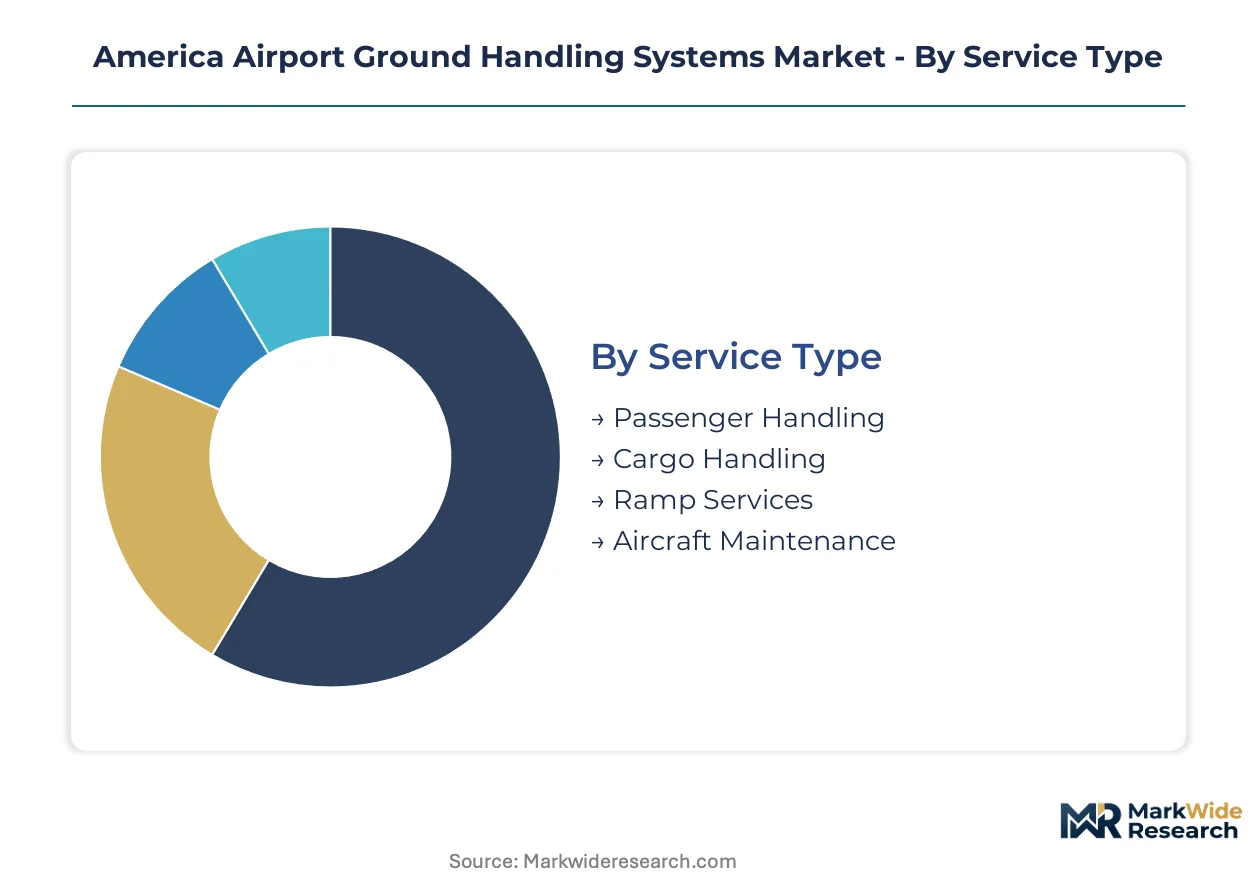
Ground handling procurement patterns diverge sharply between legacy hub operators and emerging cargo-focused facilities across the Americas. Equipment specification, technology adoption, and service bundling decisions cluster around regulatory compliance thresholds and fleet utilization pressures that vary by operator type and geography.
Service Type:
FAA apron safety mandates and OSHA collision-avoidance requirements create tiered compliance burdens that reshape service procurement priorities.
- Ramp Services:Simultaneous aircraft servicing protocols—combining deplaning, catering exchange, and fueling—demand synchronized ground equipment deployment. Low-cost carriers operating 40-minute turnaround windows at Atlanta and Charlotte drive fastest adoption of integrated ramp solutions.
- Cargo Handling:Temperature-controlled pharmaceutical freight requirements under Brazil's ANVISA protocols expand demand for refrigerated dollies and climate-monitored loaders. Certification layers add margin pressure but create pricing differentiation for compliant handlers.
- Passenger Handling:Gate-side baggage sorting and passenger boarding bridge coordination.
- Aircraft Maintenance:Scheduled line maintenance and A-check servicing during ground time.
Established volume favors Ramp Services; emerging adoption favors Cargo Handling.
Technology:
Capital deployment intensity stratifies sharply between automation-ready premium tiers and connectivity-enabled mid-market solutions.
- Automated Systems:Autonomous baggage tractors with lidar navigation and 5G backhaul compress labor deployment at congested gates. Single-operator oversight of multiple units replaces dedicated drivers, with southeastern US hubs retrofitting fastest.
- Mobile Applications:Real-time equipment tracking and dispatch optimization for distributed fleet logistics. Handling agents managing multi-airport contracts deploy these tools to improve utilization visibility and contract profitability.
- Tracking Systems:Telemetry aggregation from tugs, loaders, and power units into unified dashboards.
- Robotics:AI-guided cargo positioning and automated loading mechanisms.
Margin concentration sits with Automated Systems; deployment velocity favors Mobile Applications.
Equipment Type:
Electrification mandates and battery supply constraints are restructuring procurement timelines across equipment categories.
- Baggage Tugs:Electric variants rated for 60,000-pound drawbar pull face lithium-ion cell supply bottlenecks from Asian manufacturers. Lead time volatility favors handlers with advance procurement commitments.
- Ground Power Units:400-Hz regulated alternating current systems delivering parked jet power. FAA Part 65 certification requirements for aviation electricians constrain technician availability, extending maintenance backlogs.
- Cargo Trucks:Specialized vehicles for palletized and containerized freight movement.
- Baggage Carts:Dollies and trains for loose baggage and container transport.
Operational criticality elevates Ground Power Units; replacement cycle urgency drives Baggage Tugs.
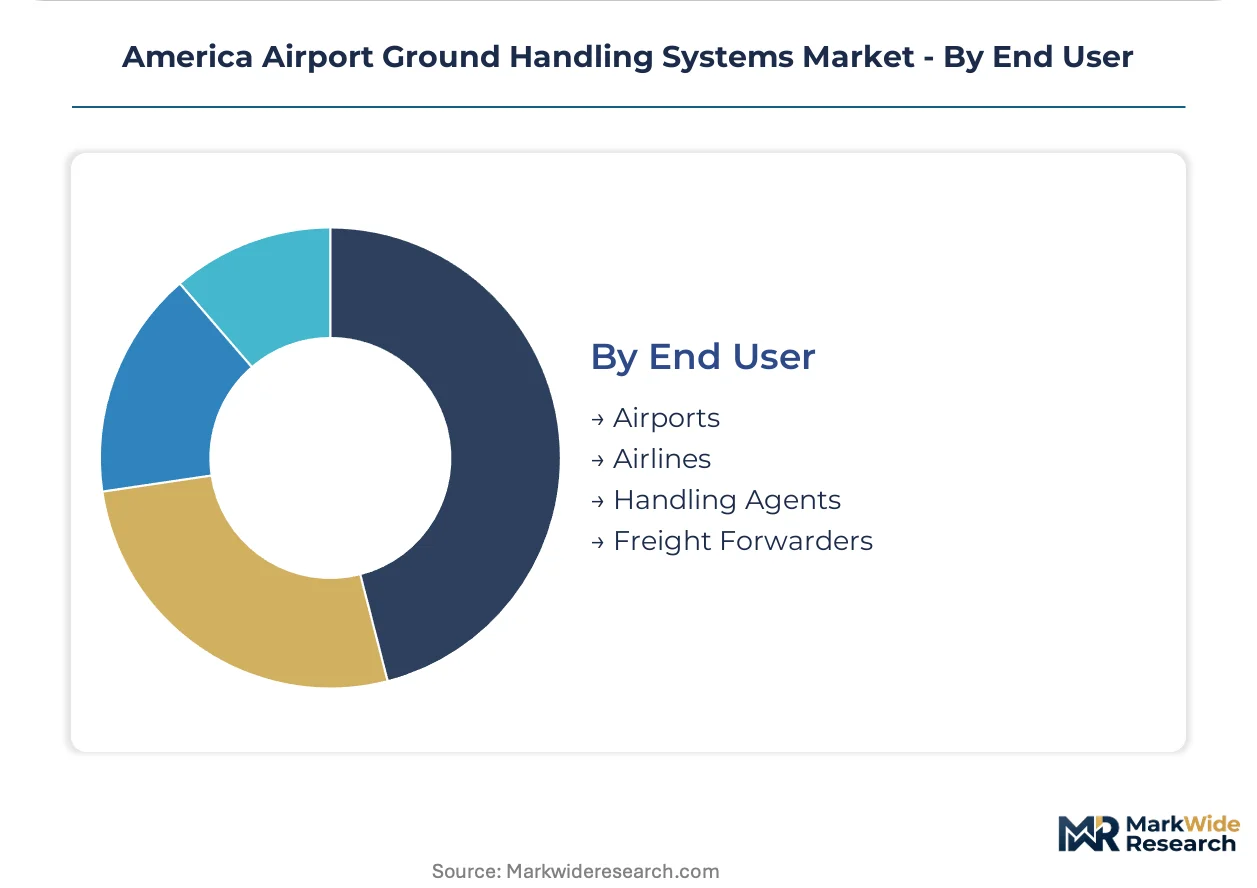
End User:
Contract structure and equipment ownership models fragment procurement authority across the apron ecosystem.
- Handling Agents:Third-party ground service providers managing distributed operations across multiple airport authorities. Equipment utilization visibility directly impacts contract profitability, driving fastest adoption of consolidated fleet management platforms.
- Airlines:Network carriers and low-cost operators with dedicated ground handling subsidiaries. Fleet standardization pressures favor equipment-as-a-service leasing models to bypass capex barriers.
- Airports:Authority-owned common-use infrastructure and gate equipment.
- Freight Forwarders:Specialized pharmaceutical and express cargo handlers with certification requirements.
Procurement scale favors Airlines; technology integration pace favors Handling Agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ground handling procurement elasticity varies sharply across the Americas, with price-sensitive regional operators in Brazil and Canada contrasting against premium-automation buyers at congested United States hubs. FAA emission mandates and ANVISA pharmaceutical protocols create divergent compliance cost structures that reshape equipment specification priorities by geography.
United States
Southeastern hub congestion at Atlanta, Miami, and Charlotte drives fastest adoption of autonomous baggage tractors and simultaneous servicing protocols. The FAA Voluntary Airport Low Emissions program accelerates electric tug replacement cycles at Tier 1 airports. Dallas-Fort Worth and Denver International retrofit apron operations with 5G-enabled fleet management platforms to compress turnaround windows below 40 minutes.
Brazil
Pharmaceutical freight certification under ANVISA temperature-control mandates expands demand for refrigerated dollies and climate-monitored cargo loaders at São Paulo-Guarulhos and Viracopos International. The country's national aviation regulator coordinates with airport operators on cargo handling hygiene protocols that add certification layers for ground systems. Campinas anchors the fastest-growing cargo handling cluster as express freight volumes concentrate in the São Paulo state corridor.
Canada
Prairie airports in Calgary and Edmonton lack dedicated cargo infrastructure, creating first-mover space for integrated handling system providers targeting underpenetrated facilities. Transport Canada harmonizes equipment safety standards with FAA protocols while maintaining distinct cold-weather operational requirements for ground power units. Toronto Pearson and Vancouver International drive premium-tier automation adoption as network carriers prioritize fleet standardization across North American operations.
Mexico
Low-cost carrier fleet expansion at Mexico City International and Cancun International generates demand for narrow-body tow tractors rated for high-frequency turnaround cycles. The country's federal civil aviation authority enforces apron safety standards aligned with ICAO guidelines while adapting OSHA-derived proximity-sensor requirements for Latin American operational contexts. Monterrey and Guadalajara emerge as secondary automation adoption nodes as handling agents consolidate multi-airport fleet management contracts.
America Airport Ground Handling Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with vertical integration into refrigeration and electro-hydraulic systems distinguishing premium-positioned players from component-focused competitors. The market structure stratifies into three strategic archetypes: diversified industrial conglomerates with captive aviation divisions, pure-play ground support equipment specialists, and automation-focused technology entrants targeting autonomous apron operations. Competitive moves concentrate on backward integration into battery supply chains and strategic partnerships with 5G infrastructure providers to enable predictive maintenance platforms.
Among North American industrial conglomerates, John Bean Technologies Corporation and Oshkosh Aerotech exemplify the integrated-leader archetype through their diversified equipment portfolios spanning refrigeration, cargo loading, and specialized vehicle platforms. TUG Technologies Corporation and Tronair, Inc. occupy positions within the specialist tier, with company names signaling focused engineering heritage in tow tractor and ground power unit categories. Cavotec SA and Mototok International GmbH represent the automation-focused entrant pattern, their geographic suffixes indicating European origination while their market presence anchors the electrified and autonomous equipment vector. BEUMER Group A/S exemplifies the materials-handling conglomerate archetype extending into aviation logistics through automated conveyor and sorting systems.
| Leading Market Players |
|---|
| John Bean Technologies Corporation |
| TUG Technologies Corporation |
| Cavotec SA |
| Tronair, Inc. |
| BEUMER Group A/S |
| Mototok International GmbH |
| Oshkosh Aerotech |
| Alliance Ground International |
| Swissport International |
| Others |
Value Chain & Pricing Dynamics
Electric motor substitution for diesel powertrains is simultaneously redrawing supplier geography toward Asian battery manufacturers and compressing margin structures for North American equipment assemblers. This input transition concentrates pricing power with cell producers while forcing handlers to absorb technology premiums or defer fleet renewal.
Pricing Analysis
After-sales service contracts and spare parts availability drive lifetime value capture across ground support equipment portfolios. Three-tier pricing structure across premium automation-ready, standard electric, and economy diesel tiers reflects certification grade and integration complexity. Pricing pressure stems from lithium-ion cell supply bottlenecks and extended procurement lead times. Regional ground handlers with thin margin profiles exhibit highest price sensitivity, while Tier 1 airport authorities prioritize uptime reliability over unit cost.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell production for electric tugs and ground power units. North American equipment assemblers draw from these sources for battery packs, power electronics, and thermal management systems. Single-source vulnerability concentrates in cathode active material processing. Distribution runs through OEM direct sales for major airport authorities and specialized handling agents, with regional distributors serving secondary facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 65 certified aviation electricians represent the critical skill gap constraining maintenance capacity expansion, with vocational program output lagging equipment deployment timelines across American hubs.
For Market Incumbents: Fortify backward integration into battery pack assembly and thermal management systems to offset Asian cell supplier pricing power. Deepen captive maintenance service networks to capture recurring revenue streams as electrified fleets expand. Automation-focused entrants threaten established pricing structures through equipment-as-a-service leasing models. For New Entrants and Emerging Players: Lead with hybrid platform leasing offerings targeting mid-size ground handling agents in Canadian prairie airports and Brazilian cargo hubs. Underpenetrated facilities in Calgary, Edmonton, and Campinas lack integrated handling infrastructure. Position around 5G-enabled predictive maintenance as a differentiated value proposition against legacy equipment tracking systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed handling agents consolidating multi-airport contracts across the southeastern United States. Long-term viability hinges on electrification compliance positioning and software integration capabilities. Watch for FAA emission mandate acceleration as the inflection signal triggering replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captures margin from Asian cell suppliers while securing supply continuity for electric tug production. |
| 5G-Enabled Predictive Maintenance Platform | Reduces unplanned downtime for narrow-body fleets through real-time component telemetry monitoring. |
| Equipment-as-a-Service Leasing Model | Bypasses capex barriers for mid-size ground handlers while generating recurring revenue streams. |
| Certified Technician Training Program | Addresses FAA Part 65 electrician shortages constraining maintenance capacity at electrified hubs. |
| Autonomous Apron Operations Deployment | Compresses labor deployment at congested gates through single-operator oversight of multiple units. |
Study Parameters
Desk research of FAA regulatory filings, OSHA safety standards, equipment manufacturer technical specifications, and airport authority procurement records preceded structured interviews with ground handling operations directors, fleet maintenance managers, airport procurement officers, and aviation equipment distributors. Primary fieldwork captured operational constraints and technology adoption timelines. Secondary validation drew from customs trade data, SEC 10-K disclosures, and industry association reports. Bottom-up equipment deployment estimates and top-down airport infrastructure spending analysis were triangulated for convergence.
Variance decomposition across service type, technology tier, equipment category, and end-user segments structured the analytical framework. Modeled dimensions included automation readiness level, powertrain architecture, fleet size tier, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and infrastructure investment trajectories. Forecast inputs incorporated FAA emission compliance deadlines and ANVISA pharmaceutical certification expansion timelines.
Forecasts assume regulatory continuity in FAA Voluntary Airport Low Emissions program participation and OSHA powered industrial truck standards; material policy shifts would require re-modeling. Supply chain disruption from lithium-ion cell export restrictions or tariff escalation represents specific revision triggers. Recalibration cycles align with material shifts in fleet electrification mandates and autonomous equipment certification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Smart Airport Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Airport Baggage Conveyor System Market