
 Bird Detection System for Airports Market | 2026-2036
Bird Detection System for Airports Market Size, Share, and Industry Trends Forecast 2026-2036
Bird Detection System for Airports Market Insights
FAA wildlife hazard assessment mandates are recalibrating the cost-of-entry calculus for airport safety infrastructure. Volacom leverages its vertical integration in radar hardware to sustain pricing power across European installations. Xsight Systems Ltd anchors its position through specialized runway surveillance deployments at tier-one aviation hubs. Robin Radar Systems differentiates via machine-learning-enhanced tracking algorithms that reduce false-positive rates during peak traffic windows.
Bird detection systems for airports integrate multi-spectral sensors, typically combining X-band or S-band radar with thermal imaging arrays operating in the 8-14 micrometer wavelength range, to identify avian targets at distances exceeding five nautical miles and trigger automated alert protocols for air traffic controllers. Fixed installations dominate current revenue pools due to their integration with permanent airfield infrastructure, while mobile units represent the fastest-expanding deployment category as smaller regional airports seek flexible, capital-light alternatives. Machine learning segments command premium positioning owing to adaptive classification algorithms that improve detection accuracy across varying weather and terrain conditions.
The FAA, EASA, and ICAO standards collectively shape product certification requirements, airworthiness directives, and cross-border interoperability protocols that determine vendor market access. National regulators in Canada and Australia have begun harmonizing their wildlife strike reporting thresholds with FAA guidelines, compressing procurement cycles for compliant detection platforms. Stakeholders must monitor evolving mandates on automated response integration and real-time data sharing between airport operators and national aviation authorities.
Market Dynamics
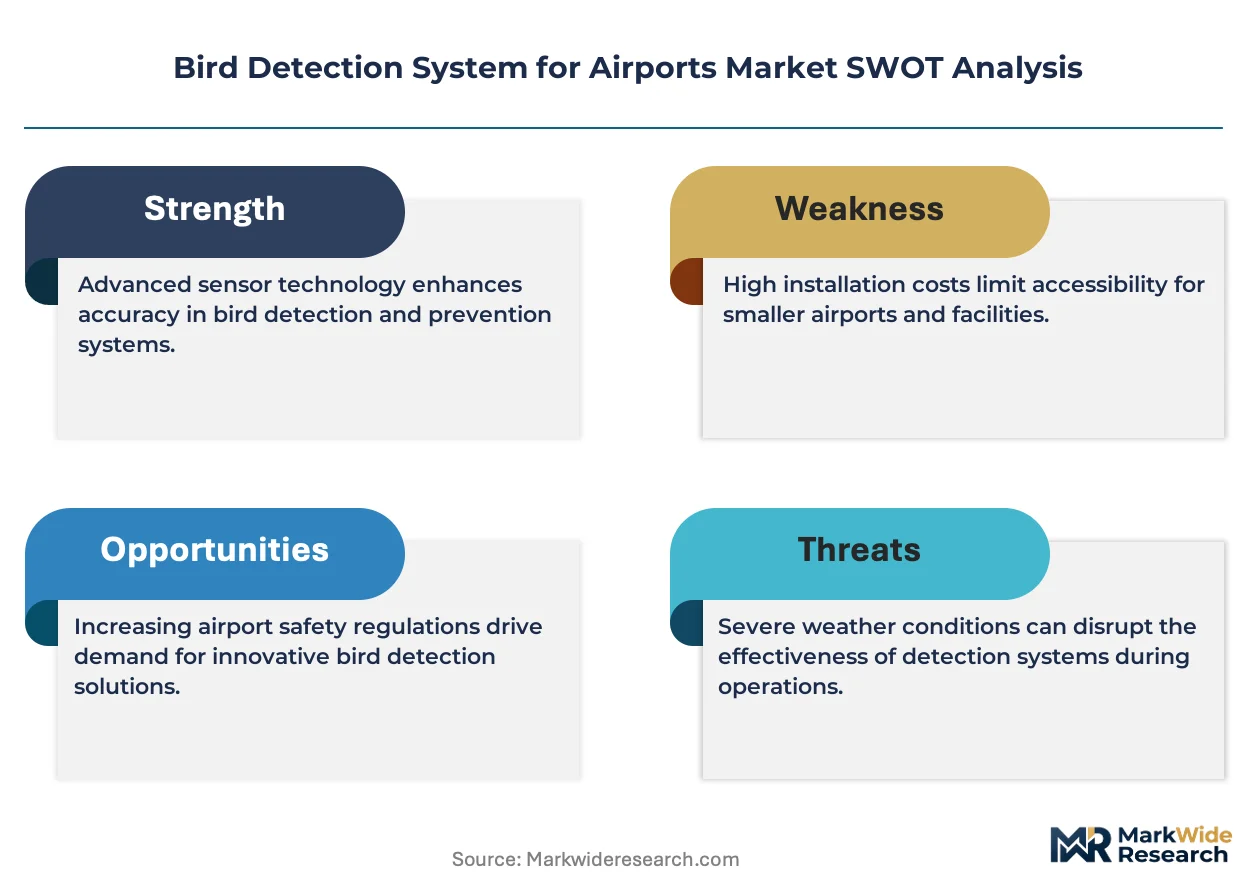
FAA wildlife hazard assessment mandates are compressing procurement timelines for commercial airports, forcing rapid infrastructure upgrades while machine learning classification algorithms reshape competitive differentiation among detection system vendors.
Growth Catalysts
- ICAO wildlife strike reporting harmonization:National aviation authorities in Canada and Australia are aligning strike thresholds with FAA guidelines, accelerating cross-border standardization of detection platform requirements.
- Regional airport fleet expansion:Secondary aviation hubs across the United States are deploying mobile radar-thermal units to satisfy escalating passenger throughput without permanent infrastructure commitments.
- Multi-spectral sensor fusion:Integration of X-band radar with 8-14 micrometer thermal imaging arrays is extending detection ranges beyond five nautical miles, satisfying controller demand for earlier alert generation.
Market Restraints
- Specialized radar component concentration:X-band and S-band transmitter supply concentrates among a limited pool of defense-electronics contractors, exposing procurement schedules to aerospace priority allocation.
- Machine learning training data scarcity:False-positive reduction algorithms require region-specific avian behavior datasets that remain fragmented across national wildlife research institutions.
- Airport capital allocation competition:Runway safety budgets face sustained pressure from air traffic control modernization and terminal expansion programs at tier-one hubs.
Strategic Opportunities
- Drone detection convergence:Dual-use platforms combining bird and unmanned aerial vehicle tracking are expanding into airspace security contracts at critical infrastructure adjacent to airports.
- Real-time data sharing mandates:FAA directives on automated response integration are creating openings for vendors with cloud-native alert distribution architectures.
- Mobile unit channel innovation:Equipment leasing and detection-as-a-service models are penetrating regional airport procurement where capital expenditure constraints previously blocked adoption.
Industry Challenges
- Radar-thermal calibration expertise gap:Field engineering talent capable of synchronizing multi-spectral sensor arrays across varying terrain and weather conditions remains scarce relative to deployment velocity.
- Legacy ATC integration complexity:Existing air traffic control display protocols require custom middleware development to ingest automated avian alerts without disrupting controller workflow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bird Detection System for Airports Market |
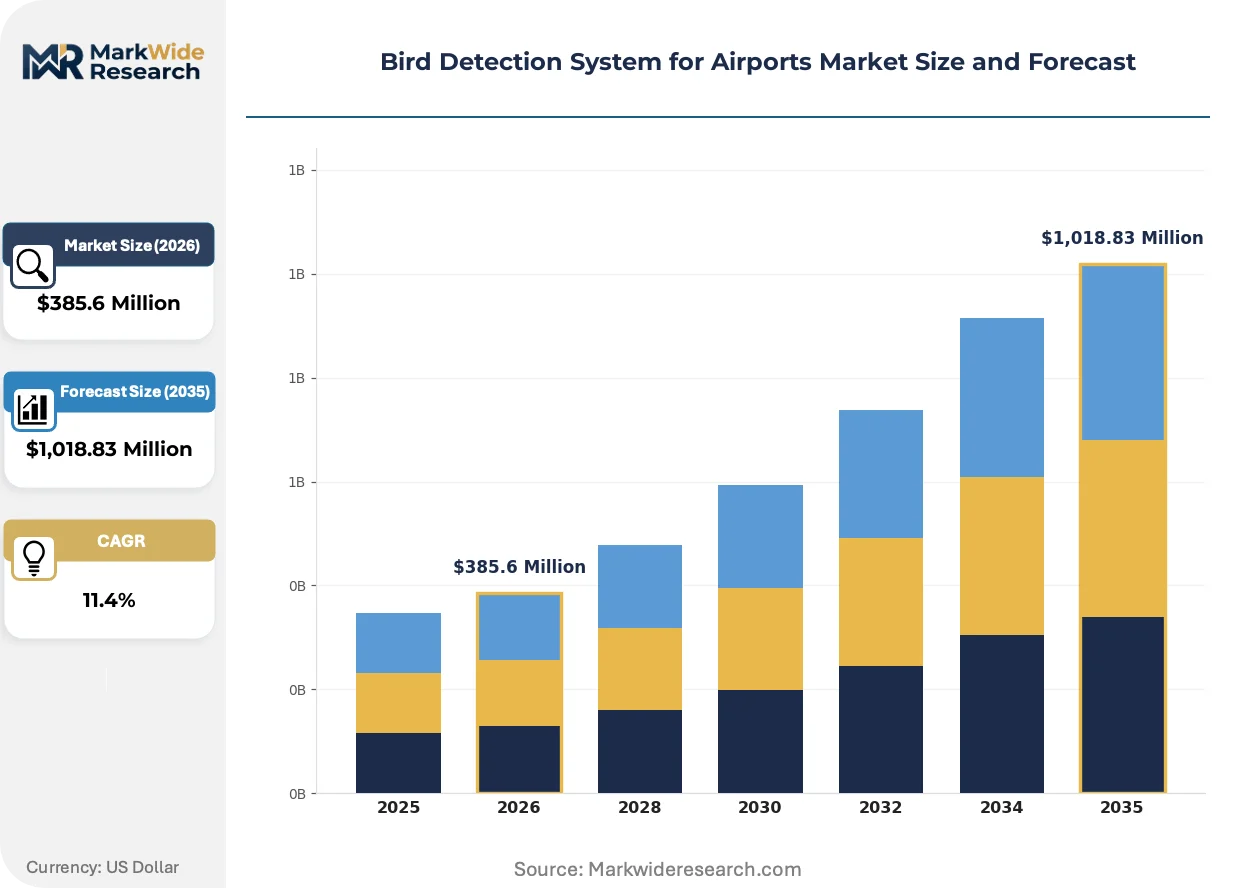
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Infrared Imaging, Acoustic Sensors, Machine Learning, Thermal Cameras Application: Wildlife Hazard Management, Runway Safety, Airspace Surveillance, Automated Warning Systems Deployment: Fixed Installations, Mobile Units, Remote Monitoring, Integrated Control Tower Systems End User: Airport Authorities, Aviation Safety Agencies, Wildlife Management Teams, Air Traffic Controllers |
| Companies Covered | Volacom, Bioseco, NEC Corporation, Xsight Systems Ltd, Bird Control Group, Robin Radar Systems, QinetiQ Group plc, DHI Group, DeTect Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bird Detection System for Airports Market Trends and Innovations
Machine learning-enhanced classification is displacing rule-based detection algorithms, while regulatory mandates on real-time data interoperability and mobile deployment flexibility are reshaping product architecture roadmaps across the vendor base.
Deep learning architectures for avian target classification are expanding into operational deployments at major commercial airports. Tier-one aviation hubs in the United States are adopting adaptive algorithms that self-optimize against local bird species and flight patterns. This capability compression is reducing manual threshold calibration requirements while tightening integration timelines with existing air traffic infrastructure.
EASA certification requirements for automated wildlife hazard detection systems are tightening validation protocols for multi-sensor fusion platforms. European installations must now demonstrate cross-border interoperability with neighboring national aviation authorities under harmonized ICAO guidelines. Vendors with pre-certified modular architectures are capturing procurement preference at airports in Germany, France, and the Netherlands.
Airport operators are unbundling detection hardware from long-term maintenance contracts, compressing vendor switching cycles and intensifying aftermarket service competition. Tier-two regional airports in the United States are piloting subscription-based sensor access models that transfer obsolescence risk to equipment providers. This procurement evolution is most visible in the southeastern United States, where rapid passenger growth strains legacy capital budgeting processes.
Bird Detection System for Airports Market Segmentation
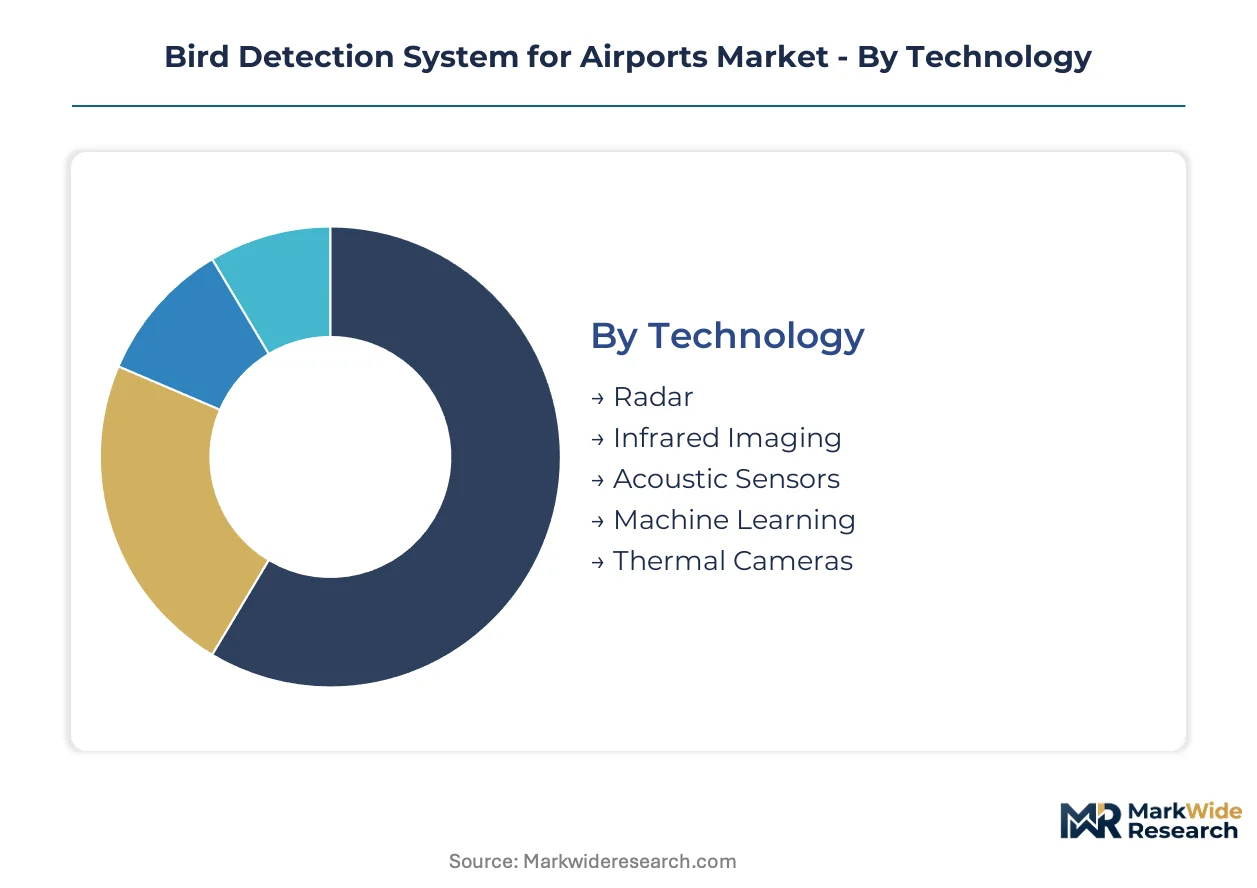
Segmentation in bird detection systems reflects divergent procurement priorities across airport infrastructure tiers. Technology choices determine detection range and false-positive performance, while deployment models separate capital-intensive hubs from flexible regional operators.
Technology:
Sensor modality selection dictates integration complexity and regulatory compliance pathways for airfield operators.
- Radar:X-band and S-band transmitters generate returns from avian targets beyond five nautical miles, with signal processing pipelines filtering clutter from weather and terrain. Demand concentrates at tier-one United States airports where FAA mandates require extended-range coverage for high-throughput runways.
- Infrared Imaging:8-14 micrometer wavelength arrays detect thermal signatures against ambient backgrounds, performing reliably in low-visibility conditions where radar suffers multipath interference. European installations under EASA guidelines favor hybrid radar-thermal fusion to satisfy cross-border interoperability requirements.
- Acoustic Sensors:Directional microphone arrays triangulate bird vocalizations for species-specific identification in supplement to optical methods.
- Machine Learning:Adaptive classification algorithms self-optimize against local avian behavior patterns, reducing manual threshold calibration.
- Thermal Cameras:Solid-state uncooled detectors provide maintenance-light alternatives to cryogenic infrared systems for mid-sized airfields.
Mature deployment sits with radar-dominant configurations. Newer deployment is concentrated in machine learning-enhanced sensor fusion architectures.
Application:
Functional use cases segment procurement budgets between reactive hazard response and predictive airspace management.
- Wildlife Hazard Management:Integrated platforms combining detection with deterrent activation—bio-acoustic dispersal, laser systems, or trained raptor programs—address the full strike prevention chain. United States airports facing FAA wildlife assessment deadlines allocate the largest capital shares to this category.
- Runway Safety:Perimeter-focused deployments prioritize immediate threat corridors where aircraft operate at critical flight phases. Regional airports in Australia align procurement with harmonized ICAO strike reporting thresholds.
- Airspace Surveillance:Wide-area monitoring extends beyond airport boundaries to approach and departure corridors.
- Automated Warning Systems:Direct controller alert integration bypasses human interpretation latency for time-critical responses.
Procurement volume clusters around wildlife hazard management. Steepest expansion trajectory belongs to automated warning systems with cloud-native alert distribution.
Deployment:
Physical installation models separate permanent infrastructure commitments from operational flexibility requirements.
- Fixed Installations:Permanent radar-thermal masts integrate with airfield electrical and data backbone, serving as the default for tier-one aviation hubs with predictable traffic profiles and multi-decade capital planning horizons.
- Mobile Units:Trailer-mounted or vehicle-integrated systems relocate across runway thresholds and taxiway complexes based on seasonal bird activity patterns. Secondary United States airports deploy these to satisfy passenger growth without permanent infrastructure commitments.
- Remote Monitoring:Satellite or cellular backhaul enables centralized oversight of distributed sensor networks.
- Integrated Control Tower Systems:Native display integration within existing ATC workstations reduces controller cognitive load.
Revenue concentration remains with fixed installations. Gaining share fastest are mobile units via equipment leasing and detection-as-a-service procurement models.
End User:
Stakeholder purchasing authority reflects organizational boundaries between airport operations, regulatory oversight, and field execution.
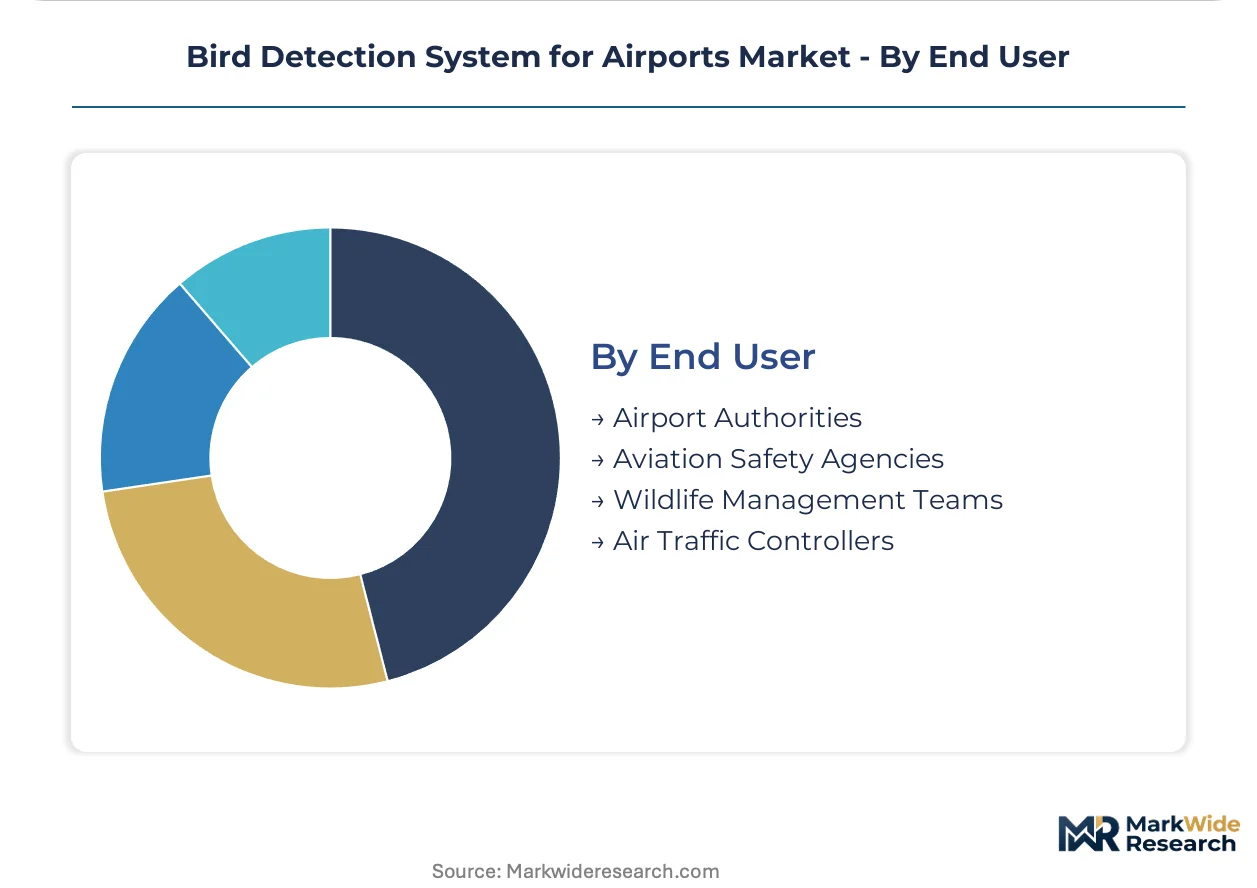
- Airport Authorities:Capital budget holders at commercial hubs direct procurement toward integrated multi-sensor platforms with decade-long service life expectations.
- Aviation Safety Agencies:National regulators including FAA and EASA shape certification requirements and compliance timelines that determine vendor market access.
- Wildlife Management Teams:Operational units prioritize handheld or vehicle-mounted detection tools for reactive dispersal missions.
- Air Traffic Controllers:End-users demand minimal-disruption alert formats compatible with existing display protocols.
Budget authority rests with airport authorities. Emerging influence concentrates in aviation safety agencies mandating real-time data sharing architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates concentrate aerospace testing infrastructure, attracting radar-thermal integration facilities serving Gulf Cooperation Council airports. Tax-advantaged manufacturing parks in Shenzhen and Chengdu anchor thermal sensor component production for Asia-Pacific distribution networks.
United States
FAA wildlife hazard assessment mandates compress procurement timelines for commercial airports nationwide. The Airport Improvement Program channels federal funding toward runway safety infrastructure at tier-one hubs. Dallas-Fort Worth International Airport deploys integrated radar-thermal arrays across multiple runway complexes, establishing operational benchmarks for high-throughput facilities.
Germany
EASA certification requirements for automated wildlife hazard detection tighten validation protocols for multi-sensor fusion platforms. The EU Green Deal accelerates procurement of energy-efficient thermal imaging systems at major aviation hubs. Frankfurt Airport's perimeter surveillance upgrades exemplify harmonized ICAO interoperability standards across neighboring national aviation authorities.
United Arab Emirates
Dubai South Free Zone tax incentives concentrate aerospace testing infrastructure for Middle East and Africa markets. The General Civil Aviation Authority mandates real-time wildlife hazard reporting for all commercial airports. Abu Dhabi International Airport's integrated control tower systems demonstrate cloud-native alert distribution architectures compliant with emerging data-sharing directives.
Australia
Harmonized ICAO strike reporting thresholds align national wildlife hazard protocols with FAA guidelines. The Civil Aviation Safety Authority accelerates procurement cycles for compliant detection platforms at secondary aviation hubs. Sydney Kingsford Smith Airport's mobile radar-thermal deployments address seasonal bird activity patterns across multiple runway thresholds.
Canada
Transport Canada harmonizes wildlife strike reporting thresholds with FAA guidelines, compressing procurement timelines for detection platforms. The National Airport System funding program supports runway safety infrastructure at designated facilities. Toronto Pearson International Airport's perimeter surveillance installations demonstrate integrated deterrent activation systems for full strike prevention chains.
Bird Detection System for Airports Market Competitive Landscape
Israeli producers anchor one tier; Dutch specialists hold differentiated positions in machine-learning-enhanced tracking. The vendor base structures around defense-electronics heritage, radar-thermal fusion expertise, and software-centric classification platforms. Three archetypes dominate: vertically integrated hardware manufacturers, algorithm-focused detection specialists, and diversified aerospace conglomerates with airfield safety divisions. M&A activity concentrates on sensor fusion capabilities, while strategic partnerships target cloud-native alert distribution architectures.
Within the radar-hardware tier, Volacom exemplifies vertically integrated production control. Xsight Systems Ltd and Robin Radar Systems occupy positions in specialized runway surveillance and machine-learning classification respectively. These three entities represent distinct competitive vectors: captive supply chain management, permanent infrastructure integration, and adaptive algorithm development for false-positive reduction.
| Leading Market Players |
|---|
| Volacom |
| Bioseco |
| NEC Corporation |
| Xsight Systems Ltd |
| Bird Control Group |
| Robin Radar Systems |
| QinetiQ Group plc |
| DHI Group |
| DeTect Inc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FAA-compliant integrated platforms and non-certified component systems manifests in both pricing premiums and supply chain sourcing patterns. Tier-one United States airports absorb 40-60% cost premiums for EASA-validated multi-sensor fusion architectures, while procurement teams at secondary hubs exploit component modularity to compress capital outlays through spot-market thermal camera sourcing.
Pricing Analysis
Short lead-time premiums of 15-25% apply to X-band radar transmitter procurement from defense-electronics contractors facing aerospace priority allocation queues. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier, with machine-learning-enhanced platforms commanding brand premiums over rule-based alternatives. Cost compression in the mobile unit category is intensifying because regional airports are aggregating demand through equipment leasing consortia. Wildlife management teams exhibit highest price sensitivity due to handheld tool budget constraints, while airport authorities demonstrate lowest sensitivity for integrated control tower systems.
Supply Chain Analysis
Regional distribution centers in the Netherlands and United States anchor hub-and-spoke fulfillment patterns for radar-thermal fusion components. Manufacturing concentrates in Israel for radar hardware, the Netherlands for machine-learning software stacks, and China for uncooled thermal detector arrays. Component dependencies include gallium nitride semiconductors for radar transmitters, germanium lenses for infrared optics, and edge-computing processors for classification algorithms. Single-source vulnerability sits with X-band transmitter foundries serving dual-use aerospace markets. Distribution runs through authorized system integrators holding FAA certification credentials for airfield installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into radar transmitter production and captive supply of thermal sensor arrays defines the current vertical-integration race among detection system vendors. Players pursuing upstream control over gallium nitride foundry capacity secure procurement priority allocation during defense-sector demand spikes.
For Market Incumbents: Deploy machine-learning training data network effects to deepen algorithmic moats against software-centric entrants. Consolidate position through exclusive partnerships with national wildlife research institutions for region-specific avian behavior datasets. Counter the threat of cloud-native alert distribution startups by embedding middleware directly into legacy ATC display protocols at tier-one United States airports. For New Entrants and Emerging Players: Secondary aviation hubs in the southeastern United States represent an underserved buyer archetype receptive to detection-as-a-service procurement models. Penetrate this segment through seasonal mobile unit leasing contracts that transfer obsolescence risk from capital-constrained operators. Target wildlife management teams with handheld acoustic-laser hybrid tools for reactive dispersal missions underserved by permanent infrastructure vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified aerospace conglomerates seeking airfield safety division expansion. Long-term viability hinges on regulatory harmonization durability across FAA-EASA-ICAO certification frameworks. Watch for inflection signals in real-time data sharing mandate implementation timelines, as cloud-native architectures gain procurement preference over legacy on-premise systems.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Capability Acquisition | Machine-learning-enhanced tracking algorithms reduce false-positive rates during peak traffic windows at tier-one hubs. |
| Cloud-Native Alert Distribution Development | FAA directives on automated response integration favor vendors with API-first architectures for real-time data sharing. |
| Mobile Unit Leasing Model Launch | Equipment-as-a-service penetration addresses capital expenditure constraints at regional United States airports. |
| Defense-Electronics Contractor Partnership | X-band transmitter supply agreements secure priority allocation against aerospace sector demand competition. |
| EASA Pre-Certification Investment | Modular validation protocols accelerate procurement preference at German, French, and Dutch aviation hubs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with airport operations directors, air traffic control integration specialists, wildlife management team leads, and radar-thermal system field engineers combined with FAA wildlife strike database extracts and EASA certification registries. Bottom-up triangulation across deployment model, technology modality, and airport infrastructure tier dimensions validated top-down market sizing from aviation authority procurement disclosures.
Granularity-level modeling distinguished fixed installation from mobile unit deployment economics, machine-learning-enhanced from rule-based detection performance tiers, and tier-one hub from regional airport procurement cycles across the analysis window. CAGRs derived from logistic diffusion curves fitted to regulatory mandate implementation timelines and airport capital budget allocation patterns. Forecast inputs incorporated X-band radar transmitter lead-time volatility and thermal sensor component price trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to defense-electronics priority allocation shifts and ICAO harmonization adoption lags. Forecasts reflect documented assumptions on regulatory compliance deadlines and technology substitution thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Middle-East and Africa Airport Ground Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Smart Airport Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Europe Airport Ground Handling Systems Market