
 Airport Baggage Conveyor System Market | 2026-2036
Airport Baggage Conveyor System Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Baggage Conveyor System Market Insights
ICS 9000-grade reliability certification is collapsing the competitive field toward suppliers with proven mean-time-between-failures records above 50,000 hours. Daifuku leverages its captive manufacturing of precision drive components to guarantee uptime commitments. Siemens anchors European upgrade cycles through integrated IoT-enabled predictive maintenance platforms. Vanderlande dominates tilt-tray sorter deployments at tier-one hub airports across Asia-Pacific and Middle Eastern markets.
An airport baggage conveyor system comprises motorized belt, roller, chain, and modular conveyor arrays integrated with automated sortation mechanisms, typically operating at speeds between 0.5 and 2.5 meters per second with load capacities exceeding 75 kilograms per linear meter. These systems route checked luggage from check-in counters through security screening to departure gates and arrival carousels, replacing manual cart-based transport with continuous-flow mechanized handling. Belt conveyors sustain the largest installed base due to lower capital thresholds and retrofit compatibility, while cross-belt sorters capture the fastest expansion as airports pursue sub-60-second connection bag processing. RFID tracking technology leads technology segment value pools because tag infrastructure supports end-to-end custody visibility mandated by IATA Resolution 753 compliance deadlines.
The Federal Aviation Administration enforces airfield equipment safety standards through AC 150/5220 specifications that govern conveyor electrification and fire suppression integration on airport ramps. The European Union's CE marking and Machinery Directive frameworks compel OEMs to certify emergency stop architectures and worker-safety guarding before intra-EU commercialization. Stakeholders must monitor evolving IATA baggage tracking mandates and national carbon-reduction targets for airport ground support equipment, as these dual pressures will determine which conveyor architectures qualify for future infrastructure financing.
Market Dynamics
The EU's F-Gas Regulation is compressing equipment replacement cycles across European hubs, forcing airport operators to retire refrigerant-dependent pneumatic actuators and accelerate capital deployment into electrified conveyor architectures before mandated phase-out deadlines.
Growth Catalysts
- RFID Mandate Compliance:IATA Resolution 753 requires end-to-end baggage tracking visibility, compelling airports to retrofit conveyor infrastructure with integrated tag readers and sensor networks.
- Hub Modernization Programs:Germany's Frankfurt and Munich airports are expanding automated sortation capacity to handle connection traffic below 60-second processing thresholds.
- Energy Efficiency Standards:The EU Green Deal's carbon-reduction targets for ground support equipment are channeling infrastructure financing toward low-GWP motor systems and regenerative drive technologies.
Market Restraints
- Precision Component Supply Concentration:Captive manufacturing of drive components by dominant system integrators limits second-source availability for airport maintenance teams.
- Copper and Rare Earth Volatility:Conveyor motor windings and permanent magnet rotors face input cost swings tied to concentrated mining jurisdictions.
- Legacy Electrification Conflicts:AC 150/5220 specifications governing airport ramp equipment create compliance friction when integrating IoT-enabled predictive maintenance platforms with existing fire suppression architectures.
Strategic Opportunities
- Cross-Belt Sorter Deployment:Tier-one hub airports in Asia-Pacific and Middle Eastern markets present white space for sub-60-second connection bag processing systems.
- Predictive Maintenance Convergence:Integration of IoT sensor networks with machine learning analytics enables uptime guarantees above 50,000-hour mean-time-between-failures benchmarks.
- Retrofit Channel Expansion:Belt conveyor installed base compatibility creates aftermarket revenue streams through modular upgrade kits rather than greenfield replacement.
Industry Challenges
- ICS 9000 Certification Timeline:Reliability verification above 50,000 hours extends product development cycles and compresses competitive entry for emerging suppliers.
- Legacy System Integration Complexity:Tilt-tray sorter deployments at established hubs require custom engineering to interface with existing carousel and belt conveyor arrays without operational disruption.
- Specialized Technician Scarcity:Automated sortation mechanism maintenance demands expertise spanning mechanical drive systems, pneumatic controls, and networked sensor diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Baggage Conveyor System Market |
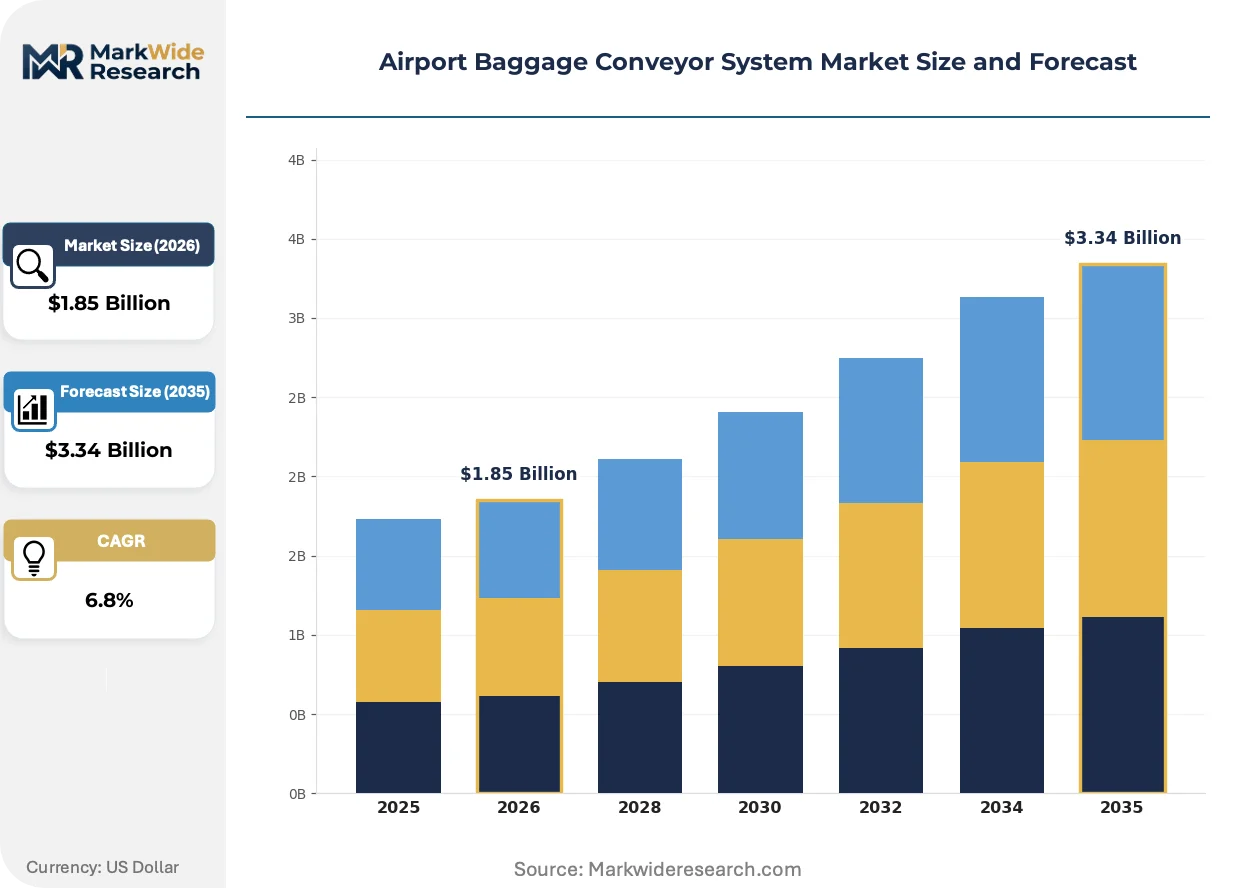
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Conveyors, Belt Conveyors, Roller Conveyors, Chain Conveyors, Tilt-Tray Sorters, Cross-Belt Sorters Technology: RFID Tracking, Barcode Scanning, IoT Integration, Automated Controls, Vision Systems, Pneumatic Systems Application: Baggage Handling, Cargo Sorting, Security Screening, Check-in Sorting, Loading Systems, Passenger Services End User: Airport Operators, Ground Handling Companies, Airlines, Aviation Service Providers, Cargo Handlers, Airport Maintenance Teams |
| Companies Covered | Daifuku, JBT Corporation, Siemens, G&S Airport Conveyor, Fives, Vanderlande, Intelligrated, ULMA Group, BEUMER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Baggage Conveyor System Market Trends and Innovations
Active sensor miniaturization and edge computing deployment are compressing fault-detection latency from minutes to seconds, while regulatory pressure on refrigerant-based systems accelerates architectural shifts toward fully electrified handling infrastructure.
RFID inlay technology is miniaturizing tag dimensions while extending read-range reliability, enabling single-tag baggage tracking from check-in through arrival carousel without secondary barcode verification. Tier-one hub airports in Asia-Pacific are deploying these reduced-form-factor tags at scale to eliminate manual sortation interventions. The structural consequence is collapsing tracking infrastructure cost per bag and enabling tier-two airports to justify full IATA Resolution 753 compliance.
The EU's F-Gas Regulation mandates phased reduction of hydrofluorocarbon refrigerants in pneumatic conveyor actuators, compelling OEMs to certify all-electric drive alternatives before intra-EU commercialization deadlines. Industrial consequence includes accelerated R&D allocation toward servo motor architectures and regenerative braking systems. Cross-belt sorter deployments face the most acute retrofit pressure, as these systems historically relied on pneumatic pusher mechanisms for high-speed diverting.
Airport operators are unbundling after-sales service contracts from initial equipment procurement, creating discrete revenue pools for predictive maintenance analytics and spare parts logistics. Traditional system integrators face channel disruption from specialized service firms offering uptime guarantees independent of hardware origin. This behavioral shift is most visible in German-speaking Europe, where Frankfurt and Munich airports have separated ten-year maintenance obligations from capital equipment tenders.
Airport Baggage Conveyor System Market Segmentation
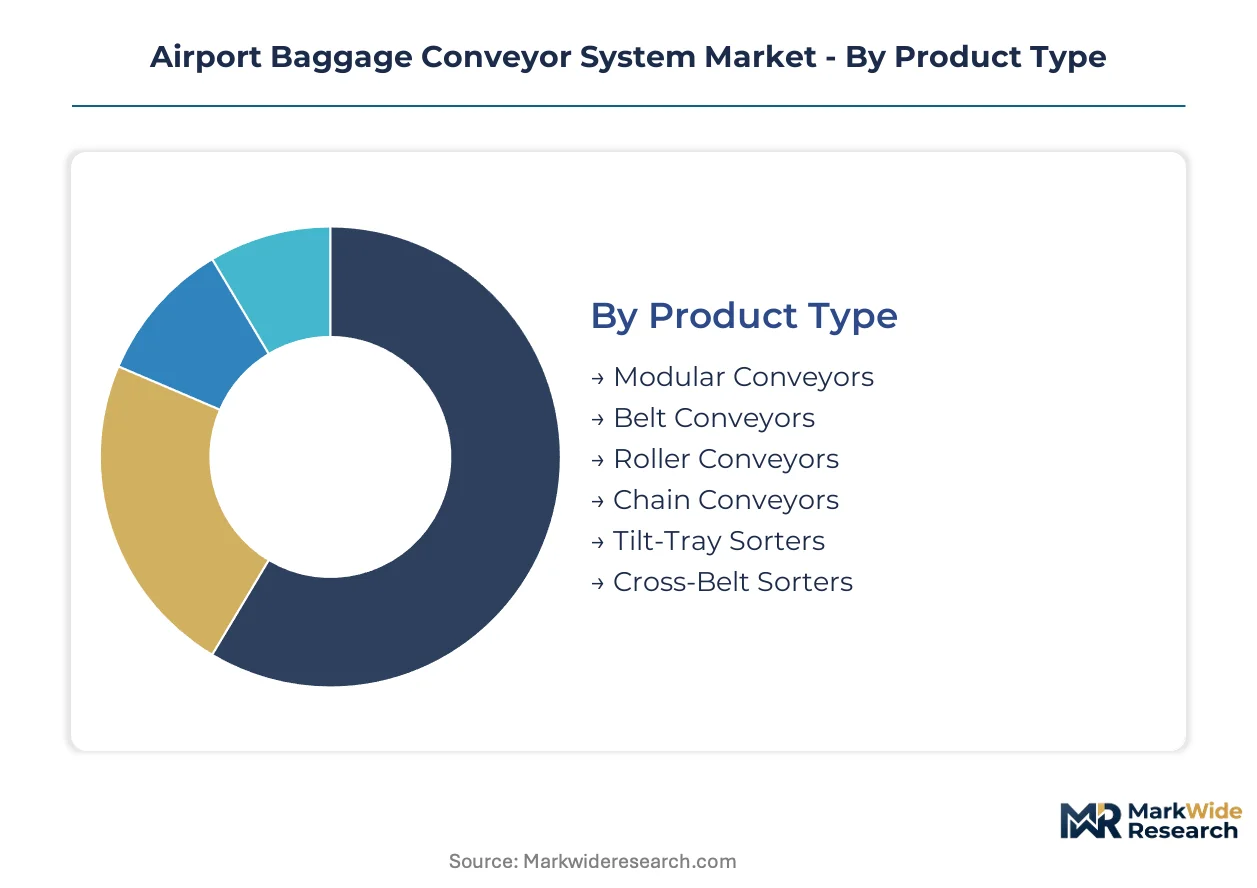
Conveyor architecture selection determines capital deployment scale and operational flexibility across hub modernization programs. Segmentation reveals how technology tiers and user types concentrate procurement authority and maintenance obligations differently across airport ecosystems.
Product Type:
Belt and roller systems dominate domestic retrofit channels across established European hubs, while tilt-tray and cross-belt sorters concentrate in export-led greenfield deployments across Asia-Pacific and Middle Eastern markets.
- Belt Conveyors:Continuous fabric or rubber belts transport luggage at 0.5 to 2.5 meters per second with load capacities exceeding 75 kilograms per linear meter. Frankfurt and Munich airports specify these for retrofit compatibility with existing carousel infrastructure, constrained by fire suppression integration requirements under AC 150/5220.
- Cross-Belt Sorters:Orthogonal belt arrays enable sub-60-second connection bag processing through high-speed diverting at sortation junctions. Tier-one hubs in the United Arab Emirates and Saudi Arabia deploy these for passenger transfer traffic volumes exceeding 10 million annual connections.
- Modular Conveyors:Interchangeable aluminum or steel frame sections support rapid reconfiguration for seasonal capacity adjustments.
- Roller Conveyors:Gravity or motorized roller arrays handle irregular cargo dimensions and outsized baggage categories.
- Chain Conveyors:Heavy-duty link chains manage palletized cargo and unit load devices in integrated baggage-cargo facilities.
- Tilt-Tray Sorters:Pneumatic or electric tray tilting mechanisms discharge luggage at programmable destinations.
Belt conveyors hold the largest share; momentum sits with cross-belt sorters.
Technology:
RFID and IoT integration command premium pricing tiers due to IATA Resolution 753 compliance mandates, while barcode scanning and pneumatic systems occupy cost-sensitive retrofit segments with shorter replacement cycles.
- RFID Tracking:Miniaturized inlay tags enable single-tag custody visibility from check-in through arrival carousel without secondary verification. Germany's Fraport and Munich Airport Group deploy these at scale to eliminate manual sortation interventions and meet baggage tracking deadlines.
- IoT Integration:Edge computing nodes and predictive analytics platforms compress fault-detection latency from minutes to seconds. Daifuku and Siemens anchor European upgrade cycles through uptime guarantees exceeding 50,000-hour mean-time-between-failures benchmarks.
- Barcode Scanning:Laser or camera-based optical character recognition supports legacy infrastructure compatibility at tier-two airports.
- Automated Controls:Programmable logic controllers and distributed sensor networks manage conveyor speed synchronization and load balancing.
- Vision Systems:Camera arrays detect baggage anomalies and security threats without manual screening intervention.
- Pneumatic Systems:Compressed air actuators face accelerated phase-out under EU F-Gas Regulation mandates for hydrofluorocarbon reduction.
RFID tracking commands the dominant value pool; IoT integration is climbing the fastest.
Application:
Baggage handling and check-in sorting concentrate procurement volume at major hub operators, while cargo sorting and security screening applications fragment across ground handling contractors and specialized service providers.
- Baggage Handling:Integrated conveyor arrays route checked luggage from check-in counters through security screening to departure gates and arrival carousels. Frankfurt Airport's Terminal 3 expansion specifies these systems for 25 million annual passenger capacity additions.
- Check-in Sorting:Early bag storage and outbound flight assignment algorithms optimize conveyor utilization during peak departure banks. Munich Airport's automated sortation capacity expansion targets connection processing below 60-second thresholds.
- Cargo Sorting:Unit load device handling and mail parcel processing require modified load capacities and dimensional tolerances.
- Security Screening:Explosive detection system integration and hold baggage screening compliance mandate conveyor modifications for CT scanner compatibility.
- Loading Systems:Aircraft container and pallet loading bridges interface with apron conveyor networks.
- Passenger Services:Self-service bag drop and reclaim carousel systems reduce ground handling labor intensity.
Baggage handling captures the largest deployment base; check-in sorting shows steepest expansion trajectory.
End User:
Airport operators and ground handling companies control capital procurement decisions, while airlines and maintenance teams influence specifications through operational requirements and aftermarket service demand.
- Airport Operators:Frankfurt Airport, Munich Airport, and comparable hub authorities specify integrated system architectures and negotiate ten-year maintenance obligations separately from capital equipment tenders. These entities prioritize ICS 9000-grade reliability certification and EU Green Deal carbon-reduction compliance.
- Ground Handling Companies:Swissport, dnata, and comparable service providers operate conveyor infrastructure under concession agreements with airport authorities. Their procurement concentrates on modular upgrade kits and predictive maintenance analytics to defend uptime guarantees.
- Airlines:Network carriers influence baggage tracking mandate compliance and connection time specifications.
- Aviation Service Providers:Specialized firms deliver predictive maintenance and spare parts logistics independent of hardware origin.
- Cargo Handlers:Integrated logistics operators manage dedicated freight conveyor segments at combined passenger-cargo facilities.
- Airport Maintenance Teams:In-house technical staff demand second-source availability for precision drive components and networked sensor diagnostics.
Airport operators dominate capital allocation; ground handling companies are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import demand for automated baggage handling infrastructure exceeds export capacity from established manufacturing bases, redirecting capital flows toward regional assembly partnerships and localized service networks. Germany and the United States maintain net exporter positions in precision drive components, while Asia-Pacific and Middle Eastern markets absorb the majority of finished system deployments.
Germany
Frankfurt and Munich airports anchor European demand through terminal expansion programs targeting sub-60-second connection processing. The EU F-Gas Regulation accelerates replacement of refrigerant-dependent pneumatic actuators with electrified conveyor architectures. Bavaria's industrial corridor hosts captive manufacturing of precision drive components serving hub modernization tenders across the continent.
United States
AC 150/5220 specifications from the FAA govern conveyor electrification and fire suppression integration, creating compliance thresholds for IoT-enabled predictive maintenance platforms. Dallas-Fort Worth and Atlanta Hartsfield-Jackson drive retrofit demand as legacy belt systems approach end-of-life cycles. Domestic assembly capacity concentrates in the Midwest industrial belt to serve North American airport operator procurement.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International airports deploy cross-belt sorters for passenger transfer volumes exceeding 10 million annual connections. The country's national aviation regulator mandates ICS 9000-grade reliability certification for ground support equipment tenders. Jebel Ali industrial zone hosts regional service hubs for Middle Eastern hub modernization programs.
China
Beijing Daxing and Shanghai Pudong airports expand automated sortation capacity under national dual carbon goals for ground support equipment. The Ministry of Ecology and Environment enforces energy-efficiency standards for conveyor motor systems in new airport construction. Yangtze River Delta manufacturing clusters supply belt conveyor components for domestic retrofit channels and Southeast Asian export markets.
Saudi Arabia
NEOM and King Abdulaziz International airport developments specify integrated baggage handling infrastructure for greenfield passenger capacity additions. The Saudi Food and Drug Authority and national aviation regulator coordinate equipment safety certification timelines. Riyadh-based engineering firms broker technology transfer agreements with European system integrators for localized assembly capacity.
Airport Baggage Conveyor System Market Competitive Landscape
Concentration sits with system integrators possessing captive manufacturing of precision drive components and proven uptime guarantee capabilities. The competitive field compresses toward suppliers with ICS 9000-grade reliability verification above 50,000 hours mean-time-between-failures. Three archetypes dominate: vertically integrated industrial conglomerates with in-house component production, specialized airport automation firms with regional service networks, and diversified material handling providers leveraging cross-sector technology transfer. Dominant competitive moves include unbundling of after-sales service contracts from initial equipment procurement and geographic expansion through localized assembly partnerships.
Within the integrated industrial tier, Daifuku and Siemens exemplify archetypes combining captive drive component manufacturing with predictive maintenance platform deployment. Vanderlande occupies a position representing specialized airport automation expertise concentrated in tilt-tray and cross-belt sorter deployments. These three anchors demonstrate how reliability certification and service contract separation reshape procurement authority across tier-one hub airports.
| Leading Market Players |
|---|
| Daifuku |
| JBT Corporation |
| Siemens |
| G&S Airport Conveyor |
| Fives |
| Vanderlande |
| Intelligrated |
| ULMA Group |
| BEUMER Group |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing scale at Daifuku and Siemens compresses component cost floors while elevating reliability-premium capture for ICS 9000-certified systems. This concentration simultaneously hardens price resistance at the standard tier and widens spreads to premium electrified architectures demanded by EU F-Gas compliance deadlines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium ICS 9000-certified systems, standard belt conveyor retrofits, and economy-grade modular components. Price differentiation hinges on mean-time-between-failures certification grade and after-sales service bundling duration. Pricing pressure intensifies in the standard tier as Chinese manufacturers expand belt conveyor export capacity. Ground handling companies exhibit highest price sensitivity due to concession-margin constraints, while Frankfurt and Munich airport operators prioritize uptime guarantees over capital cost minimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate precision drive component procurement, though EU F-Gas Regulation phase-out timelines are forcing strategic stockpiling of electrified servo motor architectures. Supply concentrates in Germany for precision gearboxes, Japan for high-reliability servo motors, and China for belt conveyor structural components. Raw material dependencies span copper motor windings, rare earth permanent magnets, and aluminum frame extrusions. Single-source vulnerability concentrates in captive-manufactured drive components. Distribution runs through system integrator direct sales for greenfield projects and specialized service firms for aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport baggage conveyor demand is recovering through hub modernization cycles triggered by IATA Resolution 753 compliance deadlines and EU refrigerant phase-out mandates.
For Market Incumbents: Shield installed base relationships by unbundling predictive maintenance contracts from capital equipment tenders before specialized service firms capture aftermarket revenue pools. Accelerate captive manufacturing expansion into servo motor architectures to defend margin position against electrification transitions forced by EU F-Gas Regulation timelines. For New Entrants and Emerging Players: Lead with cross-belt sorter deployments at tier-two Asia-Pacific hubs where ICS 9000 certification requirements remain less stringent than Middle Eastern markets. Target white space in predictive maintenance analytics for legacy belt conveyor infrastructure. Pursue technology licensing agreements with European system integrators to bypass reliability verification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized airport automation firms with proven tilt-tray sorter deployment records and regional service networks. Long-term viability rests on electrification transition execution and predictive maintenance platform monetization. Watch for inflection when tier-one hubs unbundle ten-year maintenance obligations from capital tenders at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Captures unbundled service revenue pools as Frankfurt and Munich airports separate maintenance from equipment tenders. |
| Servo Motor Architecture Certification | Secures intra-EU commercialization eligibility before EU F-Gas Regulation phase-out deadlines. |
| Cross-Belt Sorter Geographic Expansion | Addresses sub-60-second connection processing demand at Dubai and Abu Dhabi tier-one hubs. |
| ICS 9000 Reliability Verification Investment | Collapses competitive field toward suppliers with proven mean-time-between-failures records above 50,000 hours. |
| Retrofit Channel Partnership Development | Monetizes belt conveyor installed base through modular upgrade kits rather than greenfield replacement cycles. |
Research Methodology
Desk research of IATA regulatory filings, EU F-Gas Regulation implementation schedules, and airport authority procurement databases preceded structured interviews with airport operations directors, ground handling procurement leads, system integrator sales executives, and aftermarket service firm technical directors. Primary fieldwork captured tender unbundling trends and predictive maintenance contract structures. Secondary validation drew from FAA AC 150/5220 specification updates, CE marking compliance records, and customs data on precision drive component trade flows. Bottom-up deployment modeling across hub modernization programs was triangulated against top-down infrastructure spending forecasts.
Variance decomposition across the projection horizon isolates volume drivers by conveyor architecture type, technology tier, and end-user procurement authority. Segmentation dimensions modeled include product type, technology integration level, application workflow, and end-user category. CAGRs were derived from installation base replacement cycles and greenfield capacity additions. Industry-specific inputs incorporate IATA Resolution 753 compliance deadlines and EU Green Deal carbon-reduction targets for ground support equipment.
The analysis sits within stated boundaries; outcomes outside sustained hub passenger traffic recovery or accelerated EU refrigerant phase-out timelines would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency and copper price stability. Revision becomes warranted when tier-one hub unbundling of maintenance contracts crosses threshold penetration or when rare earth supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Smart Airport Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
North America Airport Baggage Handling Systems Market