
 Aviation Beacons Technology Market | 2026-2036
Aviation Beacons Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Beacons Technology Market Analysis
Subscription-based remote monitoring and predictive maintenance software is realigning how aviation beacon systems generate recurring revenue alongside hardware sales. Honeywell International leverages its avionics integration expertise to bundle beacon diagnostics into broader airport management platforms. Astronics Corporation sustains competitive positioning through specialized power and lighting systems designed for harsh aerospace environments. Carmanah Technologies dominates solar-powered beacon segments with proprietary energy management architectures that reduce grid dependency for remote airfields.
Aviation beacons technology encompasses electroluminescent and xenon flash systems engineered to emit specified candela outputs within precise beam patterns, typically operating between 20 and 2,000 candela depending on obstacle height and ambient light conditions, with primary purpose of marking structures hazardous to air navigation. LED Beacons now lead product type segments due to operational longevity exceeding 50,000 hours and substantial energy reduction versus xenon alternatives. GPS-Based Systems represent the fastest-growing technology dimension as precision approach requirements drive integration with satellite augmentation networks. Fixed Installation categories anchor revenue stability through regulatory-mandated replacement cycles for permanent obstacle marking.
FAA obstruction lighting standards under AC 70/7460-1L and ICAO Annex 14 Volume I define mandatory photometric and flash characteristics for structures exceeding specified heights above ground level. EASA CS-ADR-DSN implements parallel certification pathways across European member states with additional electromagnetic compatibility requirements. Military Operations end users navigate MIL-STD-810 environmental testing protocols alongside FAA compliance for dual-use installations. Stakeholders must monitor evolving drone integration rules that will expand low-altitude beacon requirements beyond traditional manned aviation corridors.
Market Dynamics
LED retrofit mandates and satellite-based augmentation requirements are compressing replacement cycles for legacy xenon systems while expanding the addressable hardware base for precision approach infrastructure.
Growth Catalysts
- FAA AC 70/7460-1L photometric standards:Mandated candela output upgrades for structures exceeding 200 feet AGL are forcing systematic replacement of incandescent obstruction lighting across United States metropolitan air corridors.
- ICAO Annex 14 compliance deadlines:Member states face synchronized certification requirements for medium-intensity approach lighting systems, accelerating procurement for runway end identifier installations.
- Drone integration corridors:Low-altitude unmanned traffic management networks require supplemental beacon marking for vertiports and charging infrastructure below traditional manned aviation thresholds.
Market Restraints
- Aluminum and copper price volatility:Housing and heatsink material costs fluctuate with energy-intensive smelting output, compressing margin stability for fixture manufacturers.
- Optical component supply concentration:Precision lens and reflector fabrication clusters in East Asian manufacturing hubs create single-source vulnerability for beam pattern calibration.
- Xenon flash tube obsolescence:Declining production volumes for legacy high-voltage trigger components are extending lead times for spare parts in remote airfield installations.
Strategic Opportunities
- India regional airport expansion:UDAN scheme subsidies for underserved routes are generating greenfield demand for solar-compatible beacon systems at unelectrified airstrips.
- Power-over-Ethernet convergence:Integrated data and electrical transmission through CAT6 cabling enables remote diagnostics without separate control wiring infrastructure.
- EASA CS-ADR-DSN electromagnetic compatibility amendments:Stricter EMC testing protocols for LED drivers create certification barriers that favor established European subsystem suppliers.
Industry Challenges
- Photometric calibration technician shortage:Specialized expertise for candela measurement and beam spread verification is scarce outside major aviation maintenance hubs.
- Legacy control system integration:Existing airfield lighting circuit protocols require protocol translation hardware for modern addressable LED fixtures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Beacons Technology Market |
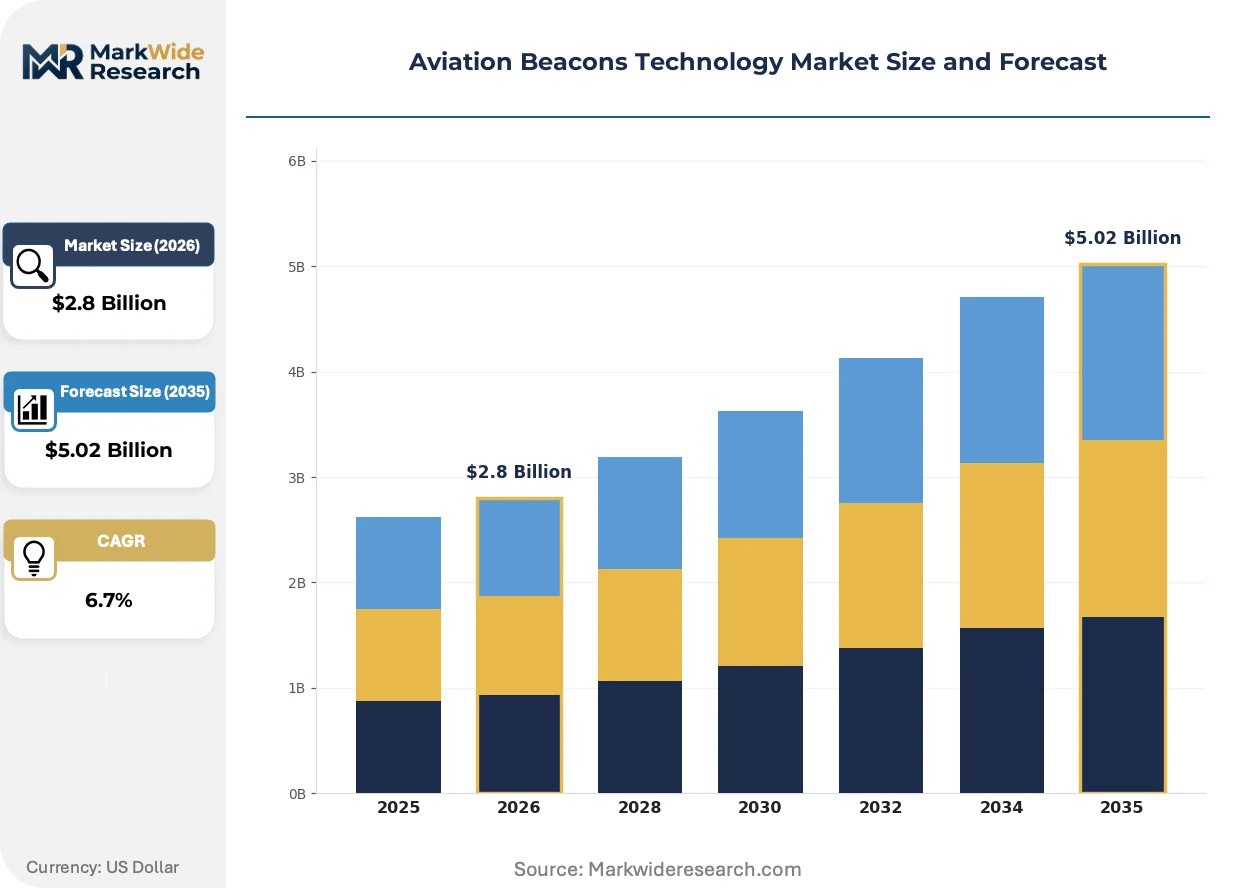
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Beacons, Xenon Beacons, Solar Beacons, Infrared Beacons End User: Aerospace Manufacturers, Airport Authorities, Military Operations, Drone Operators Installation: Fixed Installation, Portable Installation, Temporary Setup, Integrated Solutions Technology: Active Beacons, Passive Beacons, Hybrid Beacons, GPS-Based Systems |
| Companies Covered | Honeywell International, Astronics Corporation, Carmanah Technologies, Dialight, Hughey and Phillips, Point Lighting Corporation, Avlite Systems, Flash Technology, Obelux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Beacons Technology Market Emerging Trajectories
Autonomous monitoring architectures and solid-state illumination advances are restructuring how obstruction lighting systems are specified, procured, and maintained across civil and military installations.
Solar-hybrid beacon architectures with proprietary energy management firmware are decentralizing power infrastructure requirements for remote obstacle marking. Regional airport authorities in Australia and sub-Saharan Africa are deploying these systems at unelectrified sites. The technology is decentralizing grid dependency and enabling marking of previously uneconomical terrain features.
ICAO Annex 14 Volume I amendments addressing LED flicker characteristics and colorimetric stability are tightening type certification requirements for medium-intensity white obstruction lighting. European manufacturers face parallel EASA CS-ADR-DSN electromagnetic compatibility testing expansion. Military dual-use installations must now satisfy MIL-STD-810 environmental protocols alongside civil photometric standards, compressing supplier qualification timelines.
Subscription telemetry models are displacing capital-heavy upfront procurement for beacon system monitoring. Airport operators in the United States are piloting per-luminaire service contracts bundling hardware, cellular connectivity, and predictive maintenance algorithms. This reconfiguration is most visible across Federal Contract Tower facilities and municipal airport authorities with constrained maintenance staffing.
Aviation Beacons Technology Market Segmentation
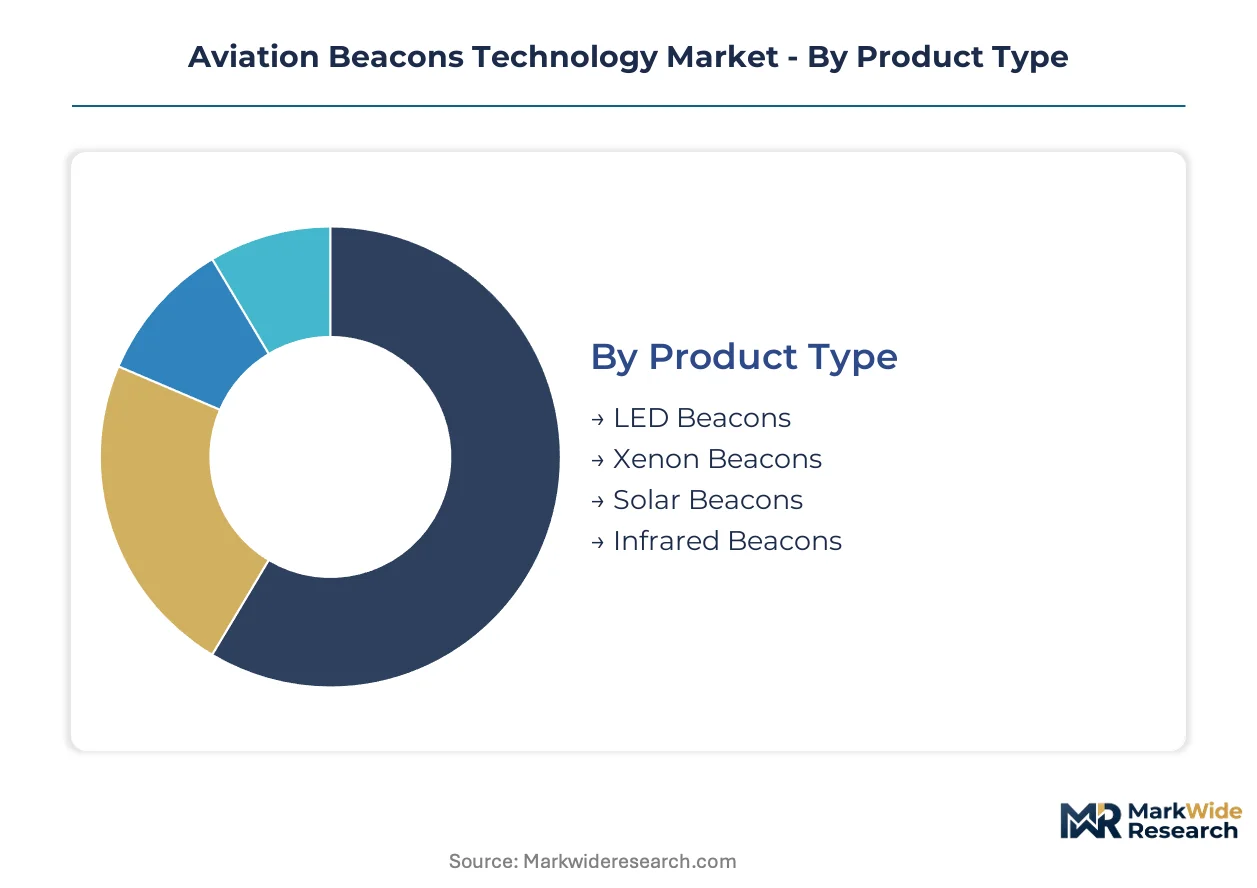
Aviation beacon procurement patterns diverge sharply across regulatory environments, energy infrastructure maturity, and operational tempo requirements. Understanding these fault lines reveals where technology substitution accelerates and where legacy systems retain defensive moats.
Product Type:
Energy cost exposure and maintenance access constraints separate buyers into distinct technology tiers.
- LED Beacons:Solid-state semiconductor arrays deliver candela outputs from 20 to 2,000 with operating lifespans exceeding 50,000 hours. Airport authorities across United States metropolitan air corridors are systematically replacing xenon installations to meet FAA AC 70/7460-1L photometric standards while reducing energy draw.
- Xenon Beacons:High-voltage discharge tubes produce intense flash patterns through gas ionization, historically dominant for high-intensity applications above 500 feet AGL. Spare parts availability is compressing as trigger component manufacturers exit, forcing early replacement at remote installations.
- Solar Beacons:Photovoltaic panels paired with lithium-ion storage and proprietary energy management firmware enable off-grid obstacle marking. Regional airport authorities in Australia and sub-Saharan Africa deploy these at unelectrified airstrips under UDAN-style subsidy schemes.
- Infrared Beacons:Near-infrared emitters support military night vision operations and covert approach lighting without visible signature. MIL-STD-810 environmental testing protocols apply alongside civil photometric standards for dual-use installations.
LED Beacons lead volumes today; Solar Beacons are climbing the fastest as grid-independent infrastructure spreads.
End User:
Procurement sophistication and compliance burden intensity vary dramatically across buyer categories.
- Aerospace Manufacturers:Original equipment integration demands beacon systems certified to RTCA DO-160 environmental categories for vibration, temperature, and electromagnetic interference. Boeing and Airbus supply chains impose traceability requirements that favor qualified subsystem suppliers with established production part approval processes.
- Airport Authorities:Municipal and federal facility operators navigate FAA certification for obstruction lighting and ICAO Annex 14 compliance for approach systems. Federal Contract Tower facilities in the United States are piloting subscription telemetry models bundling hardware, cellular connectivity, and predictive maintenance.
- Military Operations:Dual-use installations must satisfy MIL-STD-810 environmental protocols alongside civil photometric standards. Electromagnetic compatibility requirements under EASA CS-ADR-DSN create additional certification layers for European NATO installations.
- Drone Operators:Low-altitude unmanned traffic management networks require supplemental beacon marking for vertiports and charging infrastructure below traditional manned aviation thresholds. Regulatory frameworks for urban air mobility corridors remain in flux across FAA and EASA jurisdictions.
Airport Authorities anchor current procurement; Drone Operators show the steepest expansion trajectory as vertiport infrastructure scales.
Installation:
Capital commitment horizon and relocation flexibility define procurement trade-offs in this dimension.
- Fixed Installation:Permanent mounting on towers, buildings, and terrain features with hardwired electrical connections and control circuit integration. Regulatory-mandated replacement cycles for obstruction lighting create predictable revenue stability for fixture manufacturers.
- Portable Installation:Battery-powered or generator-tethered units deployable for construction cranes, temporary structures, and emergency response. Mobile phone tower construction in India and Southeast Asia drives rental demand for rapid-deployment units.
- Temporary Setup:Short-duration deployments for events, film production, and disaster relief with minimal infrastructure requirements. Power-over-Ethernet convergence enables integrated data and electrical transmission through CAT6 cabling.
- Integrated Solutions:Beacon systems bundled with airfield lighting control, weather monitoring, and remote diagnostics platforms. Honeywell International leverages avionics integration expertise to bundle beacon diagnostics into broader airport management platforms.
Fixed Installation dominates replacement-driven revenue; Integrated Solutions are expanding most quickly through platform bundling.
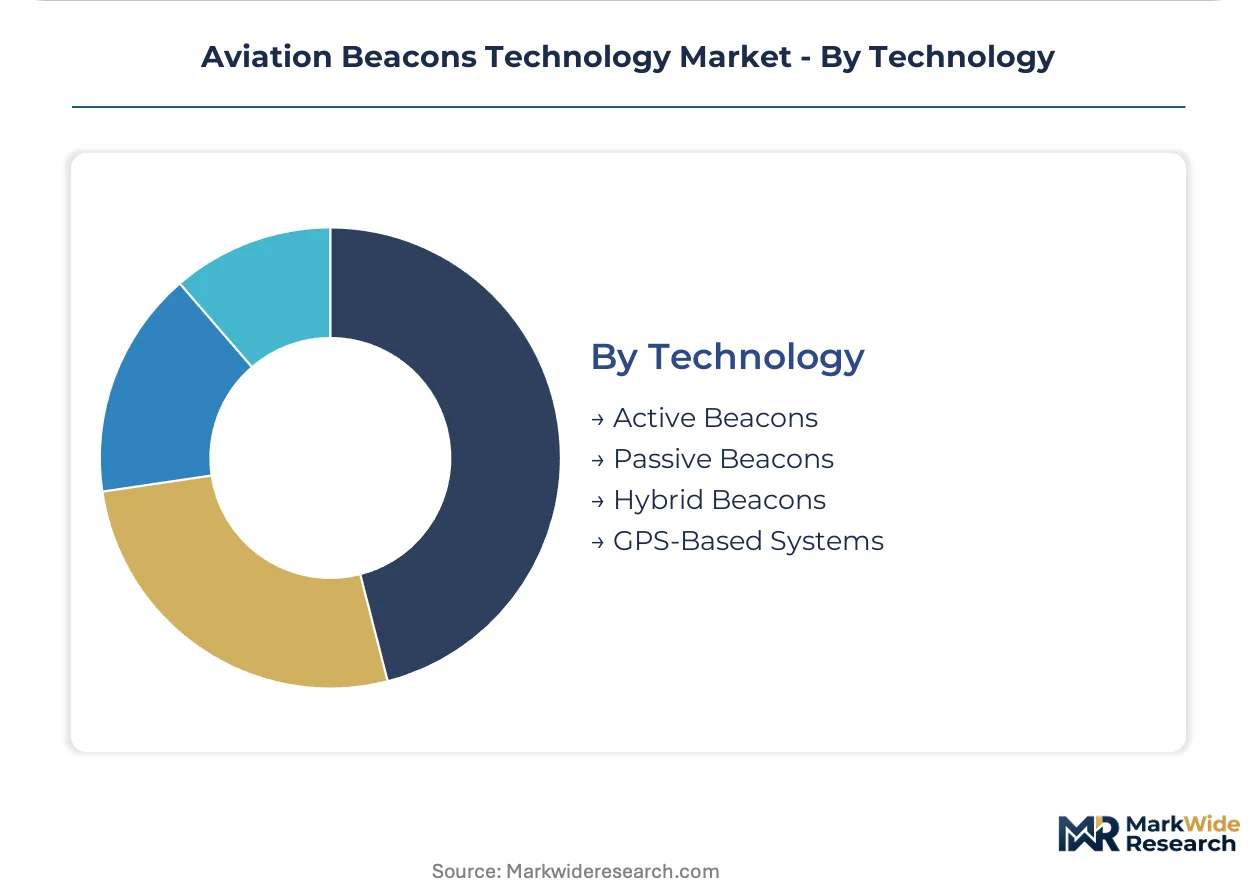
Technology:
Autonomy level and satellite dependency separate architectural approaches in modern beacon systems.
- Active Beacons:Self-illuminated systems with onboard power and control electronics, encompassing LED, xenon, and solar variants. Photometric calibration requirements under FAA AC 70/7460-1L mandate specialized technician expertise scarce outside major aviation maintenance hubs.
- Passive Beacons:Retroreflective devices returning incident light from aircraft searchlights or ground illumination without active emission. Limited to low-intensity applications under ICAO Annex 14 Volume I specifications.
- Hybrid Beacons:Dual-mode systems combining active illumination with passive backup or solar primary with grid fallback. Energy management firmware optimizes battery cycling to extend operational availability.
- GPS-Based Systems:Satellite-augmented precision approach requirements drive integration with WAAS, EGNOS, and other augmentation networks. GPS-Based Systems are gaining share fastest as precision approach infrastructure expands.
Active Beacons retain volume leadership; GPS-Based Systems are displacing legacy architectures in new approach lighting installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping supplier footprints as manufacturers relocate production to jurisdictions with streamlined FAA and EASA certification reciprocity, compressing cost-of-compliance gaps between North American and European sourcing.
United States
Metropolitan air corridors around Atlanta, Dallas-Fort Worth, and Los Angeles are driving LED retrofit procurement for structures exceeding 200 feet AGL. FAA AC 70/7460-1L mandates are accelerating replacement cycles for legacy xenon installations. Federal Contract Tower facilities in the Mountain West are piloting subscription telemetry models bundling hardware with predictive maintenance algorithms.
Germany
Precision approach infrastructure expansion at Frankfurt and Munich airports is integrating GPS-based augmentation with EGNOS satellite networks. EASA CS-ADR-DSN electromagnetic compatibility amendments are tightening certification barriers for LED driver subsystems. Industrial clusters in Bavaria and Baden-Württemberg host subsystem suppliers specializing in optical component fabrication for beam pattern calibration.
India
UDAN scheme subsidies for underserved regional routes are generating greenfield demand for solar-compatible beacon systems at unelectrified airstrips. Central Electricity Authority guidelines for off-grid airport infrastructure are accelerating photovoltaic integration. Construction corridors in Maharashtra and Karnataka are deploying portable beacon units for mobile phone tower erection.
Australia
Remote airfield operators in Queensland and Western Australia are adopting solar-hybrid architectures with proprietary energy management firmware to eliminate grid dependency. Civil Aviation Safety Authority alignment with ICAO Annex 14 Volume I is synchronizing LED flicker characteristic standards. Mining infrastructure corridors in the Pilbara region are marking previously uneconomical terrain features with decentralized power systems.
United Arab Emirates
Vertiport infrastructure for urban air mobility corridors below traditional manned aviation thresholds is creating supplemental beacon requirements in Dubai and Abu Dhabi. General Civil Aviation Authority drone integration rules are expanding low-altitude marking mandates. Solar beacon deployments at unelectrified desert airstrips are reducing transmission infrastructure costs for remote oil and gas logistics.
Aviation Beacons Technology Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in military-grade infrared systems contrasting fragmented supply for portable construction applications. The vendor base organizes around three archetypes: diversified avionics integrators bundling beacon diagnostics into airport management platforms, specialized power and lighting engineers focused on harsh-environment aerospace certification, and solar energy management specialists with proprietary off-grid firmware. Dominant competitive moves include strategic partnerships for satellite augmentation integration and backward integration into precision optical component fabrication.
Within the diversified integrator tier, Honeywell International exemplifies platform-scale positioning through avionics ecosystem leverage. Astronics Corporation and Carmanah Technologies occupy complementary specialist positions, with the former representing aerospace power systems engineering and the latter anchoring solar-hybrid energy architectures. These three entities collectively illustrate how certification depth and energy management intellectual property are concentrating competitive advantage in procurement decisions by airport authorities and military operators.
| Leading Market Players |
|---|
| Honeywell International |
| Astronics Corporation |
| Carmanah Technologies |
| Dialight |
| Hughey and Phillips |
| Point Lighting Corporation |
| Avlite Systems |
| Flash Technology |
| Obelux |
| Others |
Supply Flow & Price Mechanics
FAA AC 70/7460-1L photometric compliance mandates gate qualified supply and premium-tier pricing access by disqualifying uncertified fixture manufacturers from metropolitan air corridor procurement while rewarding EASA CS-ADR-DSN dual-certified suppliers with margin premiums. This regulatory filtering concentrates pricing power among avionics integrators and specialized aerospace lighting engineers with established production part approval processes.
Pricing Analysis
Capacity additions in China and Vietnam are reshaping price floors for LED driver subsystems and precision optical housings. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified European suppliers from FAA-compliant North American manufacturers and uncertified Asian contract producers. Cost compression in economy-tier portable beacon rentals is intensifying because mobile phone tower construction demand in India and Southeast Asia attracts low-cost battery-powered unit suppliers. Municipal airport authorities with constrained maintenance staffing show highest price sensitivity, while military dual-use installations with MIL-STD-810 requirements demonstrate lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Trans-Pacific freight cost volatility alters landed cost calculations for aluminum heatsink castings and lithium-ion battery cells sourced from East Asian manufacturing hubs. Precision lens and reflector fabrication concentrates in China, Taiwan, and South Korea, while aerospace-grade LED semiconductor arrays draw from established German and Japanese foundries. Single-source vulnerability for xenon flash tube trigger components creates supply chain risk as legacy high-voltage component manufacturers exit production. Distribution runs through avionics integrators with airport management platform bundling, direct procurement by federal contract tower operators, and rental channels for portable construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where synchronized FAA AC 70/7460-1L and ICAO Annex 14 compliance deadlines create replacement-driven demand windows that compress procurement cycles and concentrate supplier qualification advantages.
For Market Incumbents: Lock in certification moats by accelerating EASA CS-ADR-DSN electromagnetic compatibility investment ahead of amended testing protocols while securing backward integration into precision optical component fabrication to neutralize East Asian single-source vulnerability. Solar-hybrid energy management firmware represents a defendable technology layer against commoditized LED fixture competition from Asian contract manufacturers. For New Entrants and Emerging Players: GPS-based augmentation integration with WAAS and EGNOS satellite networks offers a technology-first wedge into precision approach infrastructure expansion at Frankfurt, Munich, and Dallas-Fort Worth airports. Vertiport beacon marking for urban air mobility corridors below traditional manned aviation thresholds presents the most penetrable white-space target, with Power-over-Ethernet convergence enabling remote diagnostics without separate control wiring infrastructure as the optimal go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized solar energy management firmware developers because decentralized grid dependency for remote airfield installations creates recurring service revenue streams with high switching costs. Long-term viability hinges on regulatory tailwinds from drone integration corridor mandates expanding addressable hardware base beyond traditional obstruction lighting. Watch FAA unmanned traffic management rulemaking progress as the critical inflection signal for vertiport infrastructure deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in EASA CS-ADR-DSN EMC Testing | Creates procurement barriers favoring established European subsystem suppliers over Asian competitors. |
| Backward Integration into Precision Optical Fabrication | Neutralizes East Asian single-source vulnerability for beam pattern calibration components. |
| Solar-Hybrid Energy Management Firmware Development | Enables off-grid deployments at Australian and sub-Saharan African unelectrified airstrips. |
| Subscription Telemetry Service Launch | Pilots per-luminaire contracts bundling hardware, cellular connectivity, and predictive maintenance algorithms. |
| Strategic Partnership for GPS Augmentation Integration | Links beacon systems with WAAS and EGNOS networks for precision approach infrastructure. |
Methodological Framework
Direct dialogue with airport authority procurement directors, military airfield engineering officers, avionics integration specialists, and solar energy management firmware developers grounded qualitative assessment in operational constraints and certification timelines. Secondary validation drew from FAA AC 70/7460-1L advisory circulars, ICAO Annex 14 Volume I amendments, EASA CS-ADR-DSN design specifications, and MIL-STD-810 environmental testing protocols. Bottom-up and top-down triangulation cross-checked segment-level procurement patterns against aggregate regulatory compliance expenditure forecasts.
Bottom-up modeling traced LED beacon, xenon system, and solar-hybrid unit shipments through installation type, end-user category, and technology architecture dimensions across the analysis window. Top-down validation anchored aggregate market expansion to FAA-mandated replacement cycles for structures exceeding 200 feet AGL and ICAO member state synchronization deadlines for medium-intensity approach lighting. CAGRs derived from regression of historical procurement data against regulatory milestone timing and energy infrastructure investment flows.
The model holds under steady regulatory enforcement intensity and aluminum-copper price corridor stability; deviation in FAA drone integration rulemaking acceleration or East Asian optical component export restrictions would shift forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Global Remote Towers Market
Airport Technologies
Airport Baggage Tracking Systems Market
Airport Technologies
Commercial Airport Radar Systems Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Smart Airport Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Asia-Pacific Airport Baggage Handling Systems Market
Airport Technologies
North America Smart Airport Market
Airport Technologies
Europe Airport Ground Handling Systems Market