
 Europe Airport Ground Handling Systems Market | 2026-2036
Europe Airport Ground Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airport Ground Handling Systems Market Foresight
Ground crew certification bottlenecks across the European Union is reorganizing how airports contract handling services. Swissport International AG leverages its pan-European training academies to sustain crew availability at major hubs. Menzies Aviation anchors its position through specialized cargo handling contracts at UK and Scandinavian airports. BEUMER Group GmbH & Co. KG differentiates via automated baggage system integration for terminal expansion projects.
Europe airport ground handling systems encompass the motorized and automated equipment, control software, and physical infrastructure used to service aircraft between flights, including belt loaders rated for specific cargo weights, 400 Hz ground power units delivering standardized electrical output, and passenger boarding bridges with vertical and horizontal reach adjustments. Their primary purpose is minimizing aircraft turnaround time while ensuring safety compliance during fueling, cleaning, catering, and baggage transfer operations. Passenger handling services capture mature, high-volume revenue streams at established hubs, while automated systems within the technology segment represent the fastest-expanding category as airports replace diesel ground support equipment with electric and autonomous alternatives. Cargo handling services concentrate margin pools at integrator-focused gateways such as Leipzig and Liège, where express freight operators demand specialized cold-chain and sorting capabilities.
The European Union Aviation Safety Agency (EASA) mandates airside equipment certification standards that shape product design cycles for ground power units and loading bridges, while the EU Green Deal's Fit for 55 framework forces airports to retire fossil-fuel ground support equipment on accelerated timelines. REACH and RoHS compliance adds material composition constraints for electrical components and battery systems used in electric pushback tractors. Stakeholders must monitor how national transposition of EU emissions rules affects fleet replacement schedules and whether airport privatization trends in Italy and Spain open new procurement channels for integrated system providers.
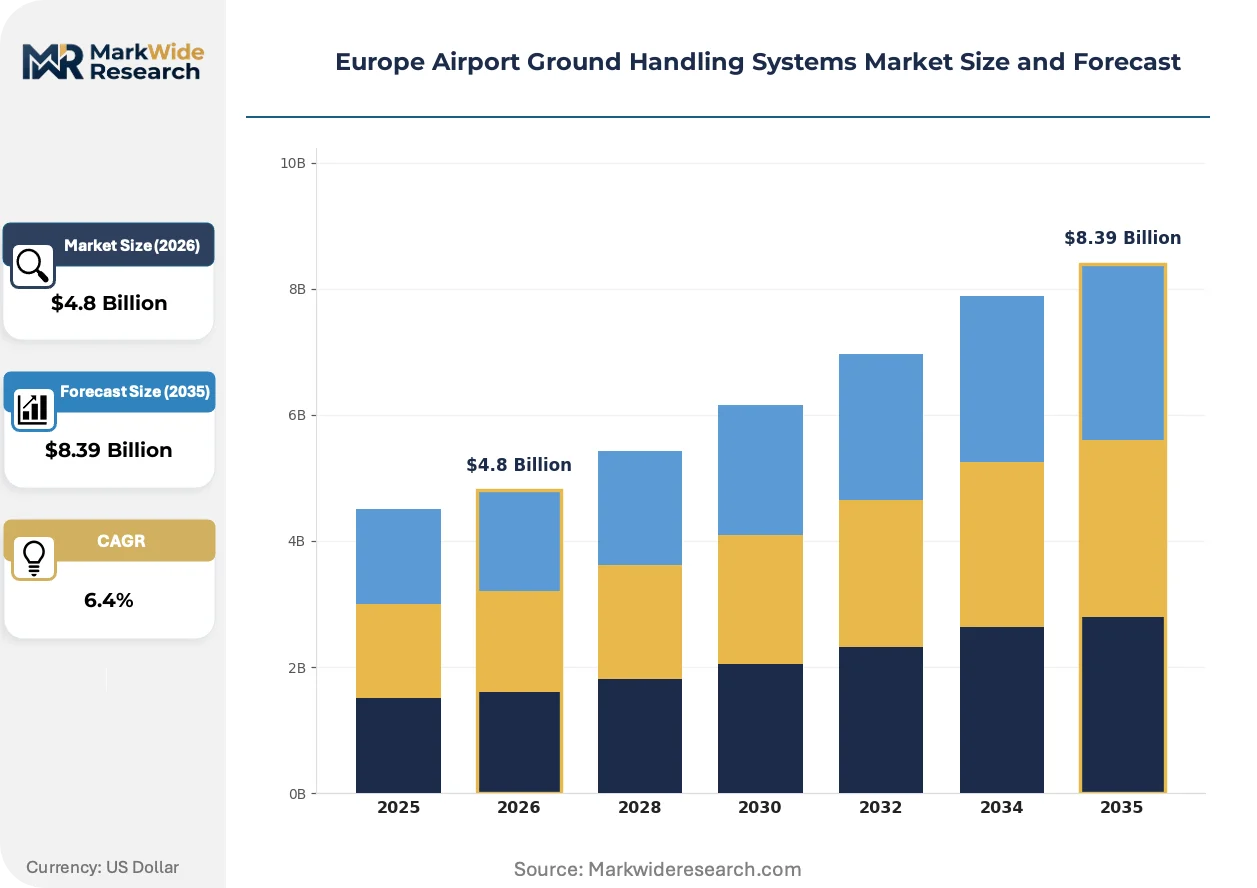
Market Dynamics
The EU Green Deal's Fit for 55 framework is forcing airports to retire diesel ground support equipment on accelerated timelines, compressing fleet replacement cycles and reshaping supplier relationships across European ramp operations.
Growth Catalysts
- EU Green Deal Emissions Mandates:The Fit for 55 framework obliges airports to electrify ground support equipment fleets by 2030, creating sustained procurement demand for electric pushback tractors and ground power units at major hubs.
- Passenger Volume Recovery:Airlines across Germany, France, and the United Kingdom are expanding automated baggage handling capacity to match post-pandemic traffic surges at Frankfurt, Charles de Gaulle, and Heathrow.
- Automated Sorting Technology:Robotic baggage handling systems are displacing manual transfer operations, reducing aircraft turnaround times by integrating belt loaders with AI-driven routing software.
Market Restraints
- Lithium-Ion Battery Supply Concentration:European electric ground support equipment manufacturers depend on Asian cell suppliers, exposing procurement schedules to raw material price volatility and shipping bottlenecks.
- Airside Equipment Certification Delays:EASA's airside equipment certification standards extend product validation timelines, slowing new ground power unit and loading bridge introductions by 12-18 months.
- High Initial Capital Requirements:Full-fleet electrification demands simultaneous infrastructure upgrades including charging stations and grid connections, straining airport capital allocation.
Strategic Opportunities
- Italian and Spanish Airport Privatization:Asset sales in Rome, Milan, Barcelona, and Madrid are opening integrated procurement channels for system providers capable of delivering turnkey ramp modernization packages.
- Cold-Chain Cargo Specialization:Express freight growth at Leipzig and Liège is creating demand for temperature-controlled sorting systems and specialized belt loaders with pharmaceutical-grade sealing.
- Autonomous Vehicle Convergence:Integration of LiDAR navigation with electric drivetrains is enabling self-driving baggage tractors and follow-me pushback units for unmanned ramp operations.
Industry Challenges
- Ground Crew Certification Bottlenecks:EASA-mandated training requirements for electric equipment operation are outstripping academy capacity, constraining crew availability during peak summer schedules.
- Legacy System Integration Complexity:Retrofitting 400 Hz ground power units and passenger boarding bridges with IoT monitoring interfaces requires custom engineering at each gate position.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airport Ground Handling Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Handling, Ramp Services, Cargo Handling, Aircraft Maintenance Technology: Automated Systems, RFID Tracking, Mobile Applications, Data Analytics End User: Airlines, Ground Service Providers, Airports, Logistics Companies Equipment Type: Baggage Trolleys, Pushback Tractors, Loading Bridges, Ground Power Units |
| Companies Covered | Worldwide Flight Services, BEUMER Group GmbH & Co. KG, Swissport International AG, Adelte Group SL, JBT Europe B.V., Aviapartner, Cavotec SA, Textron, Menzies Aviation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airport Ground Handling Systems Market Shifts & Advancements
Electrification and automation are converging to redefine European ramp operations, with regulatory deadlines compressing technology adoption timelines and procurement models shifting toward integrated service contracts.
Advanced battery pack architectures for ground support equipment are miniaturizing. These high-density lithium-ion systems power electric pushback tractors through multiple aircraft movements without mid-shift charging. Frankfurt and Munich airports are deploying these compact powertrains across their entire diesel replacement programs. The technology is miniaturizing equipment footprints, allowing narrower taxiway clearances and denser gate configurations at constrained urban airports.
The EU Green Deal's Fit for 55 framework mandates 55% emissions reduction by 2030. This policy forces ground handling operators to quantify and report Scope 1 emissions from diesel ground support equipment. Cold-chain cargo handlers at Leipzig-Halle face the steepest compliance costs, responding by pre-ordering electric belt loaders with regenerative braking systems ahead of regulatory deadlines.
Airlines are consolidating ground handling contracts under performance-based service agreements. Fixed-price per-turnaround models are replacing hourly equipment rental rates, transferring operational risk to handling agents. This restructuring is most visible in the United Kingdom, where British Airways and easyJet have bundled baggage, cargo, and aircraft servicing into single-source agreements at London Gatwick and Manchester.
Europe Airport Ground Handling Systems Market Segmentation
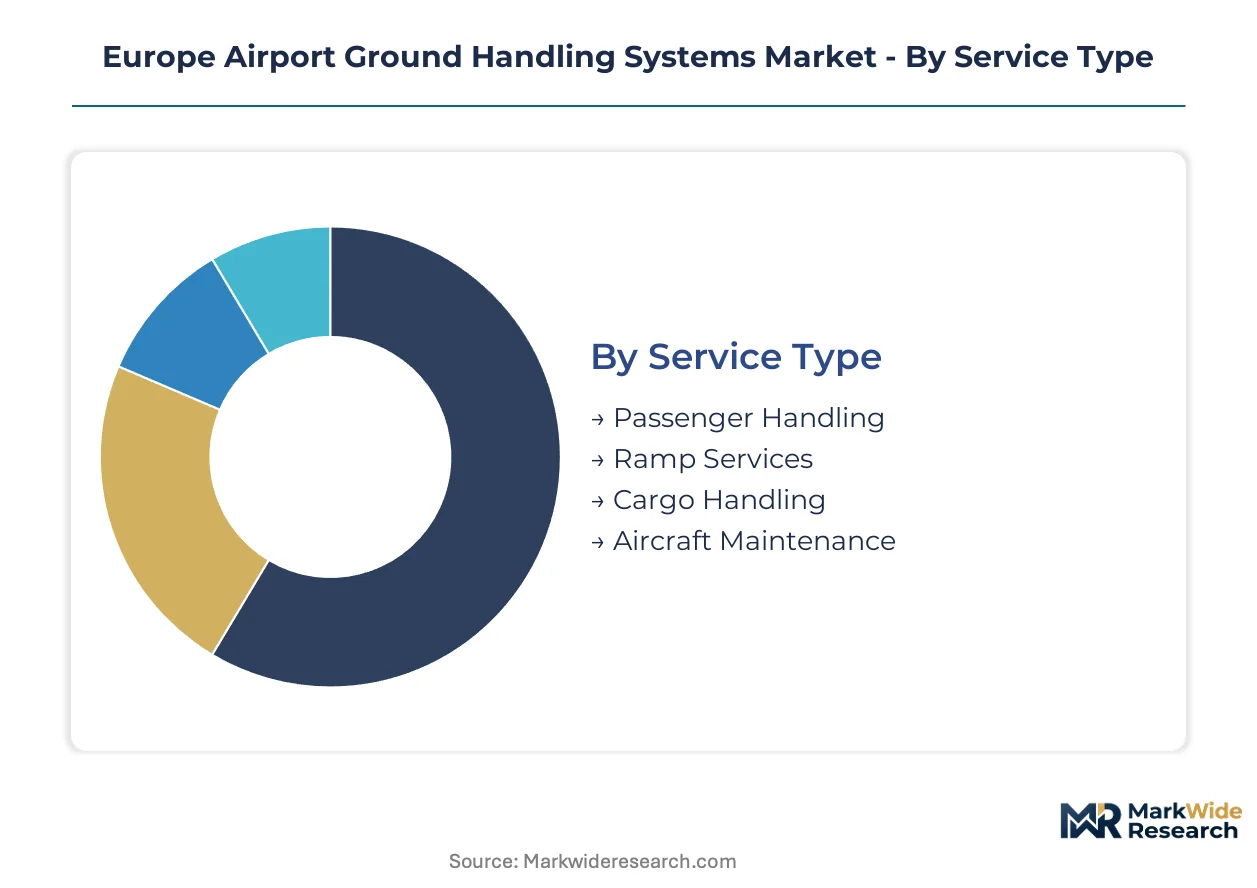
Ground handling procurement patterns diverge sharply across service models and technology tiers, with electrification mandates compressing equipment replacement cycles and automated systems commanding premium pricing at major hubs.
Service Type:
Margin pools concentrate heaviest in cargo handling contracts at integrator-focused gateways, where pharmaceutical-grade cold-chain capabilities justify specialized equipment investments and long-term service agreements.
- Passenger Handling:Encompasses check-in counter management, boarding gate operations, and passenger boarding bridge deployment. Frankfurt and Heathrow anchor volume demand as legacy carriers expand self-service kiosk networks and biometric boarding corridors to reduce touchpoints.
- Ramp Services:Covers aircraft marshalling, fueling coordination, and cabin cleaning between flights. French and German airports are consolidating these contracts under single-source operators to streamline turnaround accountability and meet EU Green Deal emissions reporting requirements.
- Cargo Handling:Leipzig-Halle and Liège generate the steepest margins through express freight sorting and temperature-controlled storage. Integrator demand for pharmaceutical logistics is driving automated warehouse-to-ramp conveyor investments.
- Aircraft Maintenance:Line maintenance and routine inspections during ground time. Italian and Spanish airports are expanding third-party maintenance bays as privatization opens infrastructure to independent service providers.
The dominant share belongs to Passenger Handling, while Cargo Handling is closing the gap fastest.
Technology:
Adoption velocity varies by capital intensity, with mobile software deploying fastest at budget-constrained regional airports and automated systems concentrating at tier-one hubs with dedicated modernization budgets.
- Automated Systems:Robotic baggage sorting, autonomous pushback tractors, and AI-driven gate allocation software. Munich and Charles de Gaulle are deploying LiDAR-guided baggage tractors to eliminate manual towing operations and reduce ground crew certification bottlenecks.
- RFID Tracking:Real-time baggage and cargo location monitoring through radio-frequency identification tags. Scandinavian airports are mandating RFID compliance for all transfer baggage to minimize mishandling penalties during peak summer schedules.
- Mobile Applications:Digital task allocation and equipment status dashboards for ground crew. Regional airports in Eastern Europe are adopting cloud-based workforce management tools to offset training academy capacity constraints.
- Data Analytics:Predictive maintenance algorithms and turnaround time optimization engines. British Airways and easyJet are requiring analytics integration in ground handling contracts at London Gatwick and Manchester to enforce performance-based pricing.
Automated Systems command the highest capital allocation, with Data Analytics expanding most quickly through retrofit contracts.
End User:
Procurement authority is fragmenting as airports reclaim direct control over electrification timelines while outsourcing day-to-day ramp operations to specialized agents.
- Airlines:Legacy carriers and low-cost operators specifying equipment standards in ground handling contracts. Lufthansa and Air France-KLM are bundling baggage, cargo, and servicing requirements into single-source agreements to transfer operational risk.
- Ground Service Providers:Swissport International AG and Menzies Aviation managing multi-airline ramp operations. These agents are investing in pan-European training academies to sustain crew availability across peak and off-peak seasons.
- Airports:Frankfurt, Munich, and Amsterdam Schiphol owning infrastructure and electrification procurement directly. EU Green Deal compliance deadlines are forcing capital expenditure on charging networks and grid connections ahead of fleet replacement.
- Logistics Companies:DHL and FedEx integrators operating dedicated cargo terminals at Leipzig and Liège. These end users are pre-ordering electric belt loaders with regenerative braking to secure equipment slots before manufacturer backlogs extend.
Ground Service Providers retain the largest contract volume, though Airports are accelerating direct procurement fastest under regulatory pressure.
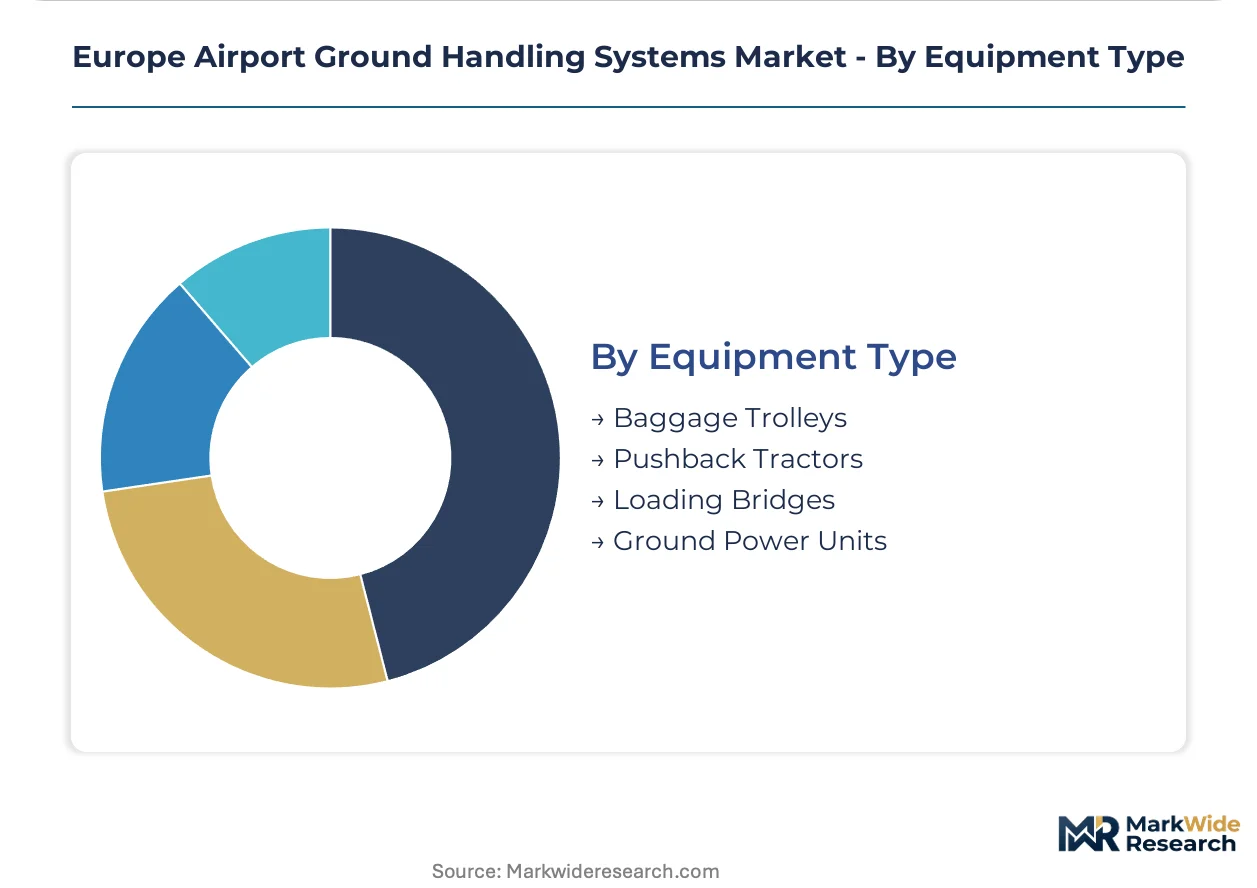
Equipment Type:
Electrification economics favor smaller-footprint equipment where battery density gains enable multi-shift operation without mid-day charging infrastructure.
- Baggage Trolleys:Motorized and non-motorized carts for baggage transport between terminal and aircraft. Electric variants with swappable battery packs are displacing diesel units at constrained urban airports where charging station real estate is limited.
- Pushback Tractors:Aircraft repositioning vehicles rated by maximum towed weight. Electric pushback tractors with high-density lithium-ion architectures are enabling Frankfurt and Munich to complete full diesel replacement programs without operational interruption.
- Loading Bridges:Passenger boarding bridges with vertical and horizontal reach adjustments. EASA certification timelines extend replacement cycles, slowing IoT-enabled predictive maintenance retrofits at aging European terminals.
- Ground Power Units:400 Hz electrical supply systems for parked aircraft. Electric GPU procurement is accelerating fastest in the United Kingdom as British airports face earlier national transposition deadlines for emissions reductions.
Ground Power Units dominate procurement volumes, while Pushback Tractors are gaining share fastest through bundled electrification packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA certification requirements and EU Green Deal timelines anchor procurement intensity across the continent, with national transposition schedules creating staggered replacement waves for ground support equipment fleets.
Germany
Frankfurt and Munich airports are executing full diesel replacement programs for pushback tractors and ground power units ahead of 2030 regulatory deadlines. The national implementation of EU Fit for 55 obligations compresses fleet procurement cycles, forcing simultaneous charging infrastructure deployment. Bavaria's airport cluster concentrates manufacturer backlogs for high-density lithium-ion battery systems.
United Kingdom
British Airways and easyJet have consolidated ground handling contracts at Gatwick and Manchester under performance-based pricing models. Earlier national emissions transposition deadlines accelerate electric ground power unit procurement compared to continental peers. London Heathrow anchors volume demand for automated baggage handling capacity expansion.
France
Charles de Gaulle is deploying LiDAR-guided autonomous baggage tractors to eliminate manual towing operations. ANSM oversight of airside equipment certification extends validation timelines for new loading bridge introductions. The Paris airport cluster leads adoption of AI-driven gate allocation software among European hubs.
Italy
Airport privatization in Rome and Milan is opening integrated procurement channels for turnkey ramp modernization packages. REACH compliance adds material composition constraints for electrical components in electric pushback tractors. The Lombardy aviation corridor sees third-party maintenance bay expansion as infrastructure access liberalizes.
Netherlands
Amsterdam Schiphol owns electrification procurement directly, capitalizing on grid infrastructure advantages for charging network deployment. GDPR compliance frameworks shape data analytics integration in ground handling software procurement. The Randstad logistics cluster concentrates cold-chain cargo specialization investments for pharmaceutical logistics.
Europe Airport Ground Handling Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pan-European training networks and automated system capabilities determining contract access at major hubs. The vendor base organizes around three archetypes: full-service ground handling agents with academy networks, automated baggage system integrators, and specialized cargo handling operators. Consolidation pressure intensifies as airports bundle multi-service contracts and electrification mandates favor fleet-scale procurement.
Among integrated service providers, Swissport International AG and Menzies Aviation exemplify the pan-European handling agent archetype with established training infrastructure, while BEUMER Group GmbH & Co. KG represents the automated systems specialist tier focused on terminal expansion integration.
| Leading Market Players |
|---|
| Worldwide Flight Services |
| BEUMER Group GmbH & Co. KG |
| Swissport International AG |
| Adelte Group SL |
| JBT Europe B.V. |
| Aviapartner |
| Cavotec SA |
| Textron |
| Menzies Aviation |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month EASA certification lead times for new ground power units and loading bridges concentrate pricing power with incumbent manufacturers possessing validated product portfolios, while compressing procurement flexibility for airports facing EU Green Deal deadlines. This elongated validation cycle locks buyers into premium-tier contracts with established suppliers, amplifying cost exposure for late electrification adopters.
Pricing Analysis
Geographic price spreads between German and Eastern European procurement contracts exceed standard logistics differentials, reflecting bundled service-attach premiums for charging infrastructure deployment. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified electric pushback tractors from pre-certified prototypes and refurbished diesel units. Pricing pressure stems from lithium-ion battery raw material volatility transmitted through Asian cell supplier contracts. Low-cost carriers exhibit highest price sensitivity, while integrator cargo terminals at Leipzig and Liège absorb premium equipment costs to secure pharmaceutical-grade cold-chain capabilities.
Supply Chain Analysis
Strait of Malacca transit exposure for lithium carbonate and nickel sulfate concentrates European electric ground support equipment manufacturers' vulnerability to Asian raw material bottlenecks. Manufacturing capacity clusters in China, South Korea, and Japan supply high-density battery cells, while Germany and the Netherlands host final assembly and EASA certification facilities. Semiconductor shortages for power management integrated circuits and LiDAR navigation modules constitute single-source vulnerability points. Distribution runs through OEM-direct contracts for major hub electrification programs, with regional distributors serving fragmented municipal airport demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including predictive maintenance software subscriptions and charging infrastructure management contracts are expanding faster than hardware sales, repositioning ground handling equipment procurement as recurring-revenue relationships rather than capital expenditure events.
For Market Incumbents: Secure EASA pre-certification for next-generation autonomous pushback tractor platforms before regulatory frameworks solidify, locking out competitors lacking validation track records. Deepen backward integration into high-density battery pack architectures to insulate margins from Asian cell supplier price volatility. Consolidate training academy networks across German and French hubs to capture ground crew certification bottlenecks as competitive moats. For New Entrants and Emerging Players: Anchor in Italian and Spanish airport privatization waves, where turnkey ramp modernization packages face limited established vendor relationships. Target secondary cargo gateways in Eastern Europe with electric belt loader offerings that bypass EASA validation delays through modular retrofit designs. Pursue direct airport authority relationships rather than ground service provider channels to accelerate reference account accumulation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU Green Deal mandates create non-discretionary replacement demand through 2030 regardless of passenger traffic cyclicality. Acquisition candidates with integrated charging infrastructure deployment capabilities and existing EASA certification pipelines command structural scarcity premiums. Monitor national transposition timelines for Fit for 55 obligations as inflection indicators for procurement acceleration windows.| Strategic Initiative | Industry Significance |
|---|---|
| Pan-European Training Academy Expansion | Swissport and Menzies capture crew availability constraints as competitive differentiation at peak summer schedules. |
| LiDAR-Guided Autonomous Vehicle Development | Munich and Charles de Gaulle deployments validate unmanned ramp operations for broader hub adoption. |
| High-Density Battery Pack Miniaturization | Frankfurt and Munich complete diesel replacement programs without operational interruption through compact powertrains. |
| Turnkey Electrification Service Contracts | British Airways and easyJet bundled agreements transfer operational risk to handling agents under fixed-price models. |
| Cold-Chain Cargo Specialization Investment | Leipzig and Liège integrator terminals justify premium equipment costs through pharmaceutical logistics margins. |
Research Methodology
Desk research of EASA certification databases, EU Green Deal regulatory filings, and airport capital expenditure disclosures preceded structured interviews with ground handling operations directors, airport procurement managers, electric vehicle engineering leads, and ground crew training academy administrators. Primary fieldwork validated secondary data points regarding fleet replacement timelines and charging infrastructure deployment schedules. Bottom-up equipment unit forecasts triangulated against top-down airport modernization budget allocations across the analysis window.
Variance decomposition across service type, technology tier, equipment category, and end-user procurement authority anchored the analytical framework throughout the projection horizon. CAGRs derived from logistic diffusion curves modeling electrification adoption S-cycles, calibrated to national transposition schedules for EU Fit for 55 obligations. Industry-specific forecast inputs incorporated EASA validation backlog estimates and lithium-ion battery manufacturer capacity expansion announcements.
Material uncertainties — regulatory deadline delays, battery raw material supply disruptions, and ground crew training capacity constraints — sit outside the modeled envelope and could compress or extend replacement wave timing. Forecasts reflect documented assumptions regarding EASA certification throughput and airport capital allocation prioritization. Practitioners should keep alternative scenarios live as national emissions transposition schedules and charging infrastructure grid connection timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Asia-Pacific Airport Ground Handling Systems Market
Airport Technologies
Advanced Airport Technologies Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Smart Airport 4.0 Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Smart Airport 3.0 Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Smart Airport Market